
 Global Microelectronics Cleaning Equipment Market | 2026-2036
Global Microelectronics Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microelectronics Cleaning Equipment Market Outlook
Memory foundry capital expenditure is collapsing toward logic and advanced packaging buyers as DRAM bit-growth decelerates. Applied Materials leverages its broad process equipment portfolio to bundle cleaning solutions with deposition and etch systems. Tokyo Electron sustains dominance in wet bench architecture through proprietary megasonic and brush-scrubbing modules. SCREEN Holdings competes aggressively on single-wafer spin-clean throughput metrics for sub-7nm nodes.
Microelectronics cleaning equipment encompasses systems that remove particulate, metallic, and organic contaminants from semiconductor wafers, photomasks, and process chamber components using wet chemical, plasma, or dry gas-phase methods, typically achieving surface cleanliness below 10^10 atoms per square centimeter for critical atomic-layer processing steps. Wet Cleaning Systems occupy the largest installed base across 300mm fabs due to their versatility with solvent, acid, and deionized water chemistries, though Dry Cleaning Systems represent the fastest-expanding segment as cryogenic aerosol and plasma-based methods reduce water consumption and chemical waste disposal burdens. Wafer Cleaning applications command the deepest margin pools because node shrinkage below 5nm introduces new defectivity challenges from EUV resist residues and atomic-scale roughness.
EPA regulations in the United States restrict perfluorinated compound emissions from semiconductor etch and clean processes, while REACH and the EU F-Gas Regulation in Europe mandate substitution timelines for high-global-warming-potential chemistries used in vapor-phase and cryogenic cleaning. Japan's METI enforces JIS standards for equipment safety and chemical handling protocols that influence export certification requirements for Korean and Taiwanese tool suppliers. Stakeholders must monitor evolving chemical restriction schedules and pre-qualify alternative clean chemistries before existing formulations face regulatory sunset clauses.
Market Dynamics
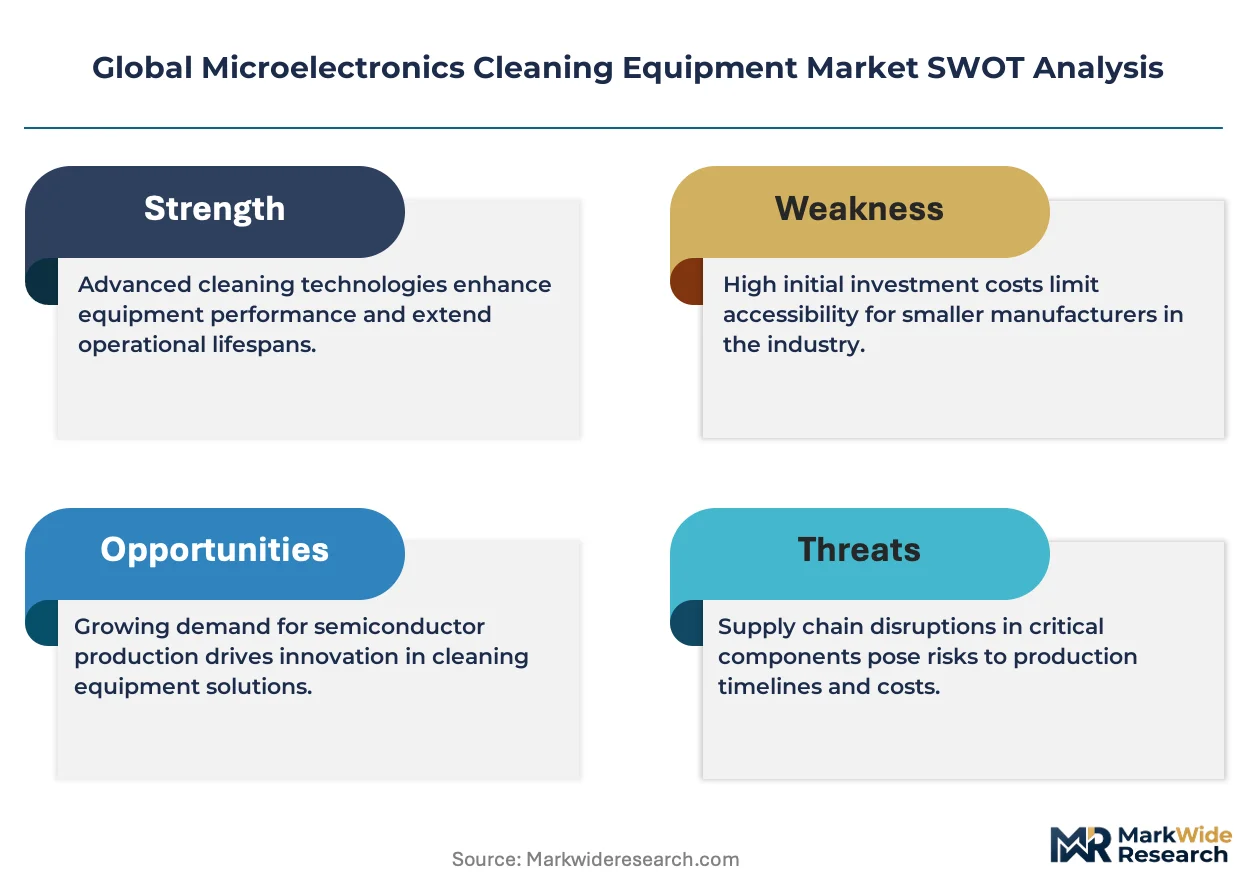
Node migration below 5nm is multiplying cleaning steps per wafer while EUV resist residue removal demands atomic-scale precision, forcing equipment suppliers to integrate metrology feedback loops directly into wet bench and single-wafer architectures.
Growth Catalysts
- Advanced packaging proliferation:Heterogeneous integration and chiplet architectures require multiple cleaning cycles during wafer-to-wafer bonding and through-silicon-via formation, expanding addressable equipment hours per substrate.
- EPA perfluorinated compound restrictions:Tightening emissions caps on etch and clean chemistries are accelerating capital replacement cycles as fabs retire wet benches unable to capture or recycle fluorinated process gases.
- South Korea-Taiwan-US fab clustering:Concentrated foundry and memory investment in these three markets creates localized demand spikes for high-throughput single-wafer cleaning systems with sub-10nm defectivity specifications.
Market Restraints
- High-purity chemical input volatility:Ultra-pure water, hydrogen fluoride, and sulfuric acid supply chains face periodic disruption from energy cost spikes and semiconductor-grade purification bottlenecks, compressing equipment gross margins.
- Critical component supplier concentration:Megasonic transducers, brush materials, and chemical delivery subsystems rely on specialized Japanese and German component vendors, creating single-source vulnerability.
- Dry cleaning throughput limitations:Cryogenic aerosol and plasma-based methods remain slower than wet chemistry for bulk contaminant removal, restricting their penetration to final cleaning steps despite environmental advantages.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme subsidies and state-level fab commitments in Gujarat and Karnataka create first-mover advantage for cleaning equipment vendors establishing local service infrastructure.
- Photomask cleaning automation:EUV mask defectivity requirements below 0.001 defects per square centimeter are opening dedicated equipment categories for pellicle-compatible cleaning systems.
- EU F-Gas Regulation substitution mandates:Forced phase-out timelines for high-global-warming-potential chemistries are creating pull for alternative vapor-phase cleaning technologies that qualify under REACH pre-registration pathways.
Industry Challenges
- Process engineer talent scarcity:Atomic-layer precision cleaning requires rare expertise in surface chemistry, acoustic physics, and contamination control that outpaces university pipeline output in Taiwan and South Korea.
- Multi-node qualification burden:Equipment vendors must simultaneously validate cleaning recipes for 3nm logic, 18A foundry, and legacy 28nm automotive nodes, stretching R&D resources across incompatible process windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microelectronics Cleaning Equipment Market |
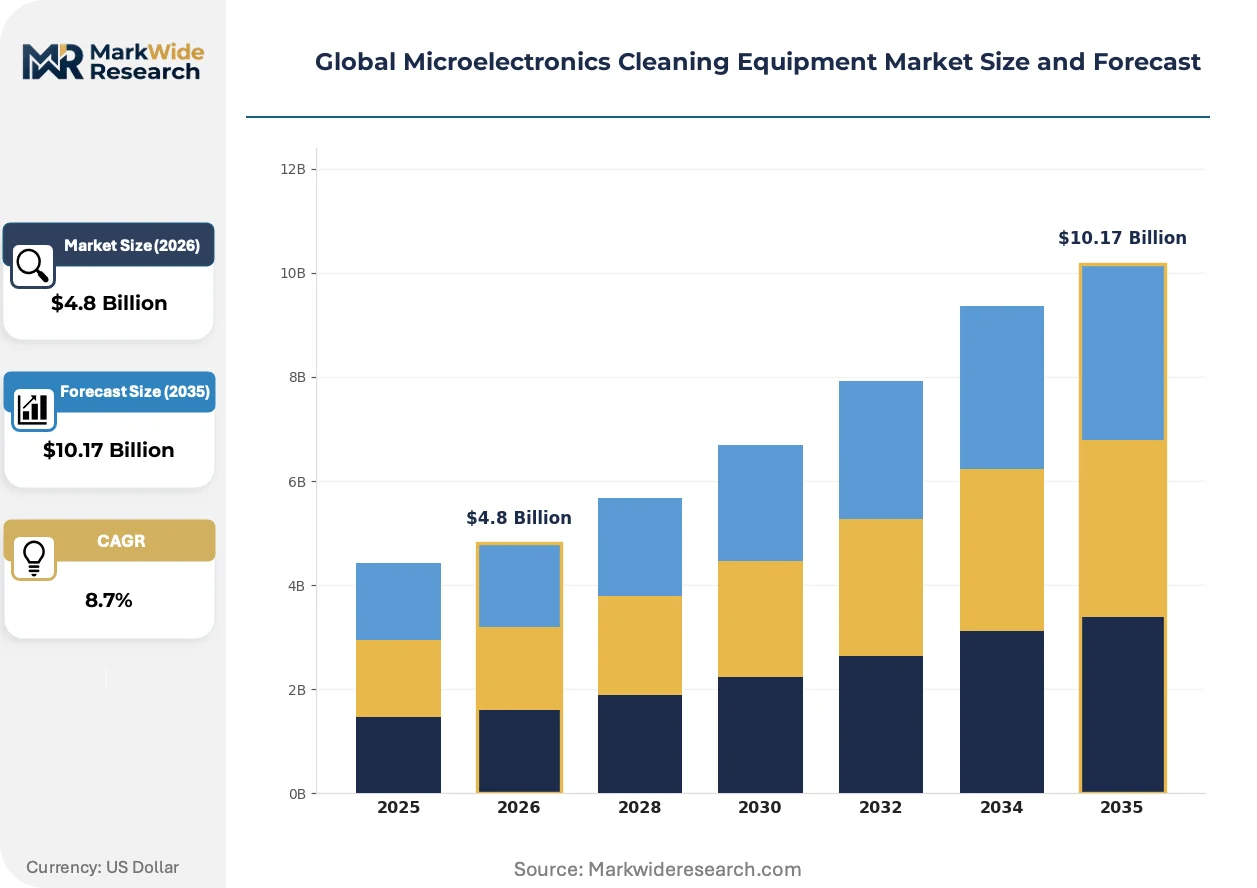
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Cleaning Systems, Dry Cleaning Systems, Chemical Cleaning Equipment, Ultrasonic Cleaners End User: Semiconductor Manufacturers, PCB Manufacturers, MEMS Fabricators, Solar Cell Manufacturers Technology: Plasma Cleaning, Solvent Cleaning, Vapor Phase Cleaning, DI Water Rinse Technology Application: Wafer Cleaning, Component Cleaning, Equipment Maintenance, Surface Treatment |
| Companies Covered | Applied Materials, Lam Research, Tokyo Electron, SCREEN Holdings, KLA Corporation, RENA Technologies, Panasonic Corporation, Entegris, SEMES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microelectronics Cleaning Equipment Market Strategic Shifts
Cleaning technology is bifurcating between water-intensive wet chemistry optimization and dry methods that eliminate liquid waste streams entirely, with equipment architectures converging toward modular platforms that accommodate both process flows.
Supercritical carbon dioxide cleaning is fragmenting traditional wet chemistry dominance in back-end-of-line applications. Memory manufacturers in South Korea are piloting systems for porous low-k dielectric damage-free residue removal. This displacement is compressing the addressable market for solvent-based immersion tanks while opening service revenue from CO2 recycling infrastructure.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of vapor-phase cleaning chemistries across European fabs and their Asian suppliers serving EU export markets. Equipment OEMs must now certify process compatibility with replacement chemistries before sunset clauses take effect, delaying new tool qualifications by 12-18 months.
Consolidated procurement through foundry alliance purchasing desks is displacing individual fab equipment autonomy. Leading logic and memory manufacturers in Taiwan and the United States now negotiate enterprise-wide cleaning equipment frameworks spanning multiple greenfield sites. This concentration is visible most acutely in Arizona and Texas, where simultaneous fab construction creates volume leverage unprecedented in prior capital cycles.
Global Microelectronics Cleaning Equipment Market Segmentation
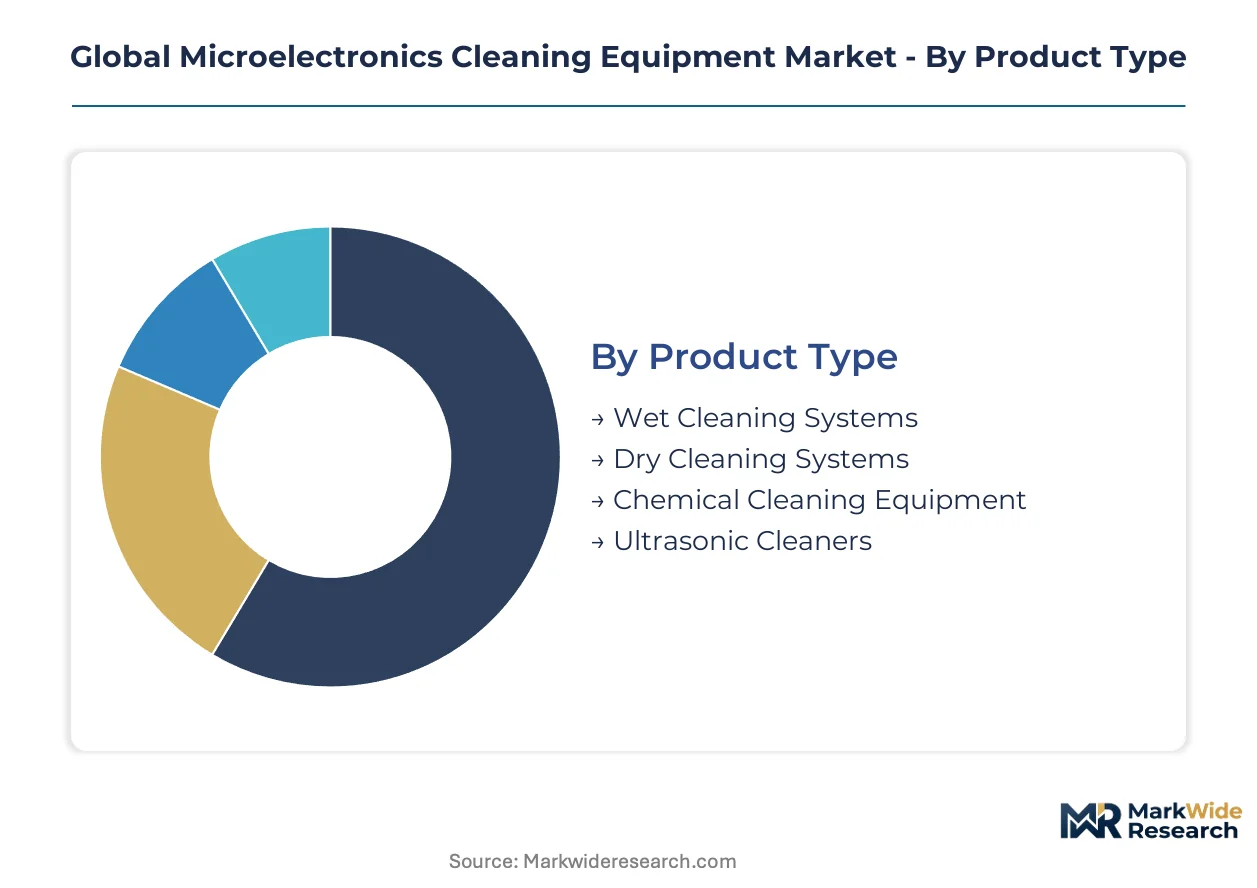
Cleaning equipment procurement channels diverge sharply by product complexity and fab scale. Integrated device manufacturers negotiate enterprise frameworks directly with OEMs, while specialty foundries and packaging houses rely on distributor networks for standardized units.
Product Type:
Equipment flows through distinct channel architectures: wet systems dominate direct OEM contracts with leading-edge fabs, while dry and ultrasonic units circulate through regional distributors serving mid-tier manufacturers.
- Wet Cleaning Systems:Immersion tanks, spray processors, and single-wafer spin-clean tools utilizing solvent, acid, and deionized water chemistries for bulk contaminant removal. Demand concentrates in South Korea and Taiwan where 300mm logic and memory fabs require sub-7nm defectivity specifications; EPA perfluorinated compound restrictions accelerate replacement of legacy wet benches lacking exhaust capture.
- Dry Cleaning Systems:Cryogenic aerosol, plasma-based, and supercritical CO2 methods eliminating liquid waste streams entirely. Growth concentrates in European fabs subject to EU F-Gas Regulation phase-out timelines for high-global-warming-potential chemistries; water scarcity in Arizona and Texas fabs drives parallel interest.
- Chemical Cleaning Equipment:Dedicated systems for hydrogen fluoride, sulfuric acid, and ozonated water delivery with integrated chemical recycling loops. Foundry alliance purchasing desks in the United States favor vendors offering chemical management service contracts bundled with hardware.
- Ultrasonic Cleaners:Megasonic and brush-scrubbing modules for photomask and component-level precision cleaning. PCB manufacturers in China and Vietnam source these through distributor channels rather than direct OEM relationships.
By volume, Wet Cleaning Systems leads. By growth pace, Dry Cleaning Systems is climbing the fastest.
End User:
Customer scale determines procurement sophistication: semiconductor manufacturers demand integrated metrology and recipe validation, while solar and PCB buyers prioritize throughput per capital dollar.
- Semiconductor Manufacturers:Logic, memory, and foundry fabs requiring atomic-layer precision for EUV resist residue removal and sub-5nm surface roughness control. South Korean memory producers and Taiwanese foundries command deepest margin pools through multi-node qualification requirements spanning 3nm to 28nm process windows.
- PCB Manufacturers:High-density interconnect and substrate fabricators needing post-etch and desmear cleaning for fine-pitch traces. Demand localizes in China, Vietnam, and Thailand where electronics assembly supply chains concentrate.
- MEMS Fabricators:Specialized cleaning for released structures and sacrificial layer removal without mechanical damage. European automotive sensor suppliers and United States aerospace contractors drive specifications for damage-free processing.
- Solar Cell Manufacturers:Texturing and post-diffusion cleaning for silicon wafer substrates. Indian PLI scheme recipients in Gujarat and Karnataka represent emerging equipment destinations as domestic cell capacity expands.
Semiconductor Manufacturers capture the largest revenue share. MEMS Fabricators show the steepest expansion trajectory as automotive LiDAR and medical sensor demand multiplies.
Technology:
Technology selection tracks regulatory pressure and water availability: plasma and vapor methods gain share where effluent restrictions tighten, while solvent and DI water rinse retain dominance in cost-sensitive high-volume applications.
- Plasma Cleaning:Reactive gas-phase removal of organic residues and native oxides using oxygen, fluorine, or hydrogen-based chemistries. United States EPA emissions caps on perfluorinated compounds constrain chemistry selection, favoring remote plasma sources with abatement integration.
- Solvent Cleaning:Isopropyl alcohol, acetone, and proprietary formulations for photoresist and adhesive removal. REACH authorization requirements for per- and polyfluoroalkyl substances force reformulation timelines across European fabs and their Asian suppliers.
- Vapor Phase Cleaning:Condensing solvent vapor for precision component cleaning with minimal liquid consumption. German automotive electronics suppliers specify these systems for sensor module pre-assembly preparation.
- DI Water Rinse Technology:Ultra-pure water systems with resistivity monitoring and particle filtration for final rinse steps. Japanese METI JIS standards for equipment safety influence export certification requirements for Korean and Taiwanese tool suppliers.
DI Water Rinse Technology maintains the broadest installed base. Plasma Cleaning is gaining share fastest as dry methods displace wet chemistry in critical final-clean steps.
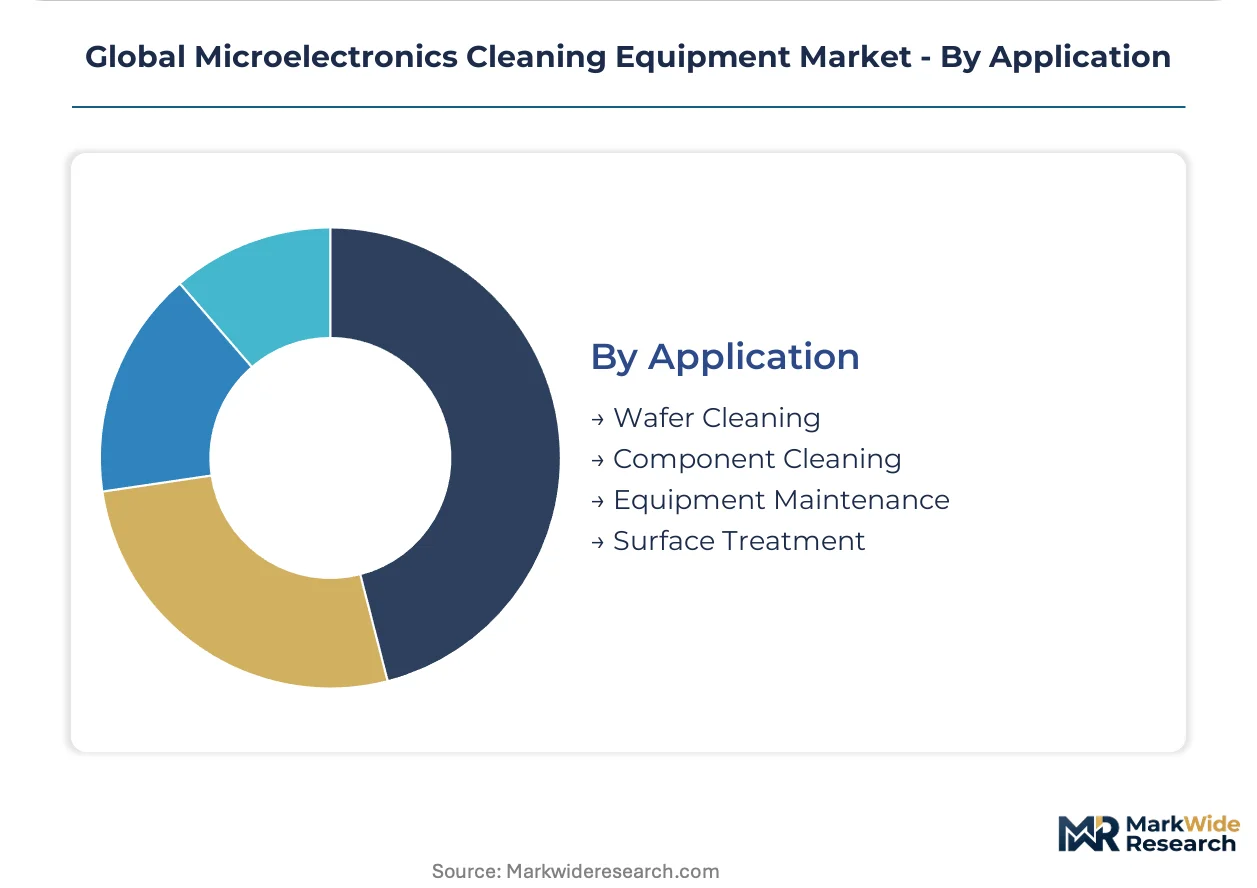
Application:
Application mix shifts with packaging complexity: wafer-level processing deepens cleaning step counts, while equipment maintenance creates recurring service revenue streams.
- Wafer Cleaning:Front-end-of-line and back-end-of-line substrate processing for particulate, metallic, and organic contaminant removal. Advanced packaging proliferation in Taiwan and United States drives multiple cleaning cycles during wafer-to-wafer bonding and through-silicon-via formation.
- Component Cleaning:Photomask, reticle, and process chamber component preparation. EUV mask defectivity requirements below 0.001 defects per square centimeter open dedicated equipment categories for pellicle-compatible systems.
- Equipment Maintenance:Chamber cleaning and preventive maintenance for deposition, etch, and implant tools. Service contracts with Japanese and German component vendors for megasonic transducers and brush materials create recurring revenue anchors.
- Surface Treatment:Activation and modification for adhesion promotion and wettability control. Heterogeneous integration and chiplet architectures expand addressable hours per substrate through repeated surface preparation steps.
Wafer Cleaning dominates revenue contribution. Equipment Maintenance expands most quickly as fabs extend tool lifecycles and outsource chamber refurbishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung high-speed rail corridor underwrites Taiwan's semiconductor logistics supremacy, shuttling photomasks and process chemicals between foundry clusters with sub-two-hour transit times.
United States
CHIPS Act disbursements to Intel, TSMC, and Samsung are accelerating fab construction in Arizona, Texas, and Ohio. EPA perfluorinated compound emissions caps are forcing retirement of legacy wet benches lacking exhaust capture systems. Phoenix and Austin metro areas concentrate simultaneous greenfield investments creating unprecedented localized demand spikes for single-wafer cleaning equipment.
South Korea
SK Hynix and Samsung Memory are expanding Pyeongtaek and Yongin complexes despite DRAM bit-growth deceleration. METI-influenced JIS equipment safety standards shape export certification requirements for Korean tool suppliers serving Japanese customers. Seoul Capital Area fabs are piloting supercritical CO2 systems for porous low-k dielectric cleaning to reduce water consumption.
Japan
Tokyo Electron and SCREEN Holdings anchor domestic equipment supply chains serving global foundry customers. METI enforces chemical handling protocols that influence Korean and Taiwanese export certifications. Kyushu Island's Kumamoto and Oita prefectures concentrate specialized megasonic transducer and brush material component manufacturing.
China
Yangtze Memory Technologies and SMIC are expanding domestic 300mm capacity despite equipment import restrictions. SAMR and MIIT coordinate dual carbon goals with semiconductor manufacturing incentives. Yangtze River Delta cities including Shanghai, Wuxi, and Hefei cluster memory and logic fab investments driving wet chemistry system procurement.
Germany
Bosch and Infineon are expanding automotive sensor and power semiconductor capacity in Dresden and Regensburg. REACH authorization requirements for per- and polyfluoroalkyl substances mandate vapor-phase chemistry reformulation timelines. Saxony's Silicon Saxony cluster coordinates equipment procurement for multiple automotive electronics suppliers.
Global Microelectronics Cleaning Equipment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and process integration dimensions. The market structure concentrates around three to five dominant equipment platforms with long qualification cycles protecting incumbent positions. Diversified process equipment conglomerates, specialized wet bench architects, and component subsystem vendors constitute the primary competitive archetypes. Strategic moves center on bundling cleaning with deposition and etch systems, plus geographic expansion through foundry alliance purchasing desks.
Within the diversified conglomerate tier, Applied Materials and Lam Research exemplify platform breadth strategies spanning multiple process steps. Tokyo Electron occupies a position as the specialized wet bench architect with proprietary megasonic and brush-scrubbing module integration. SCREEN Holdings represents throughput-focused competition on single-wafer spin-clean metrics for sub-7nm nodes.
| Leading Market Players |
|---|
| Applied Materials |
| Lam Research |
| Tokyo Electron |
| SCREEN Holdings |
| KLA Corporation |
| RENA Technologies |
| Panasonic Corporation |
| Entegris |
| SEMES |
| Others |
Value Chain & Pricing Dynamics
Twenty-four to thirty-six week lead times for megasonic transducers and specialized brush materials from Kyushu-based component vendors concentrate pricing power with Japanese and German subsystem suppliers serving foundry alliance purchasing desks in Arizona and Texas.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by qualification rigor and metrology integration depth. Premium tiers command substantial markups for sub-7nm single-wafer systems with embedded defect detection, while economy positioning serves PCB manufacturers through distributor channels. Cost compression in mid-tier wet bench configurations is intensifying because Korean and Taiwanese OEMs compete aggressively on throughput metrics for 28nm automotive node qualifications. Foundry alliance buyers exhibit lowest price sensitivity due to multi-site enterprise frameworks, whereas Indian PLI scheme recipients and emerging Southeast Asian packaging houses drive hardest bargain negotiations.
Supply Chain Analysis
Inventory buffers for hydrogen fluoride and sulfuric acid purification systems rarely exceed six weeks, exposing fabs to energy cost spike pass-through from German and Japanese chemical equipment vendors. Component manufacturing concentrates in Japan, Germany, and South Korea, with specialized megasonic transducer fabrication anchored in Kumamoto prefecture and precision brush material production centered on Baden-Württemberg. Single-source vulnerability pervades the subsystem tier where Tokyo Electron and SCREEN Holdings maintain captive supply relationships with designated component partners. Distribution runs through direct OEM contracts for leading-edge logic and memory fabs, while regional distributors serve mid-tier PCB and solar cell manufacturers in Vietnam and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions through multi-node qualification cycles that stretch eighteen to thirty-six months and lock out unproven suppliers.
For Market Incumbents: Fortify positions by deepening backward integration into megasonic transducer and chemical delivery subsystem production, eliminating exposure to Japanese component vendor concentration. Accelerate certification investment for EU F-Gas Regulation compliant vapor-phase chemistries before REACH sunset clauses force twelve-to-eighteen month qualification delays. Defend against emerging Chinese equipment vendors by embedding metrology feedback loops directly into wet bench architectures, raising switching costs for foundry customers. For New Entrants and Emerging Players: Anchor in photomask cleaning automation as EUV pellicle-compatible systems open dedicated equipment categories with less entrenched competition than wafer processing. Target Indian PLI scheme recipients in Gujarat and Karnataka with localized service infrastructure for solar cell and emerging semiconductor fabs. Pursue go-to-market partnerships with German automotive sensor suppliers specifying vapor phase cleaning systems for pre-assembly preparation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EPA perfluorinated compound restrictions and REACH authorization timelines continuously refresh equipment replacement cycles regardless of semiconductor demand cyclicality. Acquisition candidates should display proprietary subsystem integration in megasonic or cryogenic aerosol modules, not merely system assembly capability. Monitor EPA emissions cap enforcement intensity as the signal indicating acceleration or deceleration in wet bench retirement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Subsystems | Captive supply of megasonic transducers insulates margins from Japanese vendor concentration. |
| Multi-Node Qualification Expansion | Simultaneous 3nm logic and 18A foundry validation stretches competitor R&D resources thin. |
| EU F-Gas Regulation Pre-Certification | Early chemistry qualification before REACH sunset clauses locks in European fab replacement demand. |
| Photomask Cleaning Automation Development | Pellicle-compatible systems address EUV mask defectivity requirements below 0.001 defects per square centimeter. |
| India Local Service Infrastructure Buildout | PLI scheme subsidies in Gujarat and Karnataka create first-mover advantage for emerging fab demand. |
Study Parameters
Cross-validation between primary interviews with fab process engineers, OEM platform architects, and chemical supply specialists and secondary validation through SEMI equipment shipment databases, EPA emissions disclosure filings, and METI JIS certification registries anchors the qualitative findings. Bottom-up triangulation aggregates individual tool procurement patterns from foundry alliance purchasing desks, while top-down reconciliation checks against aggregate capital expenditure disclosures from Intel, TSMC, and Samsung. Stakeholder interviews span maintenance directors at 300mm fabs, procurement leads at specialty foundries, aftermarket service heads at Japanese component vendors, and technical R&D directors at chemical equipment suppliers.
Sensitivity analysis around node migration timelines and regulatory phase-out schedules tests forecast robustness across the projection horizon. Segmentation dimensions modeled include equipment type, end-user scale, technology method, and application step, with additional granularity on regional regulatory cluster alignment. CAGRs derive from equipment shipment run-rates normalized against fab capacity expansion announcements and tool replacement cycle assumptions. Industry-specific inputs incorporate EU F-Gas Regulation substitution timelines, EPA perfluorinated compound restriction enforcement patterns, and foundry alliance purchasing desk consolidation trends.
Material uncertainties — abrupt regulatory acceleration, supply chain disruptions from geopolitical friction, and faster-than-anticipated dry cleaning technology substitution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding node shrinkage cadence and chemistry authorization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Photoresist for Semiconductor Market