
 Japan Small Signal Transistor Market | 2026-2036
Japan Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Small Signal Transistor Market Insights
Single-source to multi-source procurement is rebalancing how Japanese OEMs secure small signal transistor supply. Toshiba Corporation leverages its legacy silicon fabrication infrastructure to sustain long-term contracts with domestic automotive tier-1s. ROHM Co., Ltd differentiates through gallium nitride process leadership, occupying a premium position in RF applications where thermal efficiency commands priority.
Small signal transistors are low-power semiconductor switches engineered for signal amplification and switching below one watt, typically fabricated on silicon substrates with doping concentrations precise to parts-per-billion for threshold stability. Their primary purpose spans voltage regulation in portable devices to driver circuits in precision industrial controls. Bipolar junction transistors retain structural dominance in cost-sensitive consumer electronics, while gallium nitride field effect transistors capture the fastest expansion in 5G base station modules where frequency response thresholds exceed silicon physical limits. OEM end users concentrate procurement leverage through volume commitments to captive fabrication partners, compressing margin pools at component manufacturer tiers.
METI's semiconductor strategy, JIS standards for electromechanical reliability, and PMDA-adjacent quality frameworks for automotive-grade components collectively elevate barrier thresholds for non-domestic suppliers seeking Japan market access. These regulations mandate traceable supply chains and accelerated life-test protocols that favor established Japanese fabricators with in-house qualification laboratories. Stakeholders must monitor METI subsidy disbursement timing and foundry utilization rates as signals for capacity allocation decisions.
Market Dynamics
Automotive electrification and METI's domestic fab subsidies are restructuring procurement relationships across Japan's small signal transistor value chain, compressing qualification timelines while elevating traceability requirements.
Growth Catalysts
- Automotive electronics proliferation:Electric powertrain modules and ADAS sensor arrays consume high-reliability discrete components at volumes exceeding legacy internal combustion architectures.
- METI subsidy disbursements:Domestic foundry capacity investments under Japan's semiconductor resilience framework reduce import dependency for critical signal processing components.
- Silicon carbide process maturation:Hybrid substrate technologies extend thermal operating ranges beyond traditional silicon limits, opening RF amplifier applications in base station infrastructure.
Market Restraints
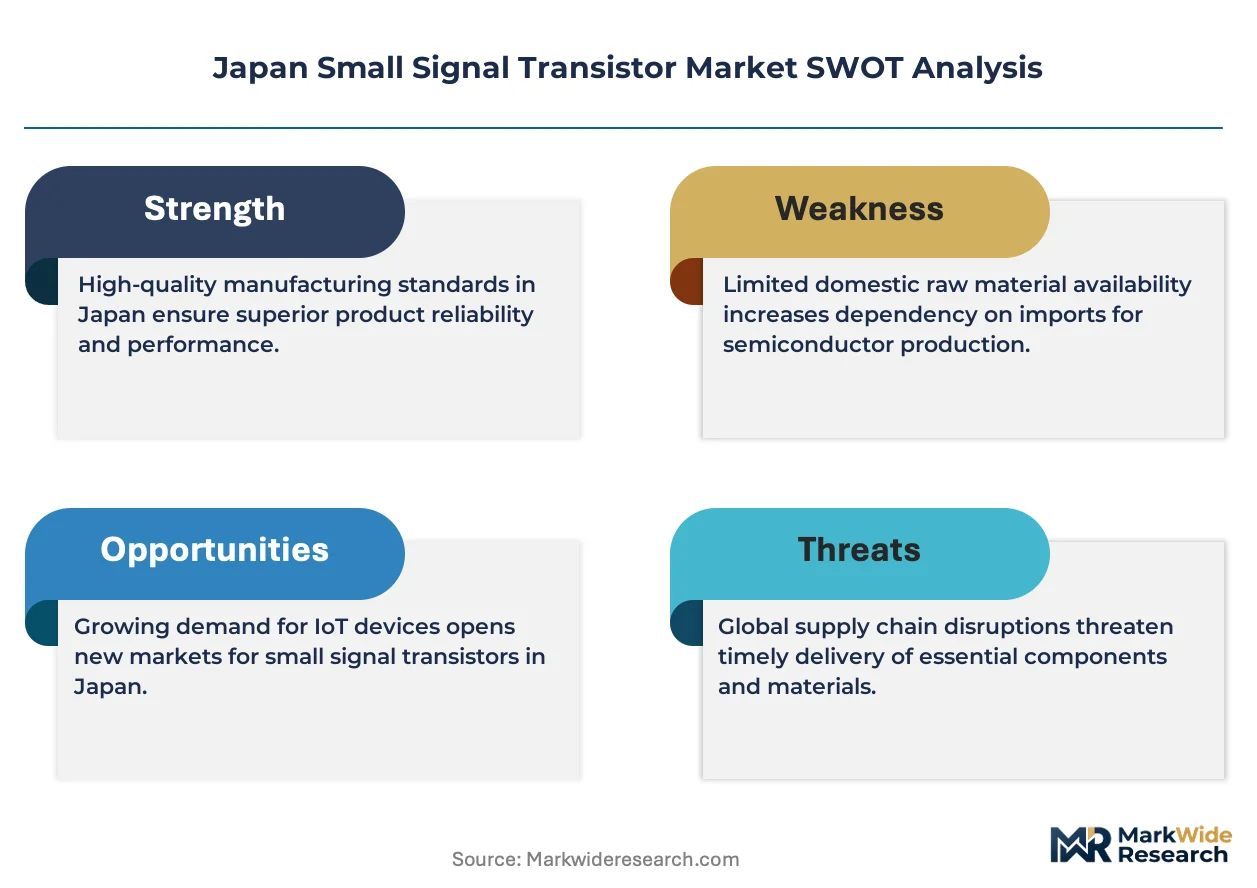
- Raw material concentration:High-purity silicon wafer supply concentrates among three Japanese ingot producers, exposing buyers to allocation risk during demand spikes.
- JIS qualification timelines:Electromechanical reliability testing protocols extend new supplier onboarding to 18-24 months, freezing out non-domestic competitors.
- Gallium nitride substitution pressure:RF applications above 3 GHz increasingly favor wide-bandgap semiconductors, eroding silicon bipolar junction transistor addressable market in base station modules.
Strategic Opportunities
- Kansai industrial corridor expansion:Osaka-Kobe manufacturing clusters seek localized component sourcing to reduce Kanto logistics exposure.
- Medical device integration:PMDA-adjacent quality frameworks for implantable electronics create premium pricing tiers for traceable supply chains.
- 5G small cell densification:Urban micro-base station deployments multiply low-power amplifier demand beyond macro-infrastructure replacement cycles.
Industry Challenges
- Compound semiconductor process engineering shortage:Gallium nitride epitaxy expertise concentrates among retiring specialists, constraining ROHM and rival expansion timelines.
- Legacy equipment integration:Tier-2 automotive suppliers maintain 1990s-era surface-mount lines incompatible with 0201 metric package formats.
- Dual-source qualification burden:OEM multi-sourcing mandates require parallel JIS testing runs, doubling certification costs without volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Small Signal Transistor Market |
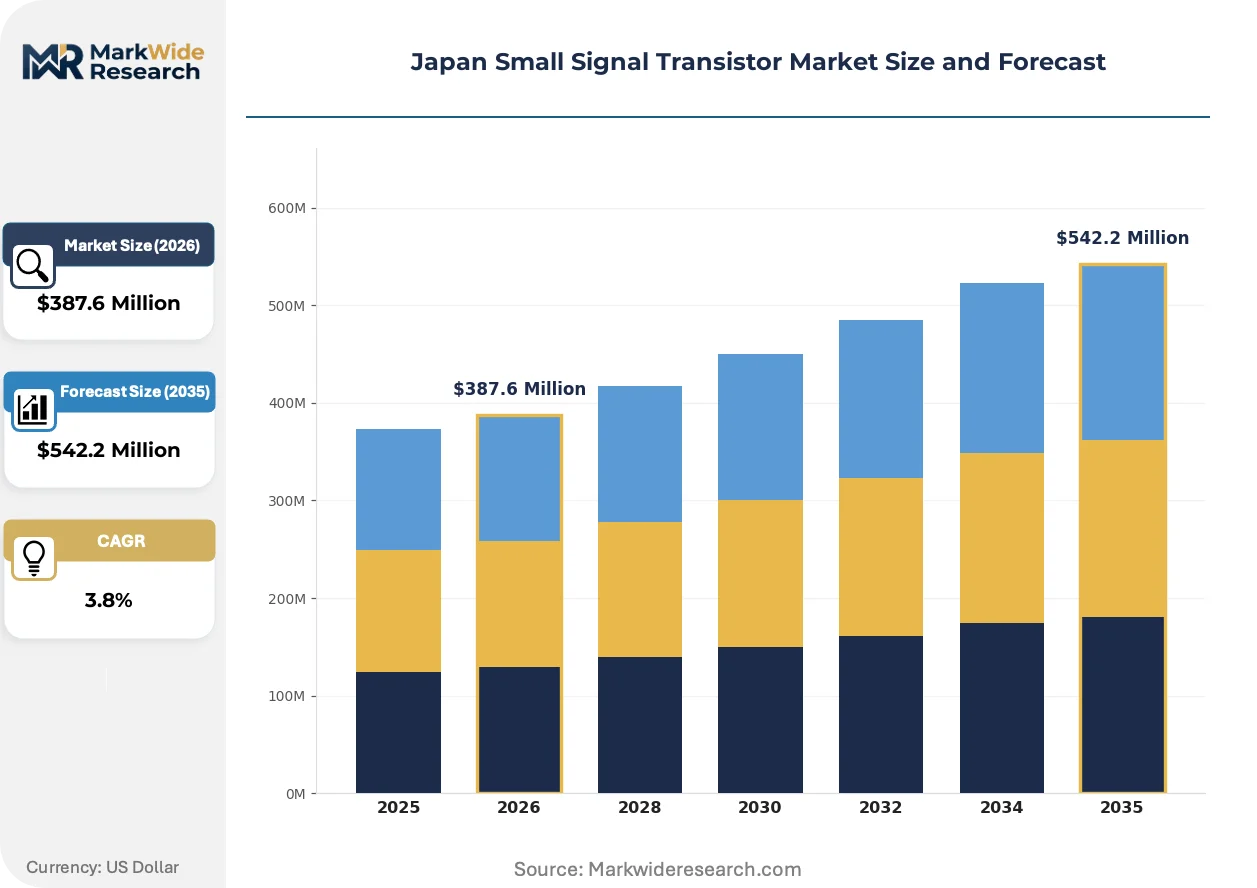
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $542.2 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, Complementary Metal-Oxide-Semiconductor, High Electron Mobility Transistor Application: Consumer Electronics, Telecommunication Equipment, Automotive, Industrial Automation End User: OEMs, Research Institutions, Component Manufacturers, Electronic Device Producers Technology: Silicon, Gallium Nitride, Discretes, Integrated Circuits |
| Companies Covered | Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co., Ltd, Renesas Electronics Corporation, ROHM Co., Ltd, NXP Semiconductors N.V, ON Semiconductor Japan Ltd, Panasonic Holdings Corporation, Sony Semiconductor Solutions Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Small Signal Transistor Market Trends and Innovations
Process miniaturization and substrate material diversification are fragmenting traditional silicon-centric supply structures, while procurement centralization among automotive tier-1s compresses component vendor margins.
Gallium nitride-on-silicon carbide heterostructure technology is modularizing RF front-end architectures, enabling discrete transistor replacement of integrated power amplifier modules in 5G massive MIMO arrays. NTT DOCOMO and Rakuten Mobile base station procurement teams specify GaN discretes for sub-6 GHz macro cells, collapsing incumbent silicon LDMOS supplier relationships. The technology is modularizing what were previously monolithic RF subsystems into swappable, thermally independent components.
METI's 2021 semiconductor strategy revision mandates traceable supply chain documentation for automotive-grade components, compelling tier-1 suppliers to maintain qualification laboratories with accelerated life-test capabilities. Domestic fabricators with in-house JIS certification infrastructure capture incremental volume from foreign competitors lacking Tokyo-based testing presence. Kanto-region automotive electronics clusters absorb the compliance burden fastest, centralizing procurement leverage among Toyota and Honda tier-1 networks.
Consignment inventory arrangements are displacing traditional spot purchasing across Japan's electronics manufacturing services sector, transferring working capital burden from OEMs to component distributors. Tokyo-based trading houses now warehouse six-month transistor buffers at Yokohama logistics hubs, collapsing lead time premiums. Kyushu semiconductor assembly plants exhibit the strongest adoption, where geographic distance from Kanto demand centers amplifies inventory risk aversion.
Japan Small Signal Transistor Market Segmentation
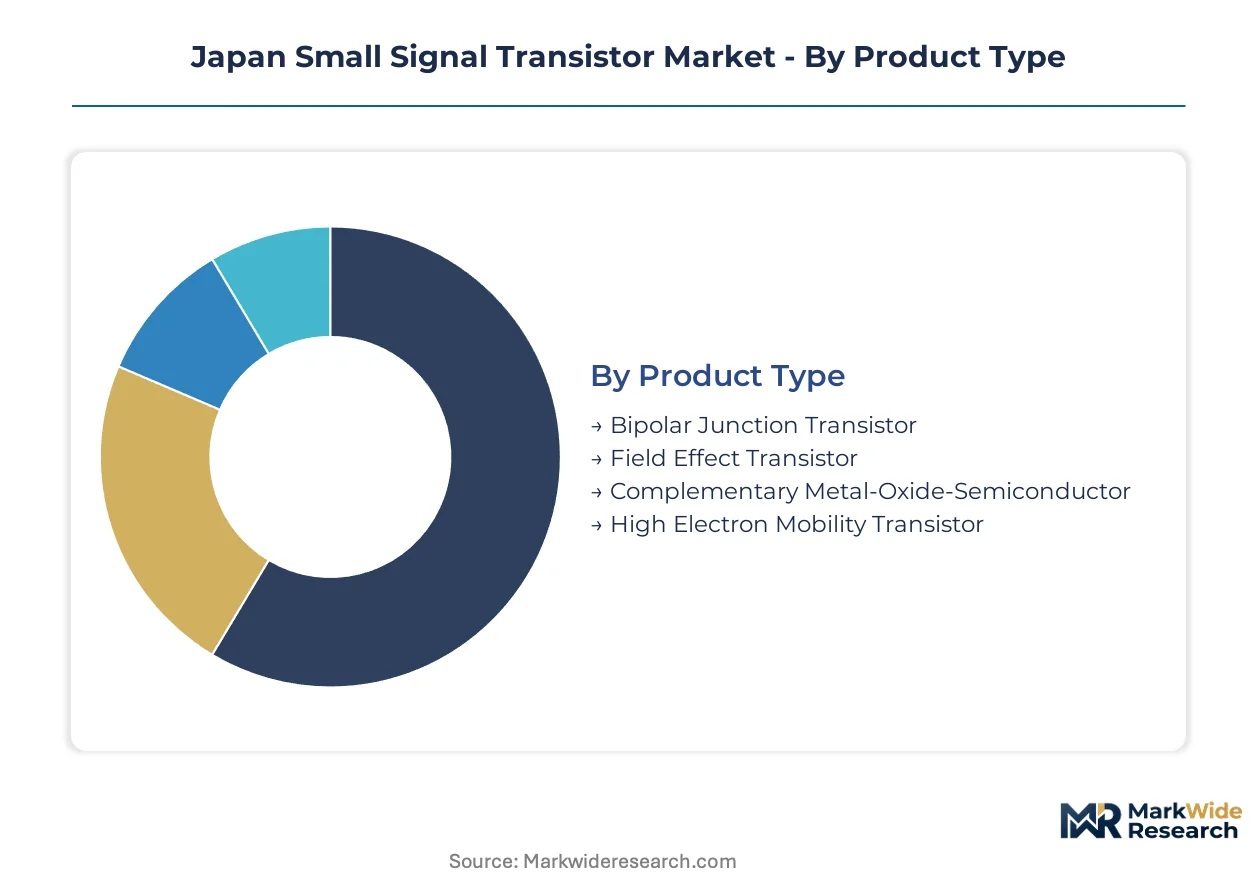
Component specification tiers and application voltage requirements fragment procurement patterns across Japan's small signal transistor market. Understanding these divisions reveals where JIS qualification investments concentrate and which substrate technologies command premium positioning.
Product Type:
Upgrade cycles from legacy silicon bipolar designs to wide-bandgap alternatives are shortening as thermal efficiency benchmarks tighten across automotive and telecom specifications.
- Bipolar Junction Transistor:Silicon-based NPN and PNP structures dominate cost-sensitive consumer electronics where threshold stability tolerances remain relaxed. Volume procurement concentrates among Osaka-Kobe EMS clusters serving white goods manufacturers; JIS qualification timelines here stretch 18 months due to electromechanical reliability protocols.
- Field Effect Transistor:Voltage-controlled channel modulation enables sub-milliwatt switching losses in precision instrumentation. Kanto-region automotive tier-1s specify MOSFET variants for electric powertrain sensor interfaces, with METI subsidy disbursements accelerating domestic fab migration from bipolar legacy lines.
- Complementary Metal-Oxide-Semiconductor:Paired NMOS-PMOS arrays deliver rail-to-rail logic switching for mixed-signal integrated peripherals. Tokyo electronics manufacturing services absorb the bulk of CMOS discrete demand for portable device voltage regulation subsystems.
- High Electron Mobility Transistor:Gallium nitride heterostructures achieve electron mobility rates exceeding silicon physical limits for millimeter-wave amplification. NTT DOCOMO base station procurement teams specify HEMT discretes for sub-6 GHz massive MIMO deployments, collapsing incumbent LDMOS supplier relationships.
Volume placements concentrate in Bipolar Junction Transistor; the faster expansion belongs to High Electron Mobility Transistor.
Application:
End-use voltage thresholds and thermal cycling intensity stratify component reliability requirements across Japan's manufacturing base.
- Consumer Electronics:Low-power audio amplification and display driver circuits in smartphones, tablets, and wearable devices. Osaka-based EMS providers consolidate procurement through consignment inventory arrangements at Yokohama logistics hubs.
- Telecommunication Equipment:RF front-end modules and base station signal conditioning demand wide-bandgap thermal performance. 5G small cell densification across Tokyo and Yokohama metropolitan corridors multiplies discrete amplifier procurement beyond macro-infrastructure replacement cycles.
- Automotive:ADAS sensor arrays and electric powertrain control modules specify automotive-grade AEC-Q101 qualified components. Toyota and Honda tier-1 networks centralize procurement leverage through volume commitments to captive fabrication partners.
- Industrial Automation:Precision motor drives and programmable logic controller interfaces require extended temperature range operation. Kyushu semiconductor assembly plants exhibit strongest adoption of consignment inventory models due to geographic distance from Kanto demand centers.
Procurement scale peaks in Automotive; Medical device integration is gaining share fastest.
End User:
Qualification infrastructure ownership and volume commitment scale determine pricing leverage across Japan's procurement tiers.
- OEMs:Toyota, Honda, and Sony maintain in-house component engineering teams that specify custom threshold voltages and package formats. Direct foundry relationships compress margin pools at distributor tiers.
- Research Institutions:NTT and AIST laboratories prototype next-generation heterostructure devices before commercial handoff. Small-batch procurement tolerates extended lead times for experimental die specifications.
- Component Manufacturers:Rohm and Toshiba captive fabrication divisions supply internal product divisions while competing for external EMS accounts. Vertical integration into epitaxy growth constrains rival expansion timelines.
- Electronic Device Producers:Tier-2 automotive suppliers and consumer EMS providers lack JIS qualification laboratories, forcing reliance on distributor-managed inventory buffers.
Contract concentration sits with OEMs; Research Institutions are expanding procurement most steeply.
Technology:
Substrate material properties dictate frequency response ceilings and thermal dissipation thresholds across application specifications.
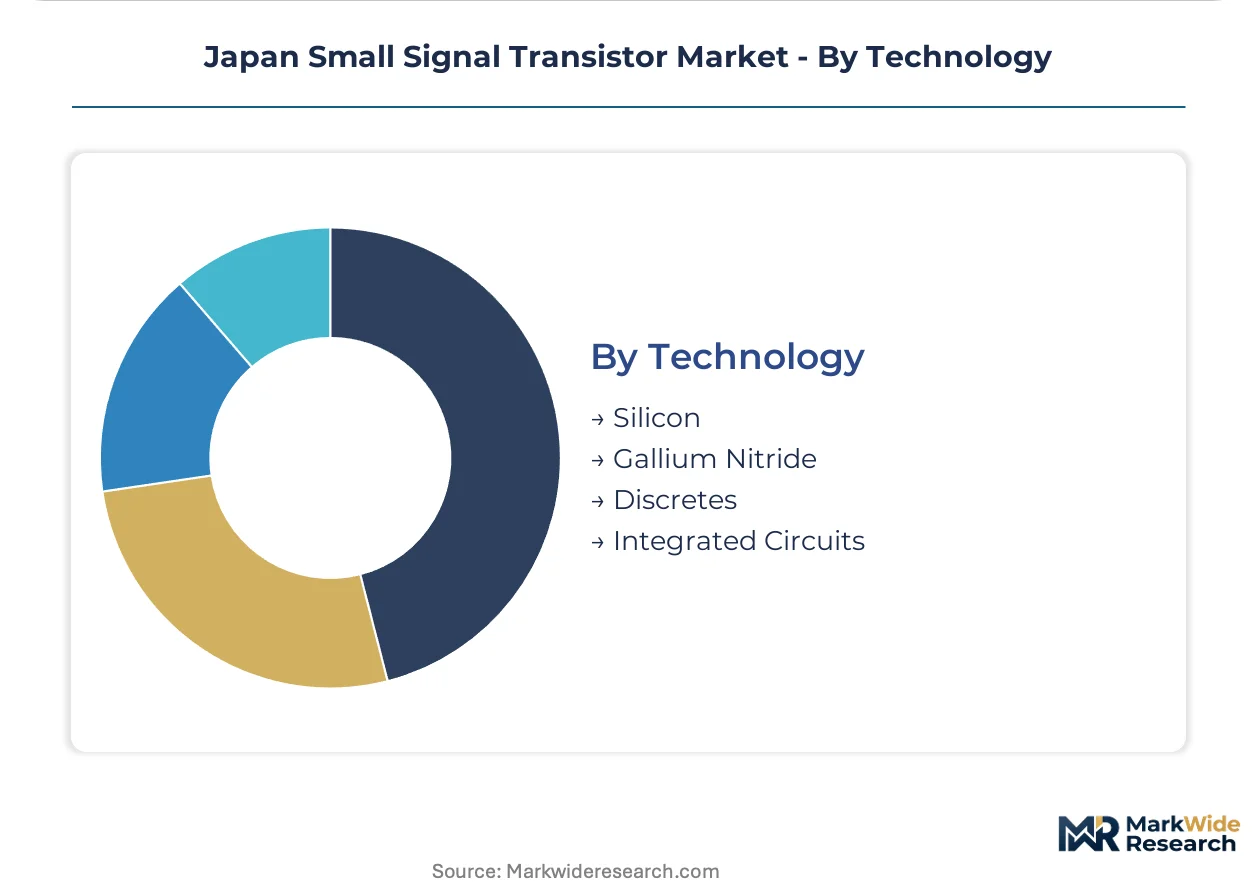
- Silicon:Mature 200mm wafer fabrication infrastructure supports cost-optimized bipolar and MOS architectures. Three Japanese ingot producers concentrate high-purity silicon supply, exposing buyers to allocation risk during demand spikes.
- Gallium Nitride:Wide-bandgap band structure enables power density multiplication in RF amplification and power switching. Compound semiconductor process engineering shortage constrains epitaxy capacity expansion at Rohm and domestic rivals.
- Discretes:Individual packaged transistors retain procurement relevance where thermal isolation or repairability priorities override integration economics. Legacy 1990s-era surface-mount lines at tier-2 automotive suppliers remain incompatible with 0201 metric package formats.
- Integrated Circuits:Monolithic multi-transistor arrays displace discrete solutions in space-constrained portable electronics. Consignment inventory arrangements transfer working capital burden from OEMs to Tokyo-based trading houses warehousing six-month buffers.
Silicon captures dominant volume; Gallium Nitride is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon ingot production concentrates in three Japanese suppliers, anchoring domestic fabrication capacity and exposing downstream buyers to allocation risk during demand spikes.
Kanto
Tokyo's electronics manufacturing cluster anchors procurement volume for automotive tier-1s and telecom equipment vendors. METI's semiconductor resilience framework channels subsidy disbursements toward domestic foundry investments in this corridor. Yokohama logistics hubs warehouse six-month transistor buffers under consignment inventory arrangements with Tokyo-based trading houses.
Kansai
Osaka-Kobe manufacturing clusters seek localized component sourcing to reduce logistics exposure from Kanto-centric supply chains. JIS qualification timelines for electromechanical reliability protocols stretch 18-24 months here, freezing out non-domestic competitors. White goods manufacturers drive bipolar junction transistor volume through consolidated EMS procurement.
Chubu
Nagoya's automotive electronics corridor concentrates Toyota and Honda tier-1 networks with captive fabrication partnerships. AEC-Q101 qualification requirements for ADAS sensor arrays and electric powertrain modules elevate traceability mandates. PMDA-adjacent quality frameworks for automotive-grade components favor established fabricators with in-house testing laboratories.
Kyushu
Semiconductor assembly plants in this southern region exhibit strongest adoption of consignment inventory models due to geographic distance from Kanto demand centers. Industrial automation applications for precision motor drives require extended temperature range operation. Legacy surface-mount lines at tier-2 automotive suppliers remain incompatible with 0201 metric package formats.
Tohoku
Research institutions including AIST laboratories prototype next-generation heterostructure devices before commercial handoff to fabrication partners. Small-batch procurement tolerates extended lead times for experimental die specifications. Compound semiconductor process engineering shortage constrains epitaxy capacity expansion among domestic rivals seeking to scale gallium nitride production.
Japan Small Signal Transistor Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic fabricators scale silicon and compound semiconductor output under METI subsidy programs. The vendor base clusters around three tiers: integrated conglomerates with captive foundries, specialized discrete component manufacturers, and foreign-owned subsidiaries with local qualification infrastructure. Strategic archetypes include backward-integrated silicon specialists, gallium nitride process leaders, and automotive-qualified volume suppliers. Technology licensing agreements and multi-source procurement mandates constitute the primary competitive moves reshaping supplier relationships.
Among Japan-based fabricators, Toshiba Corporation and ROHM Co., Ltd occupy distinct positioning vectors within the competitive structure. Toshiba exemplifies the legacy silicon fabrication archetype, leveraging established infrastructure to sustain long-term supply relationships with domestic automotive networks. ROHM represents the compound semiconductor specialization tier, where gallium nitride process capabilities command premium positioning in RF amplification applications. Renesas Electronics Corporation anchors the integrated device manufacturer segment, combining microcontroller dominance with discrete component supply to tier-1 automotive customers.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Fuji Electric Co., Ltd |
| Renesas Electronics Corporation |
| ROHM Co., Ltd |
| NXP Semiconductors N.V |
| ON Semiconductor Japan Ltd |
| Panasonic Holdings Corporation |
| Sony Semiconductor Solutions Corporation |
| Others |
Pricing and Supply Chain Analysis
Toyota and Honda tier-1 procurement networks concentrate volume leverage, forcing contract-based long-term offtake structures that compress spot-market premiums for non-captive suppliers. JIS qualification timelines and METI traceability mandates embed service-bundling into base pricing, elevating total cost of ownership for buyers lacking in-house testing infrastructure.
Pricing Analysis
Warranty and accelerated life-test bundling separates automotive-grade AEC-Q101 qualified supply from unqualified commercial tiers, with premium-mid-economy pricing differentiation anchored on certification grade and volume scale. Cost compression in silicon bipolar junction transistors intensifies as gallium nitride substitution erodes RF addressable share, while gallium nitride heterostructures command price inelasticity among NTT DOCOMO base station procurement teams. Tier-2 automotive suppliers exhibit highest price sensitivity due to legacy equipment incompatibility with advanced package formats.
Supply Chain Analysis
Yokohama logistics hubs function as regional distribution centers, warehousing six-month transistor buffers under consignment inventory arrangements that transfer working capital burden to Tokyo-based trading houses. High-purity silicon wafer supply draws from three Japanese ingot producers, creating single-source vulnerability during demand spikes. Gallium nitride epitaxy capacity rests on retiring specialist expertise, constraining domestic fab expansion. Distribution runs through captive fabrication partnerships for tier-1 automotive networks, while EMS providers rely on distributor-managed inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride epitaxy capacity constraints prop pricing premiums for RF-qualified supply, insulating backward-integrated fabricators from silicon commoditization pressure.
For Market Incumbents: Lock in long-term wafer supply agreements with Japanese ingot producers before allocation risk materializes during automotive electrification demand spikes. Accelerate in-house JIS qualification laboratory investments to capture tier-1 automotive volume migrating from foreign competitors lacking Tokyo-based testing presence. Defend against ROHM's gallium nitride process leadership by expanding silicon carbide hybrid substrate capabilities for thermal-extended applications. For New Entrants and Emerging Players: METI's semiconductor resilience subsidies in Japan open a window for domestic fab partnerships targeting Kansai industrial corridor localization demand. Medical device integration under PMDA-adjacent quality frameworks offers the most penetrable premium tier, as traceable supply chain requirements favor new entrants with purpose-built qualification infrastructure. Pursue consignment inventory arrangements with Osaka-based EMS providers seeking reduced Kanto logistics exposure. For Investors and Strategic Acquirers: The window for entry favors compound semiconductor specialists with proven gallium nitride epitaxy yield rates. Long-term viability hinges on captive integration into substrate growth and automotive qualification infrastructure. Watch METI subsidy disbursement timing and domestic foundry utilization rates as inflection signals for capacity allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Capacity Expansion | METI subsidy disbursements reduce import dependency for critical signal processing components. |
| Gallium Nitride Process Development | NTT DOCOMO base station specifications favor wide-bandgap thermal performance in sub-6 GHz deployments. |
| JIS Qualification Infrastructure Investment | In-house electromechanical reliability testing captures tier-1 automotive volume from foreign competitors. |
| Consignment Inventory Partnerships | Tokyo trading houses absorb working capital burden from EMS providers in Kyushu assembly corridors. |
| Silicon Carbide Hybrid Substrate Migration | Thermal operating range extension opens RF amplifier applications in 5G small cell infrastructure. |
Research Methodology
Document review covered METI policy filings, JIS standards documentation, and semiconductor trade flow data, complemented by interviews with tier-1 automotive procurement directors, foundry operations managers, and gallium nitride epitaxy specialists. Secondary validation drew from customs records, AEC-Q101 qualification databases, and base station deployment disclosures by NTT DOCOMO and Rakuten Mobile. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume estimates.
Segment-level outputs across product type, application, end user, and technology dimensions were modeled over the projection horizon, with CAGRs derived from elasticity-adjusted demand curves and foundry capacity expansion schedules. Inputs included automotive electronics content-per-vehicle trajectories, 5G small cell densification pipelines, and METI subsidy disbursement timelines.
The model assumes gradual silicon carbide process maturation for thermal-extended applications; alternative pathways for gallium nitride-on-silicon heterostructures would alter the outlook for RF amplification market share. Forecasts reflect documented assumptions regarding subsidy continuity and ingot supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Global Gan RF Devices Market
RF Components
Flat Panel Antenna Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Global RF Plasma Generator Market
RF Components
Dielectric Resonator Market
RF Components
Millimeter Wave Equipment Market
RF Components
EMI Microwave Absorber Market
RF Components
Wireless Module Market
RF Components
5G Driver Amplifier Market
RF Components
Digital Radio Frequency Market
RF Components
High Power RF Amplifier Module Market
RF Components
Global RF Power Semiconductor Market