
 Automatic Dicing Saw Market | 2026-2036
Automatic Dicing Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Dicing Saw Market Outlook
Japanese precision equipment manufacturing is hardening as the dominant supply base for sub-10-micron dicing applications. DISCO Corporation leverages its proprietary blade technology to sustain leadership in high-volume silicon wafer processing. Tokyo Seimitsu Co., Ltd. anchors its competitive position through integrated spindle and motion-control systems that reduce kerf loss.
An automatic dicing saw is a precision machining system that uses rotating diamond blades, laser ablation, or water-jet guidance to singulate semiconductor wafers, integrated circuits, or brittle substrates into individual die with positional accuracy below 5 microns. The equipment employs vacuum chuck tables, vision alignment, and real-time blade-height sensing to protect fragile thinned wafers during high-speed cutting cycles. Blade type systems dominate current installed base owing to mature service networks and lower capital thresholds, while laser type configurations capture expanding margin pools in compound semiconductor and MEMS applications where thermal damage must be eliminated. Thin wafer dicing technology leads R&D allocation as 3D stacking architectures force substrate thickness below 50 microns.
Japan's METI coordinates domestic equipment standards through JIS certification requirements that constrain non-compliant imports. The US FDA and EPA jointly influence market access through semiconductor manufacturing emissions rules and occupational exposure limits on coolant aerosols. Taiwan's Industrial Development Bureau enforces local content incentives that reshape vendor qualification timelines for foundry capex cycles. Stakeholders must monitor how dual-use export control expansions affect spare-part availability and service technician mobility across East Asian install bases.
Market Dynamics
Wafer thinning below 50 microns for 3D stacking architectures is forcing equipment vendors to redesign chuck tables, blade materials, and thermal management systems simultaneously. This substrate thickness compression is reshaping procurement specifications across foundry and OSAT tiers.
Growth Catalysts
- AI chip foundry expansion:Taiwan and South Korean semiconductor manufacturers are commissioning new dicing lines to singulate GPU and accelerator die. This capital deployment pulls blade and laser system orders through 2030.
- METI equipment subsidies:Japan's Ministry of Economy, Trade and Industry is accelerating domestic fab upgrades through targeted grants. Domestic vendors capture preferential qualification for sub-10-micron applications.
- Compound semiconductor volume:Silicon carbide and gallium nitride power device manufacturing is expanding. Laser dicing configurations eliminate thermal damage that blade systems inflict on these brittle substrates.
Market Restraints
- Spindle supply concentration:Precision air-bearing spindle manufacturing concentrates among Japanese and German specialists. Geopolitical friction threatens spare-part availability for multi-year equipment lifecycles.
- Blade consumable cost volatility:Synthetic diamond grit and nickel electroforming chemistry face raw material price swings. Dicing houses absorb margin pressure when blade replacement cycles compress.
- Dual-use export controls:Expanded semiconductor manufacturing equipment restrictions complicate technician mobility and software updates across East Asian install bases.
Strategic Opportunities
- India OSAT greenfield development:The country's PLI scheme for semiconductor assembly and testing is attracting first-mover equipment vendors. Early entrants shape qualification standards for emerging packaging clusters.
- Stealth dicing adoption:Laser-induced spallation technology is converging with conventional blade workflows. Hybrid process flows open margin pools in MEMS and sensor singulation.
- EU Green Deal alignment:REACH-compliant coolant formulations and energy-efficient spindle designs qualify for preferential procurement scoring. Vendors certifying low-emission configurations access sustainability-driven capex pools.
Industry Challenges
- Thin wafer handling expertise:Operators skilled in sub-50-micron vacuum chucking and crack-propagation control remain scarce. Training pipelines lag equipment deployment timelines.
- JIS certification complexity:Japan's industrial standards for precision equipment impose lengthy documentation and testing protocols. Foreign vendors face 18-24 month qualification delays.
- Legacy system integration:Brownfield fabs require dicing saws to interface with proprietary MES and inspection databases. Custom software bridges inflate deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Dicing Saw Market |
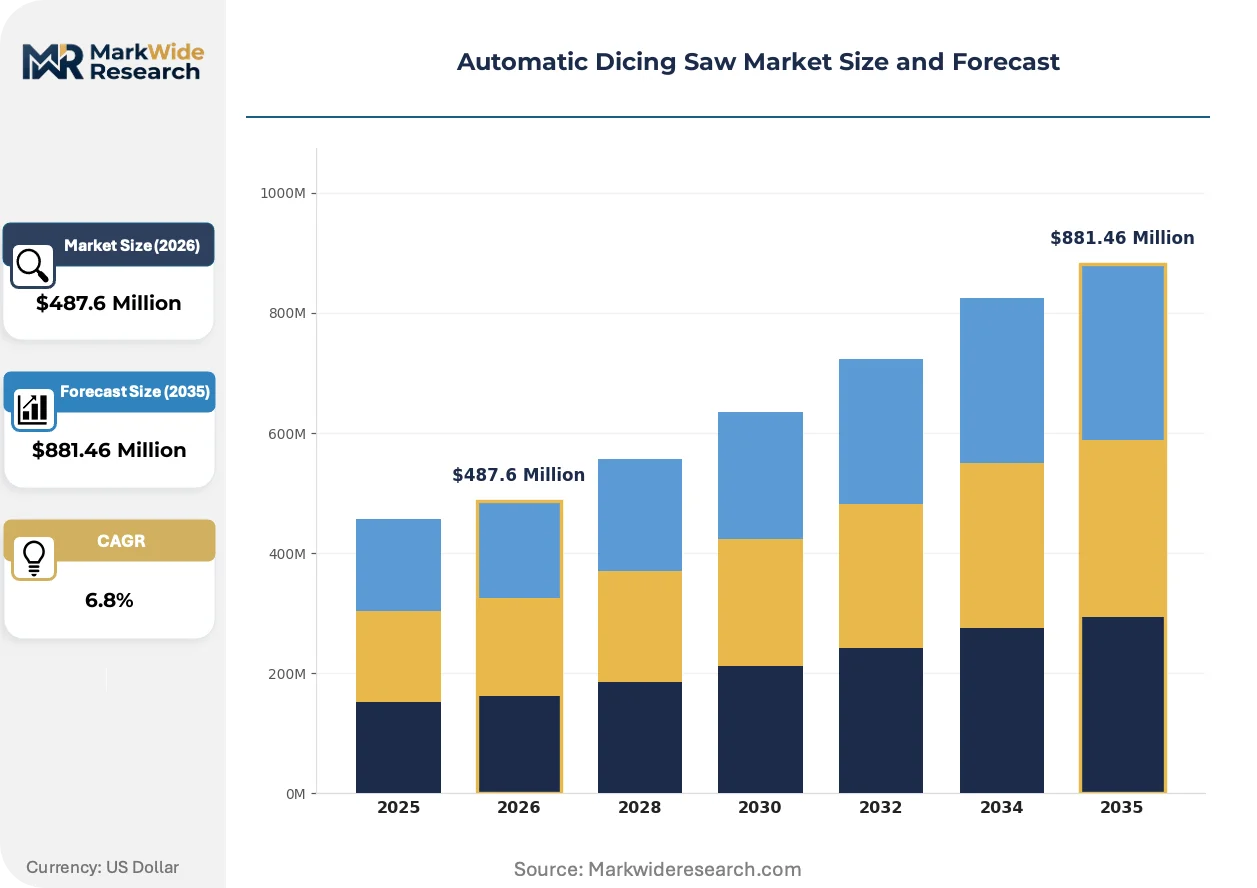
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Type, Laser Type, Water Jet Type, Diamond Wire Type Technology: Precision Dicing, Thin Wafer Dicing, High-Speed Dicing, Automated Dicing End User: Semiconductor Manufacturers, Electronics Industry, Optoelectronics Firms, Packaging Companies Application: Wafer Dicing, IC Dicing, Glass Dicing, Solar Cell Dicing |
| Companies Covered | DISCO Corporation, Tokyo Seimitsu Co., Ltd., Advanced Dicing Technologies, ASMPT ALSI, Jiangsu Jing Chuang Co. Ltd., Kulicke & Soffa Industries, Inc., Loadpoint Limited, Panasonic Connect Co. Ltd., Synova SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Dicing Saw Market Strategic Shifts
Laser-based singulation technologies are capturing share from mechanical blade systems as substrate brittleness and thermal sensitivity intensify. Equipment architectures are fragmenting into application-specific configurations rather than universal platforms.
Hybrid dicing workflows are modularizing process sequences across blade scoring, laser ablation, and plasma stealth dicing stages. Memory manufacturers in South Korea are adopting these configurable lines to handle heterogeneous die stacks. The technology is modularizing equipment purchasing decisions from monolithic system buys toward staged capability upgrades.
Japan's METI is tightening JIS certification requirements for semiconductor manufacturing equipment imported under domestic subsidy programs. Compliance documentation now mandates extended reliability testing and local service presence. European and North American vendors are responding by establishing Yokohama-based technical centers to compress approval timelines.
Foundry procurement teams are unbundling after-sales service contracts from initial equipment purchases. Taiwan-based OSATs now negotiate blade consumables, spindle refurbishment, and software maintenance as separate line items. This behavior is most visible in Kaohsiung and Tainan packaging clusters where multi-vendor tool parks complicate unified service agreements.
Automatic Dicing Saw Market Segmentation
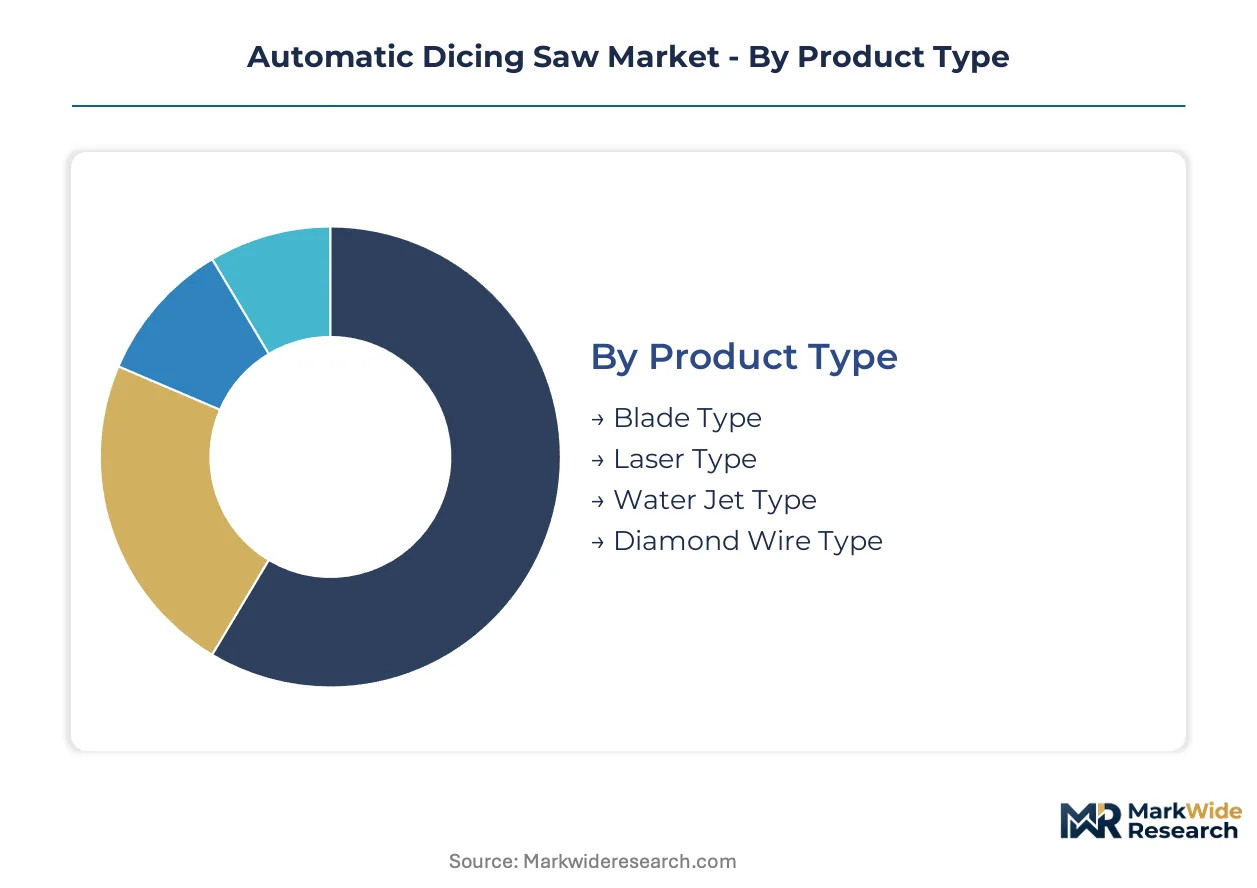
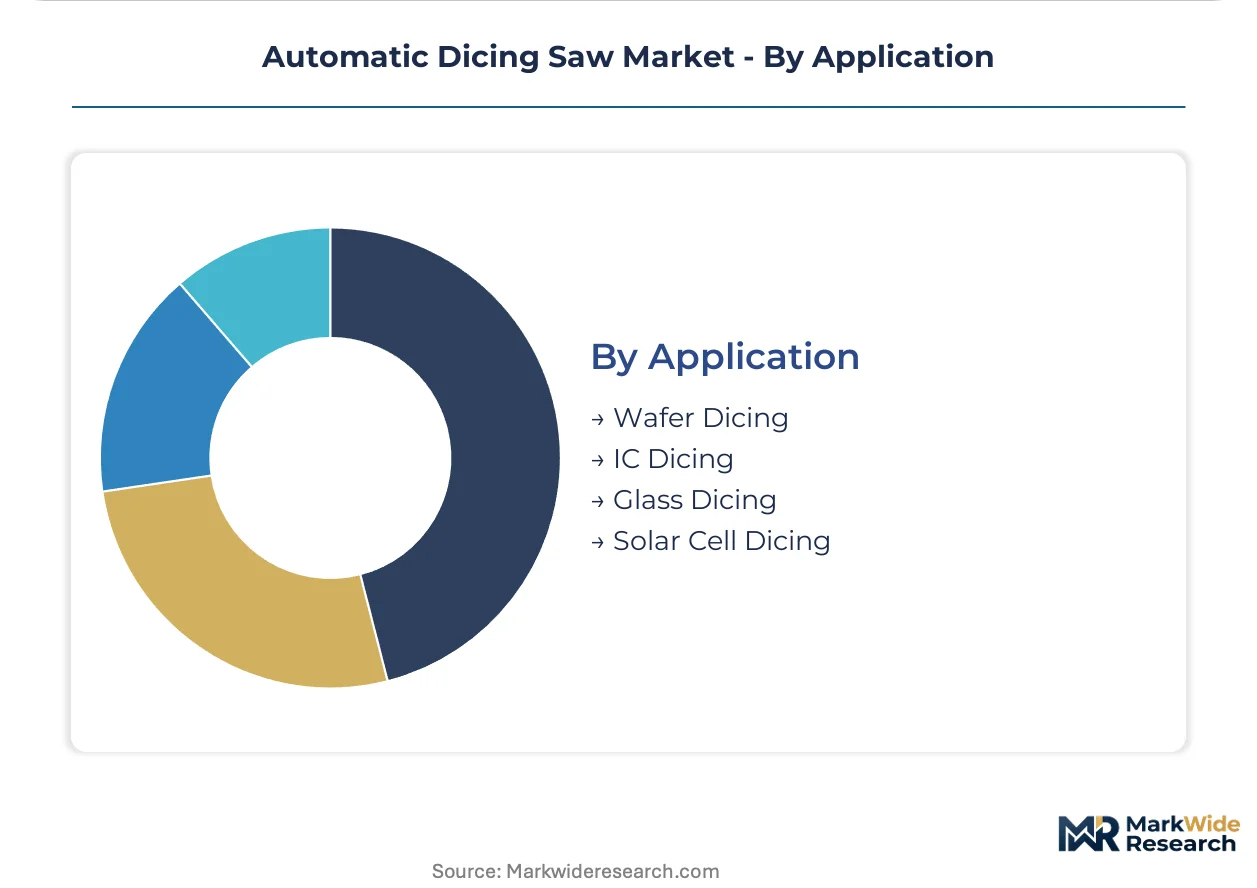
Equipment procurement in the Automatic Dicing Saw Market fragments across four distinct dimensions. Each segmentation layer reveals divergent technology requirements and margin structures that vendors must navigate.
Product Type:
Blade systems dominate unit volume while laser configurations command premium pricing tiers.
- Blade Type:Rotating diamond-embedded wheels cut silicon wafers through mechanical abrasion. Taiwan Semiconductor Manufacturing Company and Samsung Foundry deploy these systems for high-volume GPU die singulation where throughput economics override thermal concerns.
- Laser Type:Pulsed ultraviolet or infrared beams ablate material without mechanical contact. Compound semiconductor fabs in South Korea favor this technology for silicon carbide power devices where blade-induced microcracks destroy device yield.
- Water Jet Type:High-pressure abrasive slurry streams guide cutting paths for thick substrates.
- Diamond Wire Type:Continuous loop wires embedded with diamond grit slice through brittle ceramics and sapphire.
Mature deployment sits with Blade Type systems across legacy silicon foundries. Newer deployment is concentrated in Laser Type configurations for wide-bandgap semiconductor processing.
Technology:
Process sophistication separates cost tiers from commodity dicing to precision-engineered singulation.
- Thin Wafer Dicing:Specialized chuck tables and crack-propagation control handle substrates below 50 microns. Memory manufacturers in South Korea deploy these systems for 3D NAND stacking architectures where wafer fragility demands vacuum-assisted handling and real-time blade-height sensing.
- Precision Dicing:Sub-5-micron positional accuracy serves MEMS and sensor applications. Japanese OSATs in Kyoto and Osaka prefectures specify these systems for accelerometer and gyroscope singulation where die placement tolerance determines package reliability.
- High-Speed Dicing:Optimized spindle RPM and feed rates maximize throughput for commodity silicon.
- Automated Dicing:Integrated vision alignment and cassette-to-cassette handling reduce operator intervention.
Equipment spending tilts toward Thin Wafer Dicing as substrate thinning accelerates across AI chip packaging roadmaps. Precision Dicing maintains stable procurement volumes from automotive sensor suppliers.
End User:
Customer scale and integration depth reshape vendor qualification requirements and contract structures.
- Semiconductor Manufacturers:Integrated device foundries and memory houses operate captive dicing lines. Taiwan-based pure-play foundries in Hsinchu and Tainan Science Parks specify equipment with JIS certification and local service presence to satisfy METI-linked subsidy compliance.
- Packaging Companies:OSATs serving fabless design houses purchase configurable systems. Kaohsiung packaging clusters negotiate unbundled service contracts separating blade consumables from equipment capital.
- Electronics Industry:Module assemblers and subsystem integrators operate lower-volume dicing for printed circuit board components.
- Optoelectronics Firms:LED and photonics manufacturers cut gallium arsenide and indium phosphide substrates.
Semiconductor Manufacturers concentrate capital deployment for advanced node die singulation. Packaging Companies represent the fastest-growing procurement segment as outsourced assembly expands in India and Southeast Asia.
Application:
Material properties and die fragility dictate equipment specification priorities across use cases.
- Wafer Dicing:Full-wafer singulation into individual die remains the core volume application. Foundries processing 300mm silicon wafers for AI accelerators drive demand for systems handling thinned substrates with minimal edge chipping.
- IC Dicing:Singulation of packaged integrated circuits from lead frames or laminate substrates. Japanese automotive semiconductor suppliers in Aichi and Hiroshima prefectures specify dry-cut configurations to eliminate coolant contamination on sensitive circuit surfaces.
- Glass Dicing:Processing of display cover glass and MEMS substrates.
- Solar Cell Dicing:Silicon wafer cutting for photovoltaic cell manufacturing.
Wafer Dicing absorbs the majority of installed capacity for mainstream semiconductor production. IC Dicing is gaining share fastest as chiplet-based packaging architectures multiply singulation steps per finished device.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic diamond grit supply chains and precision spindle manufacturing anchor equipment production in East Asian industrial corridors. Taiwan, South Korea, and Japan concentrate wafer dicing demand as foundry capacity expands for AI accelerator chips. Regulatory frameworks in each jurisdiction reshape vendor qualification timelines and subsidy access.
Taiwan
TSMC and United Microelectronics Corporation are commissioning dicing lines for GPU die singulation at Tainan and Hsinchu Science Parks. The Industrial Development Bureau enforces local content incentives that extend vendor qualification periods for foreign equipment suppliers. Kaohsiung packaging clusters now negotiate unbundled service contracts separating blade consumables from capital purchases.
South Korea
Samsung Foundry and SK Hynix are deploying laser dicing configurations for silicon carbide power devices and 3D NAND memory stacks. The Ministry of Trade, Industry and Energy channels domestic equipment subsidies toward sub-10-micron precision applications. Memory manufacturers in the Yongin and Icheon corridors are adopting hybrid dicing workflows across blade scoring and laser ablation stages.
Japan
DISCO Corporation and Tokyo Seimitsu Co., Ltd. dominate precision spindle and blade technology supply through Kyoto and Osaka prefecture manufacturing bases. METI coordinates JIS certification requirements that impose 18-24 month documentation protocols on non-compliant imports. Japanese OSATs in the Chubu region specify dry-cut configurations for automotive sensor singulation.
China
Yangtze Memory Technologies and SMIC are expanding captive dicing capacity for domestic AI chip production pipelines. MIIT semiconductor equipment standards prioritize local vendor qualification for state-backed fab construction programs. The Yangtze River Delta cluster around Shanghai concentrates both equipment demand and emerging domestic blade manufacturing capabilities.
United States
Intel and GlobalFoundries are retrofitting dicing lines for chiplet-based packaging architectures at Arizona and New York fabrication facilities. The EPA and FDA jointly influence market access through semiconductor manufacturing emissions rules and occupational exposure limits on coolant aerosols. The Southwest packaging corridor is attracting equipment vendors seeking proximity to federal CHIPS Act subsidy recipients.
Automatic Dicing Saw Market Competitive Environment
Global majors compete with regional champions across precision spindle technology and blade material science. The vendor base stratifies into three tiers: integrated Japanese precision equipment houses, European laser system specialists, and emerging Chinese fabricators. Two dominant competitive moves are reshaping positioning: METI-linked subsidy compliance requirements are forcing foreign vendors to establish Yokohama-based technical centers, and foundry procurement teams are unbundling after-sales service contracts from initial equipment purchases.
Within the integrated precision equipment tier, DISCO Corporation and Tokyo Seimitsu Co., Ltd. occupy positions defined by proprietary blade technology and motion-control system integration. Among European laser system specialists, Synova SA represents configurations eliminating thermal damage for compound semiconductor applications. These three companies exemplify archetypes that foreign vendors must match to qualify for East Asian foundry procurement cycles.
| Leading Market Players |
|---|
| DISCO Corporation |
| Tokyo Seimitsu Co., Ltd. |
| Advanced Dicing Technologies |
| ASMPT ALSI |
| Jiangsu Jing Chuang Co. Ltd. |
| Kulicke & Soffa Industries, Inc. |
| Loadpoint Limited |
| Panasonic Connect Co. Ltd. |
| Synova SA |
| Others |
Value Chain & Pricing Dynamics
Precision spindle engineers concentrated in Japan's Kyoto-Osaka corridor command compensation premiums that widen pricing spreads between premium-tier Japanese equipment and mid-tier alternatives sourced from Taiwan or China. Labor-cost differentials in specialized air-bearing manufacturing propagate through equipment quotes, separating JIS-certified configurations from non-compliant imports by substantial margins.
Pricing Analysis
Warranty and service bundling separates capital-equipment quotes from unbundled procurement patterns now dominant in Taiwan's Kaohsiung packaging clusters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and local service presence, with JIS-compliant Japanese systems commanding top tier. Cost compression in standard-tier blade systems intensifies as synthetic diamond grit price volatility feeds through consumable economics. OSATs in Southeast Asia exhibit highest price sensitivity, while captive foundry lines in Taiwan and South Korea prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Synthetic diamond grit supply rests on Japanese and German specialty producers, with electroformed blade manufacturing concentrated in Japan, Taiwan, and South Korea. Air-bearing spindles, nickel electroforming chemistry, and precision motion-control systems constitute critical input dependencies. Single-source vulnerability in spindle supply threatens equipment lifecycle support across multi-year depreciation schedules. Distribution runs through direct OEM sales to integrated device manufacturers and regional distributor networks serving OSAT tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's METI semiconductor equipment subsidies function as a cost-of-compliance barrier, extending qualification timelines for non-JIS-certified vendors and entrenching domestic incumbents with approved local service infrastructure.
For Market Incumbents: Hedge against laser dicing displacement by acquiring stealth-dicing technology capabilities or licensing laser-induced spallation patents from European specialists. Backward integration into synthetic diamond grit supply insulates margin structures from raw material volatility. Establish Yokohama-based technical centers to compress JIS certification timelines for foreign market access. For New Entrants and Emerging Players: Regional equipment distributors in India's emerging OSAT corridors represent the most penetrable channel entry point. Target packaging houses in Gujarat and Karnataka seeking first-mover qualification partnerships. White-space opportunity sits with hybrid dicing workflow modules that bridge blade and laser process steps. Lead with dry-cut configurations to differentiate from coolant-dependent Japanese legacy install bases. For Investors and Strategic Acquirers: Re-rating potential sits with precision spindle specialists given dual-use export control expansions tightening supply scarcity. Long-term viability favors vendors with captive blade material science and established METI subsidy qualification pathways. Monitor technician mobility restrictions across East Asian install bases as inflection signal for service-revenue capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | Unlocks METI subsidy-linked procurement pools in Japanese domestic fab upgrades. |
| Hybrid Dicing Module Development | Captures margin expansion as memory manufacturers adopt configurable process workflows. |
| Yokohama Technical Center Establishment | Compresses 18-24 month qualification delays for foreign equipment vendors. |
| Stealth Dicing Technology Licensing | Positions for MEMS and sensor singulation applications eliminating thermal damage. |
| India OSAT Channel Partnership | Shapes qualification standards in PLI-scheme packaging clusters before competitor entrenchment. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with equipment procurement managers at Taiwan foundries, maintenance directors at South Korean memory houses, and aftermarket service heads at Japanese OSATs combined with METI subsidy disclosure documents, JIS certification registries, and semiconductor capex tracking databases. Bottom-up equipment shipment tallies triangulated against top-down fab capacity expansion announcements.
Segment-level granularity modeled equipment type, substrate thickness tier, end-user integration depth, and regional regulatory cluster across the analysis window. CAGRs derived from installed base depreciation schedules and replacement cycle compression trends. Forecast inputs incorporated AI chip foundry expansion pipelines, compound semiconductor volume trajectories, and stealth dicing adoption curves.
Caveats apply where dual-use export control expansions or raw material supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding subsidy program continuity and technician mobility protocols. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market