
 Global Photoresist Market | 2026-2036
Global Photoresist Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photoresist Market Foresight
Specialized photochemical engineering talent is collapsing across East Asian supply hubs, tightening formulation development cycles and extending qualification timelines for next-generation resists. JSR Corporation dominates ArF and EUV resist supply through captive polymer synthesis and direct fab partnerships. Tokyo Ohka Kogyo anchors legacy g-line and i-line production while sustaining margin pools in display photoresist segments. Shin-Etsu Chemical leverages vertical integration into silicon-containing monomers that differentiate its EUV platform.
Photoresist denotes a light-sensitive polymeric formulation engineered with photoacid generators, dissolution inhibitors, and base quenchers in solvent matrices, typically spin-coated at thicknesses between 30 nm and 500 nm depending on wavelength target; its primary function is to transfer circuit patterns onto semiconductor wafers, display glass, or PCB substrates through selective solubility changes induced by radiation exposure. Chemically amplified resist formulations lead value generation due to their catalytic deprotection mechanisms enabling sub-7 nm resolution. Extreme ultraviolet lithography represents the fastest-expanding technology segment as ASML scanner deployments multiply across leading-edge fabs. Nanoimprint resist occupies emerging positioning for photonics and memory applications where cost-sensitive patterning outweighs throughput constraints.
REACH registration requirements in Europe govern monomer imports and restrict certain fluorinated compounds used in 193 nm formulations, while Japan's METI enforces chemical substance reporting that shapes domestic formulation portfolios. South Korea's K-REACH amendments tighten disclosure thresholds for photoresist precursors, compelling suppliers to restructure supply chain documentation. Stakeholders must monitor regulatory divergence between EU fluoropolymer restrictions and East Asian fab subsidy programs when allocating R&D budgets across geographic markets.
Market Dynamics
Migration toward sub-3 nm semiconductor nodes is compressing photoresist formulation tolerances while concentrating qualified supplier pools in East Asian manufacturing clusters.
Growth Catalysts
- EUV Lithography Ramp:ASML scanner deployments at leading-edge foundries in Taiwan and South Korea are accelerating demand for metal oxide and chemically amplified EUV resists with sub-20 nm resolution.
- K-REACH Amendments:South Korea's tightened chemical disclosure thresholds for photoresist precursors are driving domestic formulation investments and local supply chain restructuring.
- Advanced Packaging:3D stacking and chiplet architectures are expanding addressable resist consumption per wafer through multiple patterning layers.
Market Restraints
- Monomer Supply Concentration:Specialty photoacid generator production clusters in Japan's Kansai region, creating single-source vulnerability for EUV resist manufacturers.
- Fluorinated Compound Restrictions:EU F-Gas Regulation and REACH Annex XVII limitations on perfluorinated substances are constraining 193 nm immersion resist formulation options.
- Qualification Timeline Compression:Leading-edge fab resist qualification cycles now extend 18-24 months, locking out new entrants from revenue capture during technology transitions.
Strategic Opportunities
- India Semiconductor Mission:Domestic fab construction incentives under India's PLI scheme are creating first-mover positioning for resist suppliers establishing local blending facilities.
- Nanoimprint Lithography:Photonics and memory applications where cost-sensitive patterning outweighs throughput constraints are opening specialty resist demand outside semiconductor mainstream.
- Display Photoresist Diversification:OLED and quantum dot display manufacturing expansion in Vietnam and Malaysia is extending resist consumption beyond wafer processing.
Industry Challenges
- Photochemical Engineering Talent Collapse:Specialized polymer synthesis expertise is thinning across East Asian supply hubs, extending development cycles for next-generation formulations.
- Multi-Site Regulatory Compliance:Divergent chemical substance reporting requirements between Japan's METI, South Korea's K-REACH, and EU REACH are fragmenting documentation systems and raising compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photoresist Market |
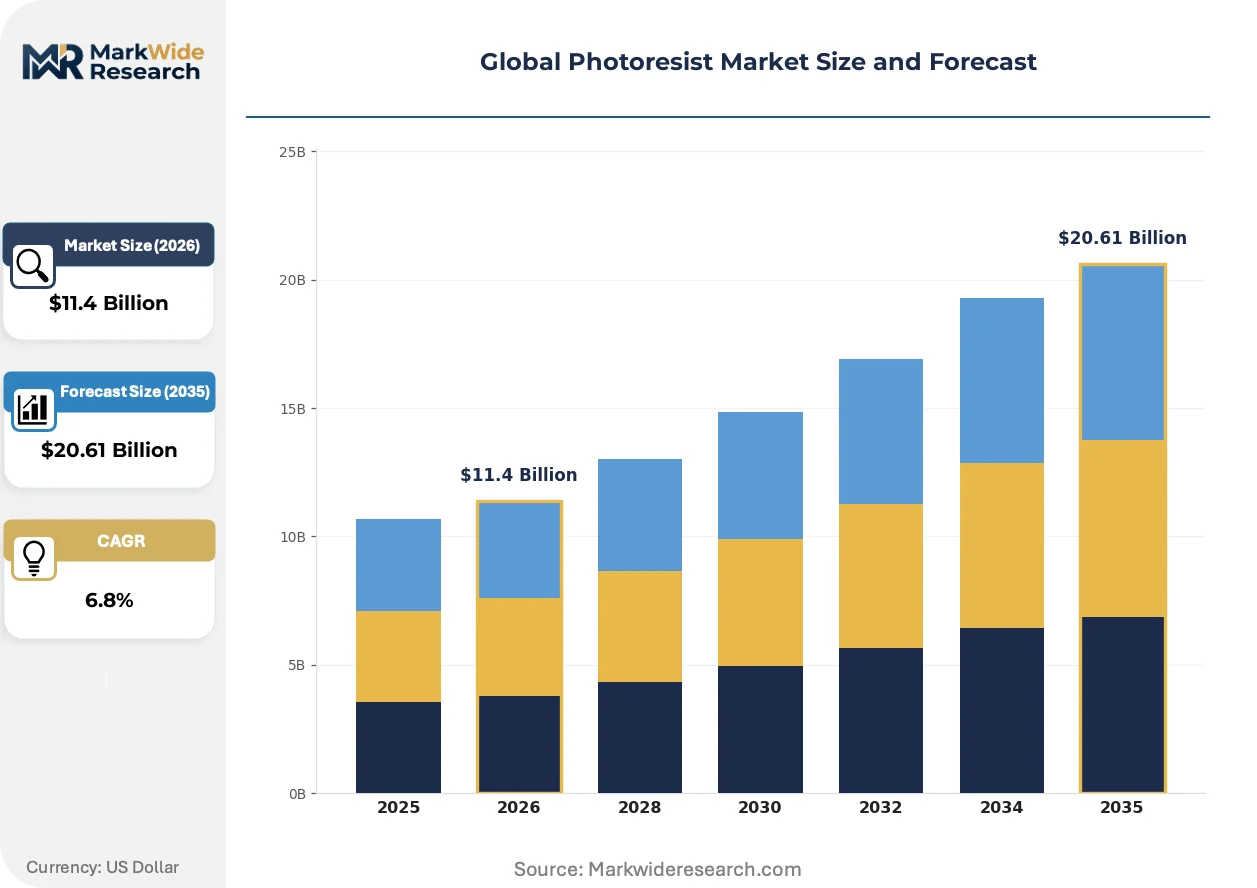
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Dry Film Photoresist, Chemically Amplified Resist, Nanoimprint Resist Application: Semiconductor Fabrication, Printed Circuit Boards, Flat Panel Displays, Photomask Production, MEMS Manufacturing Technology: Optical Lithography, Electron Beam Lithography, Extreme Ultraviolet Lithography, Ion Beam Lithography, Nanoimprint Lithography End User: Chip Manufacturers, Printed Circuit Board Makers, Display Panel Producers, MEMS Developers, Research Laboratories |
| Companies Covered | JSR Corporation, Tokyo Ohka Kogyo Co., Ltd., Shin-Etsu Chemical Co., Ltd., FUJIFILM Corporation, DuPont, Sumitomo Chemical Co., Ltd., Merck Group, Dow Chemical Company, Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photoresist Market Shifts & Advancements
Material science breakthroughs and regulatory recalibration are simultaneously expanding performance boundaries and reshaping competitive entry conditions across photoresist supply chains.
Metal oxide resist formulations incorporating tin-oxo clusters are miniaturizing patterning resolution below 13 nm half-pitch for 2 nm logic node production. Foundry customers in Taiwan and South Korea are qualifying these platforms ahead of 2026 high-volume manufacturing ramps. The technology is miniaturizing feature sizes while displacing traditional polymer-based chemically amplified resists in critical EUV layers.
EU F-Gas Regulation amendments targeting per- and polyfluoroalkyl substances are restricting fluorinated dissolution inhibitors used in 193 nm immersion lithography. Formulation houses are accelerating alternative quencher development to maintain dissolution contrast without restricted chemistries. European resist importers face the most acute compliance pressure, with several reformulating portfolios ahead of 2025 enforcement deadlines.
Direct fab partnerships are displacing traditional distributor-mediated procurement for EUV resist supply. Leading foundries in Taiwan now negotiate multi-year formulation development agreements with captive synthesis commitments. This pattern is most pronounced where scanner utilization rates exceed 90% and resist lot-to-lot consistency carries direct yield implications.
Global Photoresist Market Segmentation
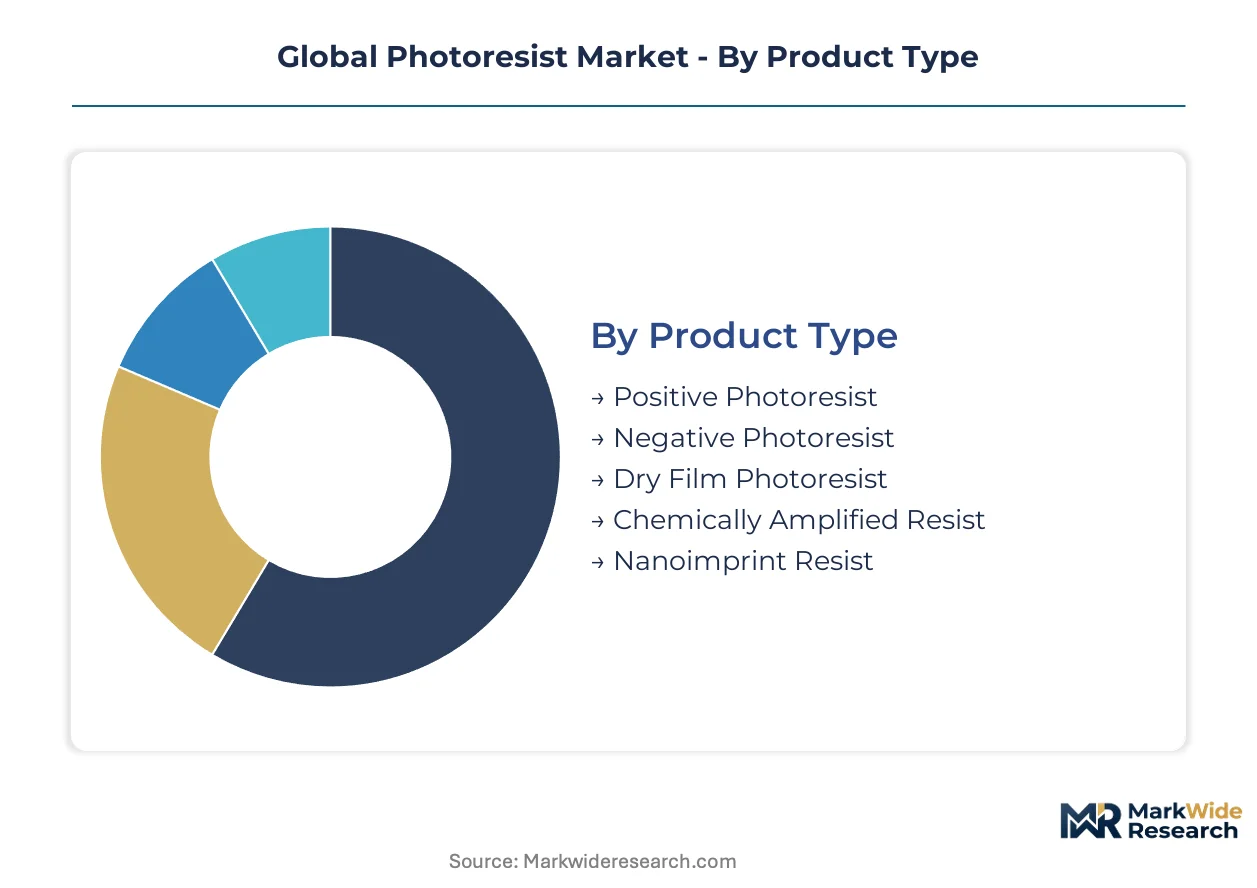
Photoresist segmentation reflects divergent channel economics across semiconductor, display, and PCB supply chains. Each dimension—product chemistry, application target, lithography wavelength, and end-user procurement power—shapes margin capture and qualification barriers differently.
Product Type:
Channel mix varies sharply: foundries procure chemically amplified and EUV resists through direct multi-year agreements, while PCB fabricators source dry film through distributor networks.
- Chemically Amplified Resist:Photoacid generator-catalyzed deprotection mechanisms enable sub-7 nm resolution in advanced logic production. Taiwan and South Korea foundries concentrate demand as ASML scanner deployments multiply.
- Positive Photoresist:Dominates wafer-level patterning through radiation-induced solubility enhancement in exposed regions. Semiconductor fabrication lines in Hsinchu and Pyeongtaek drive volume procurement.
- Negative Photoresist:Crosslinking chemistry suits thick-film MEMS and packaging applications where etch resistance outweighs resolution.
- Dry Film Photoresist:Laminate format eliminates solvent coating equipment for PCB manufacturers in Shenzhen and Osaka.
- Nanoimprint Resist:Low-temperature curing attracts photonics and memory applications where cost-sensitive patterning tolerates throughput tradeoffs.
Positive photoresist dominates installed base. Chemically amplified resist is where expansion concentrates.
Application:
Cost tier segmentation separates premium semiconductor formulations from commodity display and PCB grades.
- Semiconductor Fabrication:Multi-patterning EUV and ArF immersion layers consume the highest-value resist per wafer. Leading-edge foundries in Taiwan and South Korea qualify suppliers through 18-24 month cycles.
- Flat Panel Displays:Large-area coating requirements favor high-throughput spin or slit-die systems. OLED and quantum dot manufacturing expansion in Vietnam and Malaysia extends demand.
- Printed Circuit Boards:Dry film and liquid resists pattern copper traces through subtractive etch processes. Volume procurement concentrates in Chinese and Japanese fabricators.
- Photomask Production:Electron-beam and laser writers demand high-contrast resists for reticle patterning with sub-nanometer edge placement.
- MEMS Manufacturing:Thick-film negative resists withstand deep silicon etching for sensors and actuators.
Semiconductor fabrication commands premium pricing. Display panel production is climbing the fastest.
Technology:
Volume distribution tracks scanner installed base: optical lithography retains broadest deployment while EUV captures newest capacity additions.
- Extreme Ultraviolet Lithography:13.5 nm wavelength enables single-exposure patterning at 3 nm nodes. Metal oxide and chemically amplified formulations from JSR and Tokyo Ohka Kogyo lead qualification.
- Optical Lithography:193 nm ArF and 248 nm KrF systems continue serving mature nodes and memory layers. Fluorinated dissolution inhibitors face EU F-Gas Regulation constraints.
- Electron Beam Lithography:Maskless patterning suits low-volume prototyping and photomask production without optical proximity correction overhead.
- Ion Beam Lithography:Direct-write systems serve niche research and specialty device applications.
- Nanoimprint Lithography:Mechanical patterning displaces optical systems where cost-per-device matters more than throughput.
Optical lithography dominates installed base. Extreme ultraviolet lithography is where expansion concentrates.
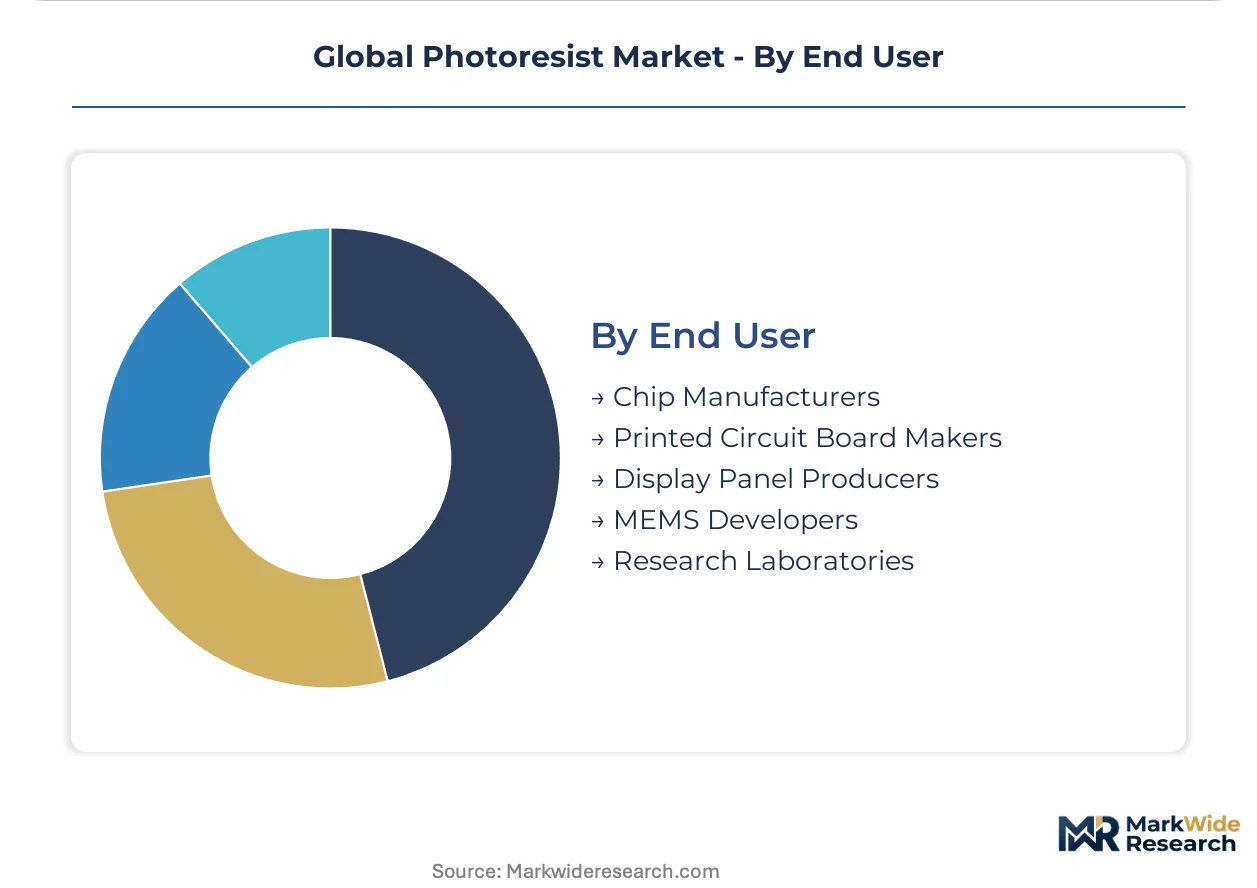
End User:
Customer type determines procurement leverage: integrated foundries negotiate captive supply agreements while research laboratories purchase through specialized distributors.
- Chip Manufacturers:TSMC, Samsung, and Intel foundries specify resist lots with sub-1% critical dimension variation. Direct fab partnerships displace distributor relationships for EUV supply.
- Display Panel Producers:Samsung Display and BOE procure large-area resists through regional blending facilities.
- Printed Circuit Board Makers:Volume fabricators in Taiwan and China source dry film through trading houses with monthly contract pricing.
- MEMS Developers:Bosch and STMicroelectronics qualify thick-film resists for accelerometer and gyroscope production.
- Research Laboratories:imec and academic consortia pilot next-generation formulations ahead of commercial foundry adoption.
Chip manufacturers dominate installed base. Display panel producers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and Taiwan consume photoresist almost exclusively for leading-edge semiconductor fabrication, while Japan and the United States maintain broader portfolios spanning display, PCB, and legacy semiconductor applications. This consumption-mix differential shapes supplier qualification priorities and regulatory compliance investments across manufacturing clusters.
South Korea
Samsung Electronics and SK Hynix drive EUV resist consumption for 3 nm logic and advanced DRAM production. K-REACH amendments tightened chemical disclosure thresholds for photoresist precursors, compelling domestic formulation investments. The Pyeongtaek semiconductor cluster hosts multiple ASML EUV scanner installations with dedicated resist supply agreements.
Taiwan
TSMC's foundry operations anchor global demand for chemically amplified and metal oxide EUV resists at sub-5 nm nodes. The island's environmental regulator enforces hazardous substance reporting that shapes formulation documentation requirements. Hsinchu Science Park concentrates resist qualification laboratories and direct fab partnership negotiations.
Japan
Domestic display panel production and legacy semiconductor nodes sustain diversified resist demand across wavelengths. METI chemical substance reporting requirements govern domestic formulation portfolios and import documentation. The Kansai region clusters specialty photoacid generator production, creating critical supply chain nodes for EUV resist manufacturers.
United States
Intel's domestic foundry expansion and defense-related semiconductor production drive demand for advanced ArF and EUV formulations. EPA oversight of fluorinated compound emissions influences 193 nm immersion resist formulation choices. Arizona and Oregon semiconductor manufacturing corridors attract resist suppliers establishing regional blending capabilities.
China
Domestic memory and mature-node logic fabrication expand resist consumption despite import substitution pressures. MIIT industrial standards and GB chemical regulations govern local formulation licensing and environmental compliance. The Yangtze River Delta and Beijing-Tianjin-Hebei corridors concentrate display and semiconductor manufacturing requiring large-area and wafer-level resists.
Global Photoresist Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding direct fab partnerships and captive polymer synthesis capabilities. The middle layer comprises regional formulators and application-specific suppliers serving display and PCB segments. Strategic archetypes include vertically integrated chemical conglomerates, lithography-focused specialists, and diversified materials platforms. Competitive moves center on multi-year supply agreements with leading foundries and backward integration into photoacid generator production.
Within the integrated chemical conglomerate tier, JSR Corporation and Shin-Etsu Chemical exemplify players with upstream control over monomer and polymer synthesis. Tokyo Ohka Kogyo occupies a position among lithography-focused specialists with historical strength in legacy wavelength formulations. These three Japanese entities anchor the premium-tier supply structure for advanced semiconductor applications.
| Leading Market Players |
|---|
| JSR Corporation |
| Tokyo Ohka Kogyo Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| FUJIFILM Corporation |
| DuPont |
| Sumitomo Chemical Co., Ltd. |
| Merck Group |
| Dow Chemical Company |
| Mitsui Chemicals, Inc. |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month qualification cycles for EUV resists compress inventory flexibility and amplify pricing power for qualified suppliers serving TSMC and Samsung foundries. This lead-time rigidity concentrates procurement leverage among Japanese formulators with captive polymer synthesis while locking out price competition from unqualified entrants.
Pricing Analysis
Long-term offtake agreements dominate EUV resist procurement, with foundries negotiating multi-year formulation development contracts that embed volume commitments and technical service bundles. Pricing stratifies across premium, standard, and economy tiers based on resolution performance and fab qualification status, with metal oxide EUV formulations commanding the highest premiums. Cost compression in mature-node ArF resists is intensifying because Chinese memory fabricators are expanding captive blending capacity. Display panel producers in Vietnam and Malaysia exhibit the greatest price sensitivity, while leading-edge logic foundries prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Japan and South Korea anchor specialty chemical production for photoresist precursors, with the Kansai region clustering photoacid generator synthesis and Pyeongtaek hosting EUV resist blending facilities. Raw material dependencies center on fluorinated monomers, tin-oxo clusters for metal oxide platforms, and high-purity solvents. Single-source vulnerability pervades EUV photoacid generator supply, where two Japanese producers control critical chemistries. Distribution runs through direct fab partnerships for semiconductor-grade resists and regional distributors for PCB dry film.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal oxide resist qualification for sub-2 nm nodes represents a high-growth disruption as foundries displace traditional polymer platforms. EU F-Gas Regulation amendments on fluorinated compounds compound this inflection by forcing 193 nm formulation restructuring.
For Market Incumbents: Fortify captive synthesis positions by backward integrating into tin-oxo cluster production and expanding Hokkaido-based polymer facilities. Lock in multi-year development agreements with TSMC and Samsung before metal oxide platforms commoditize. Defend margin pools by accelerating alternative quencher R&D ahead of 2025 EU enforcement deadlines.
For New Entrants and Emerging Players: Differentiate on nanoimprint resist specialization for photonics applications where throughput constraints matter less than patterning cost. Target India's domestic fab construction under PLI incentives for first-mover blending facility positioning. Pursue joint development agreements with memory producers seeking second-source EUV qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because qualification barriers and regulatory compliance overhead favor scaled specialists with direct fab relationships. Acquisition targets should display backward integration into photoacid generators or metal oxide precursor synthesis. Watch ASML scanner deployment announcements at greenfield fabs as the signal for resist demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoacid Generators | Captive PAG production insulates EUV resist supply from Kansai-region concentration risk. |
| Metal Oxide Resist Platform Qualification | Sub-13 nm resolution capability opens 2 nm logic node revenue at TSMC and Samsung. |
| India Blending Facility Establishment | PLI scheme subsidies reduce tariff exposure for semiconductor-grade resist imports. |
| Alternative Quencher Formulation Development | EU F-Gas compliance maintains 193 nm immersion resist market access without restricted fluorinated chemistries. |
| Direct Fab Partnership Structuring | Multi-year agreements with foundries displace distributor relationships and lock in volume commitments. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with photoresist R&D directors, foundry procurement managers, lithography equipment specialists, and regulatory compliance officers; and secondary validation through customs trade data, METI chemical substance filings, ECHA REACH registrations, and SEC disclosures from listed chemical conglomerates. Bottom-up triangulation across formulation volumes by wavelength and top-down cross-check against fab capex announcements anchored demand estimates.
Across the analysis window, the forecasting framework modeled photoresist consumption by product chemistry, application target, lithography technology, and end-user procurement power. CAGRs derived from scanner deployment pipelines, node migration timelines, and multi-patterning intensity assumptions. Metal oxide resist adoption curves and K-REACH compliance cost pass-through shaped regional growth differentials.
The analysis sits within stated boundaries; outcomes outside sustained EUV scanner utilization rates, stable fluorinated compound regulatory frameworks, or uninterrupted specialty monomer trade flows would require recalibration. Forecasts reflect assumptions about foundry yield ramp schedules and display panel capacity expansion. Recalibration cycles align with material shifts in ASML delivery schedules, EU F-Gas enforcement actions, or India fab construction milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market