
 Global Wafer Cleaning Equipment Market | 2026-2036
Global Wafer Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wafer Cleaning Equipment Market Intelligence
A scarcity of process engineers with expertise in advanced plasma and cryogenic cleaning techniques is redrawing the competitive landscape for equipment suppliers. Lam Research Corporation leverages its deep R&D in single-wafer wet clean technologies to address this skills gap. Tokyo Electron Limited dominates the batch processing segment with highly automated systems that reduce operator dependency. SCREEN Holdings Co., Ltd. specializes in single-wafer cleaning solutions tailored for next-generation logic and memory devices.
Wafer cleaning equipment comprises automated systems designed to remove particulate, metallic, and organic contaminants from silicon wafer surfaces, achieving purity levels critical for device yield by targeting particles smaller than 10 nanometers. These systems prepare wafer surfaces for subsequent deposition, etching, or lithography steps without introducing defects. Wet cleaning systems continue to hold the largest market share due to their established role in volume production. However, dry cleaning systems, including plasma-based tools, represent the fastest-growing product type, driven by the needs of advanced semiconductor fabrication.
Regulations such as the EU's REACH directive and the US EPA's rules on solvent disposal govern the chemical formulations used in wet cleaning processes. Concurrently, ISO 14644 standards for cleanroom environments impose strict contamination control requirements on equipment design and operation. Equipment vendors must therefore balance higher cleaning performance with the development of more sustainable, less hazardous chemical and energy consumption models.
Market Dynamics
The imperative to fabricate increasingly complex 3D semiconductor architectures, such as gate-all-around (GAA) transistors and vertically stacked memory, is the central force shaping the market. This transition fundamentally increases the number and criticality of wafer cleaning steps required per device.
Growth Catalysts
- Advanced Transistor Architectures:The shift to sub-3nm nodes and GAA structures multiplies the number of cleaning and surface preparation steps, demanding more precise and efficient equipment to maintain high yields.
- Government Semiconductor Initiatives:National policies, including the US CHIPS Act and the European Chips Act, are stimulating unprecedented investment in new foundry construction in North America and Europe, directly driving equipment orders.
- AI and HPC Expansion:The proliferation of artificial intelligence and high-performance computing applications requires a massive supply of advanced logic and memory chips, which in turn necessitates more sophisticated wafer cleaning capabilities.
Market Restraints
- High Capital Expenditure:The significant cost of advanced single-wafer cleaning systems, particularly those using cryogenic or advanced plasma technologies, presents a substantial investment barrier for new entrants or smaller-scale fabs.
- Process Chemistry Limitations:Developing wet chemical formulations that can effectively remove nanoscale contaminants without damaging novel, sensitive materials used in next-generation devices remains a significant technical hurdle.
- Environmental Regulations:Strict controls on chemical usage and disposal, such as the EU's REACH framework governing industrial chemicals, increase the operational costs and complexity of wet cleaning processes.
Strategic Opportunities
- Sustainable Cleaning Technologies:There is a significant opportunity for systems using green chemistries, recycled solvents, or water-free vapor and plasma methods that reduce environmental impact and lower operational costs.
- Emerging Semiconductor Hubs:New fabrication projects in geographies like India, supported by government incentives such as the PLI scheme, represent an untapped market for new equipment installations.
- Compound Semiconductor Cleaning:Developing specialized cleaning processes tailored for silicon carbide (SiC) and gallium nitride (GaN) wafers addresses a growing need in the power electronics and automotive sectors.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of process engineers and technicians with expertise in advanced plasma physics and cryogenic systems hinders the adoption and optimization of next-generation cleaning tools.
- Tool Integration Complexity:Integrating new, sophisticated single-wafer cleaning modules into highly automated, legacy 200mm and 300mm fab lines without disrupting established workflows presents a major operational challenge.
- Component Lead Times:Extended lead times for critical sub-components, such as high-purity quartz chambers and specialized RF generators, can delay equipment delivery and fab ramp-up schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wafer Cleaning Equipment Market |
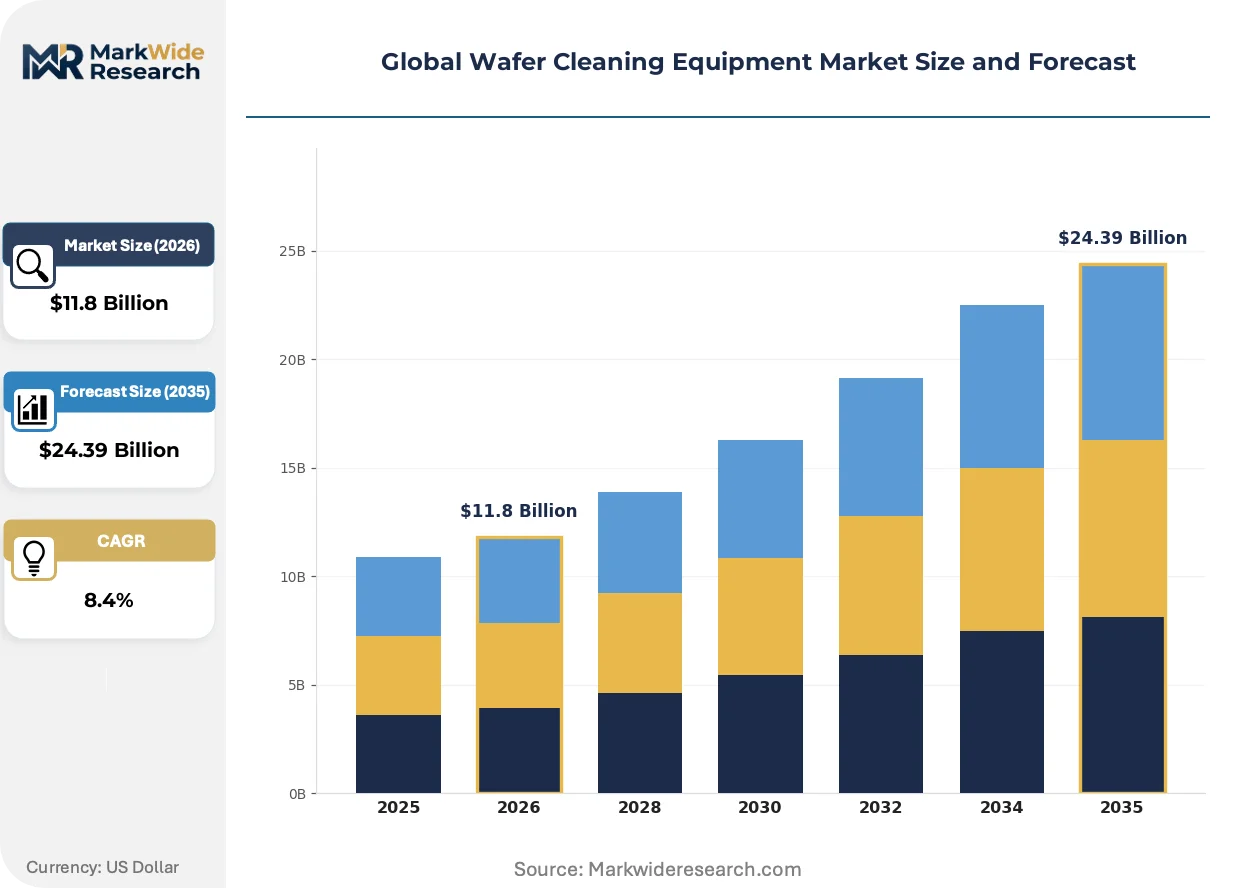
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Cleaning Systems, Dry Cleaning Systems, Ultrasonic Cleaning Equipment, Plasma Cleaning Machines Technology: Chemical Mechanical Planarization, Megasonic, Cryogenic, Spin-Rinse-Dry Application: Semiconductor Fabrication, MEMS Manufacturing, Photovoltaic Cells, LED Production End User: Foundries, Fabless Companies, Integrated Device Manufacturers, Equipment Suppliers |
| Companies Covered | Applied Materials, Inc., Modutek Corporation, SCREEN Holdings Co., Ltd., Veeco Instruments Inc., Entegris, Inc., Tokyo Electron Limited, Shibaura Mechatronics Corporation, ACM Research, Inc., Lam Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wafer Cleaning Equipment Market Strategic Shifts & Innovations
The market's innovation axis is pivoting from a singular focus on contaminant removal to a more nuanced approach of atomic-level surface conditioning. This shift prioritizes preparing pristine, precisely engineered surfaces for subsequent atomic layer deposition and etching steps in advanced manufacturing.
Cryogenic aerosol cleaning uses energized, frozen particles of argon or carbon dioxide to perform non-damaging, physical removal of contaminants. Leading-edge logic and memory fabs are adopting this technique for critical applications like cleaning EUV photomasks and delicate 3D device structures. This targeted, water-free method is decomposing the industry's historical dependence on aggressive wet chemical baths that risk etching or altering fragile device features.
The US EPA’s regulatory actions targeting per- and polyfluoroalkyl substances (PFAS) are compelling a re-evaluation of many traditional wet cleaning surfactants. This pressure accelerates research into fluorine-free chemical alternatives and drives greater adoption of dry cleaning methods like vapor-phase and plasma treatments. Consequently, equipment suppliers are heavily invested in validating new, compliant process chemistries that do not compromise cleaning performance.
Foundries are increasingly procuring integrated, multi-chamber cleaning platforms rather than standalone tools from various vendors. This model, which combines different cleaning technologies into a single, pre-qualified system, disrupts the market for single-process equipment specialists. The trend is most visible in the advanced foundry ecosystems of Taiwan and South Korea, where minimizing tool-to-tool variability and accelerating process qualification are paramount competitive advantages.
Global Wafer Cleaning Equipment Market Segmentation
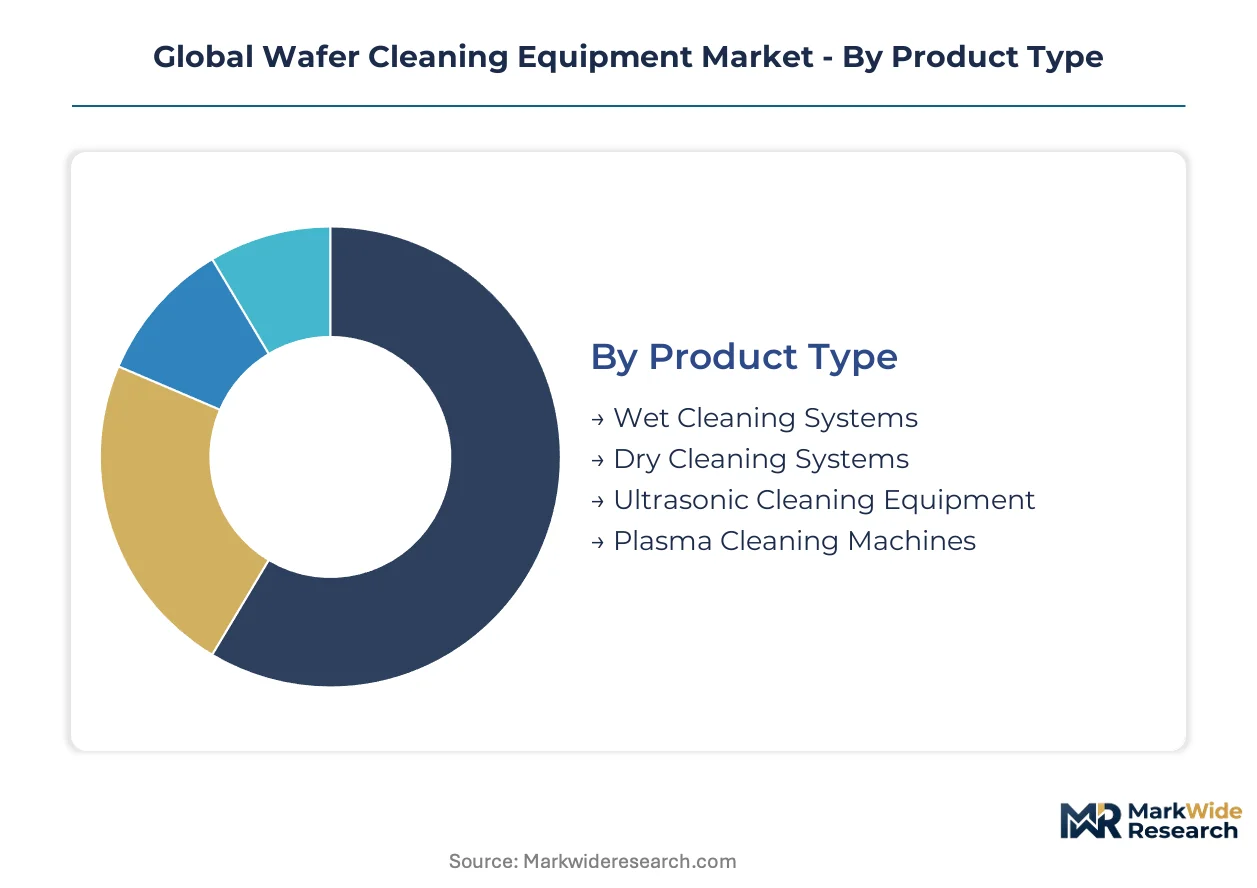
Market segmentation identifies distinct customer groups and product characteristics, providing a granular view of demand drivers and competitive dynamics within the global wafer cleaning equipment sector. Analyzing these segments helps equipment manufacturers tailor their R&D investments and market strategies, aligning product development with specific technological needs and operational requirements across diverse semiconductor fabrication environments.
Product Type:
The geographic spread of product types reveals that established wet cleaning systems maintain dominance in mature fabrication hubs, while dry cleaning solutions gain traction in regions pushing advanced node development.
- Wet Cleaning Systems:These systems utilize chemical solutions and deionized water to remove contaminants from wafer surfaces, remaining foundational for high-volume production lines globally. Their established efficacy and cost-effectiveness ensure continued deployment in foundries across Taiwan and South Korea.
- Dry Cleaning Systems:Employing plasma, vapor-phase, or cryogenic techniques, these systems offer precise, residue-free cleaning for delicate structures, particularly crucial for sub-3nm nodes. Demand for dry cleaning solutions is accelerating in cutting-edge fabs in the United States and Japan, driven by advanced logic and memory manufacturing.
- Ultrasonic Cleaning Equipment:This equipment uses high-frequency sound waves in a liquid medium to dislodge particles from wafer surfaces, providing an effective method for bulk cleaning applications. Manufacturers in China and Europe integrate these systems for cost-efficient contaminant removal in less critical steps.
- Plasma Cleaning Machines:Plasma cleaning utilizes reactive gases to remove organic contaminants and residues, offering a non-contact method for surface preparation. This technology finds specialized use in advanced packaging and MEMS fabrication facilities.
Wet Cleaning Systems commands the established base. The steepest expansion runs through Dry Cleaning Systems.
Technology:
Cost tiering dictates technology adoption, with advanced techniques commanding higher investment for critical process steps, while more mature methods provide economical solutions for less sensitive applications.
- Cryogenic:This advanced technology employs frozen gas particles (e.g., CO2 snow) for non-damaging physical removal of nanoscale contaminants, essential for EUV mask cleaning and delicate 3D structures. High-performance computing applications in North America and East Asia drive adoption of these premium systems.
- Spin-Rinse-Dry:A widely adopted and cost-effective technique that cleans wafers using chemical sprays and deionized water, followed by rapid spinning to dry the surface. This technology forms the backbone of volume manufacturing in established fabs worldwide due to its proven reliability.
- Chemical Mechanical Planarization:While primarily a planarization technique, CMP processes often integrate cleaning steps to remove slurry particles and chemical residues, ensuring surface uniformity. This technology is critical for multi-layer device fabrication in advanced semiconductor foundries.
- Megasonic:Megasonic cleaning uses high-frequency sound waves in a liquid bath to dislodge sub-micron particles from wafer surfaces without causing damage. This method is common in pre-deposition and post-etch cleaning steps across various fabrication facilities.
Spin-Rinse-Dry technology maintains a substantial installed base. Cryogenic technology is gaining significant traction for next-generation applications.
Application:
Application diversity reflects varying volume needs, with semiconductor fabrication driving the largest demand, while specialized sectors require tailored cleaning solutions for unique material properties.
- Semiconductor Fabrication:This segment represents the largest application area, encompassing all cleaning steps required for manufacturing integrated circuits, including logic, memory, and analog devices. The continuous push for smaller nodes and 3D architectures in Taiwan and South Korea fuels immense demand.
- MEMS Manufacturing:Micro-electro-mechanical systems (MEMS) production requires precise cleaning to prevent contamination of delicate micro-structures and ensure device functionality. Specialized cleaning processes are crucial for sensors and actuators used in automotive and consumer electronics.
- Photovoltaic Cells:Cleaning equipment is essential for removing impurities from silicon wafers used in solar cell manufacturing, ensuring optimal energy conversion efficiency. This application focuses on high-throughput, cost-effective solutions for large-scale production.
- LED Production:Light-emitting diode (LED) manufacturing necessitates stringent cleaning of sapphire or silicon carbide substrates to achieve high luminescence and device reliability. Contaminant removal is vital for epitaxial growth and subsequent processing steps.
Semiconductor Fabrication holds the largest market share. MEMS Manufacturing exhibits strong growth potential.
End User:
Customer type influences purchasing patterns, with large foundries prioritizing integrated, high-throughput solutions, while equipment suppliers focus on developing specialized tools for their clients.
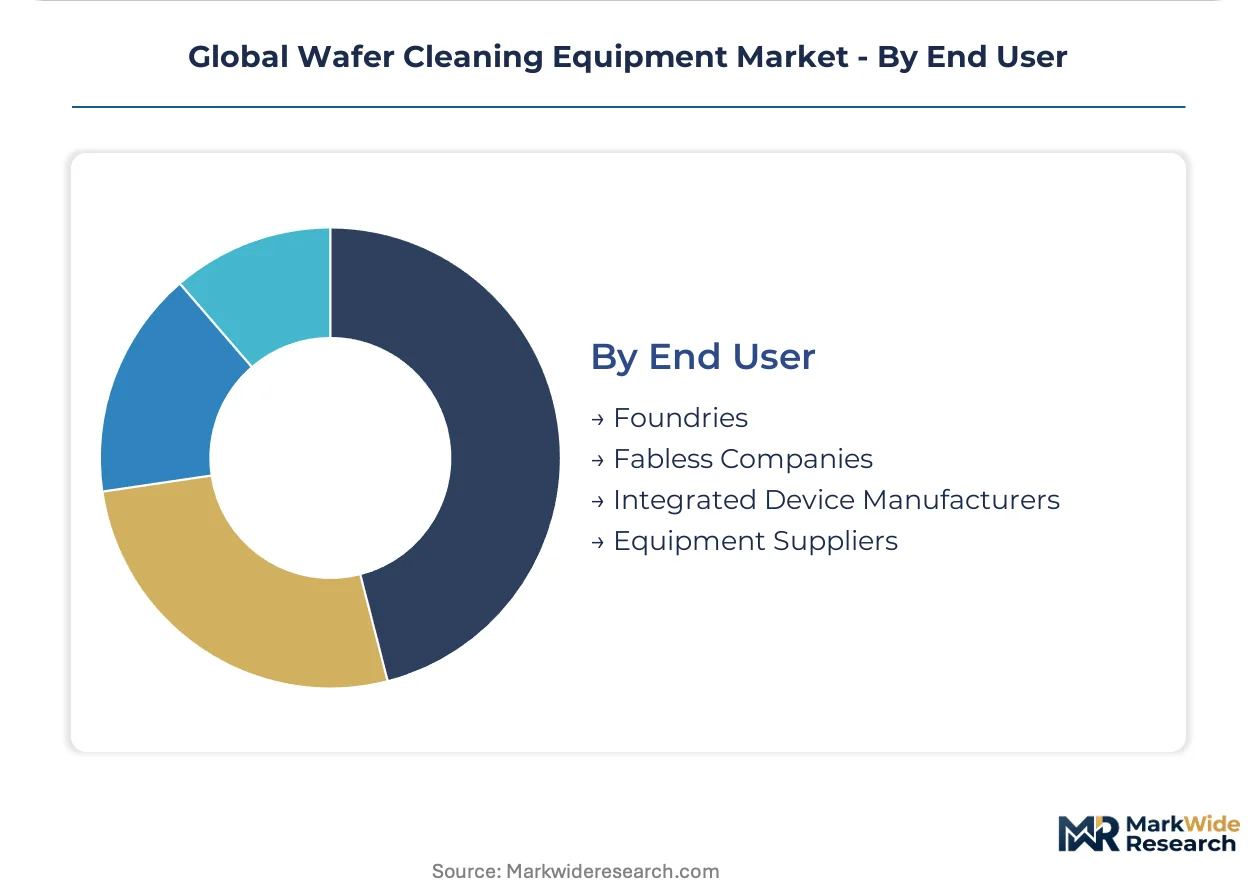
- Foundries:These independent manufacturers produce chips for fabless companies, demanding high-volume, highly automated, and precise wafer cleaning systems to maximize yield. Major foundries in Taiwan and the United States are significant investors in advanced cleaning technologies.
- Integrated Device Manufacturers:IDMs design, manufacture, and sell their own chips, requiring comprehensive cleaning solutions across their vertically integrated operations. Companies such as Intel and Samsung invest heavily in internal wafer cleaning capabilities.
- Equipment Suppliers:These entities develop and provide the actual wafer cleaning tools to foundries and IDMs, focusing on innovation and performance to meet evolving industry demands. Their R&D efforts shape the next generation of cleaning technologies.
- Fabless Companies:While not directly purchasing cleaning equipment, fabless companies indirectly drive demand through their orders with foundries, influencing the types of advanced cleaning capabilities required. Qualcomm and NVIDIA rely on foundries with cutting-edge cleaning processes.
Foundries represent the primary end-user segment. Equipment Suppliers are critical for driving technological advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced wafer cleaning equipment concentrates in regions driving next-generation semiconductor fabrication. This creates a distinct asymmetry, with cutting-edge technologies commanding higher investment in North America and East Asia. Conversely, cost-efficient solutions remain central to volume manufacturing in other established fabrication hubs.
United States
United States demand for wafer cleaning equipment stems from advanced logic and memory manufacturing. The US CHIPS Act provides significant incentives for domestic fab expansion. New fabrication facilities in Arizona and New York are rapidly adopting dry cleaning solutions for next-generation devices.
Taiwan
Taiwan's semiconductor fabrication industry drives immense demand, pushing for sub-3nm nodes and complex 3D architectures. The island's industrial policies prioritize maintaining its global foundry leadership. Hsinchu Science Park foundries are significant investors in high-volume wet cleaning systems and advanced multi-chamber platforms.
South Korea
South Korea's robust memory and logic production fuels substantial demand for wafer cleaning equipment. The national semiconductor strategy encourages investment in cutting-edge fabrication capabilities. Major IDMs in Gyeonggi Province are integrating sophisticated cleaning modules for their vertically stacked memory and GAA transistor production.
Japan
Japanese advanced logic and memory manufacturing requires precise cleaning for delicate structures. Japan's METI initiatives aim to strengthen the domestic semiconductor supply chain. Fabs in Kyushu are increasingly deploying dry cleaning solutions, including plasma and cryogenic systems, for their cutting-edge production lines.
India
India's emerging semiconductor ecosystem is generating new demand for wafer cleaning equipment. The national PLI scheme incentivizes new fabrication projects across the country. Proposed fabs in Gujarat and Uttar Pradesh will require comprehensive cleaning solutions for their planned semiconductor production.
Global Wafer Cleaning Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the wafer cleaning equipment market. The market exhibits a tiered structure, with a few dominant players offering advanced, high-capital solutions alongside specialized niche providers. Key strategic archetypes include integrated system providers, single-process technology specialists, and regional cost-efficient suppliers. Dominant competitive moves involve significant R&D investment in advanced cleaning techniques and strategic partnerships to integrate multi-chamber platforms.
Within the advanced equipment provider archetype, Lam Research Corporation exemplifies expertise in single-wafer wet clean technologies. Tokyo Electron Limited occupies a strong position in the batch processing segment with highly automated systems. SCREEN Holdings Co., Ltd. represents a specialist in single-wafer cleaning solutions tailored for next-generation logic and memory devices. These companies anchor the market for high-performance cleaning tools, particularly in regions pushing sub-3nm node development. Their offerings cater to the intricate demands of modern semiconductor fabrication, balancing performance with operational efficiency.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Modutek Corporation |
| SCREEN Holdings Co., Ltd. |
| Veeco Instruments Inc. |
| Entegris, Inc. |
| Tokyo Electron Limited |
| Shibaura Mechatronics Corporation |
| ACM Research, Inc. |
| Lam Research Corporation |
| Others |
Cost & Logistics Intelligence
Large-scale fabrication facility investments, driven by national semiconductor initiatives, shape both supply concentration and price floors for advanced wafer cleaning equipment. These capital-intensive projects necessitate long-term equipment contracts, influencing vendor pricing strategies and market entry barriers.
Pricing Analysis
Configured-to-order pricing for advanced single-wafer systems contrasts sharply with standard pricing for established wet cleaning solutions. Price differentiation stems from the level of customization required for sub-3nm nodes and the extensive after-sales service packages. Pricing softness reflects intense competition in the batch processing segment for mature nodes. Foundries focused on leading-edge technology exhibit lower price sensitivity, prioritizing performance and yield, while smaller fabs are more cost-sensitive.
Supply Chain Analysis
Extended component lead times for critical sub-components present a significant challenge for equipment manufacturers. Geographic supply concentration for specialized parts centers on Japan, the United States, and South Korea. Raw material dependencies include high-purity quartz for chambers and specialized RF generators for plasma systems. Single-source vulnerability for these highly specialized components poses a structural risk to equipment delivery schedules. Distribution runs primarily through direct sales channels to major foundries and integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as cryogenic aerosol cleaning and green chemistries threaten to displace traditional aggressive wet chemical baths.
For Market Incumbents: Secure long-term R&D partnerships with leading foundries to co-develop next-generation cleaning solutions. This mitigates the threat from emerging dry cleaning technologies and ensures early integration into new process flows. Invest in expanding internal manufacturing capacity for critical components, reducing reliance on external suppliers for specialized parts.
For New Entrants and Emerging Players: Anchor in niche applications within advanced packaging or MEMS manufacturing, which require specialized, lower-volume cleaning solutions. Target regions like India, where government incentives support new fab construction and offer a less saturated entry point. A strong go-to-market angle involves offering integrated, multi-chamber platforms that simplify tool integration for new facilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized equipment providers with deep expertise in dry cleaning or sustainable chemistry. Long-term viability hinges on companies capable of delivering atomic-level surface conditioning for future 3D architectures. The signal to watch is the increasing share of dry cleaning systems in new fab capital expenditure budgets.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Gains proprietary intellectual property in advanced plasma or cryogenic cleaning techniques. |
| Platform Integration | Combines diverse cleaning technologies into a single system, reducing fab complexity. |
| R&D in Green Chemistries | Addresses environmental regulations and reduces operational costs for foundries. |
| Geographic Expansion to Emerging Hubs | Captures new equipment orders from national semiconductor initiatives in India. |
| Long-term Supply Agreement | Secures critical components like high-purity quartz, mitigating lead time risks. |
Research Approach
A spread of perspectives from R&D directors, process engineers, fab procurement managers, and semiconductor industry analysts converged on the working assumptions for this study. This involved comprehensive primary interviews combined with rigorous secondary validation. Secondary data sources included government semiconductor policy documents, patent filings related to cleaning technologies, and corporate financial disclosures of leading equipment vendors. Triangulation across bottom-up market sizing and top-down industry trends ensured data consistency.
The segmentation dimensions modeled included Product Type, Technology, Application, End User, Geography, and wafer size. This analytical framework allowed for a granular assessment of market dynamics across the analysis window. Compound Annual Growth Rates were derived from historical growth patterns and projected future demand, influenced by global semiconductor capital expenditure and the increasing demand for AI and HPC chips.
Decision-makers should treat outputs as directional under current macroeconomic and technological assumptions; material deviation would warrant model refresh. Key risk factors include geopolitical shifts affecting global supply chains and unforeseen rapid advancements in alternative cleaning methods. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Europe Chip Mounter Market