
 Semiconductor Wafer Market | 2026-2036
Semiconductor Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wafer Market Outlook
The divergence between premium and commodity tiers is shifting as 300 mm epitaxial wafers for advanced logic command pricing multiples above 200 mm polished wafers for power discretes. Shin-Etsu Chemical leverages captive polysilicon refining to anchor cost leadership across silicon crystal growth. SUMCO Corporation specializes in defect-engineered substrates for DRAM and 3D NAND memory stacks. GlobalWafers competes through geographic diversification across Japan, Taiwan, and European fabs.
A semiconductor wafer is a thin, circular slice of crystalline semiconductor material—typically silicon with purity exceeding 99.9999999%—fabricated through Czochralski crystal pulling or float-zone refining, then lapped, polished, and cleaned to atomic-scale flatness for subsequent photolithographic patterning of integrated circuits. Silicon wafers dominate volume as the substrate backbone for logic and memory chips, while SOI wafers command premium positioning in RF and low-power applications where buried oxide layers eliminate substrate leakage. The 300 mm diameter segment leads value generation as foundries migrate capital toward single-wafer processing economies, though 200 mm supply tightens for automotive MCU and power device demand.
Japan's METI coordinates national silicon supply security through subsidies under the Semiconductor and Digital Industry Strategy, while the EU's Chips Act and F-Gas Regulation jointly constrain fluorinated greenhouse gas emissions from wafer etching processes. China's GB standards and MIIT dual carbon goals enforce energy intensity caps on polysilicon smelters, reshaping cost structures for domestic wafer producers. Stakeholders must monitor whether US CHIPS Act domestic content requirements fragment equipment procurement pools across allied fabs.
Market Dynamics
EUV lithography migration below 3 nm is compressing wafer qualification cycles while concentrating procurement among foundries with captive crystal growth capabilities.
Growth Catalysts
- Automotive MCU demand:Power discrete manufacturers are absorbing 200 mm polished wafer supply for traction inverters and battery management systems.
- Japan's METI subsidies:The Semiconductor and Digital Industry Strategy is channeling capital toward domestic silicon ingot production and epitaxial processing capacity.
- EUV node advancement:Sub-3 nm logic requirements for defect-free 300 mm substrates are pulling premium pricing for engineered silicon.
Market Restraints
- Polysilicon energy intensity:China's MIIT dual carbon goals enforce smelter energy caps that constrain feedstock cost structures for domestic wafer producers.
- Fluorinated gas constraints:The EU's F-Gas Regulation limits etching process emissions, adding compliance overhead to European wafer fabrication.
- SOI substrate substitution:Silicon-on-insulator wafers for RF applications face pressure from bulk-silicon alternatives in cost-sensitive consumer devices.
Strategic Opportunities
- India's PLI scheme:Semiconductor manufacturing incentives are attracting wafer polishing and epitaxial service investments for domestic logic and memory fabs.
- Silicon carbide convergence:Hybrid substrate platforms combining silicon control layers with SiC power structures are opening power electronics applications.
- Direct fab procurement:Foundries are bypassing merchant distributors to contract directly with crystal growers for 300 mm epitaxial supply.
Industry Challenges
- Crystal puller technician scarcity:Czochralski furnace operation requires specialized thermal gradient control expertise that fabs struggle to staff.
- Cleanroom capex intensity:Atomic-scale flatness requirements demand Class 1 particulate control infrastructure exceeding $500 million per greenfield line.
- GB standard compliance timelines:China's evolving silicon purity certifications delay qualification of imported wafers for domestic foundry use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wafer Market |
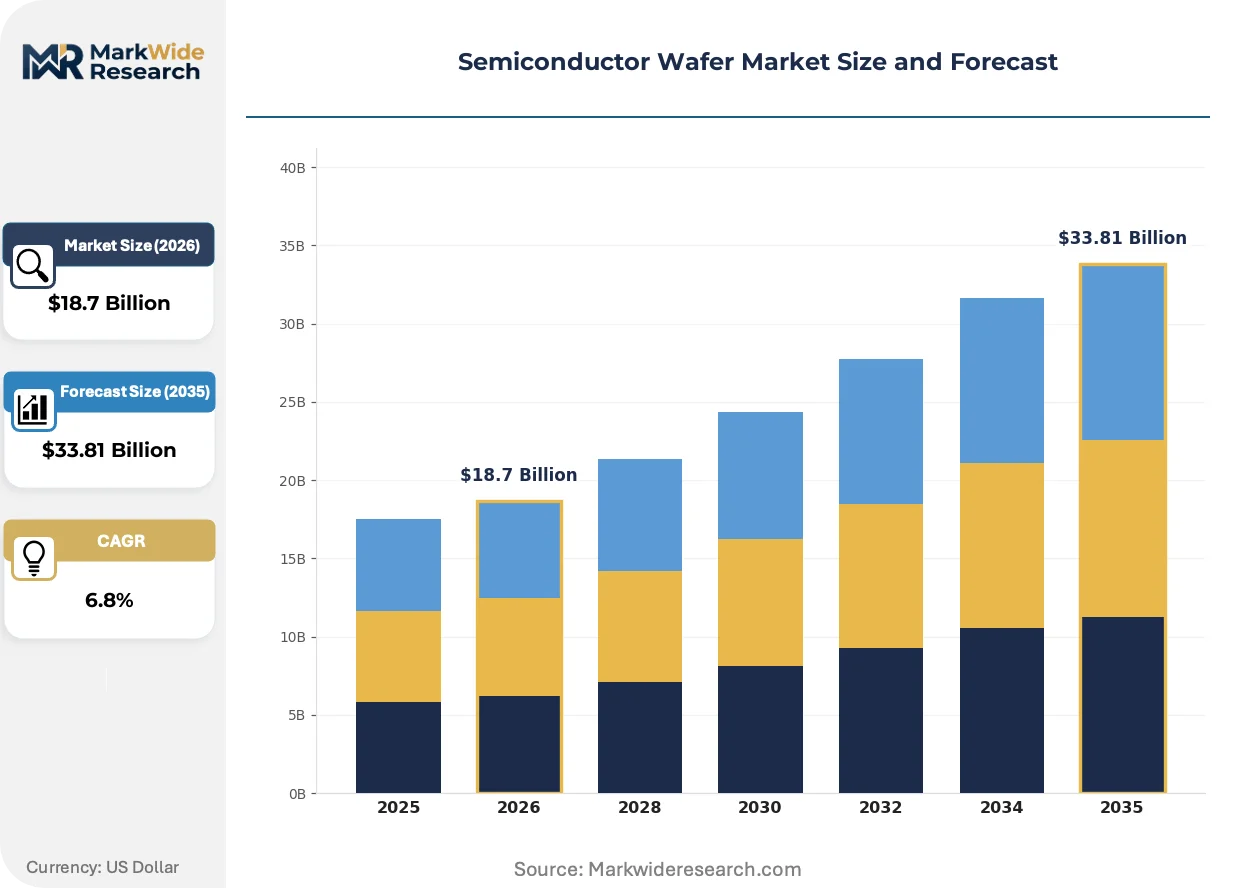
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Wafers, Gallium Arsenide Wafers, SOI Wafers, Sapphire Wafers Diameter: 200 mm, 300 mm, 450 mm, Others Application: Consumer Electronics, Communication Devices, Automotive, Industrial Equipment End User: Semiconductor Manufacturers, Foundries, OEMs, Research Institutions |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., SUMCO Corporation, GlobalWafers Co., Ltd., Siltronic AG, SK Siltron Co., Ltd., Okmetic Oyj, Soitec S.A., Wafer Works Corporation, Semiconductor Manufacturing International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wafer Market Strategic Shifts
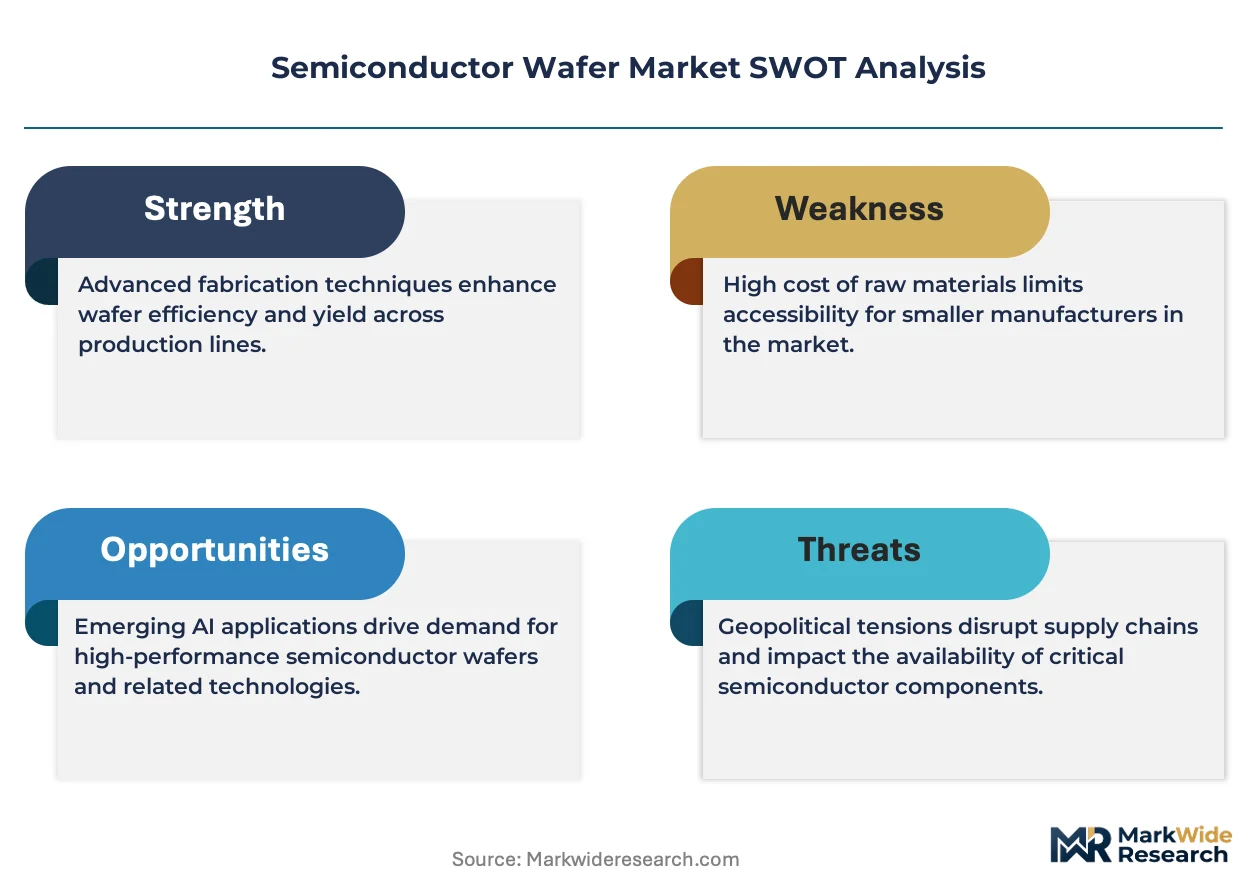
Wafer engineering is pivoting from dimensional scaling to materials architecture, with substrate customization replacing commodity volume as the primary value lever.
Defect-engineered 300 mm epitaxial wafers is overtaking polished substrates in advanced logic procurement. TSMC and Samsung Foundry are specifying surface roughness below 0.2 nm RMS for EUV lithography compatibility. This specification compression is marginalizing merchant suppliers lacking in-house epitaxial growth capability.
The EU's F-Gas Regulation and Chips Act are jointly constraining wafer etching emissions while subsidizing domestic silicon processing. European fabs must now balance fluorinated gas abatement costs against the Act's production incentives. German wafer polishers are responding by retrofitting plasma abatement systems to maintain subsidy eligibility.
Long-term supply agreements are displacing spot-market purchasing for 300 mm substrates. Foundries are locking five-year crystal supply contracts with Shin-Etsu and SUMCO to secure EUV-grade material allocation. This contracting shift is most visible in Taiwan's Hsinchu Science Park cluster, where TSMC and UMC have exhausted merchant distributor inventory.
Semiconductor Wafer Market Segmentation
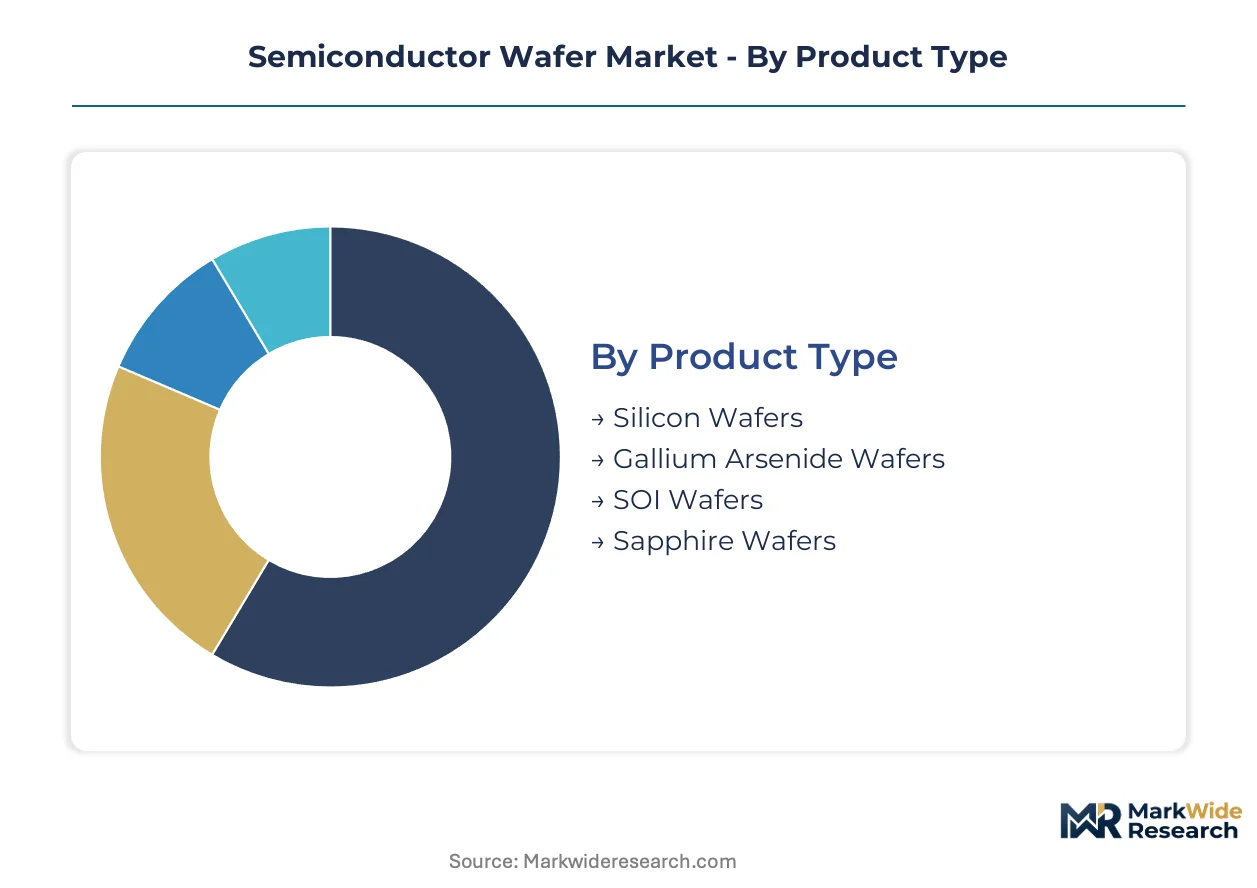
Wafer segmentation reveals how substrate specifications fragment procurement pools across logic, memory, and power applications. Diameter and material choices determine foundry capital allocation, while end-user concentration shapes contract structures between crystal growers and fabs.
Product Type:
Customization intensity spans from commodity silicon to engineered compound semiconductors, with each material tier serving distinct thermal, frequency, or optical requirements.
- Silicon Wafers:Crystalline silicon substrates exceeding 99.9999999% purity anchor volume production for logic and memory chips. TSMC and Samsung Foundry concentrate 300 mm procurement in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster, pulling premium pricing for defect-engineered epitaxial grades compatible with EUV lithography below 3 nm.
- SOI Wafers:Silicon-on-insulator architectures embed a buried oxide layer to eliminate substrate leakage in RF and low-power designs. Demand concentrates in 5G baseband processors and aerospace rad-hard applications where bulk silicon fails, though cost pressure from advanced bulk-CMOS alternatives constrains penetration in consumer devices.
- Gallium Arsenide Wafers:III-V compound substrates enable high-electron-mobility transistors for millimeter-wave communications and optical emitters.
- Sapphire Wafers:Single-crystal aluminum oxide substrates support GaN epitaxy for high-brightness LEDs and RF power amplifiers.
Leading the category by volume: Silicon Wafers. Growing fastest: SOI Wafers.
Diameter:
Wafer diameter selection trades capital efficiency against process complexity, with foundry migration patterns determining equipment depreciation cycles.
- 300 mm:The dominant diameter for advanced logic and DRAM fabrication delivers single-wafer processing economies that compress die costs at sub-5 nm nodes. TSMC, Samsung, and Intel have concentrated 300 mm capex in Taiwan, South Korea, and Arizona, exhausting merchant distributor inventory and forcing direct crystal supply contracts with Shin-Etsu and SUMCO.
- 200 mm:Mature-node diameter faces supply tightness as automotive MCU and power discrete manufacturers absorb capacity for traction inverters and battery management systems. Infineon and STMicroelectronics anchor demand in European automotive clusters, while China's SMIC and Hua Hong expand 200 mm lines under MIIT self-sufficiency mandates.
- 450 mm:Next-generation diameter stalled after Intel's 2014 pause, with no active volume production.
- Others:Legacy 150 mm and smaller diameters serve discrete power devices and research applications.
300 mm commands value share despite slower volume growth. 200 mm supply constraints are expanding fastest.
Application:
End-use fragmentation splits procurement between consumer-scale volume and industrial-grade reliability requirements.
- Consumer Electronics:Smartphones, tablets, and wearables drive 300 mm logic wafer consumption at foundries serving Apple, Qualcomm, and MediaTek. Taiwan's TSMC anchors this demand through dedicated capacity for 4 nm and 3 nm SoC production.
- Automotive:Functional safety requirements and electrification are pulling 200 mm supply for BMS MCUs, SiC gate drivers, and sensor fusion processors. Bosch, Continental, and Denso concentrate demand in Germany, Japan, and Michigan supply corridors.
- Communication Devices:5G infrastructure and satellite terminals absorb GaAs and SOI substrates for RF front-end modules.
- Industrial Equipment:Factory automation and power conversion utilize mature-node silicon for motor drives and PLC controllers.
Consumer Electronics leads by wafer volume. Automotive applications are climbing the fastest.
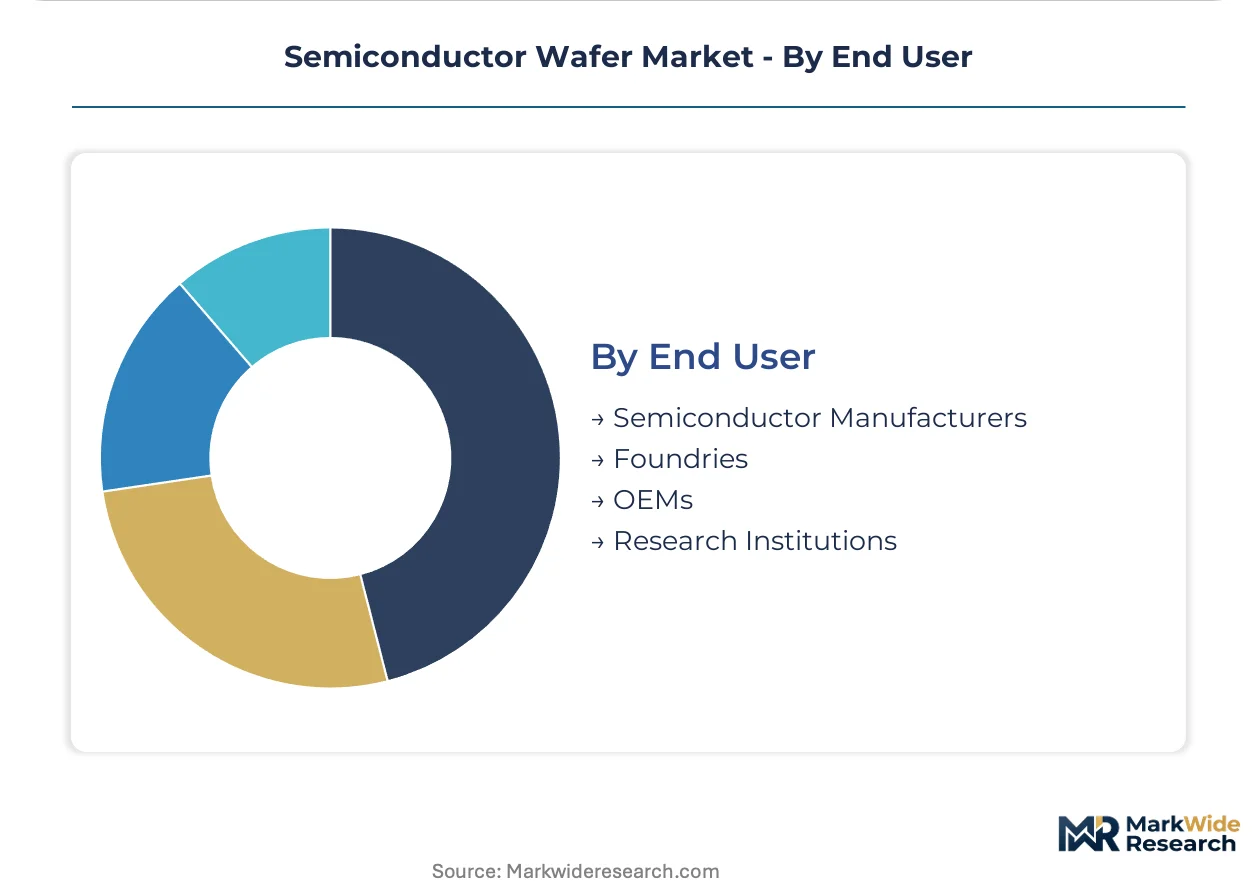
End User:
Customer-type concentration determines contract structures, from long-term crystal supply agreements to spot-market research purchases.
- Foundries:Pure-play and IDM foundries including TSMC, GlobalFoundries, and UMC dominate 300 mm procurement through multi-year silicon supply contracts. These direct agreements bypass merchant distributors and lock epitaxial capacity for EUV-grade material.
- Semiconductor Manufacturers:Integrated device manufacturers such as Intel, Samsung, and Texas Instruments operate captive crystal growth or secure dedicated supply lines for internal fab networks.
- OEMs:System houses including Tesla and Apple are contracting directly with wafer polishers for custom substrate specifications.
- Research Institutions:Universities and national laboratories purchase small-diameter wafers for process development and academic research.
Foundries lead procurement volume. OEM direct contracting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's densest concentration of 300 mm wafer consumption. Taiwan's foundry cluster pulls premium epitaxial supply through direct contracts with Japanese crystal growers, while regulatory interventions across major economies reshape where silicon processing capacity expands.
Taiwan
TSMC and UMC absorb the majority of 300 mm epitaxial wafer output for 3 nm EUV production. The National Science and Technology Council coordinates fab expansion incentives under the Chip Implementation Act. Hsinchu Science Park and Taichung's Central Taiwan Science Park concentrate the world's most advanced logic wafer demand, forcing Shin-Etsu and SUMCO to allocate dedicated crystal supply lines.
Japan
Shin-Etsu Chemical and SUMCO anchor global silicon crystal supply through captive polysilicon refining and defect-engineered substrate specialization. METI's Semiconductor and Digital Industry Strategy channels subsidies toward domestic ingot production and epitaxial processing capacity. The Kyushu and Kanto regions concentrate crystal growth facilities serving Taiwan and South Korean foundries.
China
SMIC and Hua Hong Semiconductor expand 200 mm lines for automotive MCU and power discretes under MIIT self-sufficiency mandates. GB standards and dual carbon goals enforce energy intensity caps on polysilicon smelters, constraining feedstock cost structures. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate domestic wafer polishing and epitaxial service investments.
South Korea
Samsung Foundry and SK Hynix drive 300 mm demand for DRAM and 3D NAND memory stacks alongside advanced logic. The Ministry of Trade, Industry and Energy coordinates K-Semiconductor Belt incentives for domestic silicon processing. Pyeongtaek and Yongin anchor memory-focused wafer consumption, with direct supply agreements bypassing merchant distributors.
Germany
Infineon and Bosch absorb 200 mm supply for automotive power devices and traction inverter modules. The EU's F-Gas Regulation and Chips Act jointly constrain etching emissions while subsidizing domestic silicon processing. Saxony's Silicon Saxony cluster and Bavaria's automotive corridor concentrate European wafer demand, with polishers retrofitting plasma abatement systems to maintain subsidy eligibility.
Semiconductor Wafer Market Competitive Environment
Premium-margin players sit above commodity-margin players across crystal growth capability and epitaxial processing sophistication. The vendor base consolidates around Japanese and Taiwanese specialists with captive polysilicon supply or direct foundry relationships. Three archetypes dominate: integrated chemical conglomerates with upstream refining control, pure-play wafer specialists with defect-engineering expertise, and regional diversifiers with multi-continent polishing networks. Competitive moves center on long-term supply contract lock-ins with foundries and backward integration into polysilicon smelting.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. exemplifies the integrated archetype through captive polysilicon refining. SUMCO Corporation occupies the specialist position in defect-engineered substrates for memory applications. GlobalWafers Co., Ltd. represents geographic diversification across multiple fab clusters.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| SUMCO Corporation |
| GlobalWafers Co., Ltd. |
| Siltronic AG |
| SK Siltron Co., Ltd. |
| Okmetic Oyj |
| Soitec S.A. |
| Wafer Works Corporation |
| Semiconductor Manufacturing International Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned crystal growth specialists in Japan anchor supply discipline through captive polysilicon refining, translating upstream cost control into sustained premium pricing for EUV-grade 300 mm epitaxial wafers while merchant distributors face margin compression from direct foundry contracting.
Pricing Analysis
Yield-based pricing anchors 300 mm epitaxial contracts, with TSMC and Samsung Foundry paying premiums tied to defect-free surface specifications below 0.2 nm RMS. Price differentiation separates EUV-compatible engineered substrates from commodity polished grades, with volume scale and customization level as secondary drivers. Cost compression in 200 mm polished tiers intensifies as automotive MCU manufacturers absorb constrained supply. Foundries exhibit lowest price sensitivity; power discrete OEMs face acute margin pressure from supply tightness.
Supply Chain Analysis
Specialized quartz crucible freight costs from Heraeus and Saint-Gobain facilities constrain Czochralski furnace economics, with logistics expenses amplifying total landed costs for crystal pullers in Taiwan and South Korea. Supply concentrates in Japan, Taiwan, and South Korea, drawing from high-purity polysilicon feedstock, quartz crucibles, and argon gas supplies. Single-source vulnerability in epitaxial reactor components creates chokepoint exposure. Distribution runs through direct long-term contracts between Shin-Etsu, SUMCO, and Hsinchu Science Park foundries, displacing merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial reactor capacity scarcity props pricing power for defect-engineered substrate specialists, with Czochralski furnace lead times extending procurement cycles beyond 18 months for new market entrants.
For Market Incumbents: Deploy backward integration into polysilicon smelting to defend margin position against China's MIIT energy caps reshaping feedstock cost structures. Lock five-year direct supply agreements with TSMC and UMC to preempt merchant distributor displacement. Prioritize epitaxial processing certification for sub-3 nm EUV compatibility as the primary defensive moat against SOI substrate substitution threats. For New Entrants and Emerging Players: India's PLI scheme in semiconductor manufacturing opens a window for wafer polishing and epitaxial service investments serving domestic logic fabs. Target 200 mm supply for automotive power discretes as the most penetrable segment, with Bosch and Continental procurement corridors in Germany offering qualified entry points. Pursue joint venture structures with established crystal growers to bypass Czochralski technician scarcity barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap polishers with captive epitaxial capability in Taiwan and Japan during foundry capex pauses. Long-term viability centers on EUV node migration sustaining premium substrate demand through the next decade. Watch China's GB standard compliance timelines for imported wafer qualification as the inflection signal determining domestic versus import supply mix.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Shin-Etsu's captive refining anchors cost leadership against energy-capped Chinese smelters. |
| Long-term Supply Agreement Lock-in | TSMC's five-year contracts with SUMCO exhaust merchant inventory and secure EUV-grade allocation. |
| Epitaxial Processing Certification | Sub-0.2 nm RMS surface specifications marginalize suppliers lacking in-house growth capability. |
| Geographic Diversification | GlobalWafers' multi-continent polishing networks reduce single-source exposure to Taiwan logistics. |
| Plasma Abatement Retrofit | German polishers meet EU F-Gas Regulation subsidy eligibility through emissions control investment. |
Study Parameters
SEC filings, METI subsidy disclosures, and customs trade data formed the secondary backbone, cross-referenced with primary interviews spanning crystal growth engineers, foundry procurement directors, epitaxial equipment specialists, and polysilicon smelter operations managers. Bottom-up wafer demand modeling by diameter, material, and application segment combined with top-down semiconductor capex cycle analysis to triangulate volume and value estimates.
Historical trendline analysis of foundry capacity expansion, crystal puller installation rates, and epitaxial reactor deployment informed the projection framework across the analysis window. Segmentation dimensions included wafer diameter, material architecture, end-use application, and customer-type concentration. CAGRs derived from equipment depreciation cycles, node migration timelines, and regional regulatory incentive trajectories, with EUV lithography penetration and automotive electrification content as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for gate-all-around transistor architectures would alter the outlook for substrate flatness requirements. Forecasts reflect assumptions regarding China's MIIT self-sufficiency targets, EU F-Gas Regulation enforcement intensity, and Japan's METI subsidy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Americas Power Transistor Market