
 Semiconductor Dielectric Etching Equipment Market | 2026-2036
Semiconductor Dielectric Etching Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Dielectric Etching Equipment Market Analytics
Aftermarket service revenue is fragmenting across tool refurbishment, spare parts logistics, and field engineering contracts as equipment lifecycles extend. Applied Materials leverages its installed base to sustain recurring service income across mature etch platforms. Lam Research anchors its position through deep process libraries that differentiate performance on high-aspect-ratio dielectric structures. Tokyo Electron competes by integrating chamber hardware with proprietary gas-delivery architectures that tighten process control.
Semiconductor dielectric etching equipment refers to capital tools that selectively remove insulating oxide and nitride films using chemically reactive plasmas, typically operating at chamber pressures below 100 mTorr with RF power delivery in the 13.56 MHz range, to pattern interconnect isolation and capacitor structures in integrated circuits. Plasma etching systems dominate current installations due to their throughput advantage on 300 mm wafers, while deep reactive ion etching commands premium pricing for 3D NAND staircase and logic fin profile applications. Foundry end users represent the fastest-expanding demand pool as contract manufacturers add dielectric etch steps for multi-patterning schemes at nodes below 7 nm.
EPA regulates fluorinated greenhouse gas emissions from semiconductor manufacturing under the American Innovation and Manufacturing Act, pressuring fabs to adopt abatement systems or alternative chemistries. REACH restricts perfluorinated compound use in European fabs, while ISO 14644 cleanroom standards govern particle limits that etch equipment must maintain during dielectric film removal. Stakeholders must monitor how dual carbon goals in China and EU Green Deal timelines redirect capital toward low-emission etch platforms without sacrificing wafer throughput.
Market Dynamics
Multi-patterning schemes at sub-7nm logic nodes are multiplying dielectric etch steps per wafer, stretching tool utilization rates and reshaping capacity planning across foundry operations.
Growth Catalysts
- Advanced Node Logic:Foundries in Taiwan and South Korea are expanding dielectric etch capacity for finFET and gate-all-around transistor architectures, driving tool orders for high-aspect-ratio structures.
- 3D NAND Staircase:Vertical stacking of memory cells beyond 200 layers requires deep reactive ion etching for staircase contact formation, sustaining premium equipment demand.
- EU F-Gas Regulation:REACH compliance mandates are accelerating adoption of abatement systems and alternative fluorinated chemistries, creating upgrade cycles for existing installed bases.
Market Restraints
- Fluorinated Gas Supply Concentration:Specialty etch gas production clusters in Japan and the United States create vulnerability to export restrictions or supply disruptions.
- Chamber Component Lead Times:Ceramic electrostatic chucks and quartz liners face extended procurement cycles from limited qualified suppliers, constraining tool delivery schedules.
- EPA Abatement Mandates:American Innovation and Manufacturing Act compliance adds capital burden for greenhouse gas capture systems, pressuring fab operating margins.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fabrication facilities create virgin demand for dielectric etch platforms as greenfield fabs break ground.
- Atomic Layer Etch Integration:Convergence of plasma etching with atomic layer precision enables angstrom-level control for gate oxide trimming applications.
- Refurbishment Channel Expansion:Secondary equipment markets in Southeast Asia extend tool lifecycles through certified rebuild programs, capturing value from mature platform retirements.
Industry Challenges
- Process Engineer Scarcity:Specialized expertise in plasma physics and chamber matching protocols remains concentrated among veteran practitioners approaching retirement.
- Legacy Tool Integration:Retrofitting 200mm-era etch platforms with modern gas delivery and RF matching networks demands custom engineering without vendor support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Dielectric Etching Equipment Market |
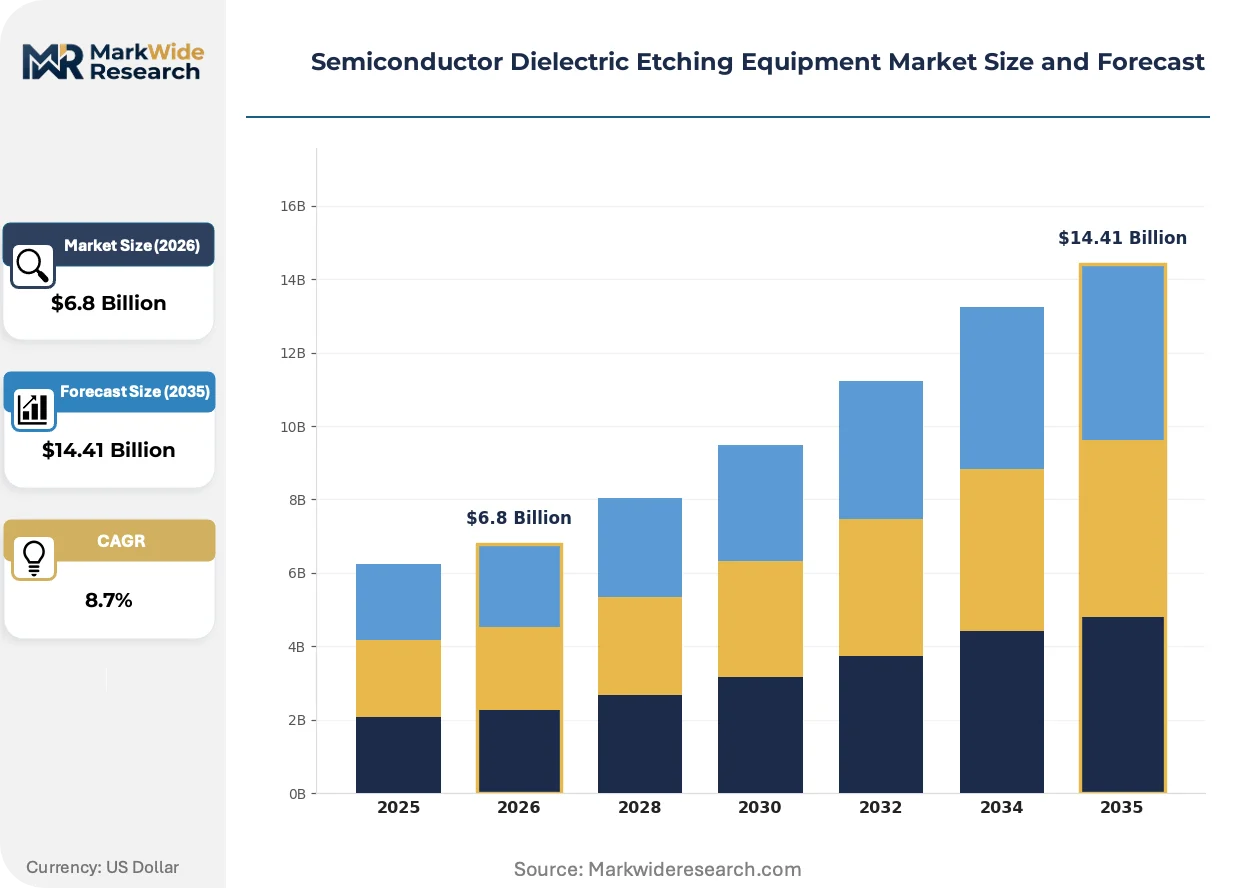
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Etching, Plasma Etching, Reactive Ion Etching, Deep Reactive Ion Etching Technology: Hydrogen Fluoride, Chlorine, Trichlorosilane, Nitrogen End User: Foundries, Integrated Device Manufacturers, Research Institutions, OEMs Installation: Clean Room, Laboratory, Production Floor, Pilot Plant |
| Companies Covered | Applied Materials, Lam Research, Tokyo Electron, Hitachi High-Technologies, ASML, KLA Corporation, SCREEN Semiconductor Solutions, ULVAC, Plasma-Therm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Dielectric Etching Equipment Market Evolving Landscape
Plasma source architectures and process chemistries are converging to address atomic-scale precision requirements while regulatory pressure on fluorinated emissions intensifies equipment redesign priorities.
Atomic layer etching is collapsing the boundary between isotropic wet processing and anisotropic plasma removal by delivering single-atom precision with directional control. Memory manufacturers in South Korea are piloting ALE modules for 3D NAND channel hole cleaning, compressing the defect window that previously required multiple tool passes.
EU F-Gas Regulation amendments are tightening allowable emissions from semiconductor manufacturing, forcing fabs to install point-of-use abatement or switch to lower-global-warming-potential chemistries. Equipment vendors are responding with integrated thermal scrubber designs that capture unreacted NF3 and CF4 before stack release, particularly in German and French production facilities.
Service contract unbundling is fragmenting the traditional bundled maintenance model into discrete spare parts, remote diagnostics, and field engineering subscriptions. Foundry operators in Taiwan are driving this shift by insourcing routine chamber cleans while outsourcing specialized match tuning, redistributing vendor revenue streams toward consumption-based arrangements.
Semiconductor Dielectric Etching Equipment Market Segmentation
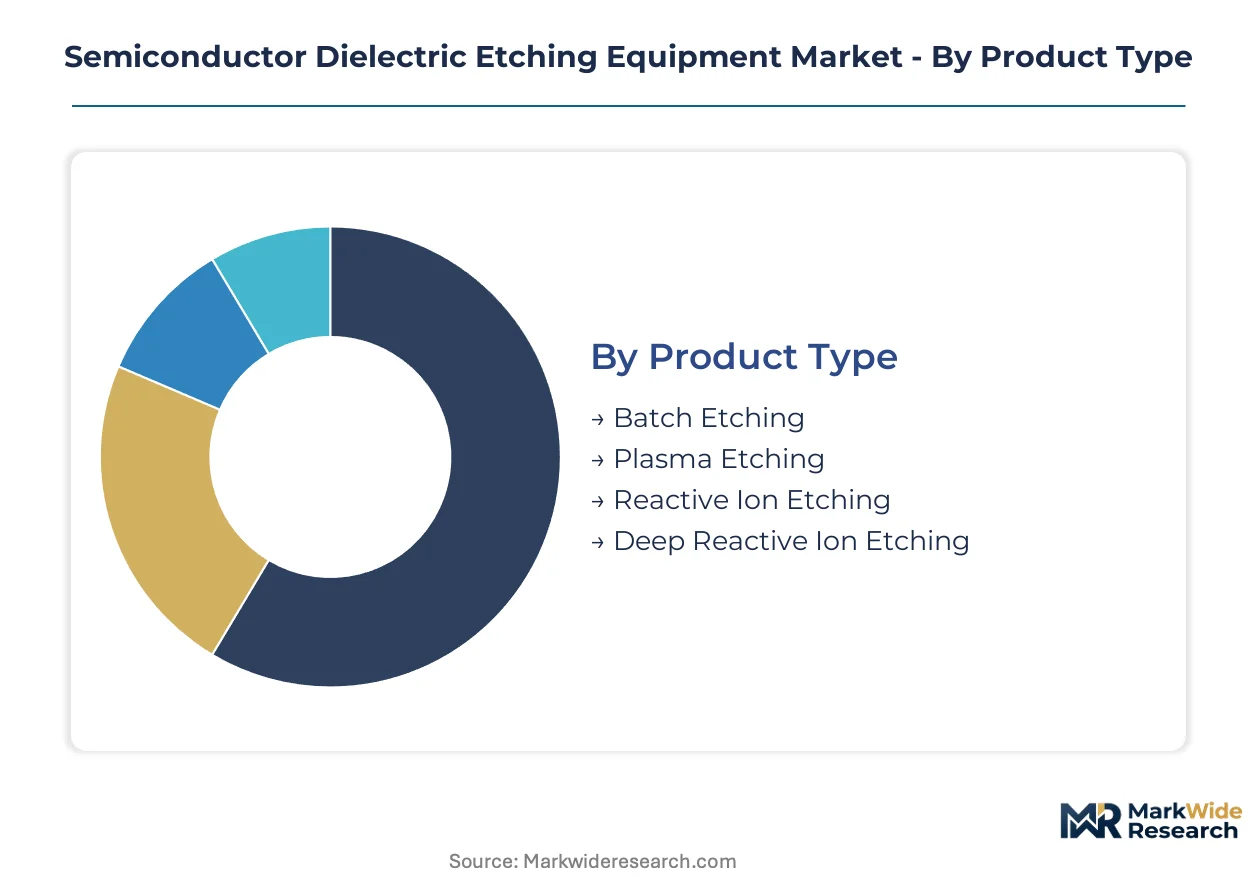
Equipment segmentation in dielectric etching reveals divergent replacement cycles, with plasma platforms turning over every 4-6 years while batch systems persist for 8-10 years. Procurement patterns cluster around process node transitions, forcing fabs to synchronize tool refresh with lithography roadmaps.
Product Type:
Cycle times vary dramatically across etch modalities, with single-wafer plasma systems refreshing fastest due to chamber wear from high-ion-density processes, while batch platforms endure longer in trailing-edge fabs.
- Plasma Etching:Capacitively coupled plasma systems dominate 300mm wafer processing through independent control of ion energy and flux. Foundries in Taiwan and South Korea drive replacement demand as they scale finFET and gate-all-around production at nodes below 5nm.
- Deep Reactive Ion Etching:Bosch-process enabled systems alternate deposition and etch cycles to achieve vertical sidewalls in high-aspect-ratio structures. Memory manufacturers in South Korea deploy these for 3D NAND staircase formation beyond 200 layers, sustaining premium pricing.
- Batch Etching:Parallel wafer processing in hot-wall reactors serves trailing-edge logic and power semiconductor fabs seeking cost efficiency over precision.
- Reactive Ion Etching:Lower-density plasma configurations persist in research settings and specialty device production where throughput requirements remain modest.
Plasma etching dominates installed base. Deep reactive ion etching is where expansion concentrates.
Technology:
Process chemistry selection hinges on material selectivity requirements, with fluorinated compounds commanding premium pricing due to abatement mandates while alternative chemistries penetrate niche applications.
- Hydrogen Fluoride:Dry etch processes utilizing HF-derived plasmas excel at silicon oxide removal with high selectivity to silicon nitride. EPA abatement requirements under the American Innovation and Manufacturing Act are forcing fabs to install point-of-use scrubbers, adding capital intensity.
- Chlorine:Cl2-based chemistries attack aluminum and metal nitrides where fluorine-based processes fail, serving compound semiconductor and power device manufacturers.
- Trichlorosilane:Specialized precursor delivery enables selective silicon etching in MEMS release and wafer thinning operations.
- Nitrogen:N2-diluted plasmas provide gentle surface treatment and residue removal without aggressive film attack, finding use in post-etch cleans.
Hydrogen fluoride chemistry anchors current installed capacity. Chlorine processes are gaining share fastest in power semiconductor applications.
End User:
Customer type determines procurement sophistication, with foundries driving specification standards while research institutions prioritize flexibility over throughput.
- Foundries:Contract manufacturers operate the most intensive etch tool fleets, with Taiwan Semiconductor Manufacturing and Samsung Foundry specifying chamber matching protocols across multi-fab networks. Multi-patterning schemes at sub-7nm nodes multiply etch steps per wafer, stretching utilization rates.
- Integrated Device Manufacturers:Captive fabs at Intel and Texas Instruments balance leading-edge development with mature product longevity, creating bifurcated procurement profiles.
- Research Institutions:Universities and national laboratories acquire refurbished platforms or flexible research-grade systems for process development.
- OEMs:Subsystem suppliers and captive equipment builders source etch modules for integration into custom cluster tools.
Foundries dominate current order books. Integrated device manufacturers are where technology transfer concentrates.
Installation:
Facility classification shapes environmental controls and tool configuration, with clean room deployments commanding the strictest particle limits and highest capital overhead.
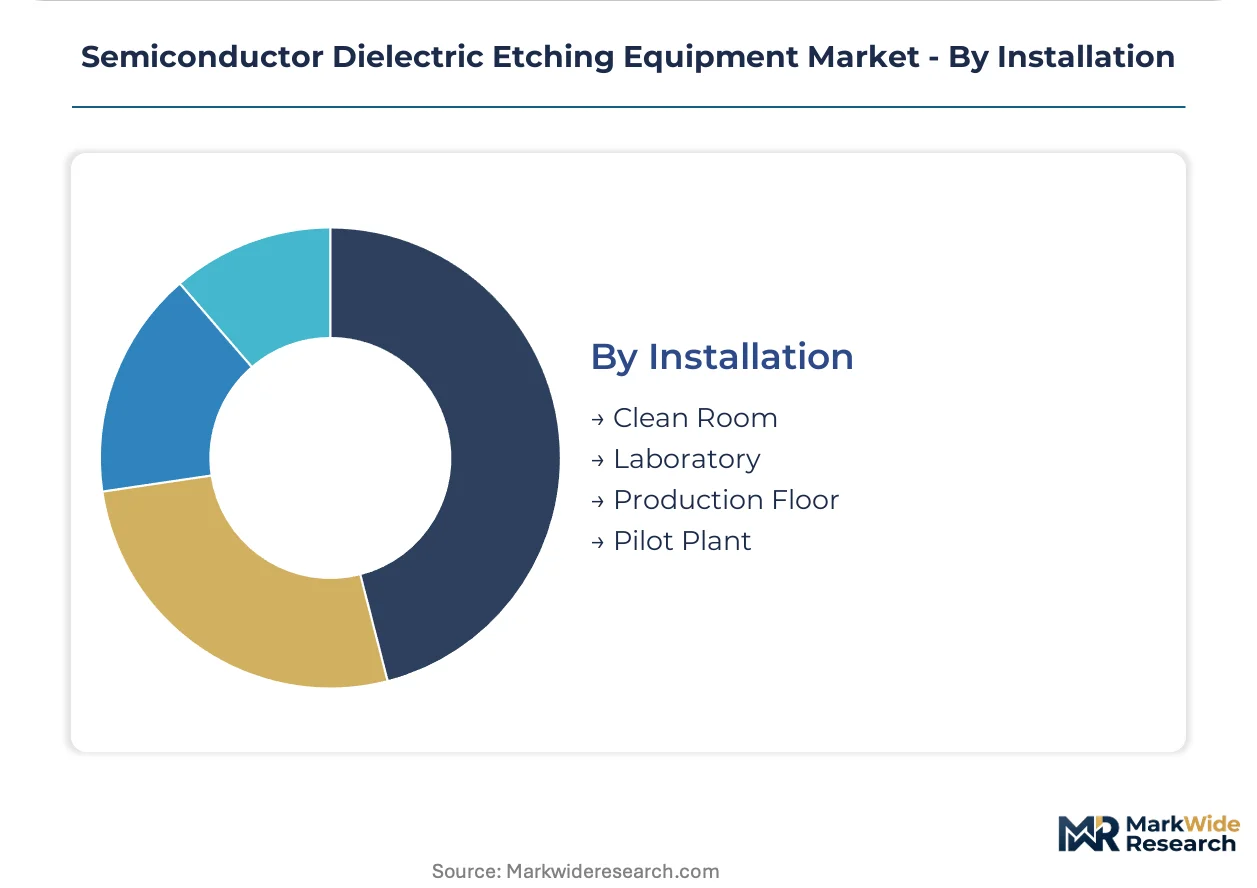
- Clean Room:ISO 14644 Class 1-10 environments host leading-edge production tools where particle counts below 0.1 µm directly impact yield. Fabs in Hsinchu and Pyeongtaek operate the largest clean room etch installations globally.
- Production Floor:Controlled manufacturing areas with relaxed particle standards serve trailing-edge and analog semiconductor production.
- Pilot Plant:Pre-production facilities bridge process development and volume manufacturing, requiring rapid reconfiguration capability.
- Laboratory:Research settings accommodate experimental chemistries and non-standard wafer sizes outside commercial production norms.
Clean room installations dominate capital deployment. Production floor configurations are where emerging market expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabs consume dielectric etch equipment for high-volume logic and memory production, while North American and European installations prioritize abatement-integrated platforms for regulatory compliance. Equipment utilization patterns diverge sharply across these geographies.
United States
Intel's leading-edge development fabs in Oregon and Arizona drive demand for atomic-scale precision etch systems. EPA enforcement under the American Innovation and Manufacturing Act mandates point-of-use abatement for fluorinated process gases. Austin and Hillsboro host concentrated equipment installations where foundry operators balance throughput targets with emissions capture requirements.
South Korea
Samsung and SK Hynix memory complexes require deep reactive ion etching systems for 3D NAND staircase formation beyond 200 layers. MFDS-aligned industrial safety protocols govern chamber certification and gas handling infrastructure. Pyeongtaek and Icheon manufacturing clusters anchor the densest dielectric etch tool concentrations outside Taiwan.
Taiwan
TSMC and United Microelectronics foundries operate the world's most intensive single-wafer plasma etch fleets for sub-5nm finFET and gate-all-around production. Bureau of Standards, Metrology and Inspection (BSMI) certifications regulate RF power delivery system safety. Hsinchu Science Park and Tainan Southern Taiwan Science Park concentrate multi-patterning etch steps that multiply tool utilization rates.
Japan
Tokyo Electron and Hitachi High-Technologies anchor domestic demand for proprietary gas-delivery architectures and chamber hardware. METI's semiconductor revitalization subsidies support capital investment in legacy node capacity expansion. Hiroshima and Kumamoto industrial corridors host trailing-edge and power semiconductor fabs with extended equipment replacement cycles.
Germany
Bosch and Infineon analog and power semiconductor fabs require dielectric etch platforms with relaxed precision specifications for automotive-grade production. EU F-Gas Regulation amendments force adoption of integrated thermal scrubbers for NF3 and CF4 capture. Dresden and Regensburg manufacturing centers balance REACH compliance with cost efficiency in chamber configuration selection.
Semiconductor Dielectric Etching Equipment Market Competitive Landscape
Capability concentration sits with integrated platform specialists; scale advantage sits with installed-base incumbents. Three vendors command the majority of leading-edge dielectric etch placements through proprietary chamber architectures and process libraries. The competitive terrain stratifies between full-stack platform providers, subsystem specialists, and regional refurbishment operators. Dominant competitive moves include service contract unbundling and abatement-integrated system redesign.
Within the integrated platform tier, Applied Materials and Lam Research exemplify divergent strategic positioning. Applied Materials leverages its broad process equipment portfolio to sustain recurring service revenue across mature etch installations. Lam Research anchors its market presence through deep process libraries for high-aspect-ratio dielectric structures. Tokyo Electron occupies a distinct position by integrating chamber hardware with proprietary gas-delivery architectures that tighten process control parameters.
| Leading Market Players |
|---|
| Applied Materials |
| Lam Research |
| Tokyo Electron |
| Hitachi High-Technologies |
| ASML |
| KLA Corporation |
| SCREEN Semiconductor Solutions |
| ULVAC |
| Plasma-Therm |
| Others |
Value Network & Pricing Analysis
Japanese ceramic electrostatic chuck and quartz liner suppliers anchor upstream concentration for critical chamber components, directing margin pools toward qualified sub-tier vendors capable of meeting extended procurement cycles from Lam Research, Applied Materials, and Tokyo Electron.
Pricing Analysis
Long-term offtake agreements dominate equipment procurement between foundries and platform vendors, with TSMC and Samsung Foundry locking multi-year delivery schedules. Price differentiation hinges on chamber matching certification tiers and after-sales service bundling intensity. Cost compression in standard plasma etch platforms is intensifying because Chinese equipment vendors are penetrating trailing-edge segments with aggressive service unbundling. Research institutions exhibit highest price sensitivity; leading-edge foundries prioritize process library depth over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for etch equipment vendors navigating export control classifications. Component sourcing draws from Japan, the United States, and Germany for RF matching networks, electrostatic chucks, and gas delivery manifolds. Single-source vulnerability concentrates in fluorinated etch gas production clusters. Distribution runs through direct vendor-fab relationships with limited channel intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Taiwan and South Korean foundry operators as TSMC, Samsung Foundry, and SK Hynix consolidate procurement specifications across multi-fab networks.
For Market Incumbents: Harden installed-base lock-in through proprietary gas-delivery architecture upgrades that complicate third-party refurbishment. Deepen backward integration into ceramic chamber component production to offset Japanese supplier lead time volatility. Prioritize abatement-integrated platform redesigns ahead of EU F-Gas Regulation enforcement timelines.
For New Entrants and Emerging Players: Indian greenfield fabs under the Semiconductor Mission PLI scheme represent the most penetrable entry point for certified rebuild programs and mature platform retrofits. Southeast Asian secondary equipment markets offer white-space for refurbishment channel establishment. Lead with consumption-based field engineering subscriptions to bypass capital-intensive new tool development.
For Investors and Strategic Acquirers: Capital is best deployed toward subsystem specialists with captive gas-delivery intellectual property and established foundry qualification records. Long-term viability centers on atomic layer etch module integration capability and regulatory-compliant abatement technology portfolios. Watch for inflection in India fab construction permits as demand signal validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Abatement-Integrated Platform Redesign | EU F-Gas Regulation compliance mandates thermal scrubber integration for NF3 and CF4 capture. |
| Atomic Layer Etch Module Development | Samsung and SK Hynix pilot ALE for 3D NAND channel hole cleaning applications. |
| Refurbishment Channel Certification | Secondary equipment markets in Southeast Asia extend tool lifecycles through rebuild programs. |
| Proprietary Gas-Delivery Architecture Investment | Tokyo Electron tightens process control through integrated chamber hardware designs. |
| India Greenfield Fab Partnership | PLI scheme incentives create virgin demand for dielectric etch platforms at domestic facilities. |
Research Methodology
Operator-level perspectives from fab process engineers, equipment procurement managers, chamber matching specialists, and aftermarket service directors anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings, SEMI equipment billings data, customs trade records, and EPA regulatory dockets. Bottom-up equipment unit forecasts triangulated against top-down fab capex projections across the analysis window.
Scenario-bracketing framed the projection horizon with base, upside, and downside cases reflecting foundry node transition timing and memory capital expenditure cyclicality. Segmentation dimensions modeled include etch modality, process chemistry, end-user archetype, and installation environment. CAGRs derived from fitted growth curves against historical equipment billings patterns. Industry-specific inputs incorporated lithography roadmap synchronization and multi-patterning step intensity at sub-7nm nodes.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, memory pricing recoveries, or export control enforcement would shift the trajectory. Forecasts reflect documented assumptions on node transition schedules and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Electrostatic Chucks Market