
 Semiconductor Process and Control Equipment Market | 2026-2036
Semiconductor Process and Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Process and Control Equipment Market Intelligence
The historical reliance on personal computing and smartphone cycles is decoupling from overall equipment demand as automotive and data center applications create independent growth vectors. ASML dominates the critical photolithography segment with its EUV technology leadership. Lam Research specializes in advanced etching and deposition solutions vital for 3D NAND and logic device fabrication. KLA, in turn, leads the process control and inspection market, ensuring yield management for these complex manufacturing steps.
Semiconductor process and control equipment encompasses the highly specialized machinery used within Class 1 cleanrooms to fabricate integrated circuits on silicon wafers, typically 300mm in diameter. These systems perform critical functions like photolithography, material deposition, etching, and metrology to create complex electronic devices. Photolithography systems, particularly EUV, command the largest share of capital spending due to their complexity and cost. Concurrently, demand for advanced etching equipment and atomic layer deposition tools is rising to enable the intricate 3D architectures of modern logic and memory chips.
Government initiatives like the US CHIPS Act and the European Chips Act are directly influencing investment decisions by providing substantial subsidies for domestic fabrication plant construction. Environmental regulations, including China's dual carbon goals and the EU's F-Gas Regulation, also impact equipment design by governing chemical usage and energy consumption. Equipment manufacturers must therefore navigate a complex web of trade controls and localized industrial policies to secure market access and manage supply chain stability.
Market Dynamics
The semiconductor industry's transition to gate-all-around (GAA) transistor architectures for sub-3nm process nodes is the central force shaping the equipment market. This fundamental shift requires entirely new categories of atomic layer deposition and selective etching tools, driving a major capital investment cycle.
Growth Catalysts
- AI Hardware Demand:The proliferation of artificial intelligence and high-performance computing applications necessitates advanced packaging technologies like 2.5D and 3D stacking, spurring investment in specialized bonding and through-silicon via (TSV) etching equipment.
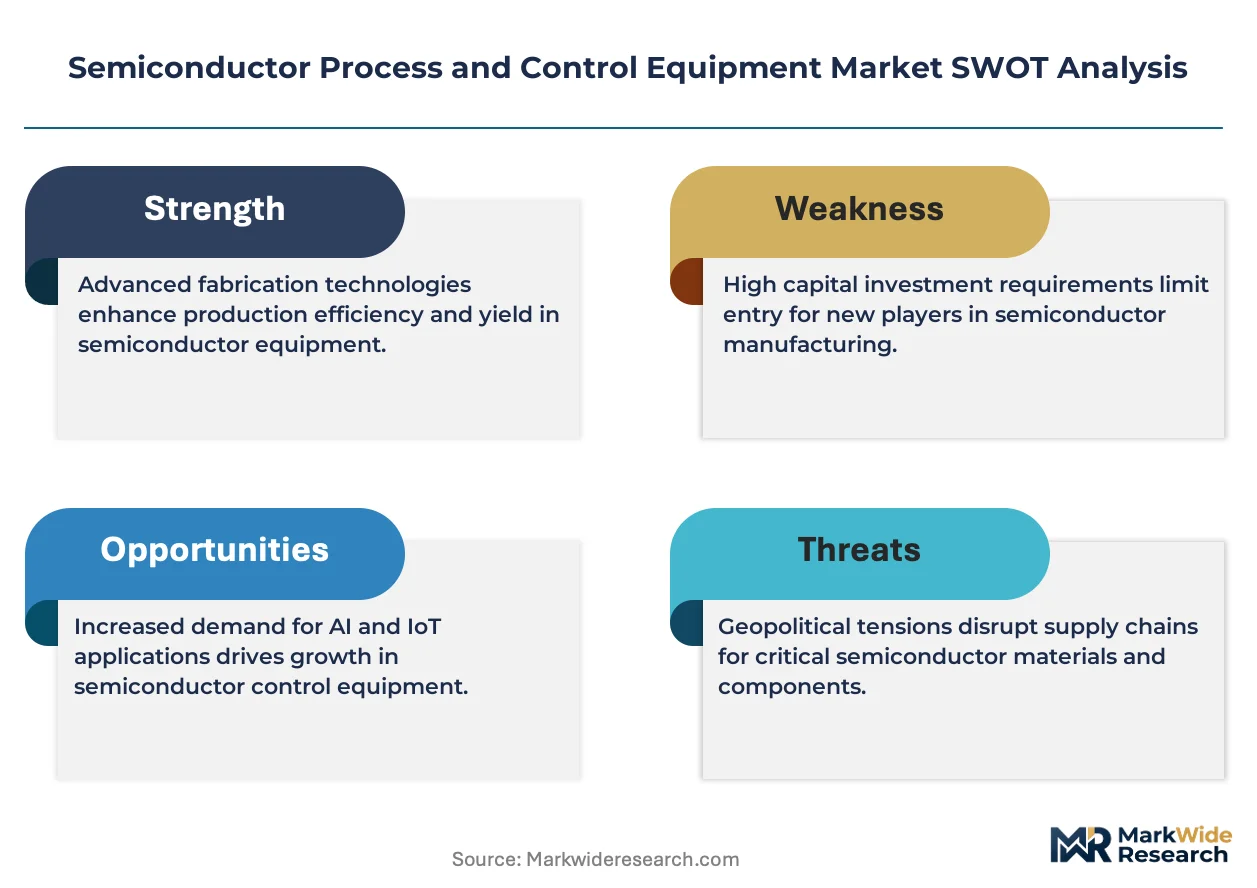
- Government Subsidies:National industrial policies, including the US CHIPS Act and the European Chips Act, provide direct financial incentives for building new fabrication plants, which directly translates into large-scale orders for process and control equipment.
- Automotive Semiconductor Content:The rapid expansion of advanced driver-assistance systems (ADAS) and vehicle electrification is creating sustained demand for mature-node and power semiconductor manufacturing equipment, diversifying the market beyond leading-edge logic.
Market Restraints
- Extreme Capital Cost:The immense price of next-generation equipment, particularly Extreme Ultraviolet (EUV) photolithography systems, creates a significant financial barrier to entry and expansion, concentrating manufacturing capability among a few top-tier companies.
- Supply Chain Bottlenecks:The supply of critical subsystems and materials, such as high-precision lenses, vacuum components, and high-purity quartzware, is concentrated in a few specialized suppliers, creating vulnerabilities and long lead times.
- Physical Scaling Limits:As fabrication approaches atomic limits, manufacturers face immense technical challenges related to quantum tunneling effects and stochastic variations, increasing process complexity and R&D costs for new equipment generations.
Strategic Opportunities
- Emerging Semiconductor Hubs:National initiatives in countries like India to establish domestic semiconductor ecosystems present a significant greenfield opportunity for equipment vendors to supply new fabrication facilities.
- Compound Semiconductors:The growing market for power and RF devices based on materials like Gallium Nitride (GaN) and Silicon Carbide (SiC) requires specialized epitaxy, ion implantation, and etching tools, opening a new equipment vertical.
- Process Control Software:Developing advanced analytics and AI-driven software platforms that integrate with metrology and inspection tools offers a high-margin opportunity to improve fab yield and productivity through data-driven process optimization.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of process engineers and field service technicians with the skills to install, calibrate, and maintain highly complex EUV, deposition, and etch systems constrains industry growth.
- Regulatory and Trade Complexity:Equipment manufacturers must navigate a complex web of export controls, technology transfer restrictions, and differing chemical regulations like the EU's F-Gas Regulation, which impacts global operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Process and Control Equipment Market |
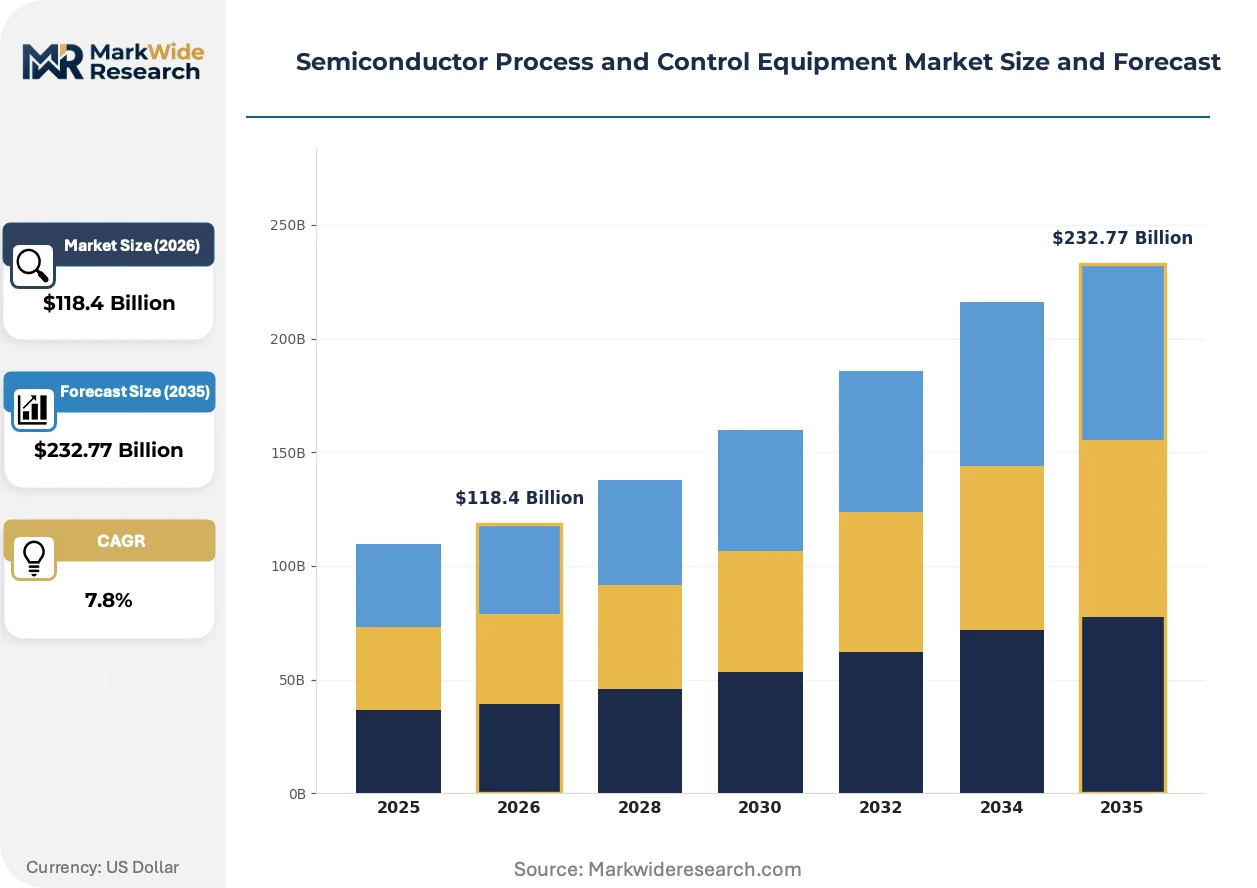
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $232.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photolithography Systems, Etching Equipment, Deposition Tools, Inspection Devices, Cleaning Systems Technology: Atomic Layer Deposition, Chemical Vapor Deposition, Plasma Etching, Electron Beam Lithography, Ion Implantation Application: Integrated Circuits, Power Devices, MEMS Fabrication, LED Manufacturing, Photovoltaic Cells End User: Semiconductor Fabricators, Foundries, Wafer Manufacturers, OSAT Providers, Equipment OEMs |
| Companies Covered | Applied Materials, ASML, Lam Research, Tokyo Electron, KLA, SCREEN Semiconductor Solutions, Hitachi, Lasertec, Nikon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Process and Control Equipment Market Strategic Shifts & Innovations
The market is defined by a strategic pivot from monolithic scaling towards heterogeneous integration. This evolution requires a corresponding shift in equipment capabilities, moving beyond front-end transistor creation to encompass advanced packaging and interconnect technologies that define final device performance.
Advanced packaging, including 2.5D and 3D stacking, allows for the integration of multiple specialized chiplets into a single, powerful system-in-package. Data center and AI hardware developers are rapidly adopting this method to overcome the performance plateaus of traditional monolithic chips. This trend is decentralizing the equipment focus from purely front-end lithography to also include critical back-end-of-line bonding, dicing, and interconnect tools.
The European Union's F-Gas Regulation imposes strict lifecycle controls on certain fluorinated gases used extensively in plasma etching processes for semiconductor manufacturing. This directive is forcing equipment makers to research and qualify alternative etchant chemistries that have a lower global warming potential. The dry etch equipment segment is most affected, with vendors now engineering systems optimized for these new, compliant gas mixtures to ensure market access.
A move toward co-optimized process development is altering how foundries and integrated device manufacturers select new equipment. Instead of purchasing standalone tools, fabs increasingly engage equipment vendors early in the R&D phase to jointly develop entire process flows for a specific technology node. This deep partnership model is most prominent in Taiwan and South Korea for developing leading-edge logic and memory technologies.
Semiconductor Process and Control Equipment Market Segmentation
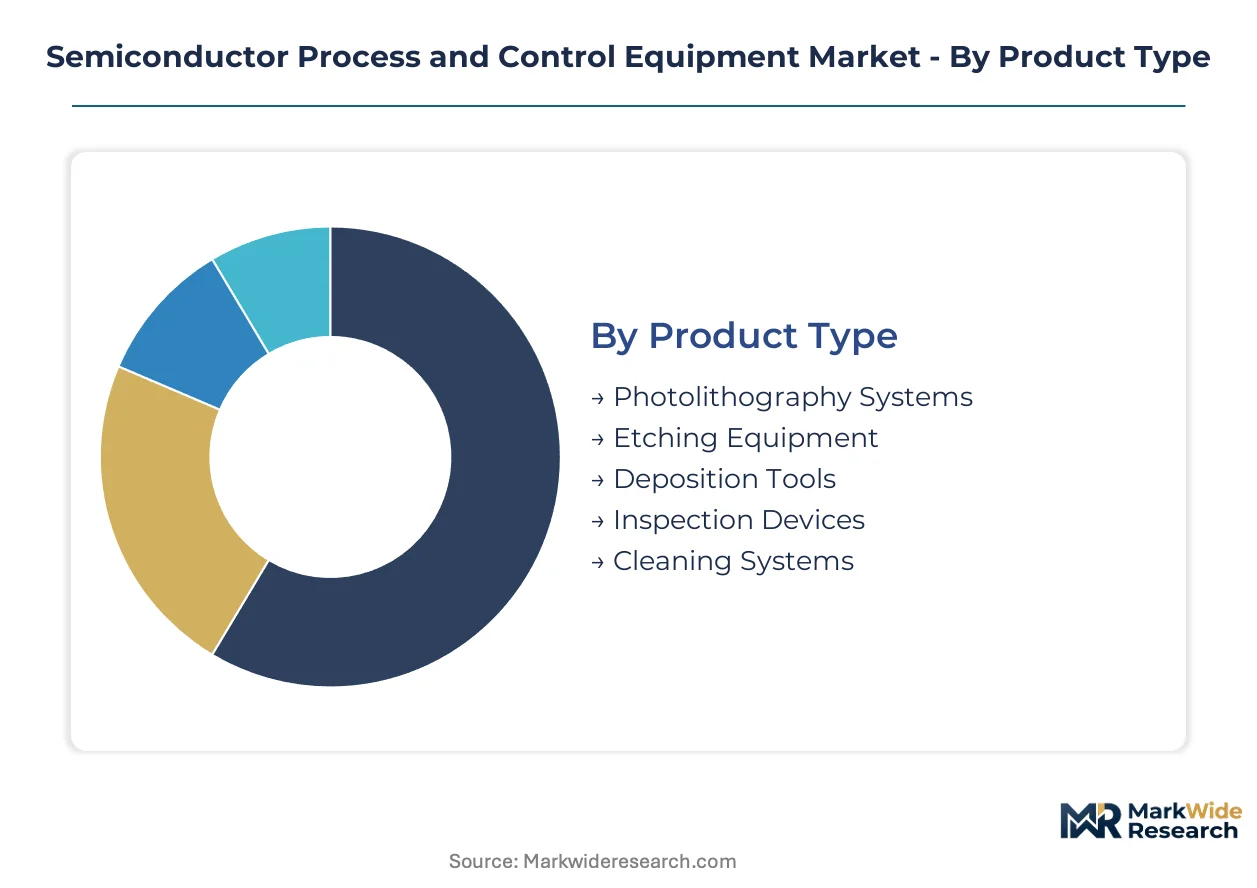
Understanding the Semiconductor Process and Control Equipment Market through segmentation offers critical insights into the diverse technological requirements and strategic investment priorities within the industry. Each segment reflects distinct challenges and opportunities, driven by evolving device architectures and manufacturing demands. This granular analysis helps identify areas of concentrated capital expenditure and emerging growth vectors across the complex semiconductor value chain.
Product Type:
Equipment procurement decisions often hinge on the specific manufacturing step requiring advanced tools, guiding choices across distinct product types.
- Photolithography Systems:These highly complex machines use light to transfer circuit patterns onto silicon wafers, with Extreme Ultraviolet (EUV) technology enabling the smallest feature sizes. Demand concentrates in Taiwan and South Korea for leading-edge logic and memory production, driving investment in sub-3nm process nodes.
- Etching Equipment:This category includes tools that selectively remove material from the wafer surface to create circuit patterns, utilizing plasma or chemical processes. Significant demand arises from 3D NAND and advanced logic fabrication, requiring intricate vertical structures and gate-all-around (GAA) transistor architectures.
- Deposition Tools:These systems apply thin layers of various materials onto silicon wafers through processes like atomic layer deposition and chemical vapor deposition.
- Inspection Devices:KLA leads this segment, providing critical metrology and inspection solutions to ensure process quality and maximize manufacturing yield.
- Cleaning Systems:These essential tools remove contaminants and residues from wafers between processing steps, crucial for preventing defects and ensuring device reliability.
Volume sits with Etching Equipment; growth tilts toward Photolithography Systems.
Technology:
The specific process technology required to achieve desired device characteristics drives selection among diverse fabrication methods.
- Atomic Layer Deposition:This precision technique creates ultra-thin, highly conformal films by depositing material one atomic layer at a time, essential for complex 3D structures. This technology is expanding most quickly due to its necessity for gate-all-around (GAA) transistor architectures and advanced memory devices.
- Plasma Etching:Plasma etching utilizes reactive gases to anisotropically remove material, enabling the creation of high-aspect-ratio features and intricate circuit patterns. Advanced logic and 3D NAND fabrication heavily rely on precise plasma etching for vertical integration and critical dimension control.
- Chemical Vapor Deposition:This technology forms thin films via chemical reactions on the wafer surface, used for dielectric layers, conductors, and semiconductors.
- Electron Beam Lithography:Used primarily for mask making and specialized high-resolution patterning, electron beam lithography offers unparalleled precision for research and development.
- Ion Implantation:This process precisely dopes semiconductor materials with impurities to alter their electrical properties, forming transistors and other device elements.
Atomic Layer Deposition is expanding most quickly due to its necessity for gate-all-around architectures.
Application:
Semiconductor equipment serves distinct fabrication needs across various end-product applications, influencing tool design and specification.
- Integrated Circuits:This segment encompasses the manufacturing of logic, memory, and microprocessors, forming the core of computing and electronic devices. Demand is concentrated from AI hardware developers and data center operators, requiring advanced packaging and high-performance chips.
- Power Devices:These components manage and convert electrical power, vital for efficient energy use in a wide range of systems. The market for power devices benefits from the rapid expansion of automotive electrification and industrial power management solutions.
- MEMS Fabrication:This application produces miniature mechanical and electrical devices for sensors, actuators, and microfluidic systems.
- LED Manufacturing:Specialized deposition and etching tools support the production of light-emitting diodes for displays, lighting, and optoelectronic components.
- Photovoltaic Cells:Equipment in this segment supports the production of solar cells, crucial for renewable energy generation and sustainable power solutions.
The primary volume driver comes from Integrated Circuits, while Power Devices represents a key growth opportunity.
End User:
The scale and type of manufacturing operations dictate equipment purchasing patterns among diverse end-user segments.
- Semiconductor Fabricators:These are Integrated Device Manufacturers (IDMs) like Intel and Samsung, which design, manufacture, and sell their own chips. They drive significant capital expenditure in leading-edge logic and memory production, particularly in Taiwan and South Korea.
- Foundries:Companies such as TSMC and GlobalFoundries specialize in manufacturing chips designed by other companies, providing fabrication services. Foundries represent a major procurement force for sub-3nm process nodes and advanced manufacturing systems.
- Wafer Manufacturers:These companies produce the foundational silicon substrates upon which integrated circuits are ultimately built.
- OSAT Providers:Outsourced Semiconductor Assembly and Test providers offer post-fabrication services, including packaging, assembly, and final testing of chips.
- Equipment OEMs:These original equipment manufacturers purchase components and subsystems for integration into their own highly specialized semiconductor manufacturing tools.
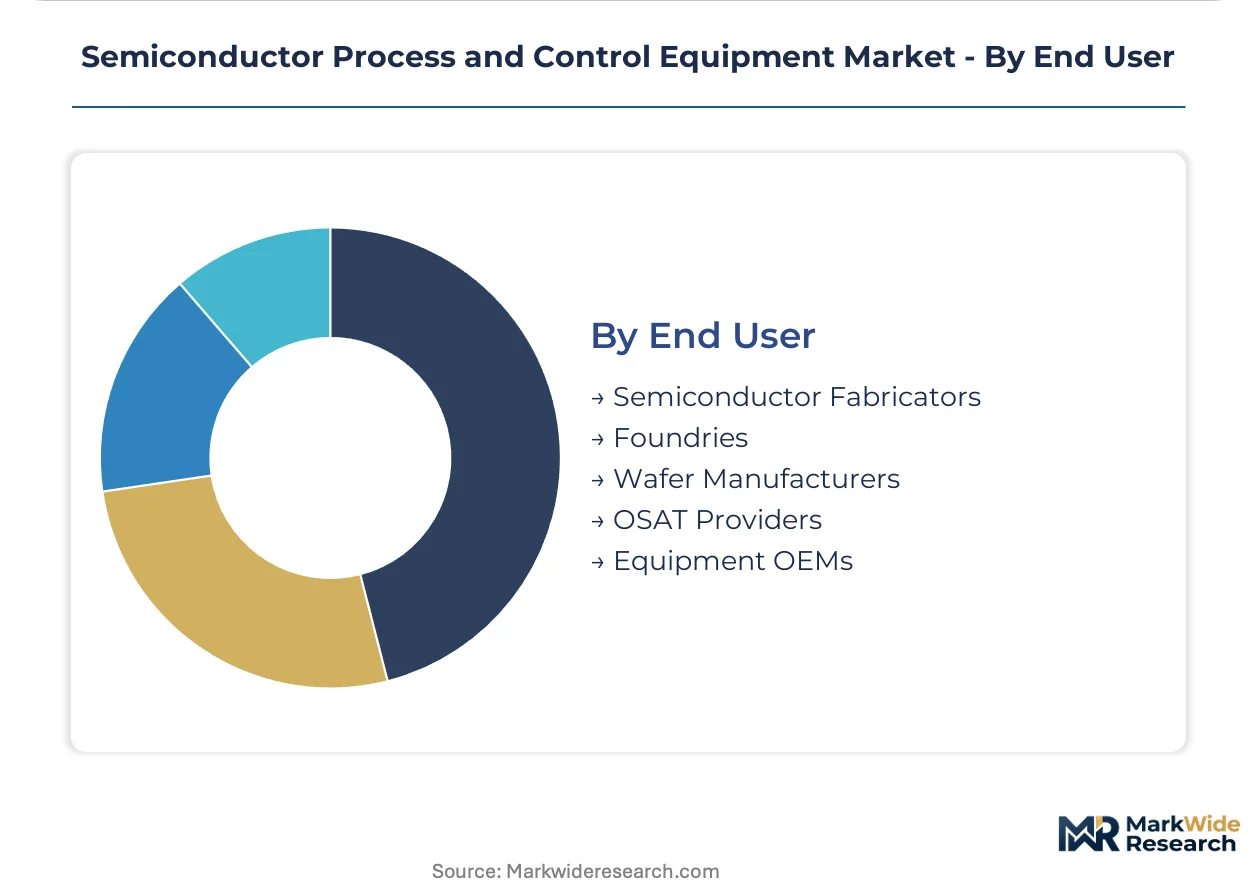
Demand from Foundries underpins market stability, with Semiconductor Fabricators showing significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The establishment of specialized industrial parks and tax-incentive zones, such as those promoted by the US CHIPS Act, drives significant regional concentration in semiconductor equipment demand. These strategic initiatives foster the development of advanced fabrication facilities, directly translating into substantial procurement of process and control machinery. Leading-edge manufacturing hubs in Asia and emerging centers in Europe and North America define the global market landscape.
Taiwan
Taiwan's robust foundry ecosystem, led by TSMC, necessitates continuous investment in advanced photolithography and etching equipment for sub-3nm process nodes. Government industrial policies prioritize semiconductor manufacturing, providing incentives for technology upgrades. Hsinchu Science Park remains a global epicenter for leading-edge chip production, attracting substantial capital expenditure.
South Korea
South Korea's dominance in memory and advanced logic fabrication sustains high demand for deposition and inspection tools. The Ministry of Trade, Industry and Energy supports R&D and manufacturing incentives. The Gyeonggi Province concentrates extensive semiconductor production facilities and associated equipment procurement.
United States
Domestic fab construction, spurred by the US CHIPS Act, is creating new demand for a full spectrum of process and control equipment. This federal legislation provides substantial subsidies for onshore manufacturing. Arizona and New York are emerging as critical hubs for new fabrication plants, drawing significant investment.
Germany
German initiatives, aligned with the European Chips Act, aim to strengthen the region's semiconductor manufacturing capabilities, increasing equipment procurement. The EU's F-Gas Regulation influences equipment design by requiring compliant chemical usage. Dresden's "Silicon Saxony" cluster is expanding its fabrication capacity, attracting investment.
India
India's national PLI scheme for semiconductors is attracting significant investment for establishing domestic fabrication facilities and assembly units. This policy provides financial incentives for setting up manufacturing operations. Gujarat is positioning itself as a primary hub for new semiconductor projects, creating greenfield opportunities.
Semiconductor Process and Control Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the semiconductor process and control equipment market. The market structure exhibits a high degree of consolidation in critical technology areas like photolithography, while other segments like cleaning systems are more fragmented. Strategic archetypes include technology leaders driving innovation, diversified equipment providers offering broad solutions, and niche specialists focusing on specific process steps. Companies pursue competitive advantage through capacity expansion and technology partnerships.
Specialists in critical process steps exemplify the market's technological intensity. ASML, a Netherlands-based manufacturer, anchors the extreme ultraviolet photolithography segment with its proprietary technology, representing a high-barrier-to-entry archetype. Lam Research Corporation, a US-based entity, occupies a position as a leader in advanced etching and deposition solutions, crucial for complex 3D architectures and next-generation memory. KLA Corporation, another US-based firm, sits within the process control and inspection market, providing essential yield management solutions to global fabricators for complex manufacturing steps.
| Leading Market Players |
|---|
| Applied Materials |
| ASML |
| Lam Research |
| Tokyo Electron |
| KLA |
| SCREEN Semiconductor Solutions |
| Hitachi |
| Lasertec |
| Nikon |
Cost & Logistics Intelligence
The EU's F-Gas Regulation gates both qualified equipment supply and premium-tier pricing access for compliant plasma etching systems. This mandate forces equipment makers to invest in new chemistries, influencing manufacturing costs and market availability.
Pricing Analysis
Premium pricing for semiconductor equipment reflects short lead times and advanced customization, while standard tools may see discounts on bulk orders. Contract-based long-term offtake agreements dominate for leading-edge systems like EUV. Price differentiation stems from technology complexity and after-sales service bundles. Cost compression in mature-node equipment intensifies due to increased competition, making integrated device manufacturers highly price-sensitive for these tools.
Supply Chain Analysis
Single-source vulnerability sits with specialized suppliers for critical subsystems like high-precision lenses from Japan and vacuum components from Europe. Geographic supply concentration for advanced equipment components and raw materials, including high-purity quartzware, centers on Japan, Germany, and the Netherlands. Regulatory restrictions, such as export controls, present a structural risk to global equipment flows. Distribution runs through direct sales channels to major foundries and IDMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cost-of-compliance story, where the European Union's F-Gas Regulation creates a significant barrier-to-entry moat for equipment manufacturers able to deliver compliant etching systems. Adhering to strict chemical usage guidelines requires substantial R&D investment.
For Market Incumbents:Deepen strategic partnerships with leading foundries in Taiwan and South Korea to co-develop next-generation process flows for sub-3nm nodes. Invest significantly in R&D for alternative etchant chemistries to mitigate the threat of evolving environmental regulations. Expand capacity for critical components in diversified geographies to counter supply chain bottlenecks.
For New Entrants and Emerging Players:Digital platforms offering advanced process control software and AI-driven analytics represent a significant white-space opportunity. Target specialized niches like compound semiconductor equipment or advanced packaging tools where incumbents may be slower to adapt. A go-to-market angle focused on yield optimization and predictive maintenance offers compelling value. The most penetrable segment lies in providing software solutions that integrate with existing fab infrastructure.
For Investors and Strategic Acquirers:Persistent talent scarcity across process engineering roles is the leading indicator that specialized human capital will command premium valuations long-term. This market offers viability over a five-to-ten-year window, driven by continuous node transitions. Target acquisition archetypes include niche specialists in atomic layer deposition or advanced metrology. Increased government subsidies for domestic fab construction signals sustained capital expenditure.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production throughput for critical tools to meet demand from new fabrication plants in the United States. |
| Technology Licensing | Secures access to proprietary EUV or GAA process expertise, accelerating development of advanced manufacturing systems. |
| R&D Investment in Green Chemistries | Ensures compliance with environmental regulations like the EU's F-Gas Regulation, maintaining market access in Europe. |
| Strategic Acquisition of Metrology Specialists | Strengthens process control capabilities, enhancing yield management solutions for complex 3D architectures. |
| Partnerships with AI Hardware Developers | Aligns equipment design with future performance requirements for advanced packaging and high-performance computing devices. |
Research Approach
Multi-period observation of capital expenditure trends and process node transitions anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with process engineers, fab managers, equipment procurement specialists, and R&D directors. Secondary validation drew from corporate financial reports, industry association publications, patent databases, and government technology roadmaps. This approach ensured robust bottom-up and top-down triangulation.
An input-output matrix framing guided the quantitative modeling across the analysis window. This framework disaggregated the market by product type, technology, application, end user, and process node complexity. Compound annual growth rates were derived from historical data and projected forward based on anticipated technological advancements and market dynamics. Fab utilization rates and R&D spending on new materials served as key forecast inputs.
The model holds under current geopolitical stability and technological development trajectories; deviation in trade policies or unforeseen scientific breakthroughs would shift projections. Forecasts reflect documented assumptions regarding industry investment cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market