
 Global Wafer Processing and Assembly Equipment Market | 2026-2036
Global Wafer Processing and Assembly Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wafer Processing and Assembly Equipment Market Foresight
A shift from single-source lithography dependency toward multi-source qualification for deposition and etching tools is broadening procurement options across leading fabs. Applied Materials Inc. leverages its materials engineering breadth to anchor etch and deposition portfolios. Tokyo Electron Limited competes through co-development partnerships with memory makers. ASML Holding Semiconductor Company dominates extreme ultraviolet lithography, a position it sustains through source technology control.
Wafer processing and assembly equipment encompasses machinery that modifies, deposits, patterns, inspects, and interconnects semiconductor substrates at node geometries now reaching angstrom-scale precision, with plasma etch uniformity specifications tighter than one percent wafer-to-wafer. Its primary commercial purpose is enabling yield-compliant volume manufacturing of logic, memory, and compound semiconductor devices. Lithography tools command the largest capital allocation pools among equipment types, while bonding equipment for 3D integration represents the fastest structural expansion. Foundries drive the highest absolute spending among end users, though contract manufacturers are gaining share as outsourced advanced packaging proliferates.
FDA device regulations for diagnostic chips, EU REACH chemical restrictions on process chemistries, and Japan METI semiconductor subsidies collectively shape equipment demand through compliance cost and localization incentives. EPA emissions rules in the United States add permitting complexity for new fab construction, extending equipment delivery timelines. Stakeholders must monitor which regulatory jurisdictions accelerate domestic fab buildouts versus those imposing stricter chemical handling protocols.
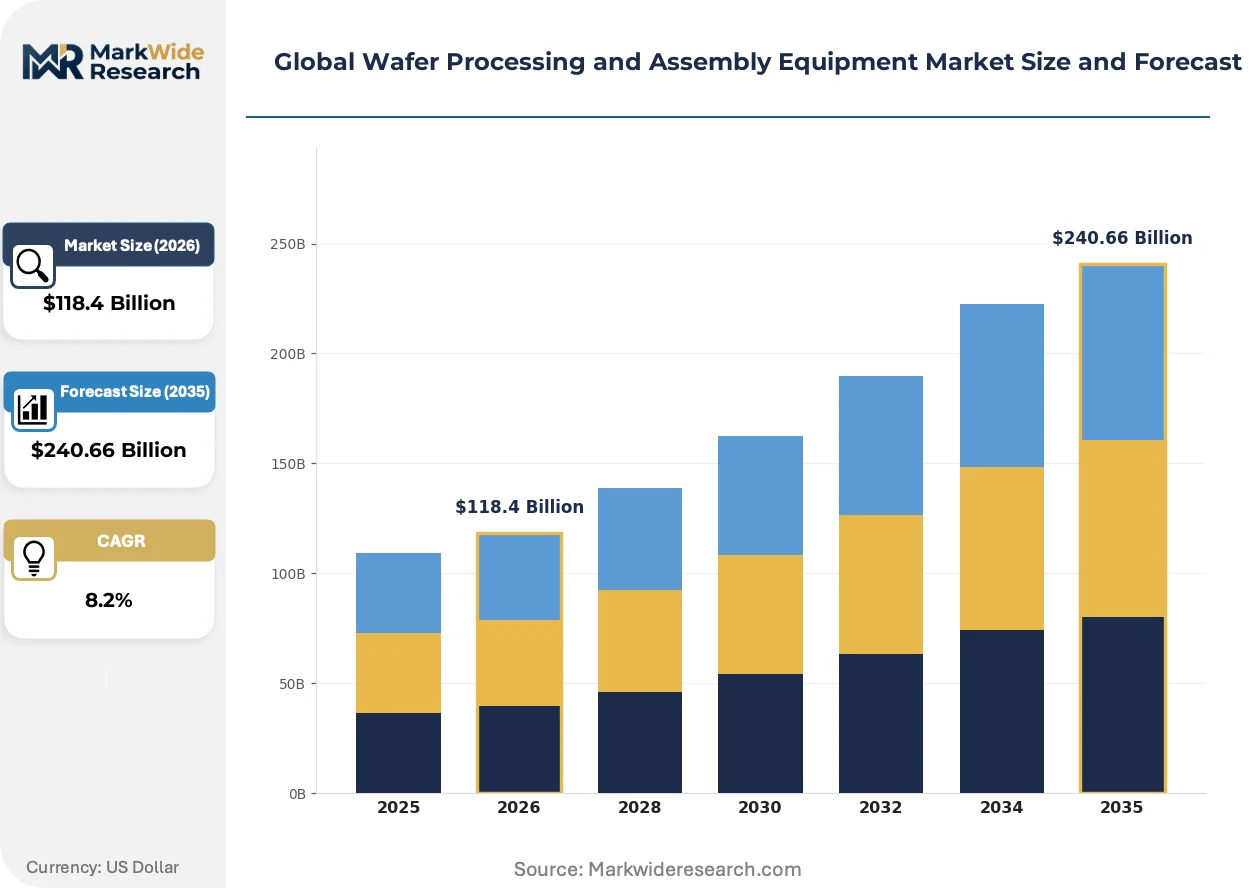
Market Dynamics
Advanced packaging for AI accelerators is compressing node migration timelines and concentrating capital allocation into lithography and bonding tool categories. EU REACH chemical restrictions and Japan METI semiconductor subsidies are simultaneously redirecting supply chain decisions toward compliant chemistries and domestic fab buildouts.
Growth Catalysts
- AI accelerator packaging demand:High-bandwidth memory integration requirements are pulling investment into 3D bonding and hybrid bonding equipment across leading foundries.
- Japan METI subsidies:Domestic semiconductor production incentives are accelerating equipment procurement for Kagoshima and Kumamoto fab clusters.
- EUV lithography node extension:High-NA EUV tooling roadmaps are sustaining capital intensity at logic foundries through angstrom-scale patterning requirements.
Market Restraints
- Helium supply concentration:Cryogenic cooling dependencies for superconducting magnets in EUV systems expose tool availability to Qatar and US federal reserve allocation decisions.
- Fluorinated gas restrictions:EU F-Gas Regulation phase-down mandates are constraining etch process chemistry selection and requiring abatement retrofit investments.
- Single-source lithography dependency:Extreme ultraviolet source technology control limits multi-vendor qualification options for leading-edge logic production.
Strategic Opportunities
- India semiconductor manufacturing:Gujarat and Assam fab project approvals under the PLI scheme are creating greenfield equipment installation demand for mature-node processing tools.
- Hybrid bonding adoption:Chiplet-based processor architectures are converging wafer-to-wafer and die-to-wafer bonding technologies into unified platform roadmaps.
- US CHIPS Act localization:Arizona and Texas fab construction timelines are compressing delivery windows for domestic tool qualification and service infrastructure.
Industry Challenges
- Plasma etch process engineering talent:Atomic-scale uniformity specifications require specialized expertise that outpaces university pipeline output in Taiwan and South Korea.
- Multi-patterning integration complexity:Self-aligned quadruple patterning sequences demand cross-functional coordination between deposition, lithography, and etch modules that strains legacy fab organizational structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wafer Processing and Assembly Equipment Market |
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $240.66 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Etching Machines, Deposition Systems, Lithography Tools, Bonding Equipment, Inspection Systems Technology: Chemical Vapor Deposition, Atomic Layer Deposition, Plasma Etching, Electroplating, Thermal Oxidation Application: Power Devices, MEMS, Optoelectronics, Sensors, RF Components End User: Foundries, Integrated Device Manufacturers, Contract Manufacturers, Research Institutes |
| Companies Covered | Applied Materials Inc., ASML Holding Semiconductor Company, Tokyo Electron Limited, Lam Research Corporation, KLA Corporation, DISCO Corporation, Kulicke and Soffa Industries Inc., BE Semiconductor Industries N.V., Screen Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wafer Processing and Assembly Equipment Market Shifts & Advancements
Equipment architectures are adapting to angstrom-scale precision requirements while regulatory jurisdictions compete to anchor domestic manufacturing capacity through subsidy and compliance frameworks.
Hybrid bonding is consolidating advanced packaging process flows by eliminating wirebond and flip-chip interposers in high-performance compute devices. Memory makers in South Korea are adopting wafer-to-wafer bonding for HBM4 stacking at accelerated qualification paces. This technology is consolidating capital allocation away from traditional die-attach equipment categories toward precision alignment and plasma activation tools.
EU REACH chemical restrictions are forcing reformulation of photoresist solvents and cleaning chemistries across European tool installed bases. Industrial consequences include extended process qualification timelines and supplier re-qualification costs for fluorinated polymer components. Deposition equipment segments are responding through closed-loop chemical delivery systems that reduce ambient exposure and waste generation.
Foundry procurement patterns are compressing equipment evaluation cycles as node transition windows narrow below twenty-four months. Tool vendors are displacing traditional specification-based bidding with co-development partnerships that embed field engineering teams within customer fabs. This behavioral shift is most visible in Taiwan's Hsinchu Science Park cluster where Applied Materials and Tokyo Electron maintain resident technical staff.
Global Wafer Processing and Assembly Equipment Market Segmentation
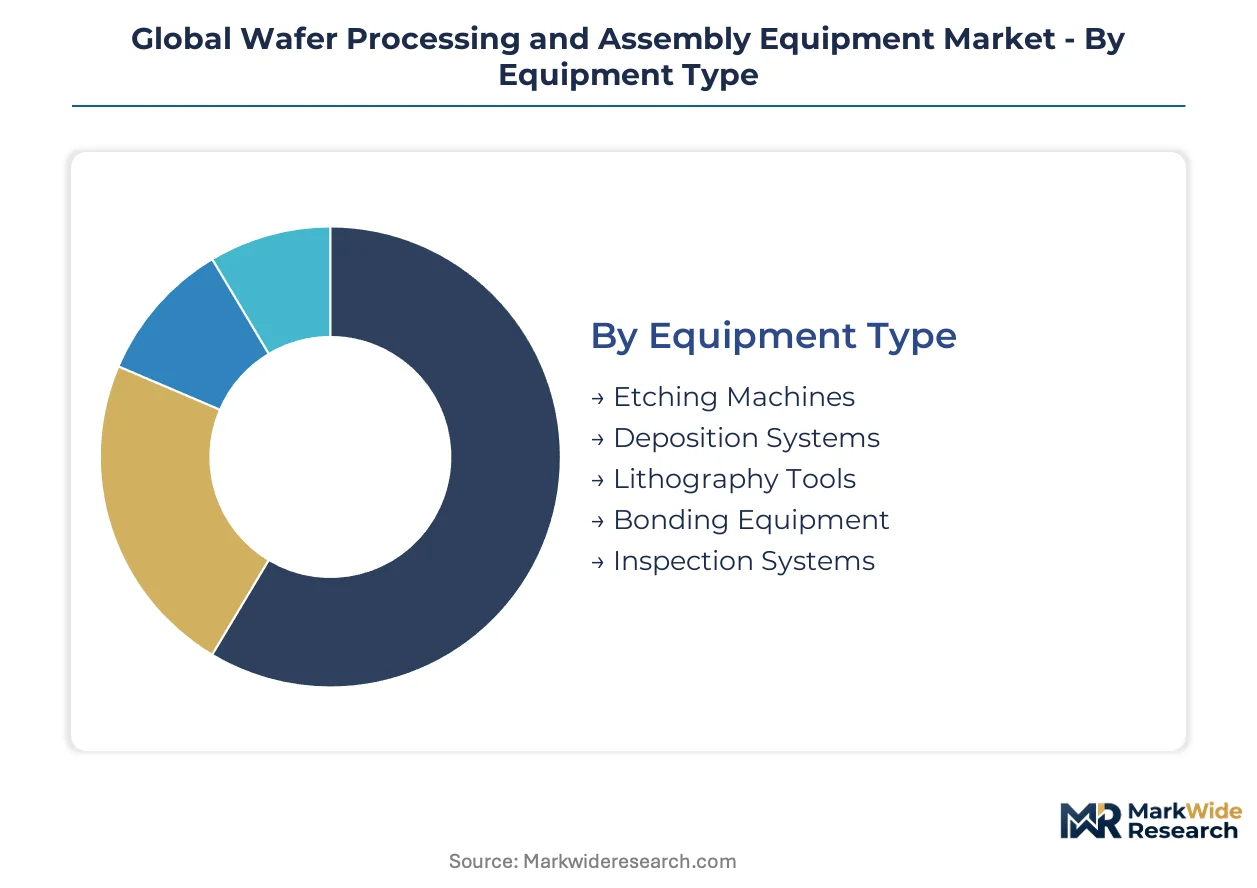
Equipment segmentation in wafer processing reveals how capital allocation concentrates around lithography and bonding tools for AI accelerator packaging, while regulatory compliance requirements vary sharply across deposition chemistries and inspection protocols. Understanding these divisions enables procurement teams to align vendor qualification timelines with specific node migration roadmaps.
Equipment Type:
EPA emissions rules govern new fab construction permitting for etching and deposition systems, while FDA device regulations apply to inspection systems used in diagnostic chip manufacturing.
- Lithography Tools:Extreme ultraviolet systems pattern angstrom-scale features using superconducting magnet arrays requiring helium cryogenic cooling. Taiwan's foundry cluster in Hsinchu Science Park drives the highest absolute capital allocation for high-NA EUV roadmaps, constrained by single-source dependency on source technology control.
- Bonding Equipment:Wafer-to-wafer and die-to-wafer platforms enable 3D integration for high-bandwidth memory stacking. South Korea's memory complex accelerates qualification paces for hybrid bonding tools, displacing traditional die-attach equipment categories.
- Etching Machines:Plasma etch systems achieve sub-one-percent wafer-to-wafer uniformity for atomic-scale features, facing fluorinated gas restrictions under EU F-Gas Regulation.
- Deposition Systems:Chemical and physical vapor deposition tools deposit conformal films at shrinking thickness tolerances, requiring closed-loop chemical delivery for REACH compliance.
- Inspection Systems:Optical and electron-beam platforms detect yield-critical defects at increasing throughput requirements for angstrom-class nodes.
Leading the category by volume: Lithography Tools. Growing fastest: Bonding Equipment.
Technology:
Process technology selection determines which regulatory jurisdictions impose chemical handling protocols versus equipment safety certifications.
- Atomic Layer Deposition:Self-limiting surface reactions enable angstrom-level thickness control for high-aspect-ratio structures. Japan METI subsidies accelerate tool procurement for Kumamoto fab clusters, targeting conformal film requirements in logic and memory stacks.
- Plasma Etching:Reactive ion and atomic layer etch modalities pattern features below ten nanometers with atomic-scale profile control. Taiwan's foundry ecosystem concentrates demand for advanced etch uniformity, constrained by plasma process engineering talent scarcity.
- Chemical Vapor Deposition:Low-pressure and plasma-enhanced variants deposit dielectric and conductive films across batch and single-wafer configurations.
- Electroplating:Through-silicon via and redistribution layer metallization for 3D packaging applications.
- Thermal Oxidation:High-temperature silicon dioxide growth for gate dielectric and isolation structures in mature-node production.
Dominating capital spend: Atomic Layer Deposition. Expanding most quickly: Plasma Etching.
Application:
Application segments align with end-use device regulations spanning automotive qualification standards to medical device FDA pathways.
- Power Devices:Silicon carbide and gallium nitride processing for electric vehicle traction inverters and renewable energy converters. India's Gujarat fab projects under the PLI scheme create greenfield demand for mature-node power device equipment.
- MEMS:Microelectromechanical systems for automotive sensors and consumer motion devices require specialized deep reactive ion etching and wafer-level packaging tools.
- Optoelectronics:Laser and photodetector fabrication for datacom and sensing applications.
- Sensors:Environmental and biometric sensor processing with stringent automotive reliability qualifications.
- RF Components:Filter and amplifier devices for 5G infrastructure and mobile handsets.
Highest equipment intensity: Power Devices. Fastest qualification timelines: MEMS.
End User:
End user categories reflect divergent procurement patterns, from co-development partnerships at leading foundries to specification-based bidding at research institutes.
- Foundries:Pure-play logic and memory manufacturers drive the highest absolute equipment spending with compressed evaluation cycles below twenty-four months. Taiwan's TSMC and South Korea's Samsung anchor global demand for leading-edge lithography and bonding tools.
- Integrated Device Manufacturers:Captive logic and memory producers with in-house packaging capabilities, including Texas Instruments and Intel's internal foundry operations.
- Contract Manufacturers:Outsourced assembly and test providers gaining share as advanced packaging proliferates, requiring precision alignment and plasma activation tools.
- Research Institutes:University and national laboratory users with extended qualification timelines and specialized process development requirements.
Commanding largest capital pools: Foundries. Gaining share fastest: Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium reserves in Qatar and the US federal strategic stockpile anchor cryogenic cooling supply for EUV lithography systems worldwide. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek complex concentrate foundry and memory fabrication capacity. Japan's Kumamoto and Kagoshima clusters leverage METI subsidies for domestic equipment procurement.
United States
CHIPS Act incentives accelerate Arizona and Texas fab construction timelines, compressing delivery windows for domestic tool qualification. EPA emissions rules add permitting complexity for new etching and deposition system installations. Intel's Oregon and Arizona operations anchor leading-edge logic production, driving capital allocation into high-NA EUV roadmaps.
Taiwan
TSMC's Hsinchu Science Park operations drive the highest absolute lithography and bonding equipment spending globally. The island's foundry ecosystem maintains resident technical staff from Applied Materials and Tokyo Electron through co-development partnerships. Compressed node transition windows below twenty-four months strain legacy fab organizational structures.
South Korea
Samsung and SK Hynix anchor Pyeongtaek and Icheon memory complexes, accelerating hybrid bonding qualification for HBM4 stacking. The country's plasma etch engineering talent scarcity constrains atomic-scale uniformity specification achievement. Domestic equipment vendors face procurement preference in national security-sensitive process modules.
Japan
METI semiconductor subsidies redirect supply chain decisions toward Kagoshima and Kumamoto fab clusters, accelerating Tokyo Electron and Screen Holdings tool procurement. JIS standards govern equipment safety certifications for domestic installations. Kyushu Island's silicon island initiative concentrates mature-node and power device fabrication capacity.
India
PLI scheme approvals for Gujarat and Assam fab projects create greenfield demand for mature-node processing tools. BIS certification requirements extend equipment qualification timelines for first-time market entrants. The country's national semiconductor regulator coordinates with state governments on fab site infrastructure readiness.
Global Wafer Processing and Assembly Equipment Market Competitive Landscape
Co-development partnerships dominate the current landscape, displacing traditional specification-based bidding across leading foundries. The vendor base concentrates around lithography, etch, and deposition specialists with multi-decade customer relationships. Three archetypes define competitive positioning: integrated materials engineering platforms, lithography technology monopolists, and bonding equipment specialists. Strategic partnerships and geographic expansion constitute the dominant competitive moves, followed by portfolio diversification into adjacent process modules.
Among Dutch-origin lithography specialists, ASML Holding Semiconductor Company exemplifies technology control archetypes through extreme ultraviolet source dominance. Applied Materials Inc. and Tokyo Electron Limited occupy positions as integrated materials engineering platforms, anchoring etch and deposition portfolios through resident field engineering deployments. These three entities represent the tier that shapes procurement patterns through embedded technical collaboration rather than transactional equipment sales.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| ASML Holding Semiconductor Company |
| Tokyo Electron Limited |
| Lam Research Corporation |
| KLA Corporation |
| DISCO Corporation |
| Kulicke and Soffa Industries Inc. |
| BE Semiconductor Industries N.V. |
| Screen Holdings Co., Ltd. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates gate both qualified fluorinated chemistry supply and premium-tier etch tool pricing access, compressing margins for non-compliant vendors while rewarding abatement-equipped suppliers with pricing power at leading foundries.
Pricing Analysis
Field engineering residency and extended warranty coverage anchor the dominant pricing structure, with unbundled service contracts commanding premium tiers at Taiwan's foundry cluster. Price differentiation separates source-technology-integrated lithography systems from standard deposition tools, with certification under JIS and CE marking tiers further stratifying vendor access. Cost compression in mature-node equipment intensifies as India's PLI scheme attracts second-tier suppliers. Contract manufacturers exhibit highest price sensitivity due to capital constraints, while leading foundries prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with helium cryogenic cooling feedstock concentrated in Qatar and the US federal strategic reserve, exposing EUV tool availability to allocation decisions. Manufacturing concentration centers on Taiwan, South Korea, and Japan for lithography and bonding equipment, with critical component dependencies spanning superconducting magnets, precision optical assemblies, and fluorinated process gases. Tariff exposure on Japanese-sourced ceramics and German precision motion systems threatens delivery timelines. Distribution runs through direct field service organizations co-located at Hsinchu Science Park and Pyeongtaek complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid bonding adoption is displacing wirebond and flip-chip interposer technologies, compressing equipment replacement cycles as memory makers accelerate HBM4 stacking roadmaps.
For Market Incumbents: Hedge helium supply disruption through long-term offtake agreements with Qatar and US federal reserve allocation programs. Deepen backward integration into precision motion control subsystems to offset German ceramic tariff exposure. Prioritize closed-loop chemical delivery R&D to capture EU REACH-compliant replacement demand. For New Entrants and Emerging Players: India's contract manufacturers represent the most penetrable buyer archetype, with BIS certification gaps creating entry windows for mature-node deposition and etch tools. Target Gujarat fab projects with localized service infrastructure rather than specification-matched performance. Lead with compressed qualification timelines against established vendors' twenty-four-month cycles. For Investors and Strategic Acquirers: Tokyo Electron's Kumamoto procurement acceleration is the leading indicator that Japan METI subsidy disbursement velocity is tightening equipment delivery windows. Frame long-term viability around hybrid bonding platform consolidation over the next decade. Monitor plasma etch engineering talent scarcity as the signal for acquisition timing in South Korea and Taiwan.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership | Applied Materials embeds resident engineers at TSMC to compress etch module qualification cycles. |
| Geographic Manufacturing Footprint | ASML's Arizona service hub accelerates high-NA EUV installation timelines for Intel's fabs. |
| Technology Licensing | Tokyo Electron licenses atomic layer etch recipes to Samsung for HBM4 vertical channel formation. |
| Backward Integration | Lam Research acquires ceramic component supplier to secure fluorinated gas chamber materials. |
| Joint Venture | Screen Holdings partners with Kumamoto prefecture for REACH-compliant cleaning chemistry production. |
Research Methodology
Multi-period observation of equipment procurement cycles, node migration timelines, and subsidy disbursement velocities anchored the trend analysis, supplemented by interviews with fab operations directors, equipment procurement managers, plasma process engineering leads, and aftermarket service heads. Primary fieldwork drew from SEC 10-K filings, Japan METI subsidy announcements, EU ECHA regulatory updates, and Taiwan Hsinchu Science Park investment disclosures. Bottom-up equipment unit forecasts and top-down capital expenditure triangulation validated market sizing across the analysis window.
Input-output matrices mapped lithography tool shipments against foundry capex announcements, bonding equipment orders against HBM generation transitions, and etch system deployments against node geometry requirements. Segmentation dimensions spanned equipment type, process technology, end-use application, and regional fab cluster. CAGRs derived from equipment replacement cycle compression and subsidy-accelerated procurement timelines. Industry-specific inputs included helium allocation volumes and REACH compliance certification status.
Revisions become necessary when EU F-Gas Regulation phase-down schedules accelerate, Japan METI subsidy eligibility criteria tighten, or Qatar helium export quotas shift. Forecasts reflect documented assumptions regarding node migration pacing and subsidy disbursement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Dry Reactor Market