

High Current Ion Implanter Market Size, Share, and Industry Trends Forecast 2026-2036
High Current Ion Implanter Market Insights
A capital-intensity divergence between beamline specialists and plasma-based challengers is rotating competitive dynamics in equipment supply. Applied Materials leverages its installed base across 300mm foundry transitions to sustain service revenue density. Axcelis Technologies anchors North American supply security through its Purion platform dominance in power device implantation. Nissin Ion Equipment competes in Japanese captive fab networks where tool standardization reduces qualification cycles.
High current ion implanters accelerate dopant ions into semiconductor wafers at energies typically spanning 10 keV to 1 MeV and beam currents exceeding 10 mA, enabling precise junction formation for source-drain engineering in logic and memory devices. Beamline ion implantation occupies the dominant revenue position due to its established metrology compatibility and throughput economics at mature nodes. Multi-chamber ion implanters represent the fastest-growing product configuration as foundries integrate sequential implant steps to reduce wafer handling and contamination risk. Semiconductor fabrication absorbs the largest application share, though power device manufacturing deepens its implant intensity with silicon carbide substrate adoption.
SEMI S2 and S8 safety guidelines govern equipment architecture for ion implanter deployment in US and European fabs, while China's GB standards and NMPA-equivalent semiconductor equipment certifications shape import substitution timelines for domestic toolmakers. Japan's METI coordinates supply chain resilience programs that channel R&D subsidies toward ion source and beamline component localization. Stakeholders must monitor divergence between export control classifications for high-current implanters and foundry buildout schedules in non-aligned semiconductor manufacturing zones.
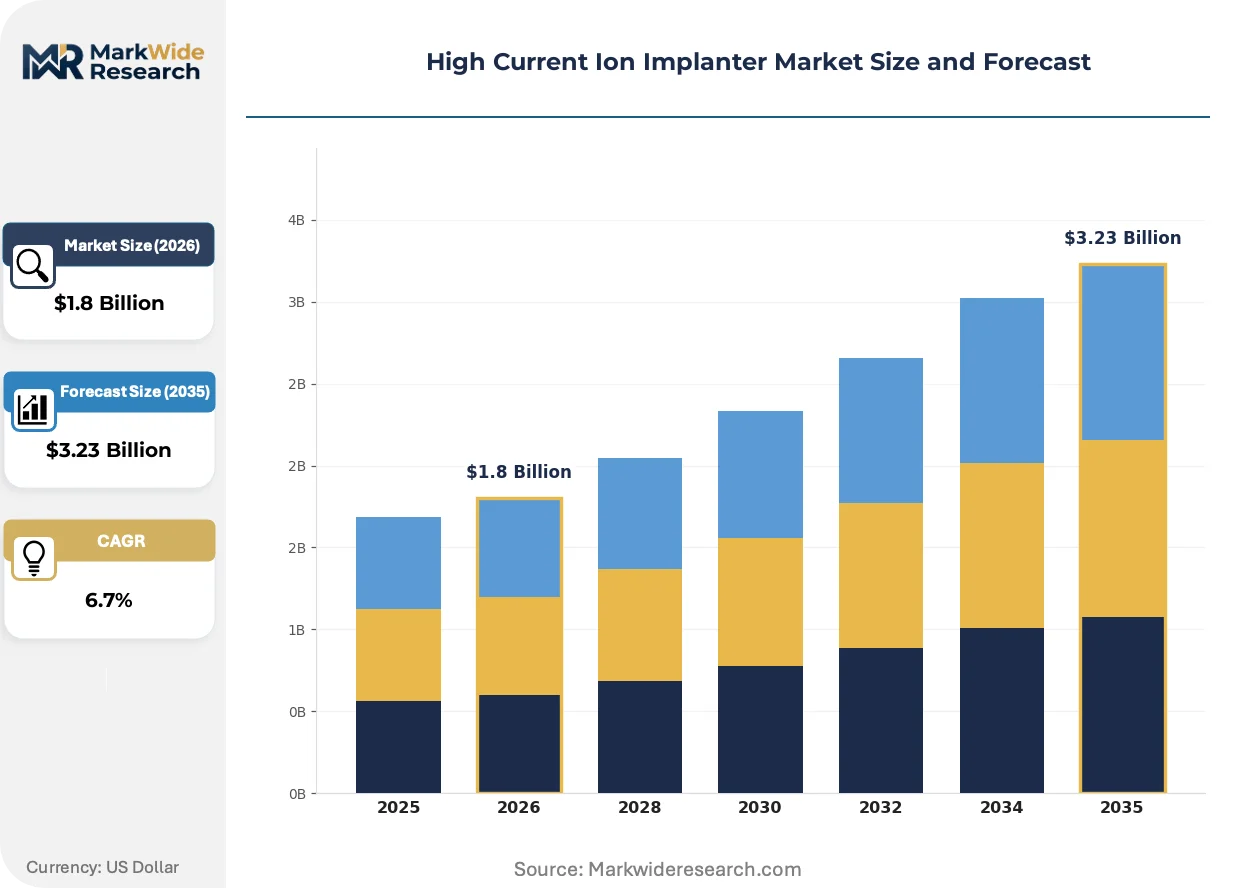
Market Dynamics
Beamline ion implantation technology is displacing legacy plasma doping approaches as semiconductor foundries pursue sub-7nm precision requirements, creating equipment refresh cycles that concentrate procurement among three East Asian fabrication clusters.
Growth Catalysts
- Silicon carbide substrate adoption:Power device manufacturers deepen implant intensity for electric vehicle inverters and renewable energy converters, expanding beam current requirements beyond traditional silicon applications.
- SEMI S2 and S8 safety guidelines:US and European fabs mandate standardized equipment architecture that accelerates qualification timelines for compliant tool vendors.
- Taiwan and South Korea foundry expansion:Leading-edge capacity additions for advanced logic nodes concentrate high-current implant procurement in East Asian fabrication clusters.
Market Restraints
- Tungsten filament supply concentration:Ion source component production clusters in Japanese and German specialty materials suppliers create single-source vulnerability for beamline system manufacturers.
- Export control classification friction:Divergence between US Commerce Department Entity List restrictions and foundry buildout schedules in non-aligned manufacturing zones delays equipment deployment.
- Plasma doping cost structure:Legacy ultra-low energy implant alternatives retain installed base economics for mature node production above 28nm, compressing beamline upgrade urgency.
Strategic Opportunities
- China domestic toolmaker qualification:GB standards and NMPA-equivalent semiconductor equipment certifications create import substitution timelines for local ion implanter development.
- Multi-chamber configuration convergence:Sequential implant step integration reduces wafer handling contamination risk while enabling throughput economics competitive with single-process tools.
- Japan METI supply chain resilience programs:R&D subsidies channel toward ion source and beamline component localization, creating captive supply opportunities for domestic equipment vendors.
Industry Challenges
- Electrostatic chuck thermal management specialization:High-current beam heating effects require materials science expertise that concentrates among veteran process engineers approaching retirement.
- SEMI S2 certification timeline compression:Safety guideline compliance documentation extends qualification cycles for new platform introductions, delaying revenue recognition.
- Legacy 200mm fab integration complexity:Beamline retrofits into existing cleanroom footprints encounter space constraints and vibration isolation requirements that demand custom engineering.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Current Ion Implanter Market Trends and Innovations
Equipment architecture is pivoting toward modularity and contamination control as foundries consolidate sequential process steps and regulators tighten safety documentation requirements.
Single-wafer high-current implanters with in-situ metrology integration are displacing batch processing configurations in advanced logic fabs. Memory manufacturers in South Korea and Taiwan adopt these platforms for 3D NAND string formation where junction depth uniformity dictates yield. The displacement compresses capital efficiency metrics for tool vendors while elevating service revenue attachment rates.
Japan's METI coordinates supply chain resilience programs that channel R&D subsidies toward ion source and beamline component localization. Equipment vendors must document domestic content ratios to qualify for procurement preferences in Japanese captive fab networks. This regulatory tailwind accelerates qualification cycles for locally manufactured subsystems while extending timelines for foreign component suppliers.
Foundry procurement teams unbundle after-sales service contracts from initial equipment purchases, creating standalone maintenance revenue streams that alter vendor cash flow profiles. Taiwan Semiconductor Manufacturing Company and Samsung Foundry negotiate multi-year service agreements separately from tool acquisitions. This behavioral shift concentrates in East Asian fabrication clusters where equipment utilization rates maximize service contract profitability.
High Current Ion Implanter Market Segmentation
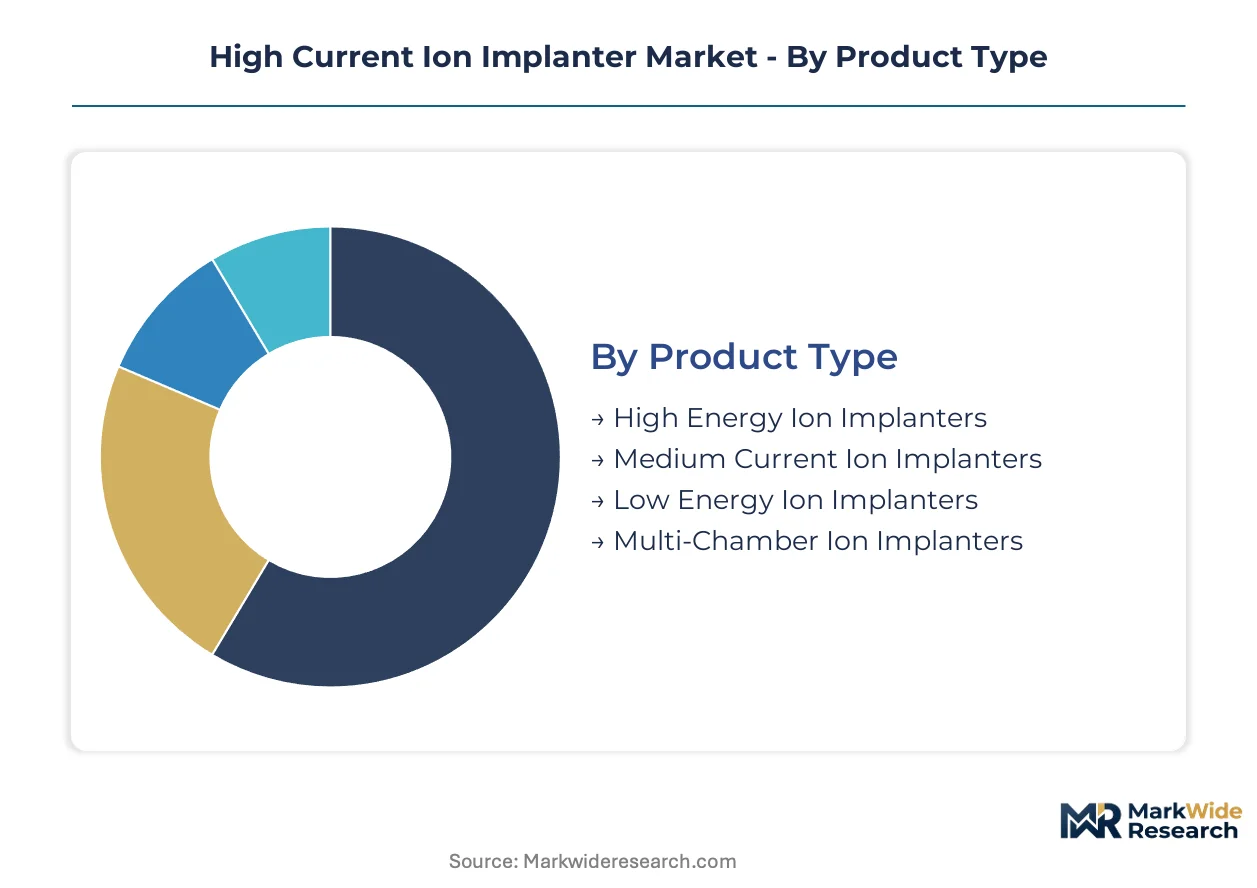
Segmentation reveals how equipment architecture, process technology, and customer procurement patterns create distinct competitive arenas within high-current ion implantation. Each dimension exposes substitution pressures and margin structures that shape vendor strategy.
Product Type:
Beamline specialists face acute substitution pressure from plasma-based alternatives in the low-energy regime, while multi-chamber configurations disrupt throughput economics across all energy tiers.
- High Energy Ion Implanters:These systems accelerate dopant ions above 200 keV for deep well formation and buried layer creation in power devices. Semiconductor foundries in Taiwan deploy these platforms for advanced logic isolation structures where penetration depth precision dictates device reliability.
- Multi-Chamber Ion Implanters:Sequential process integration within a single vacuum envelope eliminates wafer handling between implant steps. Samsung Foundry and Taiwan Semiconductor Manufacturing Company have adopted these configurations for 3D NAND string formation where contamination control and throughput economics converge.
- Medium Current Ion Implanters:Beam current ranges of 1-10 mA serve mature node CMOS and analog device production with balanced precision and speed.
- Low Energy Ion Implanters:Sub-10 keV systems target ultra-shallow junction formation for sub-7nm logic nodes where plasma doping retains cost advantages.
High energy ion implanters anchor the volume base while multi-chamber ion implanters gain share at the steepest rate.
Technology:
Cost tier stratification separates established beamline architectures from emerging plasma and electrostatic alternatives that challenge qualification timelines.
- Beamline Ion Implantation:Mass-analyzed ion beams with electrostatic scanning deliver precise dose control and angular uniformity. This technology dominates foundry procurement for advanced logic nodes where metrology traceability and process repeatability justify capital intensity.
- Plasma Ion Implantation:Conformal doping without beamline optics enables high-dose processing of three-dimensional structures. Memory manufacturers in South Korea leverage plasma immersion for 3D NAND channel doping where topography coverage outweighs precision trade-offs.
- Electrostatic Focusing:Beam transport systems using multi-element lens arrays reduce space charge blow-up at high currents. Japanese equipment vendors emphasize electrostatic column designs that minimize aberrations for sub-10nm junction placement.
- Magnetic Mass Analysis:Sector magnet separation of ion species ensures dopant purity and energy monochromaticity. Power device manufacturers prioritize magnetic analysis for silicon carbide implantation where energy contamination degrades blocking voltage performance.
Beamline ion implantation commands the premium tier while plasma ion implantation expands most quickly in memory-specific applications.
Application:
Customer type concentration varies dramatically across applications, with semiconductor fabrication consolidating procurement among foundry oligopolists while power device manufacturing fragments across automotive and industrial suppliers.
- Semiconductor Fabrication:Logic and memory production consumes the majority of high-current implant capacity. Taiwan and South Korea foundries drive equipment refresh cycles as they scale sub-7nm and 3D NAND capacity.
- Power Device Manufacturing:Silicon carbide MOSFET and IGBT production intensifies implant requirements for edge termination and channel engineering. Electric vehicle inverter demand from BYD and Tesla suppliers accelerates beam current specifications beyond silicon-era norms.
- Photovoltaic Cells:Emitter formation and back surface field doping in crystalline silicon solar cells employ medium-current beamline systems. Chinese solar module producers dominate procurement volume with cost-sensitive equipment specifications.
- MEMS Devices:Piezoelectric material modification and sacrificial layer doping require specialized implant recipes. Bosch and STMicroelectronics operate captive implant capacity for automotive sensor production.
Semiconductor fabrication generates the highest absolute revenue while power device manufacturing shows the steepest expansion trajectory.
End User:
Geographic clustering of end users creates distinct procurement ecosystems, with East Asian foundries driving technology roadmaps and European power electronics suppliers prioritizing equipment reliability metrics.
- Semiconductor Foundries:Taiwan Semiconductor Manufacturing Company, Samsung Foundry, and Intel Foundry Services concentrate leading-edge capacity additions. These customers negotiate multi-year service unbundling and demand rapid platform qualification cycles.
- Power Electronics Manufacturers:Infineon, Wolfspeed, and ON Semiconductor operate dedicated implant lines for wide-bandgap device production. Silicon carbide substrate adoption deepens their implant intensity compared to silicon-era baselines.
- Solar Module Producers:LONGi, JinkoSolar, and Trina Solar deploy ion implanters for PERC and TOPCon cell architectures. Chinese domestic equipment vendors compete aggressively on price in this segment.
- Microelectromechanical Systems Developers:Bosch, Texas Instruments, and TDK maintain specialized implant capacity for accelerometer, gyroscope, and pressure sensor fabrication. Process customization requirements limit standardization economies.
Semiconductor foundries anchor the volume base while power electronics manufacturers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. East Asian fabrication clusters prioritize throughput and contamination control for sub-7nm logic, while European power electronics suppliers emphasize equipment reliability metrics for silicon carbide production.
United States
Domestic foundry construction and power device manufacturing drive equipment procurement. The Commerce Department's Entity List restrictions shape deployment timelines for non-aligned manufacturing zones. Intel's Arizona and Oregon fabs anchor leading-edge capacity additions with multi-chamber platform adoption.
South Korea
Samsung Foundry and SK Hynix expand 3D NAND and advanced logic implant capacity. The Ministry of Trade, Industry and Energy coordinates supply chain resilience programs for beamline component localization. The Pyeongtaek semiconductor cluster concentrates high-current tool deployment for memory string formation.
Taiwan
TSMC's foundry dominance creates concentrated procurement power for beamline systems. The National Science and Technology Council channels R&D subsidies toward domestic equipment vendor qualification. The Hsinchu Science Park anchors global high-current implant density with sub-7nm capacity scaling.
Japan
Captive fab networks and power device manufacturing sustain equipment demand. METI's supply chain resilience programs require documented domestic content ratios for procurement preferences. The Kyushu region concentrates ion source and beamline component production among specialty materials suppliers.
China
Domestic foundry buildouts and import substitution timelines accelerate local toolmaker development. GB standards and NMPA-equivalent semiconductor equipment certifications shape qualification requirements. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters drive high-current implant procurement for mature node expansion.
High Current Ion Implanter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in high-current ion implanter supply. Applied Materials leverages its installed base across 300mm foundry transitions, while Axcelis Technologies anchors North American supply security through power device specialization. Nissin Ion Equipment competes in Japanese captive fab networks. Strategic moves concentrate on service contract unbundling and multi-chamber platform convergence.
Among US-based equipment vendors, Applied Materials and Axcelis Technologies occupy positions spanning foundry and power device segments. Nissin Ion Equipment represents the Japanese specialist archetype with captive network penetration. These three exemplify how geographic anchoring and application focus shape competitive positioning without requiring identical platform architectures.
| Leading Market Players |
|---|
| Applied Materials |
| Axcelis Technologies |
| Nissin Ion Equipment |
| Sumitomo Heavy Industries Ion Technology |
| ULVAC |
| Intevac |
| Ion Beam Services |
| Kingstone Semiconductor Joint Stock Company |
| High Voltage Engineering Europa |
| Others |
Pricing and Supply Chain Analysis
300mm foundry scale economies concentrate procurement leverage among Taiwan and South Korea fabrication clusters, compressing equipment price floors while elevating service contract attachment rates as vendors defend margin structures through aftermarket revenue streams.
Pricing Analysis
After-sales service contracts now generate lifetime value exceeding original equipment sales for beamline system vendors. Pricing stratifies across premium, standard, and economy tiers based on SEMI S2 certification status and geographic delivery complexity. Cost compression in the economy tier intensifies as Chinese domestic toolmakers qualify under GB standards. Solar module producers in China exhibit the highest price sensitivity, while Taiwan semiconductor foundries prioritize throughput metrics over capital expenditure minimization.
Supply Chain Analysis
Tungsten filament production clusters in Japan and Germany create single-source vulnerability for ion source component supply. Beamline system manufacturing draws from specialty steel suppliers in Japan, precision optics fabricators in Germany, and high-voltage power electronics from South Korea. Tariff exposure on Japanese specialty materials threatens qualification timelines for North American equipment vendors. Distribution runs through direct foundry procurement teams in East Asia and regional equipment distributors serving European power device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate penetration in electric vehicle powertrains signals early-cycle expansion with implant intensity deepening beyond silicon-era baselines.
For Market Incumbents: Compound service revenue density through multi-year maintenance contracts unbundled from initial tool sales. Defend against plasma doping substitution in mature nodes above 28nm by accelerating sub-7nm beamline qualification cycles. Prioritize vertical integration into electrostatic chuck thermal management components where materials science expertise concentrates among retiring veteran engineers. For New Entrants and Emerging Players: SEMI S2 certification fast-tracks through partnership with established safety documentation consultants unlock US and European fab access. White-space concentration sits in Chinese domestic foundry buildouts where GB standards and NMPA-equivalent certifications create import substitution windows. Target power device manufacturers in Europe seeking silicon carbide implant capacity with reliability-centric value propositions distinct from throughput-optimized foundry offerings. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors beamline component specialists with ion source and mass analysis magnet expertise. Long-term viability hinges on captive supply security for tungsten filament and precision optics subsystems. Monitor divergence between US Commerce Department Entity List expansion and non-aligned manufacturing zone foundry construction schedules as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chamber Platform Convergence | TSMC and Samsung Foundry adoption reduces wafer handling contamination risk while improving throughput economics. |
| Domestic Content Ratio Documentation | Japan METI procurement preferences accelerate qualification for local ion source and beamline component vendors. |
| Service Contract Unbundling | Taiwan and South Korea foundries negotiate multi-year maintenance agreements separately from tool acquisitions. |
| Silicon Carbide Implant Intensity Expansion | Wolfspeed and Infineon deepen beam current specifications for electric vehicle inverter production. |
| GB Standards Qualification Pathway | Chinese domestic toolmakers leverage NMPA-equivalent certifications to displace imported beamline systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with semiconductor foundry procurement directors, ion implanter platform engineers, power device manufacturing executives, and aftermarket service contract managers. Secondary validation drew from SEMI equipment market data, US Commerce Department export control filings, Japan METI supply chain program documentation, and China MIIT domestic equipment certification registries. Bottom-up equipment shipment tracking and top-down foundry capex analysis were triangulated to reconcile volume estimates.
Across the analysis window, forecasts were derived through segmented modeling of product type, technology architecture, application intensity, and end-user geographic concentration. Beamline versus plasma doping technology displacement curves, silicon carbide substrate adoption trajectories, and regional foundry construction pipelines served as primary forecast inputs. CAGRs were calculated from annual equipment revenue estimates cross-referenced against disclosed customer procurement patterns.
Underlying assumptions cover continued East Asian foundry dominance, stable tungsten filament supply availability, and gradual Chinese domestic toolmaker qualification timelines, with deviation risk concentrated in export control classification expansions and alternative doping technology breakthroughs. Practitioners should keep alternative scenarios live as regulatory divergence and substrate material transitions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.