
 Solar Texturing Equipment Market | 2026-2036
Solar Texturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Texturing Equipment Market Insights
Photovoltaic process engineering talent scarcity is unwinding capacity expansion timelines across Southeast Asia and Central Europe. SCHMID Group leverages its wet chemistry heritage to anchor German manufacturing lines with turnkey etching systems. Tokyo Electron Limited dominates plasma texturing tool architectures through proprietary reactor designs. Applied Materials sustains North American tool demand with broad deposition-to-texturing integration capabilities.
Solar texturing equipment encompasses machinery that modifies silicon wafer surfaces through chemical, mechanical, or photonic means to reduce reflectance and boost photon absorption, typically achieving surface roughness in the micrometer range via alkaline or acidic etch chemistries. Wet etching systems lead unit shipments due to mature alkaline bath economics, while laser texturing commands premium positioning for PERC and TOPCon cell architectures requiring selective area processing. Among end users, manufacturers absorb the dominant share of capital expenditure as gigawatt-scale fabs prioritize throughput consistency over research-grade flexibility.
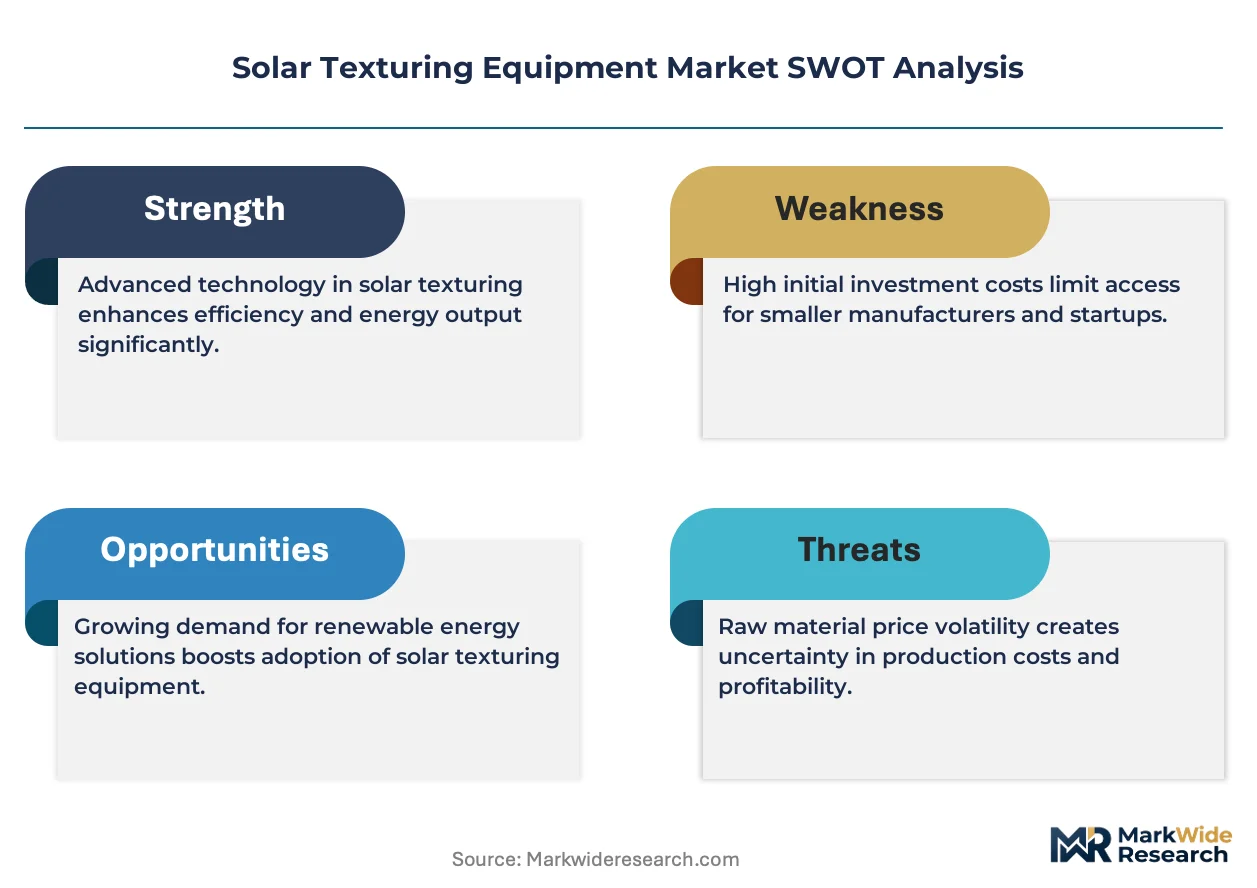
China's MIIT enforces GB standards for photovoltaic manufacturing equipment efficiency, compelling domestic tool upgrades that ripple through export markets. The EU Green Deal and REACH chemical frameworks restrict etchant chemistries, pushing equipment makers toward closed-loop bath management systems. EMA and EPA compliance layers add certification complexity for tools serving European and North American fabs. Stakeholders must weigh regulatory chemistry constraints against throughput targets when specifying next-generation texturing lines.
Market Dynamics
Photovoltaic cell efficiency mandates are compressing texturing process tolerances below 500 nanometers, forcing equipment makers to abandon batch alkaline baths in favor of inline plasma and laser architectures that deliver selective area precision.
Growth Catalysts
- EU Green Deal manufacturing subsidies:European gigafactory buildouts in Germany and Hungary are mandating closed-loop wet chemistry systems that reduce etchant waste discharge by 90 percent.
- TOPCon cell architecture migration:Tunnel oxide passivated contact designs require selective emitter texturing that alkaline isotropic etching cannot achieve, pulling laser and plasma tool orders.
- India:PLI scheme disbursements for integrated solar module manufacturing are accelerating wafer-level processing line orders from domestic and foreign equipment vendors.
Market Restraints
- High-purity hydrofluoric acid supply:Acidic texturing chemistries depend on semiconductor-grade HF where Chinese export quotas have tightened feedstock availability.
- REACH chemical authorization:ECHA's restriction roadmap for potassium hydroxide and nitric acid blends is forcing European fabs to pre-approve alternative etchant formulations.
- Plasma reactor chamber degradation:Fluorine-based plasma chemistries accelerate electrode wear, compressing mean time between maintenance below 2,000 process hours.
Strategic Opportunities
- Heterojunction cell penetration in Japan:METI's renewable energy auctions favor high-efficiency architectures requiring amorphous silicon-compatible texturing surfaces.
- Perovskite-silicon tandem integration:Tandem cell manufacturing lines demand texturing profiles that balance silicon light trapping with perovskite layer uniformity.
- Equipment-as-a-service models:Capital-constrained Southeast Asian cell makers are leasing wet bench capacity with bundled chemistry management from European vendors.
Industry Challenges
- Process engineering talent scarcity:Wet chemistry optimization for alkaline texturing requires expertise that has concentrated at legacy semiconductor fabs in Taiwan and South Korea.
- Multi-tool integration complexity:Gigafactory lines combining wet etching, plasma texturing, and PECVD deposition demand unified control software that few vendors have perfected.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Texturing Equipment Market |
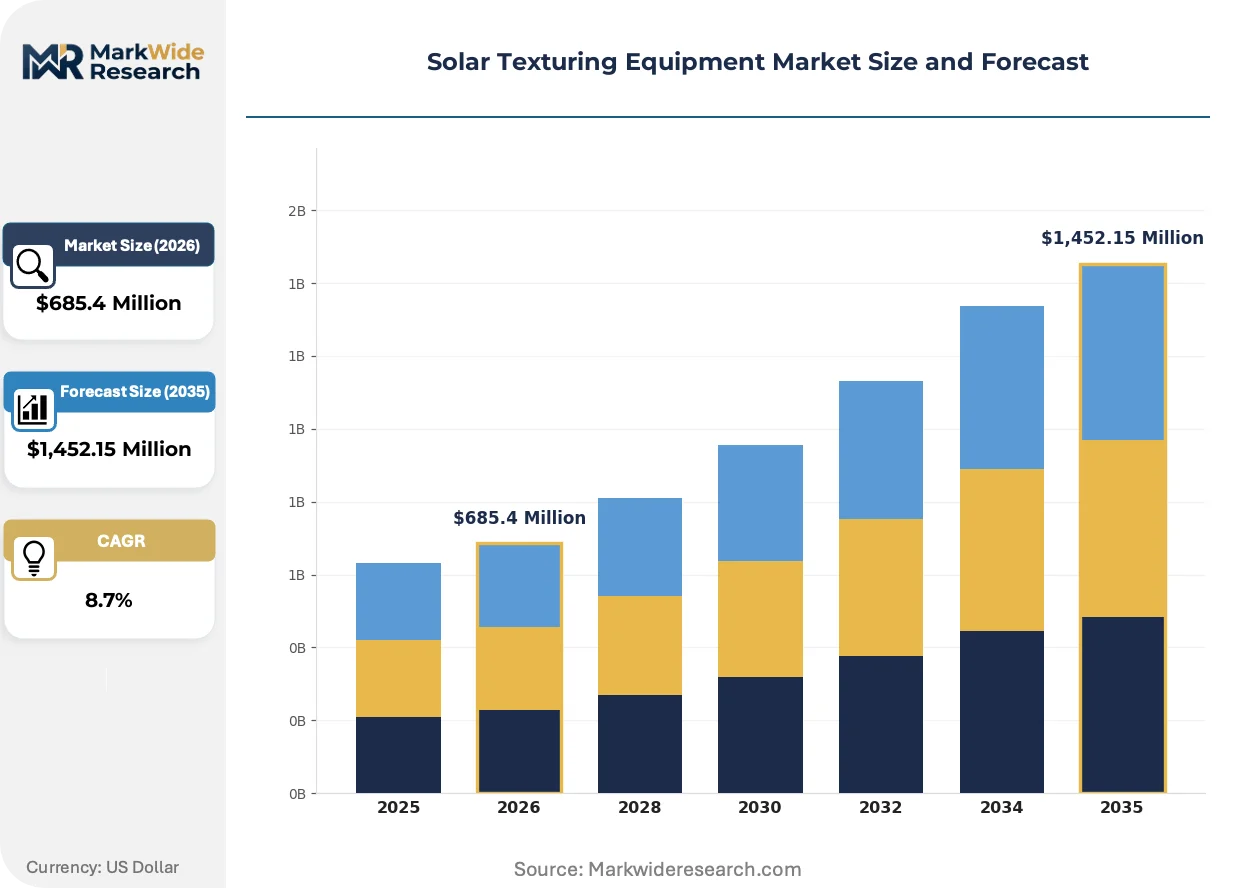
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Etching, Dry Etching, Laser Texturing, Plasma Texturing Technology: Chemical Vapor Deposition, Physical Vapor Deposition, Nanoimprint Lithography, Screen Printing End User: Manufacturers, Research Institutions, Solar Panel Installers, Component Suppliers Application: Silicon Solar Cells, Thin-Film Solar Panels, Bifacial Modules, Concentrated Photovoltaics |
| Companies Covered | RENA Technologies, SCHMID Group, Applied Materials, Tokyo Electron Limited, Veeco Instruments, WONIK IPS, Y.A.C. CO., LTD, S.P.M. s.r.l., Singulus Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Texturing Equipment Market Trends and Innovations
Equipment architectures are bifurcating between high-throughput wet benches for commodity cells and precision plasma systems for advanced architectures, with chemistry management and digital process control emerging as the primary differentiation vectors.
Laser-induced periodic surface structuring is fragmenting the monocrystalline silicon texturing landscape. Tier-one cell makers in China and Germany are adopting femtosecond laser systems for PERC and TOPCon selective emitter definition. The technology is fragmenting vendor market positions by rewarding specialists with beam delivery expertise over traditional wet chemistry incumbents.
REACH chemical authorization timelines are compressing etchant formulation cycles. ECHA's 2024 restriction proposals for potassium hydroxide concentrations above 15 percent are forcing equipment makers to validate alternative alkaline chemistries. German and Dutch fabs are responding by pre-qualifying closed-loop bath regeneration systems that extend chemistry life.
Buyer consolidation among integrated module manufacturers is reshaping procurement leverage. Gigafactory operators in India and Southeast Asia are demanding performance guarantees tied to cell efficiency outcomes rather than equipment uptime metrics. Chinese equipment vendors are responding with efficiency-linked pricing structures that align capital expenditure with production yields.
Solar Texturing Equipment Market Segmentation
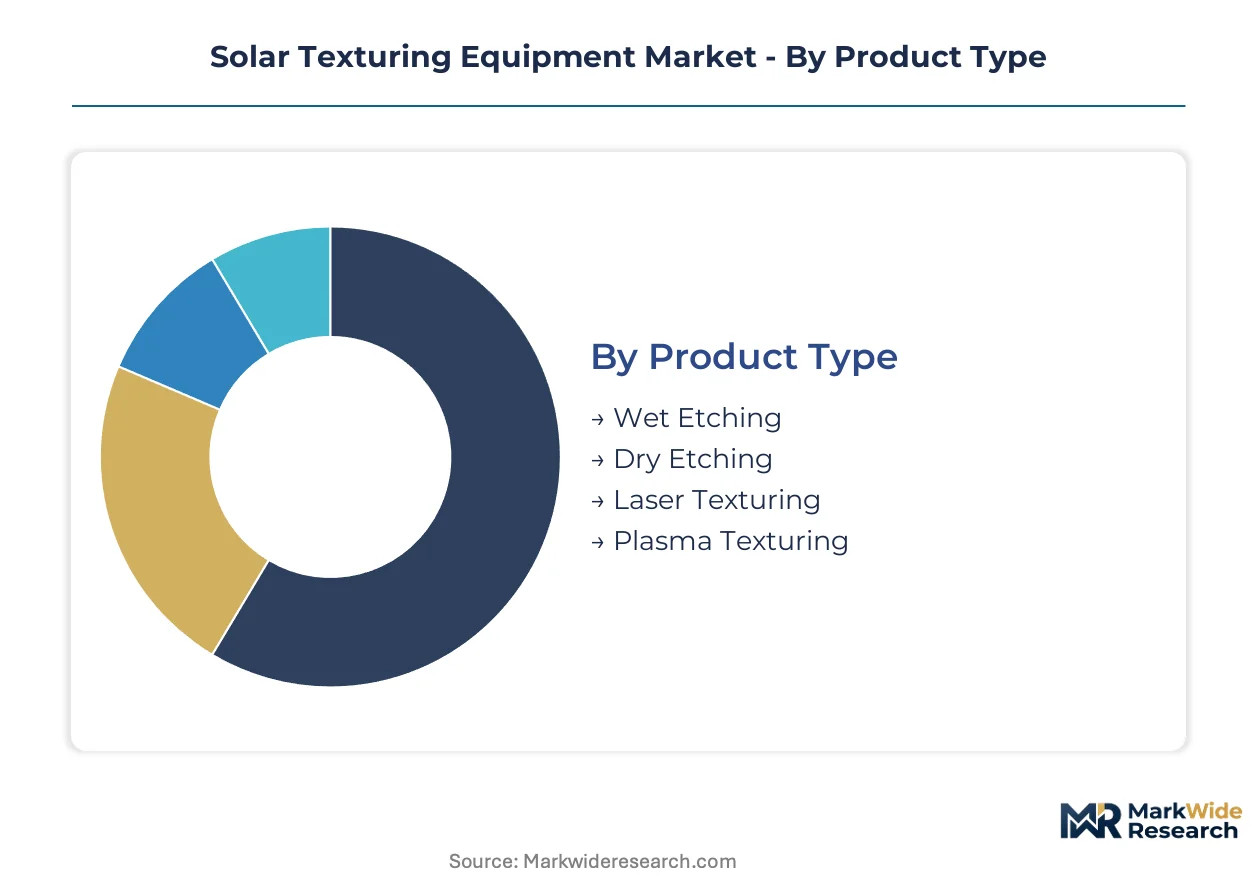
Equipment specification diverges sharply across cell architectures, with alkaline wet benches dominating commodity production while laser and plasma systems capture premium efficiency tiers. Technology selection cascades through chemistry management costs, throughput targets, and regulatory compliance layers.
Product Type:
Margin pools concentrate in selective-area processing tools where precision commands pricing premiums over batch wet chemistry.
- Wet Etching:Alkaline bath systems process monocrystalline wafers through potassium hydroxide or sodium hydroxide chemistries, achieving random pyramid surface structures. Chinese gigafactories in Jiangsu and Anhui provinces absorb the dominant share of alkaline bench orders as they scale PERC and TOPCon lines under MIIT efficiency mandates.
- Laser Texturing:Femtosecond and picosecond pulse systems deliver selective emitter definition with sub-micron precision for passivated contact architectures. German and Chinese tier-one cell makers are pulling laser tool orders as tunnel oxide passivated contact designs displace homogeneous emitter structures.
- Dry Etching:Reactive ion etch systems modify wafer surfaces through fluorine-based plasma chemistries without liquid waste streams. Installations cluster in European fabs navigating REACH chemical restrictions on alkaline etchants.
- Plasma Texturing:Capacitively coupled reactors generate surface roughness through ionized gas chemistries with closed-loop exhaust management. Japanese heterojunction cell lines specify plasma texturing for amorphous silicon compatibility.
Wet etching holds installed capacity. Laser texturing is rotating up the share rankings.
Technology:
Deposition and patterning technologies stratify by cell architecture maturity and integration complexity.
- Chemical Vapor Deposition:Atmospheric and low-pressure CVD systems deposit antireflective coatings and passivation layers atop textured surfaces. Indian PLI scheme beneficiaries are ordering CVD-integrated texturing lines for domestic module manufacturing.
- Physical Vapor Deposition:Sputtering and evaporation systems metallize textured wafers with aluminum or silver contacts. European equipment vendors bundle PVD with wet chemistry management for turnkey efficiency guarantees.
- Nanoimprint Lithography:Mechanical patterning replicates sub-wavelength surface structures for advanced light trapping. Research institutions in Germany and Japan pilot nanoimprint integration for perovskite-silicon tandem architectures.
- Screen Printing:Mesh-based metallization overlays textured surfaces with conductive pastes. Southeast Asian contract manufacturers specify screen printing for cost-sensitive aluminum back surface field cell production.
Chemical vapor deposition anchors mainstream production. Nanoimprint lithography is gaining share fastest in R&D-intensive segments.
End User:
Procurement authority concentrates with integrated manufacturers who bundle texturing specifications across multi-gigawatt expansion programs.
- Manufacturers:Cell and wafer producers operating gigafactory-scale fabs absorb the dominant capital expenditure share. Chinese, Indian, and German integrated module makers specify throughput-optimized texturing lines with efficiency-linked performance guarantees.
- Research Institutions:National laboratories and university consortia pilot next-generation texturing chemistries and architectures. Japan's METI-funded centers and Germany's Fraunhofer institutes validate laser and plasma processes before commercial scale-up.
- Solar Panel Installers:Distributed energy project developers procure limited texturing capacity for module customization or repair operations. Installers in India's Rajasthan and Gujarat clusters source refurbished wet benches for captive wafer processing.
- Component Suppliers:Backsheet, junction box, and encapsulant vendors maintain minimal texturing exposure for quality verification. Chinese component specialists occasionally deploy benchtop etching systems for incoming wafer inspection.
Manufacturers command procurement volume. Research institutions are rotating up the share rankings as pilot line investments accelerate.
Application:
Cell architecture selection dictates texturing chemistry, roughness targets, and equipment integration requirements.
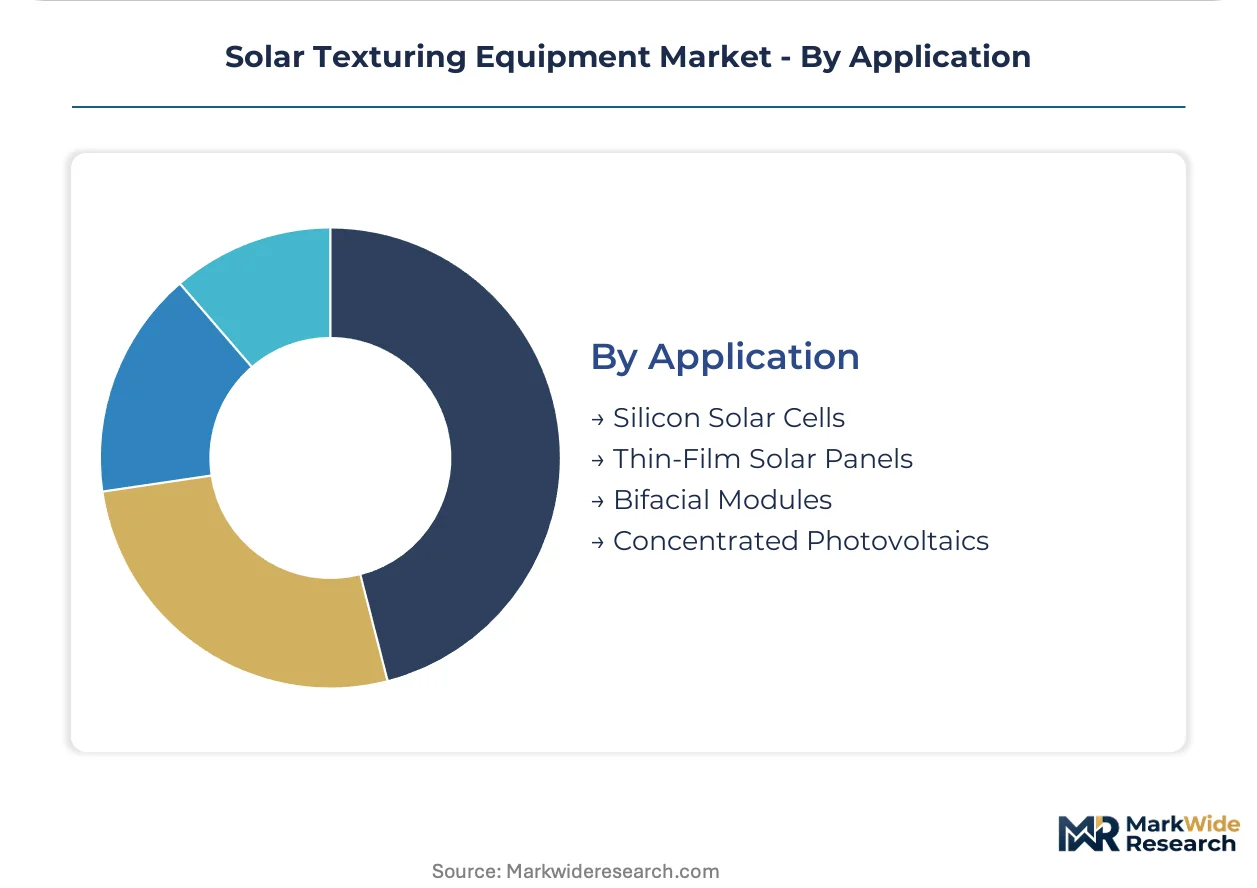
- Silicon Solar Cells:Monocrystalline and multicrystalline silicon wafers require alkaline or acidic surface modification to reduce reflectance below 15 percent. Chinese PERC and TOPCon lines in Anhui, Jiangsu, and Sichuan provinces drive wet and laser texturing demand.
- Thin-Film Solar Panels:Cadmium telluride and copper indium gallium selenide architectures bypass silicon texturing entirely. Thin-film manufacturers in the US and Germany source minimal texturing equipment for substrate conditioning only.
- Bifacial Modules:Double-sided cells demand symmetric front and rear surface texturing for balanced photon absorption. Indian gigafactories specify bifacial-compatible wet benches under PLI scheme disbursements.
- Concentrated Photovoltaics:High-efficiency multi-junction cells require minimal surface texturing due to primary optic concentration. CPV research programs in Spain and the US maintain limited etching capacity for III-V substrate preparation.
Silicon solar cells hold installed capacity. Bifacial modules are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power tilts toward German and Japanese vendors serving European precision fabs, while Chinese manufacturers dominate volume contracts through aggressive localization in Jiangsu and Anhui provinces.
China
MIIT efficiency mandates under GB standards compel domestic gigafactories to upgrade wet etching lines for PERC and TOPCon architectures. The dual carbon goals accelerate wafer-level processing investments across Yangtze River Delta clusters. Anhui and Jiangsu provinces absorb dominant alkaline bench orders as integrated module makers scale multi-gigawatt expansions.
Germany
EU Green Deal manufacturing subsidies channel capital into closed-loop wet chemistry systems that cut etchant waste discharge. ECHA REACH restrictions on potassium hydroxide concentrations above 15 percent push equipment validation toward alternative alkaline formulations. Fraunhofer institutes in Bavaria pilot laser and plasma processes before commercial scale-up to domestic cell makers.
India
PLI scheme disbursements for integrated solar module manufacturing accelerate wafer-level processing line orders from domestic and foreign equipment vendors. Central Electricity Authority guidelines mandate efficiency benchmarks that texturing equipment must achieve. Gujarat and Rajasthan clusters source refurbished wet benches for captive wafer processing alongside new high-throughput lines.
Japan
METI renewable energy auctions favor high-efficiency heterojunction architectures requiring amorphous silicon-compatible texturing surfaces. JIS standards govern equipment certification for domestic cell manufacturing investments. Kansai and Kyushu regions concentrate plasma texturing installations for next-generation cell pilot lines.
United States
EPA compliance layers add certification complexity for tools serving North American fabs navigating state-level environmental regulations. Inflation Reduction Act manufacturing credits incentivize domestic gigafactory buildouts requiring throughput-optimized texturing lines. Arizona and Texas emerging solar clusters specify equipment with efficiency-linked performance guarantees rather than uptime metrics alone.
Solar Texturing Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-focused specialists commanding premium positioning against scale-driven volume manufacturers. The vendor base stratifies across three tiers: integrated tool conglomerates with deposition-to-texturing integration capabilities, wet chemistry heritage specialists anchoring European manufacturing lines, and emerging laser system specialists fragmenting selective-area processing segments. Dominant competitive moves include strategic partnerships for unified control software development and geographic expansion through equipment-as-a-service leasing models targeting capital-constrained Southeast Asian cell makers.
Among German wet chemistry heritage specialists, SCHMID Group GmbH occupies a position exemplifying turnkey etching system anchoring for European manufacturing lines. Tokyo Electron Limited represents the integrated tool conglomerate archetype through proprietary reactor design capabilities spanning plasma texturing architectures. Applied Materials Inc. sits within the North American technology leadership tier, sustaining regional tool demand through broad process integration capabilities that span deposition-to-texturing workflows.
| Leading Market Players |
|---|
| RENA Technologies |
| SCHMID Group |
| Applied Materials |
| Tokyo Electron Limited |
| Veeco Instruments |
| WONIK IPS |
| Y.A.C. CO., LTD |
| S.P.M. s.r.l. |
| Singulus Technologies |
| Others |
Pricing and Supply Chain Analysis
Laser tool displacement of alkaline wet benches is redrawing supply geography toward German and Japanese precision vendors while compressing pricing premiums for batch processing equipment. This substitution dynamic simultaneously elevates configured-to-order laser system margins and erodes standardized wet bench pricing power across Chinese volume contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order laser texturing systems from standardized alkaline wet benches. Three-tier pricing structure across premium, standard, and economy levels reflects throughput specifications, closed-loop chemistry certification, and regional regulatory compliance bundling. Cost compression in standard wet benches is intensifying because Chinese gigafactories consolidate procurement leverage across multi-gigawatt programs. Research institutions exhibit lowest price sensitivity due to efficiency-linked performance guarantees, while Southeast Asian contract manufacturers prioritize capital expenditure minimization.
Supply Chain Analysis
Inventory-strategy preferences bifurcate between just-in-time component flows for laser system assembly and strategic stockpiling of high-purity hydrofluoric acid for wet chemistry operations. Supply concentration centers on China for alkaline bath components, Germany for precision reactor chambers, and Japan for plasma electrode assemblies. Feedstock sourcing draws from semiconductor-grade chemical suppliers in China, South Korea, and Taiwan. Single-source vulnerability in femtosecond laser source modules creates procurement risk for European tool integrators. Distribution runs through direct equipment vendor relationships with gigafactory operators, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against dry etching and nanoimprint lithography architectures that threaten alkaline wet bench incumbents. Incumbents must navigate femtosecond laser tool specialists capturing selective-area processing premiums.
For Market Incumbents: Consolidate wet chemistry expertise through backward integration into closed-loop bath regeneration technology. Acquire laser beam delivery specialists to bridge batch alkaline and selective-area plasma competencies. Defend against Tokyo Electron and emerging Chinese laser vendors by anchoring German manufacturing lines with efficiency-outcome guarantees rather than equipment uptime metrics alone. For New Entrants and Emerging Players: Anchor in India's PLI scheme beneficiary ecosystem where foreign equipment vendors face localization mandates and domestic players lack wet chemistry heritage. Target refurbished wet bench leasing models for Rajasthan and Gujarat captive processing clusters. Pursue equipment-as-a-service positioning with bundled chemistry management to bypass capital expenditure barriers. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors precision tool specialists over scale-driven volume manufacturers. Long-term viability rests on selective-area processing dominance as PERC and TOPCon architectures displace homogeneous emitter designs. Acquisition targets should display unified control software capabilities across wet, plasma, and laser texturing modules. Watch for MIIT efficiency mandate tightening as inflection indicator for laser tool order acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Chemistry Integration | REACH compliance in German fabs drives 90 percent etchant waste reduction mandates. |
| Laser Tool Specialist Acquisition | Femtosecond beam delivery expertise fragments vendor positions in selective-area processing. |
| Equipment-as-a-Service Launch | Southeast Asian capital constraints favor leased wet bench capacity with bundled chemistry management. |
| Unified Control Software Development | Gigafactory lines combining wet, plasma, and PECVD deposition demand integrated process orchestration. |
| India Localization Partnership | PLI scheme disbursements require domestic manufacturing footprint for foreign equipment vendors. |
Research Methodology
A spread of perspectives from photovoltaic process engineers, gigafactory procurement directors, wet chemistry R&D leads, and laser system integration specialists converged on the working assumptions. Primary interviews combined with secondary validation from MIIT GB standard filings, ECHA REACH restriction proposals, SEC equipment vendor disclosures, and Indian CEA efficiency guidelines. Bottom-up equipment shipment tallies triangulated against top-down gigafactory capacity expansion announcements.
Segmentation dimensions modeled include texturing technology type, cell architecture application, end-user procurement authority, and regional regulatory framework clusters. CAGRs were derived from installed capacity buildout trajectories across the projection horizon. Forecast inputs incorporated MIIT efficiency mandate compliance timelines, EU Green Deal manufacturing subsidy disbursement schedules, and TOPCon cell architecture migration curves.
Decision-makers should treat outputs as directional under sustained PERC-to-TOPCon transition assumptions; material deviation would warrant model refresh. Forecasts reflect gigafactory buildout pacing, high-purity chemical feedstock availability, and plasma reactor maintenance interval improvements. Revision becomes warranted when heterojunction cell penetration in Japan or perovskite-silicon tandem commercialization crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Remote Plasma Source Market