
 Semiconductor Wafer Process Control Equipment Market | 2026-2036
Semiconductor Wafer Process Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wafer Process Control Equipment Market Insights
East Asian foundry capital expenditure is consolidating around leading-edge nodes below 5nm. Applied Materials leverages its broad process equipment portfolio to bundle metrology solutions with deposition and etch systems. KLA Corporation anchors the defect inspection segment through deep ultraviolet and electron-beam platforms that sustain its technology leadership in critical dimension measurement.
Semiconductor wafer process control equipment encompasses metrology, inspection, and testing systems used to monitor dimensional accuracy, defect density, and electrical performance during wafer fabrication, typically operating at nanometer-scale resolution with throughputs exceeding 100 wafers per hour. These systems enable yield management by detecting pattern deviations, particle contamination, and film thickness variations before subsequent processing steps compound errors. Optical measurement systems occupy the largest product category as lithography-critical layers require sub-angstrom overlay precision. Laser interferometry dominates the technology dimension for displacement metrology in stage positioning, while X-ray diffraction serves the fastest-growing niche for crystallographic stress analysis in advanced packaging.
US FDA oversight of semiconductor manufacturing equipment safety intersects with EPA hazardous substance reporting for perfluorinated compound emissions from etch and clean processes. Japan's METI enforces JIS standards for industrial measurement instruments that govern equipment import certification. Taiwan's central environmental regulator mandates greenhouse gas inventory disclosure for fabs exceeding specified capacity thresholds. Stakeholders must weigh dual-use export control expansions against the capital intensity of regionally diversified metrology supply chains.
Market Dynamics
Node migration below 3nm is compressing metrology tolerance windows to sub-angstrom precision, forcing fabs to quadruple inspection sampling rates at critical lithography layers while EU REACH fluorinated gas restrictions mandate real-time chemistry monitoring retrofits across existing etch fleets.
Growth Catalysts
- Sub-3nm Node Ramp:Taiwan's advanced logic foundries are expanding metrology procurement to support gate-all-around transistor architectures requiring atomic-scale dimensional control.
- EU F-Gas Regulation:REACH restrictions on perfluorinated compounds are compelling fabs to adopt alternative etch chemistries that demand tighter in-situ process monitoring.
- Pyeongtaek Cluster Concentration:Samsung and SK hynix memory expansion in South Korea is concentrating demand for high-throughput defect inspection systems.
Market Restraints
- Specialized Component Bottlenecks:Extreme ultraviolet light source subsystems rely on single-source suppliers in Germany and Japan, creating geographic concentration vulnerability.
- Technical Limitation:Electron-beam inspection throughput remains capped below 10 wafers per hour for full-die imaging, constraining inline deployment.
- Regulatory Friction:US Bureau of Industry and Security export controls on advanced lithography metrology are fragmenting equipment qualification pathways.
Strategic Opportunities
- Advanced Packaging Metrology:Hybrid bonding and chiplet architectures in Taiwan and South Korea are creating demand for X-ray diffraction stress analysis systems.
- India PLI Scheme:Production-linked incentives for semiconductor fabrication are attracting metrology vendors to establish local calibration facilities.
- AI-Accelerated Defect Classification:Convolutional neural networks trained on historical wafer maps are converging with optical inspection hardware to reduce false-positive rates.
Industry Challenges
- Metrology Physicist Shortage:The intersection of optics, materials science, and statistics required for advanced node characterization exceeds current graduate program output.
- Legacy Tool Integration:300mm fabs operating 200mm-era inspection platforms face data format incompatibilities with modern yield management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wafer Process Control Equipment Market |
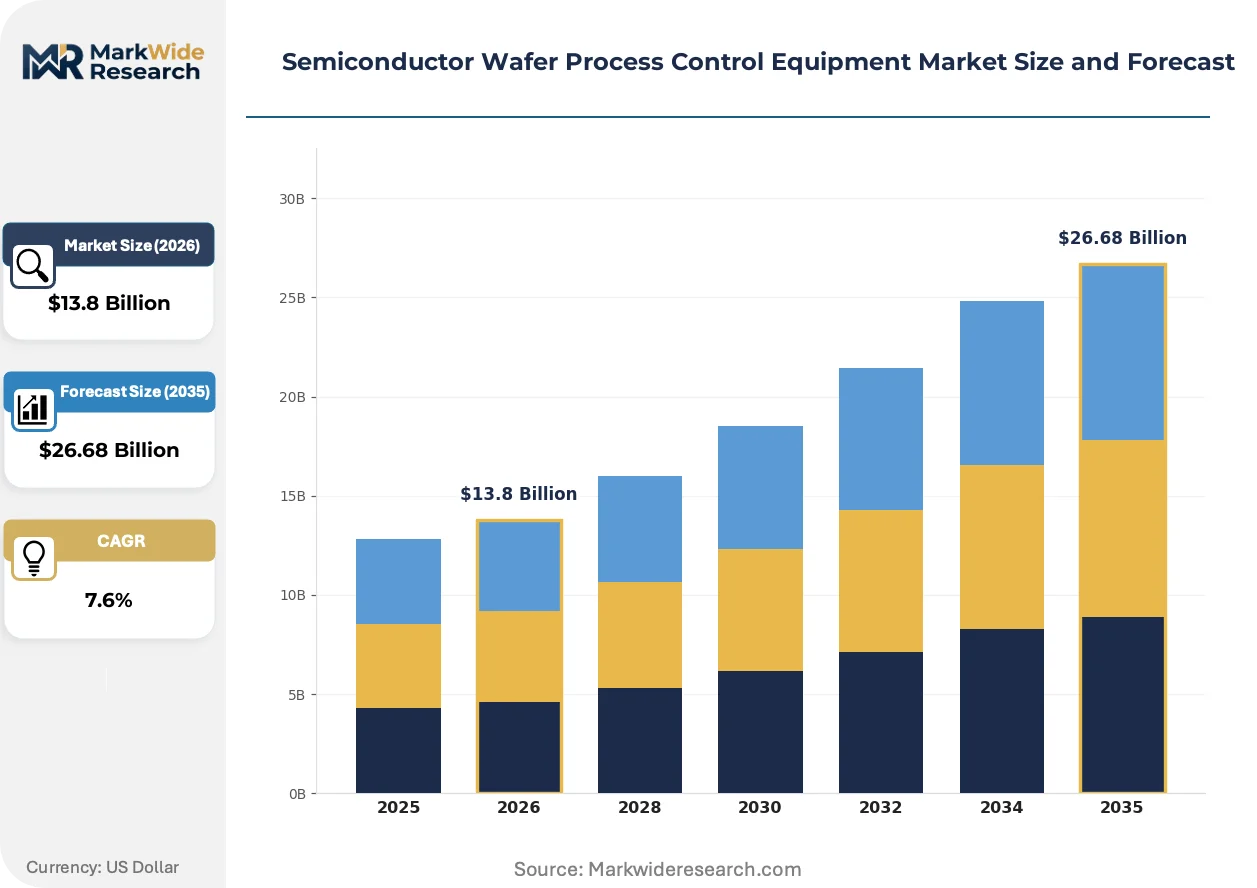
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Measurement Systems, Overlay Metrology, Electrical Test Equipment, Surface Profilers Technology: Laser Interferometry, Spectroscopy, X-Ray Diffraction, Thermal Imaging End User: Foundries, Integrated Device Manufacturers, Research Institutions, Wafer Manufacturers Application: Process Optimization, Quality Control, Yield Management, Equipment Calibration |
| Companies Covered | Applied Materials, KLA Corporation, ASML Holding, Lam Research, Tokyo Electron, Hitachi High-Technologies, Nikon Corporation, Teradyne, Onto Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wafer Process Control Equipment Market Trends and Innovations
Computational metrology and machine-learning inference are compressing measurement cycle times while regulatory chemistry mandates are retrofitting legacy process chambers with real-time gas analysis.
Multi-beam electron microscopy is overtaking single-column architectures for critical dimension measurement. Memory manufacturers in South Korea are adopting these platforms for 3D NAND string profiling. The technology is overtaking optical scatterometry for high-aspect-ratio feature characterization.
EU F-Gas Regulation amendments are mandating leak detection systems for fluorinated greenhouse gas handling equipment. Semiconductor fabs must install continuous emissions monitoring or face operational penalties. Etch process equipment in Germany and France is being retrofitted with infrared spectroscopy-based gas analyzers.
Subscription-based metrology service contracts are displacing capital purchase models for mid-tier foundries. Equipment vendors in Taiwan are unbundling hardware ownership from software analytics access. This pattern is most visible among 200mm legacy node operators seeking to preserve cash for leading-edge migration.
Semiconductor Wafer Process Control Equipment Market Segmentation
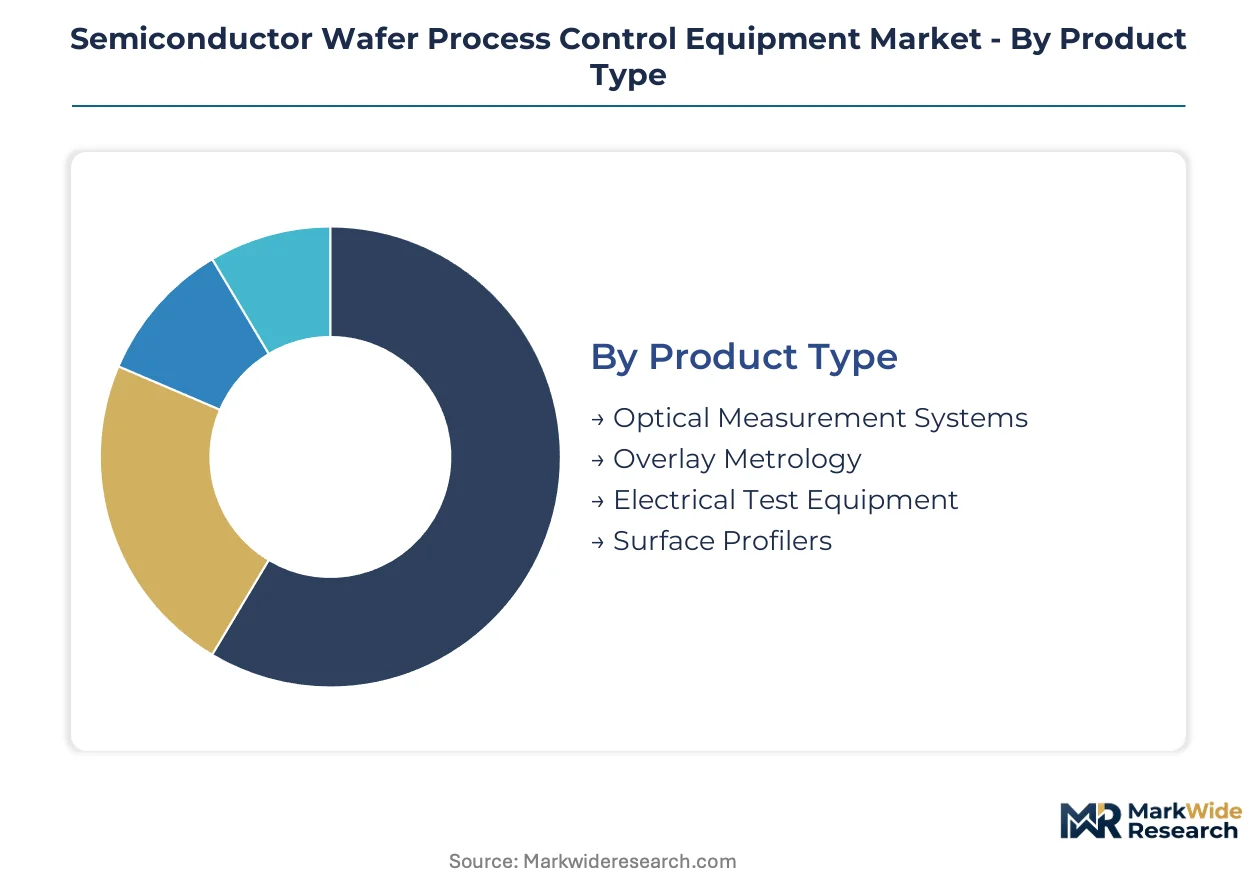
Process control equipment segments diverge sharply between standalone metrology bays and inline sensors embedded within deposition and etch tools. Equipment vendors bundle embedded solutions with process chambers while standalone systems command premium pricing for atomic-scale resolution tasks.
Product Type:
Optical systems dominate standalone installations for lithography overlay verification, while electrical testers integrate directly into probe stations.
- Optical Measurement Systems:These platforms employ broadband reflectometry and ellipsometry for film thickness mapping at sub-angstrom precision. Taiwan's advanced logic foundries deploy these at every critical lithography layer to gate subsequent processing. Demand concentrates at 3nm and below where multi-patterning stacks compound error propagation risks.
- Overlay Metrology:Specialized diffraction-based sensors measure pattern-to-pattern registration errors with precision below 0.3 nanometers. Samsung's Pyeongtaek complex has quadrupled procurement of these systems for gate-all-around transistor alignment. The technology sits at the boundary between standalone and scanner-embedded deployment models.
- Electrical Test Equipment:Parametric analyzers and probe stations verify transistor performance at wafer level before dicing.
- Surface Profilers:Atomic force and optical profilometers quantify roughness and topography for chemical mechanical planarization monitoring.
Optical Measurement Systems lead volumes today; Overlay Metrology is gaining share fastest.
Technology:
Displacement metrology relies on mature laser architectures, while crystallographic analysis demands synchrotron-grade X-ray sources.
- Laser Interferometry:Heterodyne interferometers track wafer stage position with sub-nanometer resolution at throughput exceeding 200 wafers per hour. Applied Materials embeds these sensors directly into deposition chamber motion stages. The technology anchors position feedback loops across all leading-edge lithography scanners.
- Spectroscopy:Optical emission and mass spectrometry monitor etch chemistry endpoints in real time. EU F-Gas Regulation compliance is retrofitting German and French etch fleets with infrared absorption analyzers for perfluorinated compound detection. These systems shift process control from recipe-based to molecular-feedback architectures.
- X-Ray Diffraction:High-brightness sources enable stress mapping in through-silicon vias and hybrid bonding interfaces.
- Thermal Imaging:Infrared cameras detect hot spots and thermal uniformity deviations during rapid thermal processing.
Laser Interferometry leads volumes today; Spectroscopy is expanding most quickly.
End User:
Pure-play foundries outsource metrology strategy to equipment vendors, while IDMs maintain captive characterization laboratories.
- Foundries:Taiwan Semiconductor Manufacturing and Samsung Foundry operate centralized metrology bays serving multiple process nodes simultaneously. These facilities prioritize high-throughput optical platforms that can flex across logic, RF, and specialty technologies. Capital allocation favors systems with broad node coverage over single-purpose tools.
- Integrated Device Manufacturers:Intel and Texas Instruments maintain deep in-house metrology expertise tied to proprietary process development. IDMs invest disproportionately in electron-beam and X-ray platforms for internal technology roadmapping. Their procurement patterns track R&D cycle timing rather than production ramp schedules.
- Research Institutions:IMEC in Belgium and academic cleanrooms acquire specialized platforms for pre-competitive characterization.
- Wafer Manufacturers:Siltronic and SUMCO deploy surface inspection systems for epitaxial layer quality verification.
Foundries lead volumes today; Integrated Device Manufacturers are climbing the fastest.
Application:
Yield management commands the largest capital allocation, while equipment calibration represents a recurring service revenue stream.
- Yield Management:Defect detection and classification systems intercept killer particles before they propagate through subsequent process steps. KLA's broadband plasma inspectors dominate this application at memory fabs in South Korea where 3D NAND string stacking multiplies critical layer counts. The economic threshold for 100% inspection has dropped to 5nm design rules.
- Process Optimization:In-situ sensors feed closed-loop control algorithms that adjust etch chemistry and deposition temperature in real time. Tokyo Electron and Lam Research embed these capabilities directly into process equipment. Fabs reduce variance by shifting from statistical process control to deterministic feedback.
- Quality Control:Final electrical verification and reliability screening before wafer shipment.
- Equipment Calibration:Traceable standards maintenance for dimensional metrology tools.
Yield Management leads volumes today; Process Optimization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting metrology procurement toward jurisdictions with stable environmental enforcement and subsidized capital access. Taiwan and South Korea exploit this gap through state-backed foundry expansion, while Germany absorbs compliance costs via integrated equipment-manufacturing ecosystems.
Taiwan
TSMC's sub-3nm ramp in Hsinchu and Tainan Science Parks is quadrupling overlay metrology density at critical lithography layers. The National Development Fund co-invests in process control infrastructure through its semiconductor industry support programs. Taichung's Precision Machinery Innovation Cluster is incubating domestic spectroscopy component suppliers.
South Korea
Samsung and SK hynix are concentrating 3D NAND and DRAM capacity in Pyeongtaek, driving demand for high-throughput electron-beam inspection platforms. MFDS oversight of industrial measurement instruments governs import certification for foreign metrology vendors. Yongin's Giheung complex is expanding captive calibration facilities to reduce qualification timelines.
United States
Intel's Arizona and Oregon fabs are retrofitting etch fleets with real-time gas analyzers to meet EPA perfluorinated compound reporting thresholds. The CHIPS Act fabs-incentives program is accelerating metrology procurement timelines for greenfield sites in Ohio and Texas. Albany's NY CREATES complex serves as a pre-competitive characterization hub for domestic process development.
Japan
Tokyo Electron and Hitachi High-Technologies anchor domestic demand for embedded process sensors and standalone inspection systems. METI's JIS B 7440 standards govern dimensional metrology equipment certification for both domestic use and export. Kyoto's semiconductor equipment cluster maintains captive supply chains for laser interferometer subassemblies.
Germany
Zeiss and Trumpf supply critical EUV and DUV optical subsystems to global lithography metrology vendors. EU F-Gas Regulation amendments mandate continuous emissions monitoring for etch process equipment, retrofitting fabs in Dresden and Reutlingen with infrared spectroscopy analyzers. Saxony's Silicon Saxony cluster integrates metrology development with automotive semiconductor process lines.
Semiconductor Wafer Process Control Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-accelerated defect classification and subscription-based service models. The market consolidates around three strategic archetypes: integrated process equipment vendors bundling metrology with deposition and etch platforms; standalone metrology specialists commanding premium pricing for atomic-scale resolution; and component subsystem suppliers capturing value in optical and laser interferometry subassemblies. Dominant competitive moves include vertical integration into captive sensor production and strategic partnerships between foundries and metrology vendors for co-development of node-specific characterization protocols.
Among US-based equipment conglomerates, Applied Materials and KLA Corporation exemplify divergent archetypes—one integrating metrology within broad process portfolios, the other anchoring standalone defect inspection specialization. Tokyo Electron represents the Japanese integrated equipment model, embedding spectroscopic sensors directly into process chambers. These three occupy positions spanning the bundled-to-specialist spectrum without overlapping core strategic positioning.
| Leading Market Players |
|---|
| Applied Materials |
| KLA Corporation |
| ASML Holding |
| Lam Research |
| Tokyo Electron |
| Hitachi High-Technologies |
| Nikon Corporation |
| Teradyne |
| Onto Innovation |
| Others |
Pricing and Supply Chain Analysis
Metrology physicist concentration in Hsinchu and Tainan widens labor-cost differentials between Taiwan's premium-tier systems and economy-grade alternatives, compressing margins on mid-range platforms as fabs prioritize atomic-scale resolution over throughput optimization.
Pricing Analysis
Direct-to-foundry discounts dominate high-volume procurement, while distributor markups persist for mid-tier legacy node operators. Three-tier pricing structure across premium, standard, and economy levels separates EUV-compatible overlay systems from DUV-era optical platforms and refurbished 200mm inspection tools. Cost compression in the mid-tier is intensifying because captive calibration services are being unbundled from hardware sales. Price-sensitive buyers cluster among 200mm legacy node operators in India and Southeast Asia, while Taiwan's advanced logic foundries exhibit minimal sensitivity to unit pricing.
Supply Chain Analysis
EUV light source subsystems rest on single-source suppliers in Germany and Japan, creating chokepoint vulnerability for DUV and EUV metrology platforms. Zeiss draws from captive optical glass production in Oberkochen, while Japanese laser interferometer component fabrication feeds from Kyoto's precision machinery cluster. Single-source vulnerability concentrates in extreme ultraviolet source architecture and high-brightness X-ray tube production. Distribution runs through equipment vendor direct sales forces for leading-edge fabs, with regional distributors serving legacy node operators in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by foundry migration toward sub-3nm nodes where atomic-scale metrology commands pricing power unavailable at mature geometries.
For Market Incumbents: Deepen backward integration into laser interferometer subassembly production to reduce exposure to Japanese component bottlenecks. Expand captive sensor fabrication in Taiwan's Taichung Precision Machinery cluster to shorten qualification timelines for TSMC and Samsung Foundry. Prioritize co-development agreements for gate-all-around transistor characterization protocols before emerging electron-beam specialists establish node-specific reference standards.
For New Entrants and Emerging Players: Metrology service providers represent the most accessible channel partner type for subscription-based software analytics unbundled from hardware ownership. Target India's PLI-supported fabs in Gujarat and Assam with localized calibration facilities and AI-accelerated defect classification trained on region-specific wafer map libraries. Penetrate the advanced packaging segment through X-ray diffraction stress analysis systems for hybrid bonding interfaces where incumbent coverage remains thin.
For Investors and Strategic Acquirers: Process equipment conglomerates are the most active acquirer in this space, seeking metrology specialists to bundle with deposition and etch platforms. Long-term viability hinges on exposure to leading-edge node capital cycles rather than legacy 200mm replacement demand. Target acquisition candidates with EUV-compatible overlay metrology IP and established foundry co-development relationships. Watch for inflection when TSMC announces sub-2nm pilot line metrology procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership with Foundry | TSMC's gate-all-around ramp requires node-specific characterization protocol collaboration. |
| Backward Integration into Optical Subassemblies | Zeiss and Trumpf supply concentration demands captive lens production for margin defense. |
| AI-Accelerated Defect Classification Platform | Convolutional neural networks reduce false-positive rates in KLA's broadband plasma inspectors. |
| Subscription-Based Metrology Service Model | Taiwanese vendors unbundle software analytics from hardware to preserve foundry cash flow. |
| Regional Calibration Facility Expansion | India's PLI scheme attracts local service infrastructure to reduce qualification timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged process integration engineers at Taiwan Semiconductor Manufacturing and Samsung Electronics, metrology procurement leads at Intel and SK hynix, equipment vendor product managers at Applied Materials and Tokyo Electron, and calibration service directors at Onto Innovation. Secondary validation drew from SEC 10-K equipment disclosures, SEMI capital expenditure databases, Japan's METI industrial production indices, and EU REACH regulatory filings. Bottom-up wafer fab equipment spend tracking triangulated against top-down semiconductor capital investment forecasts.
Segment-weighting applied product type, technology, end user, and application dimensions across the modeling period. Foundry versus IDM procurement patterns, lithography node migration timelines, and regional regulatory compliance costs fed into growth derivation. CAGR construction incorporated equipment replacement cycles, technology transition inflection points, and geographic capital concentration shifts without year-specific anchoring.
Revisions become necessary when EU F-Gas Regulation amendments accelerate etch fleet retrofit timelines, export control expansions fragment equipment qualification pathways, or single-source component disruptions extend lead times beyond foundry ramp schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
Electron Beam Lithography Machine Market