
 Middle East LED Lighting Market | 2026-2036
Middle East LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East LED Lighting Market Foresight
Market Context
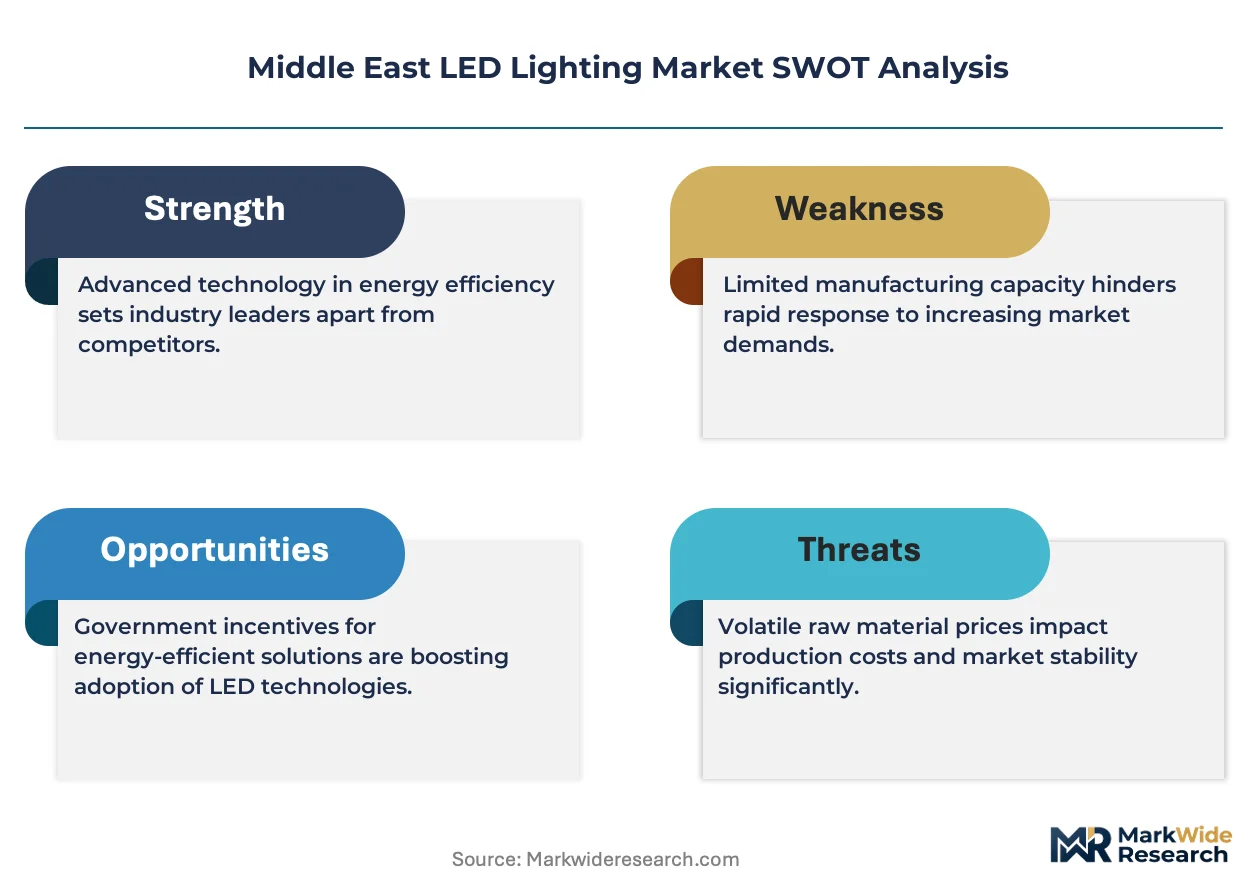
Project finance for municipal streetlight retrofits is tilting competitive dynamics toward vendors with balance-sheet capacity. Signify leverages its Gulf distribution infrastructure to anchor large-scale Dubai and Riyadh contracts. LEDVANCE GmbH competes through regional warehousing partnerships that compress delivery timelines. Al Nasser Group dominates local project execution, sustaining cost advantages on fixture installation and maintenance.
Technical Definition and Segments
Middle East LED lighting comprises solid-state luminaires using semiconductor diodes emitting visible light at 80-150 lumens per watt, engineered for thermal resilience above 50°C ambient operating conditions in desert climates. The technology serves commercial and industrial sectors seeking to cut cooling loads and extend maintenance intervals. Smart LED systems lead technology adoption as building automation integration becomes standard in Gulf commercial developments. Fixture categories command the deepest margin pools, while strip applications expand fastest in retail fit-outs across Saudi malls and UAE hospitality venues.
Regulatory Frame
UAE's Ministry of Energy and Infrastructure efficiency codes, Saudi Standards Metrology and Quality Organization product certification, and Bahrain's Electricity and Water Authority rebate programs collectively reshape procurement specifications and market access requirements. These frameworks mandate minimum efficacy thresholds and restrict incandescent and halogen imports, forcing distributor portfolio restructuring. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks that could unify testing protocols and alter cross-border compliance costs.
Market Dynamics
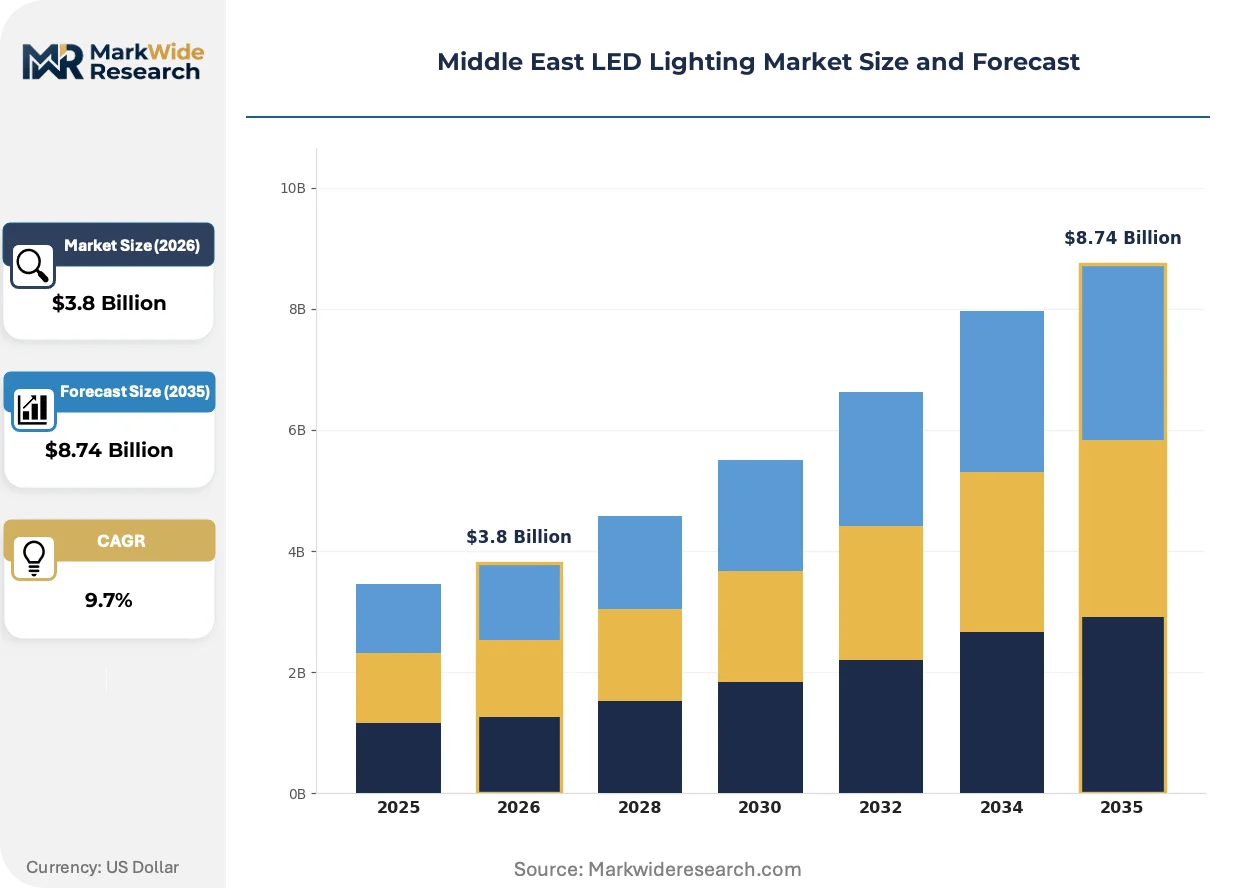
Federal efficiency mandates across Gulf Cooperation Council jurisdictions are compressing procurement cycles and tilting specifications toward smart, connected systems that integrate with building automation infrastructure.
Growth Catalysts
- UAE Federal Efficiency Mandates:The Ministry of Energy and Infrastructure codes mandate minimum efficacy thresholds for commercial retrofits, forcing rapid fixture replacement in Dubai and Abu Dhabi commercial towers.
- Saudi Hospitality Expansion:Giga-project construction in Riyadh and Jeddah generates concentrated demand for architectural LED systems with tunable white and circadian capabilities.
- Thermal Resilience Engineering:Heat-sink innovations enabling 50°C+ ambient operation are unlocking outdoor and industrial applications previously served by conventional HID luminaires.
Market Restraints
- Driver IC Supply Concentration:Semiconductor sourcing for LED power electronics clusters in East Asian foundries, exposing Gulf assemblers to lead-time volatility and currency mismatch risks.
- SASO Certification Complexity:Saudi Standards Metrology and Quality Organization testing protocols extend product registration timelines, delaying market entry for new fixture suppliers.
- Halogen Incumbency in Residential:Price-sensitive villa and apartment segments in Bahrain and Oman continue sourcing legacy filament lamps through informal trade channels.
Strategic Opportunities
- Kuwait Municipal Retrofit Lag:Street and highway lighting infrastructure remains predominantly sodium-vapor, creating a concentrated replacement opportunity as the Ministry of Electricity and Water accelerates LED tenders.
- Human-Centric Lighting in Healthcare:Circadian rhythm systems are penetrating Saudi hospital new-builds, with MOHAP specifications in UAE following the clinical evidence base.
- Li-Fi Convergence:Visible light communication integration with LED fixtures is emerging in Qatar's smart city developments, bundling data transmission with illumination services.
Industry Challenges
- Integration with Legacy BMS:DALI-2 and BACnet protocol mismatches complicate smart LED deployment in 1990s-era commercial stock across Dubai and Riyadh.
- Thermal Engineering Talent Scarcity:Gulf universities produce limited graduates specializing in high-temperature electronics packaging, forcing manufacturers to import design expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East LED Lighting Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Panels Application: Commercial, Residential, Industrial, Outdoor Technology: Smart LED, Solar LED, Conventional LED, High-Bay LED End User: Retail Stores, Offices, Factories, Hotels |
| Companies Covered | Cree Lighting, LEDVANCE GmbH, Signify (Philips Lighting), Panasonic Corporation, Zumtobel Group, ams OSRAM AG, OPPLE Lighting Co., Ltd., Al Nasser Group, Acuity Brands Lighting Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East LED Lighting Market Shifts & Advancements
Connected lighting platforms are redefining competitive advantage, shifting vendor value propositions from lumen output to data services and energy management integration.
Li-Fi technology embeds high-speed data transmission within LED light modulation, enabling wireless connectivity in RF-restricted environments. Qatar's Lusail smart district and Saudi NEOM are piloting the technology for secure indoor positioning and connectivity. The market is migrating from pure illumination hardware toward bundled light-plus-data service contracts.
UAE's Ministry of Energy and Infrastructure efficiency codes now mandate networked lighting controls for commercial buildings above specified floor areas. This regulatory pressure is compressing the installed base of standalone fixtures and accelerating demand for sensor-integrated systems. Saudi Arabia's SASO is harmonizing its product certification with these networked control requirements, creating a unified Gulf procurement specification.
Facility managers in UAE hospitality and Saudi healthcare are unbundling lighting maintenance from traditional MEP contracts, creating dedicated service agreements with performance-based uptime guarantees. Specialized LED service providers are displacing general electrical contractors in Dubai's premium commercial segment. This shift is most visible in five-star hotel portfolios where downtime penalties exceed fixture replacement costs.
Middle East LED Lighting Market Segmentation
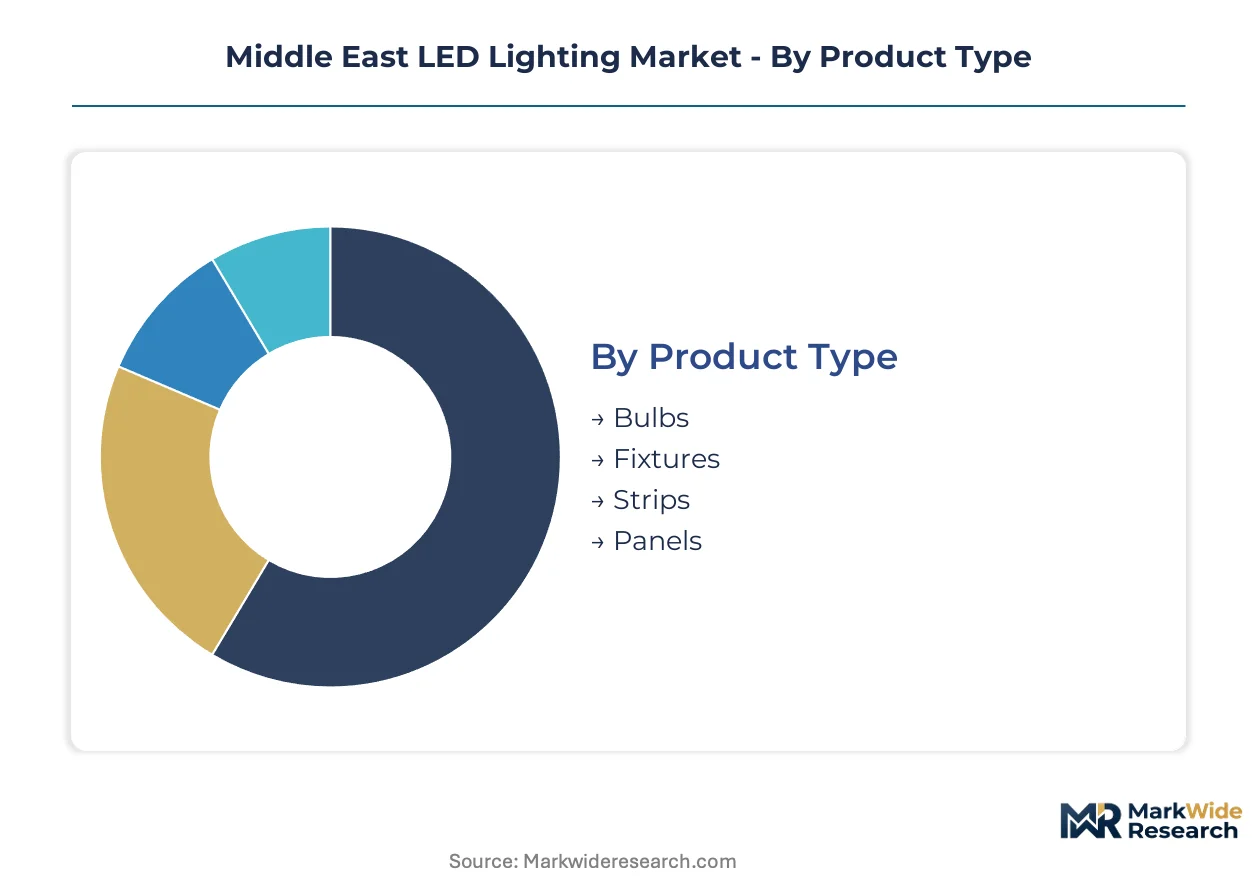
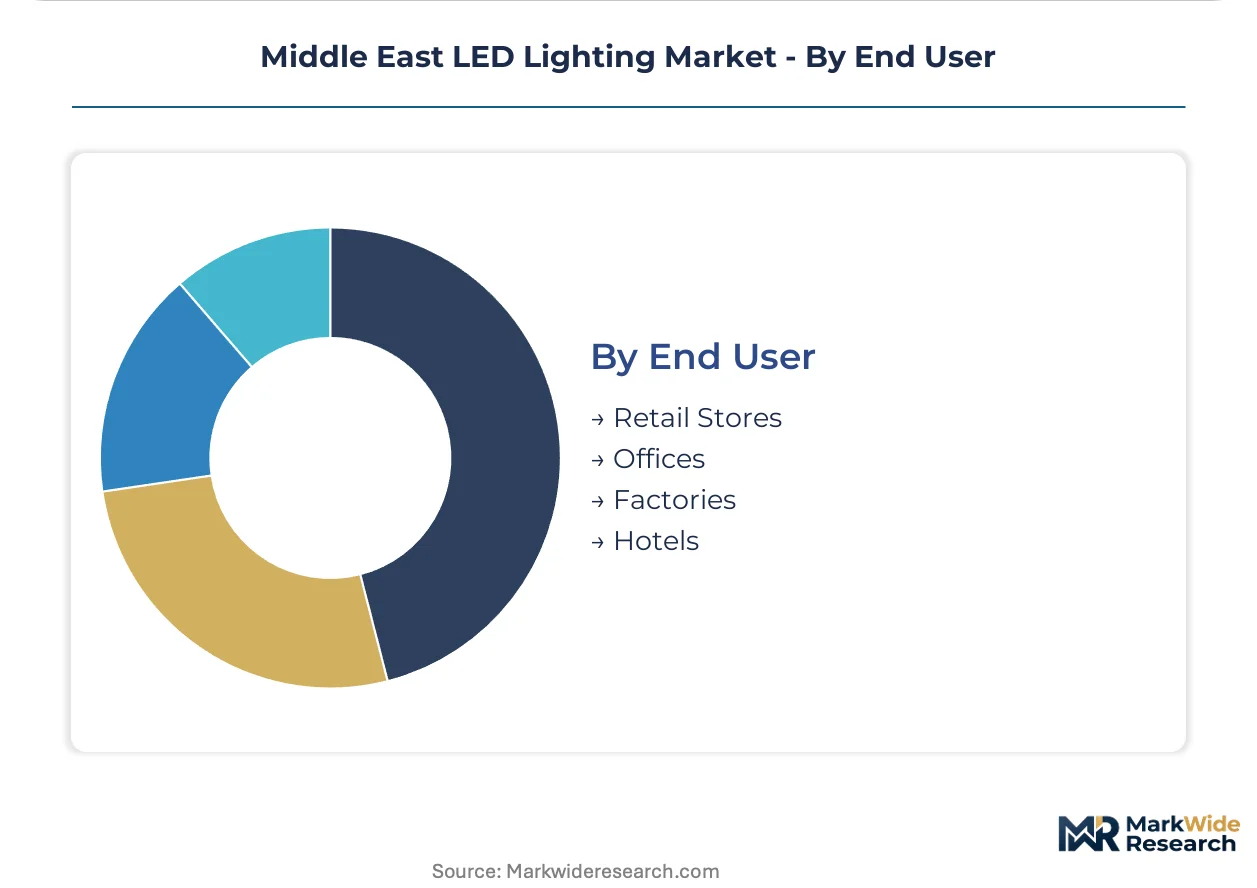
LED lighting segmentation in the Middle East reveals divergent margin structures and service intensity profiles across product architectures and deployment contexts. Procurement patterns vary sharply between specification-driven commercial retrofits and price-sensitive residential replacement cycles.
Product Type:
After-sales service intensity varies dramatically across product categories, with fixtures demanding dedicated maintenance contracts and bulbs operating on transactional replacement models.
- Fixtures:Encompass luminaire housings with integrated drivers, heat sinks, and optical systems engineered for 50,000-hour lifespans in desert thermal conditions. Demand concentrates in Saudi giga-project hospitality developments and Dubai commercial tower retrofits where SASO certification and networked control integration are mandatory specifications. These installations require multi-year service agreements with performance-based uptime guarantees.
- Panels:Flat-form-factor ceiling systems delivering uniform illumination through edge-lit or direct-backlit LED arrays, typically specified at 4000K color temperature for office environments. UAE federal efficiency codes mandate these for commercial buildings above specified floor areas, with procurement bundling controls and commissioning services.
- Bulbs:Retrofit lamps designed for existing Edison or bayonet sockets, serving residential and small commercial replacement demand across Bahrain and Oman price-sensitive segments.
- Strips:Flexible linear LED arrays with adhesive backing, expanding fastest in Saudi retail mall fit-outs and UAE hospitality accent lighting applications.
Fixtures hold the largest share; momentum sits with strips.
Application:
Cost tier stratification separates specification-heavy commercial deployments from budget-constrained residential procurement, with industrial and outdoor segments occupying intermediate positions on engineering intensity.
- Commercial:Encompasses office towers, retail environments, and hospitality venues requiring tunable white, circadian, and networked control capabilities. Dubai and Riyadh commercial stock drives volume, with UAE Ministry of Energy and Infrastructure codes compressing retrofit timelines.
- Industrial:High-bay and hazardous-location luminaires for manufacturing, warehousing, and petrochemical facilities demanding thermal resilience above 50°C ambient operation. Saudi industrial city developments and UAE free zone expansions anchor demand.
- Outdoor:Street, highway, and area lighting infrastructure, with Kuwait Ministry of Electricity and Water tenders representing concentrated replacement opportunity from legacy sodium-vapor base.
- Residential:Villa and apartment lighting across Bahrain and Oman, where halogen incumbency persists through informal trade channels and price-sensitive procurement behavior.
Commercial commands the deepest margin pools; industrial is expanding most quickly on thermal engineering advances.
Technology:
Volume concentration favors conventional LED for baseline replacement, while smart systems capture disproportionate value through controls integration and data service bundling.
- Smart LED:Sensor-integrated luminaires with DALI-2 or BACnet connectivity enabling occupancy detection, daylight harvesting, and energy management dashboard integration. UAE federal mandates and Saudi SASO harmonization are accelerating specification in new commercial builds.
- High-Bay LED:High-lumen-output fixtures for industrial ceiling heights above 6 meters, with thermal engineering enabling 50°C+ ambient operation unlocking outdoor and industrial applications previously served by HID luminaires.
- Conventional LED:Standalone luminaires without networked controls, serving cost-constrained replacement cycles and residential segments across Gulf Cooperation Council markets.
- Solar LED:Off-grid luminaires with photovoltaic panels and battery storage, deployed in remote Saudi and UAE infrastructure where grid extension is uneconomical.
Conventional LED holds the largest share; smart LED is gaining share fastest on regulatory pressure.
End User:
Customer type determines procurement sophistication, with hotels and offices demanding performance-based service contracts while factories prioritize capital efficiency and retail stores balance aesthetics against operating cost.
- Hotels:Five-star hospitality portfolios in Dubai and Riyadh specifying architectural LED with tunable white and circadian capabilities, unbundling lighting maintenance from traditional MEP contracts into dedicated service agreements with downtime penalties exceeding fixture replacement costs.
- Offices:Commercial tower landlords and corporate fit-outs across Abu Dhabi and Jeddah, where UAE federal efficiency codes mandate networked lighting controls and facility managers seek energy management integration.
- Factories:Manufacturing and warehousing operations in Saudi industrial cities and UAE free zones, prioritizing thermal resilience and extended maintenance intervals over controls sophistication.
- Retail Stores:Mall fit-outs and flagship stores across Saudi Arabia and UAE, where strip applications and accent lighting drive fastest expansion in fixture categories.
Hotels hold the largest share; retail stores show the steepest expansion trajectory on mall construction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for driver ICs and thermal management components tilts the Middle East LED lighting trade balance toward deficit, while Saudi Arabia and UAE anchor regional fixture assembly capacity for re-export across Gulf Cooperation Council markets.
Saudi Arabia
Giga-project hospitality construction in Riyadh and Jeddah drives concentrated demand for architectural LED systems with circadian capabilities. SASO certification mandates compress procurement timelines for international suppliers. The Red Sea coastal corridor hosts emerging fixture assembly clusters serving NEOM and Qiddiya developments.
United Arab Emirates
Dubai commercial tower retrofits and Abu Dhabi federal building efficiency programs sustain specification-grade fixture demand. Ministry of Energy and Infrastructure codes mandate networked lighting controls above threshold floor areas. Jebel Ali free zone distribution infrastructure anchors Gulf-wide logistics for multinational lighting vendors.
Qatar
Lusail smart district deployment pilots Li-Fi integration within LED fixtures for secure indoor positioning. Qatar General Electricity and Water Corporation tenders accelerate streetlight replacement from legacy sodium-vapor infrastructure. Doha hospitality and retail fit-outs concentrate demand for tunable white accent systems.
Kuwait
Ministry of Electricity and Water municipal retrofit programs lag regional peers, preserving concentrated replacement opportunity across street and highway networks. Residential villa segments remain price-sensitive, delaying LED penetration versus Gulf averages. Kuwait City commercial stock drives limited specification-grade demand through landlord-driven efficiency upgrades.
Bahrain
Electricity and Water Authority rebate programs reshape procurement specifications for commercial retrofits in Manama financial district. Residential halogen incumbency persists through informal trade channels from Saudi Arabia. Bahrain Investment Wharf hosts regional warehousing partnerships compressing delivery timelines for GCC re-export.
Middle East LED Lighting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Middle East LED lighting market structures around three tiers: multinational fixture vendors with Gulf distribution infrastructure, regional assemblers leveraging local certification expertise, and component distributors managing East Asian semiconductor sourcing. Competitive dynamics tilt toward vendors with balance-sheet capacity for project finance and multi-year service agreements. Consolidation pressure concentrates among mid-scale assemblers facing SASO compliance cost escalation.
Among multinational platform vendors, Signify and LEDVANCE GmbH exemplify divergent Gulf penetration strategies. Signify anchors large-scale Dubai and Riyadh contracts through captive distribution infrastructure. LEDVANCE competes via regional warehousing partnerships compressing delivery timelines. Al Nasser Group represents the local execution archetype, sustaining cost advantages on fixture installation and maintenance through project labor force scale.
| Leading Market Players |
|---|
| Cree Lighting |
| LEDVANCE GmbH |
| Signify (Philips Lighting) |
| Panasonic Corporation |
| Zumtobel Group |
| ams OSRAM AG |
| OPPLE Lighting Co., Ltd. |
| Al Nasser Group |
| Acuity Brands Lighting Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in East Asian semiconductor foundries is compressing driver IC pricing and tilting Gulf assemblers toward spot-market procurement rather than long-term contracts. This utilization slack cascades into fixture manufacturing economics, where Saudi and UAE-based vendors gain component sourcing leverage even as finished-product pricing faces pressure from regional certification mandates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Middle East LED lighting market. Price differentiation separates SASO-certified fixtures with networked controls from basic retrofit lamps and thermal-engineered industrial luminaires. Cost compression in the residential bulb tier is intensifying because of informal halogen imports through Bahrain and Oman trade channels. Factories and warehousing operations exhibit the highest price sensitivity, while five-star hospitality portfolios in Dubai and Riyadh prioritize performance-based service contracts over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment are constraining driver IC production expansion outside East Asia, limiting supply diversification for Gulf lighting assemblers. Component sourcing draws from Taiwan, South Korea, and China for LED power electronics, with aluminum heat sinks and optical-grade polymers feeding from GCC-adjacent extrusion facilities. Single-source vulnerability concentrates in East Asian foundry capacity for thermal management controllers. Distribution runs through Jebel Ali free zone warehousing partnerships that compress delivery timelines across Saudi Arabia, UAE, and Qatar project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East LED lighting market builds defensive moats through regulatory entrenchment, where SASO certification complexity and UAE federal efficiency mandates create switching costs that lock in incumbent vendors with established compliance infrastructure.
For Market Incumbents: Harden project finance capabilities to anchor municipal streetlight retrofits in Kuwait and Saudi giga-developments, where balance-sheet capacity determines contract access against emerging regional assemblers. Deepen backward integration into thermal management controller sourcing to offset East Asian semiconductor lead-time volatility. SASO harmonization with UAE networked control requirements threatens mid-scale assemblers lacking certification investment scale. For New Entrants and Emerging Players: Build out dedicated LED service agreements with performance-based uptime guarantees in Dubai's premium commercial segment, where facility managers are unbundling lighting maintenance from traditional MEP contracts. Kuwait municipal retrofit programs lag regional peers, offering a concentrated replacement opportunity from legacy sodium-vapor infrastructure. Target healthcare circadian rhythm specifications in Saudi hospital new-builds as the clinical evidence base hardens procurement requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized LED service providers displacing general electrical contractors in five-star hospitality portfolios, where multi-year maintenance contracts generate predictable cash flows. Long-term viability centers on vendors controlling Gulf distribution infrastructure and certification expertise rather than pure manufacturing scale. Acquisition targets should show established SASO registration portfolios and Jebel Ali logistics integration. The signal to monitor is MOHAP circadian specification adoption across UAE healthcare new-builds, which would validate human-centric lighting as a durable premium tier.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Accelerates market entry timelines for international fixture suppliers facing Saudi regulatory mandates. |
| Li-Fi Technology Integration | Bundles data transmission with illumination services in Qatar's Lusail smart district pilots. |
| Regional Warehousing Partnership | Compresses delivery timelines for multinational vendors competing against Al Nasser Group's local execution. |
| Circadian System Development | Captures specification-grade demand from Saudi MOHAP and UAE healthcare new-build requirements. |
| Project Finance Capability Buildout | Determines competitive access to Kuwait Ministry of Electricity and Water municipal retrofit tenders. |
Research Methodology
A standing panel of lighting specification engineers, facility management directors at Dubai commercial towers, SASO certification consultants, and Kuwait Ministry of Electricity and Water procurement officers provided ongoing calibration across primary fieldwork. Secondary validation drew from UAE Ministry of Energy and Infrastructure code filings, Saudi Standards Metrology and Quality Organization product registries, Gulf Cooperation Council customs trade data, and hospitality development pipeline disclosures. Bottom-up fixture demand modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario bracketing around regulatory implementation pace, semiconductor supply normalization, and giga-project construction timelines shaped projection sensitivity bands across the analysis window. Segmentation dimensions modeled include product architecture, application context, technology tier, and end-user procurement sophistication. CAGRs were derived from installed base replacement cycles, new-build penetration curves, and efficiency mandate compliance deadlines. Thermal resilience engineering advances and networked control integration rates served as industry-specific forecast inputs.
Stress conditions across East Asian foundry utilization, Gulf Cooperation Council regulatory harmonization progress, and Saudi giga-project funding continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline compression and smart LED specification adoption. Material shifts in UAE-Saudi regulatory harmonization talks or unexpected driver IC supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Four-Digit 7 Segment LED Displays Market
LED
LED Chip Market
LED
GCC LED Lighting Market
LED
Microled Market
LED
LED Panel Market
LED
China Outdoor LED Lighting Market
LED
LED Encapsulation Market
LED
LED Control Unit Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
North America Outdoor LED Lighting Market
LED
Africa LED Lighting Market
LED
UAE LED Lights Market
LED
Global Waterproof LED Module Market
LED
UK LED Lighting Market
LED
LED Driver Market
LED
Gan Substrate Market