
 FOUP Load Port Market | 2026-2036
FOUP Load Port Market Size, Share, and Industry Trends Forecast 2026-2036
FOUP Load Port Market Foresight
Leading foundries is collapsing legacy manual handling protocols across new 300mm wafer fabrication facilities. Brooks Automation leverages deep vertical integration into vacuum handling subsystems to sustain equipment leadership at advanced nodes. RORZE anchors its position through specialized non-contact magnetic transport architectures that dominate Japanese fab retrofits. Hirata competes aggressively on cost-engineered pneumatic solutions for mid-tier foundry expansions in Southeast Asia.
A FOUP Load Port constitutes the precision mechanical interface that docks Front Opening Unified Pods to process equipment, typically achieving particle counts below 0.1 particles per cubic foot at 0.1 micrometers through sealed nitrogen purge systems. Automatic Load Port configurations command premium positioning as fabs eliminate human intervention in Class 1 cleanroom zones. Non-contact magnetic technology segments attract accelerated engineering investment where wafer edge damage risks from mechanical gripping threaten yield at sub-7nm nodes. Semiconductor Manufacturing applications absorb the dominant share of unit demand, though Research Laboratories represent a margin-rich niche for multi-pod handling configurations.
ISO 14644 cleanroom classifications and SEMI E15.1 mechanical interface standards govern dimensional tolerances and contamination limits across all supplier designs. Japan's METI semiconductor revitalization subsidies and South Korea's K-Battery/K-Semiconductor tax credits directly expand load port procurement budgets at domestic fabrication sites. Taiwan's Industrial Development Bureau enforces localized supply chain requirements that shape vendor qualification timelines for foreign equipment providers. Stakeholders must monitor which handling technology standard—contact, vacuum, or magnetic—emerges as the default for next-generation GAA transistor production architectures.
Market Dynamics
Advanced node semiconductor manufacturing is forcing fabs to eliminate particle contamination at the wafer-handling interface, driving wholesale replacement of legacy mechanical load port architectures with sealed nitrogen-purge systems that satisfy ISO 14644 Class 1 requirements.
Growth Catalysts
- Sub-7nm Node Migration:Taiwan Semiconductor Manufacturing and Samsung Foundry require non-contact magnetic handling architectures to prevent edge damage during GAA transistor production ramp-ups.
- Japan's METI Subsidies:Domestic semiconductor revitalization funding expands procurement budgets for automated load port retrofits at legacy 300mm fabrication facilities.
- SEMI E15.1 Standardization:Unified mechanical interface specifications reduce qualification timelines for multi-vendor fab tool integration, accelerating equipment refresh cycles.
Market Restraints
- Specialized Component Concentration:Precision linear motion bearings and ceramic wafer-lift mechanisms depend on concentrated supply from Japanese and German precision manufacturers.
- Cleanroom Construction Backlogs:Extended lead times for HEPA filtration infrastructure and vibration-isolation flooring delay load port commissioning at greenfield fab sites.
- Technical Integration Complexity:Legacy pneumatic load ports lack the sensor density required for AMHS host communication protocols, forcing complete subsystem replacement rather than upgrade.
Strategic Opportunities
- Research Laboratory Niche:Multi-pod handling configurations for materials science and photonics R&D command margin premiums above semiconductor manufacturing volumes.
- South Korea Tax Credits:K-Semiconductor incentives reduce effective equipment costs for domestic foundry expansions at Pyeongtaek and Yongin clusters.
- Edge Computing Fab Buildouts:Specialty 200mm wafer facilities for power semiconductors and RF devices create demand for cost-engineered load port variants outside leading-edge nodes.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-disciplinary engineering expertise combining precision mechanics, vacuum technology, and semiconductor process knowledge remains concentrated at established equipment suppliers.
- SEMI S2/S8 Certification Timelines:Safety and ergonomics compliance documentation for new load port designs extends vendor qualification periods by 8-14 months at risk-averse memory manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FOUP Load Port Market |
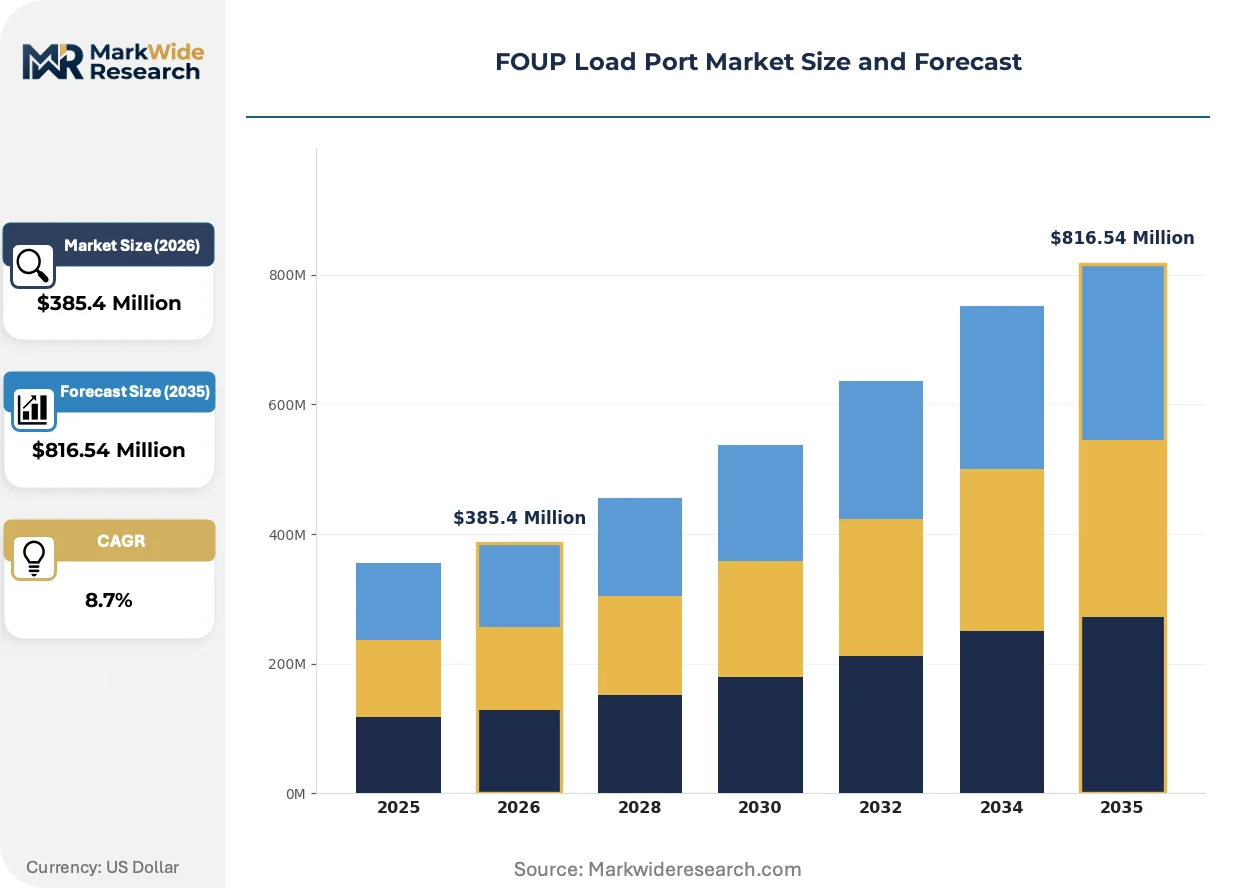
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Load Port, Automatic Load Port, Semi-Automatic Load Port, Cassette Load Port Technology: Contact, Non-Contact, Vacuum, Magnetic, Pneumatic Application: Semiconductor Manufacturing, Wafer Processing, Cleanroom Automation, Photolithography End User: Wafer Fabrication Plants, Foundries, Equipment Suppliers, Research Laboratories |
| Companies Covered | MEIKIKOU, RORZE, TDK, GL Automation, Hirata, Brooks Automation, Genmark Automation, Hung Ching Development, Kensington, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FOUP Load Port Market Shifts & Advancements
Wafer-handling architecture is diverging along contamination-control performance tiers, with magnetic and vacuum technologies displacing mechanical gripping at advanced nodes while pneumatic solutions retain relevance in cost-sensitive segments.
Non-contact magnetic levitation transport is fragmenting competitive positioning between equipment tiers. This technology suspends FOUPs using permanent magnet arrays, eliminating particle-generating friction from mechanical guides. Leading memory manufacturers in South Korea and Taiwan are adopting magnetic load ports for sub-5nm DRAM and NAND production. The technology is fragmenting supplier market share, creating distinct premium and standard equipment categories based on magnetic subsystem inclusion.
Japan's METI semiconductor equipment subsidies are redirecting domestic procurement toward locally manufactured load port systems. The policy mandates domestic content thresholds for subsidy eligibility, compressing foreign vendor market access. Japanese foundry retrofits in Hiroshima and Kagoshima are prioritizing domestic-qualified equipment under these requirements. Equipment suppliers are responding with localized assembly partnerships and joint venture manufacturing arrangements.
Fab operators are consolidating load port maintenance contracts under multi-year service agreements bundled with AMHS infrastructure. This displaces transactional spare parts procurement and spot-repair dispatch models. Memory manufacturers in Taiwan and South Korea are negotiating enterprise-level service contracts covering entire fab load port fleets. The shift is most visible at greenfield facilities where total cost of ownership calculations dominate capital approval processes.
FOUP Load Port Market Segmentation
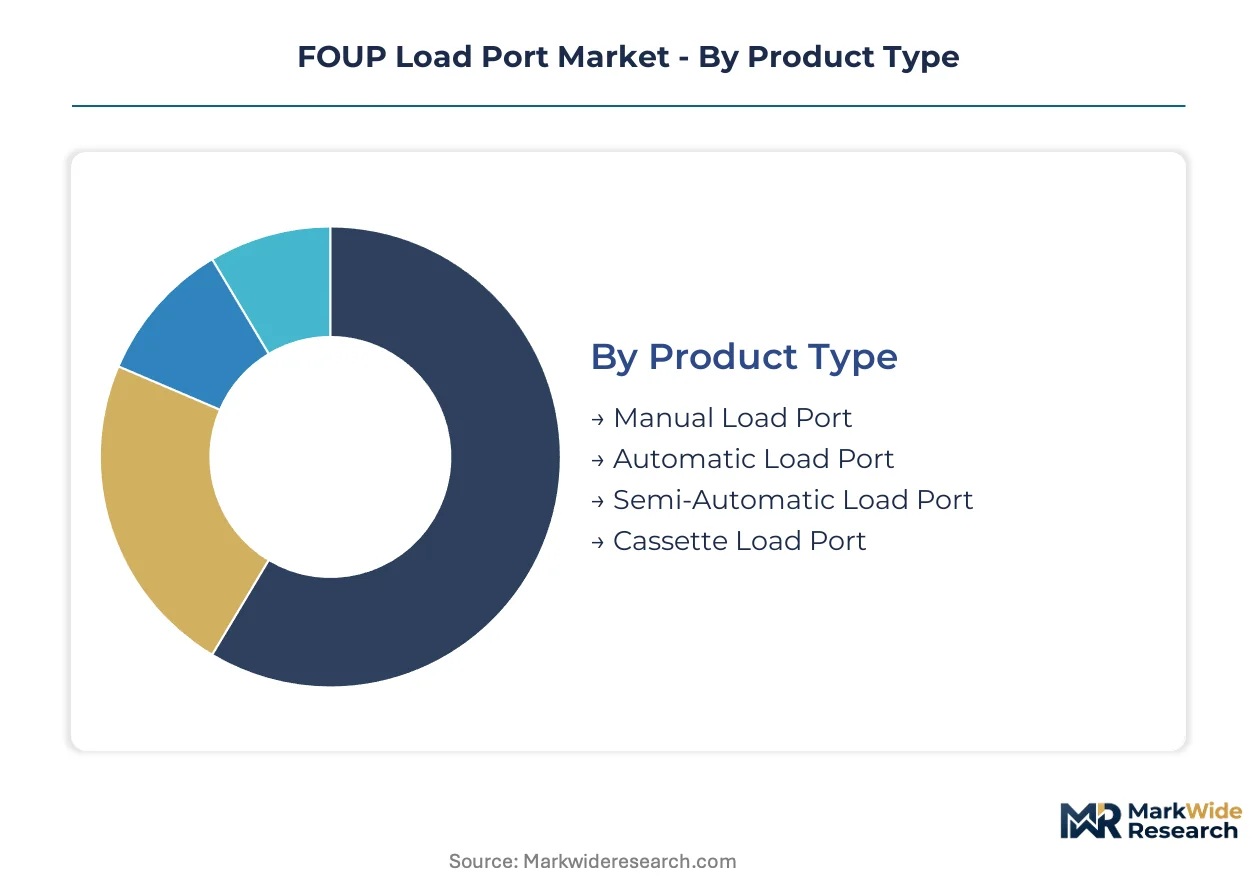
FOUP Load Port procurement patterns diverge sharply across handling automation levels, contamination-control technologies, and end-use cleanliness requirements. Each segmentation axis reveals distinct margin architectures tied to semiconductor node advancement and facility retrofit cycles.
Product Type:
Margin pools concentrate in configurations that eliminate human intervention from Class 1 cleanroom zones, where particle contamination risks escalate at sub-7nm production.
- Automatic Load Port:Fully sealed nitrogen-purge systems achieve particle counts below 0.1 particles per cubic foot at 0.1 micrometers through integrated AMHS host communication. Taiwan Semiconductor Manufacturing and Samsung Foundry specify these for all new 300mm greenfield fabs to satisfy ISO 14644 Class 1 protocols.
- Manual Load Port:Legacy mechanical docking interfaces retain relevance in 200mm specialty fabs and research environments where capital constraints outweigh contamination risks. Japanese equipment suppliers dominate refurbishment demand at legacy facilities in Hiroshima and Kagoshima clusters.
- Semi-Automatic Load Port:Hybrid configurations bridge operator-assisted loading with partial sensor automation for mid-tier foundry expansions.
- Cassette Load Port:Older wafer cassette interfaces serve niche 150mm and 200mm legacy tool compatibility requirements.
The dominant share belongs to Automatic Load Port configurations, while Semi-Automatic Load Port is closing the gap fastest in Southeast Asian cost-optimized expansions.
Technology:
Technology selection tracks directly with wafer edge damage sensitivity, where mechanical contact risks escalate as transistor dimensions shrink below 5nm.
- Magnetic:Permanent magnet arrays suspend FOUPs without friction-generating mechanical guides, eliminating particle sources critical for GAA transistor production. South Korean memory manufacturers at Pyeongtaek deploy these for sub-5nm DRAM and NAND ramp-ups.
- Vacuum:Suction-based handling through precision orifice plates grips wafer surfaces without edge contact, dominating photolithography tool integration where substrate flatness requirements are most stringent.
- Non-Contact:Optical or ultrasonic positioning systems serve specialized metrology and inspection equipment.
- Pneumatic:Compressed-air actuation retains cost advantages in 200mm power semiconductor and RF device facilities where node advancement pressures are muted.
- Contact:Mechanical gripping mechanisms persist only in lowest-cost legacy retrofits and non-semiconductor industrial applications.
Magnetic handling commands the steepest expansion trajectory among advanced node manufacturers, though Pneumatic solutions defend volume leadership in mature-node segments.
Application:
Application segmentation reflects cleanliness tier requirements, with photolithography imposing the most stringent handling specifications.
- Semiconductor Manufacturing:Front-end wafer fabrication absorbs the dominant equipment volume, spanning diffusion, etch, and deposition tool integration with standardized SEMI E15.1 mechanical interfaces.
- Photolithography:Scanner and stepper tool docking demands vibration-isolated precision positioning with sub-micron repeatability, commanding the highest per-unit pricing in the category.
- Wafer Processing:Back-end grinding, dicing, and packaging operations utilize simplified load port variants with reduced purge specifications.
- Cleanroom Automation:AMHS integration and inter-bay transport systems require specialized load port configurations for overhead hoist compatibility.
Semiconductor Manufacturing retains the dominant share, while Photolithography is expanding most quickly as EUV scanner deployments accelerate.
End User:
End user segmentation separates high-volume fleet procurement from specialized low-volume configurations with diverging service contract structures.
- Wafer Fabrication Plants:Integrated device manufacturers operate captive load port fleets with enterprise-level multi-year maintenance agreements bundled with AMHS infrastructure.
- Foundries:Pure-play foundries prioritize vendor qualification speed and standardization across multi-vendor tool sets to minimize downtime during process technology transitions.
- Equipment Suppliers:OEM integration demand concentrates on compact footprint designs for cluster tool and single-wafer processing equipment.
- Research Laboratories:Materials science and photonics R&D facilities specify multi-pod handling configurations with flexible pod size compatibility, capturing margin premiums above manufacturing volumes.
Wafer Fabrication Plants command the dominant procurement volume, while Research Laboratories are gaining share fastest on margin-rich specialized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese equipment manufacturers export precision load port systems to Taiwan's foundry clusters and South Korea's memory fabs, establishing the dominant trade corridor in this specialized semiconductor handling segment.
Taiwan
TSMC and United Microelectronics operate the world's densest concentration of 300mm wafer fabrication capacity, driving automatic load port procurement for ISO 14644 Class 1 cleanroom compliance. Taiwan's Industrial Development Bureau enforces localized supply chain requirements that extend foreign vendor qualification timelines. The Hsinchu Science Park anchors demand as foundries retrofit existing lines for GAA transistor production.
South Korea
Samsung Foundry and SK Hynix require non-contact magnetic handling architectures for sub-5nm DRAM and NAND manufacturing ramp-ups. South Korea's K-Semiconductor tax credits under the K-Battery/K-Semiconductor initiative directly reduce equipment procurement costs at Pyeongtaek and Yongin clusters. The Pyeongtaek semiconductor complex represents the fastest-growing load port installation site outside Taiwan.
Japan
Domestic memory manufacturers and equipment suppliers maintain captive demand for precision load port retrofits at legacy 300mm facilities. Japan's METI semiconductor revitalization subsidies mandate domestic content thresholds that redirect procurement toward locally manufactured systems. The Hiroshima and Kagoshima fab clusters prioritize domestic-qualified equipment under these subsidy requirements.
China
SMIC and Hua Hong Semiconductor expand 300mm fabrication capacity despite technology access restrictions, creating demand for cost-optimized load port configurations. China's MIIT semiconductor self-sufficiency directives accelerate localization requirements for fab equipment procurement. The Yangtze River Delta and Beijing-Tianjin-Hebei regions concentrate new greenfield fab construction with extended commissioning timelines.
United States
Intel's Ohio and Arizona fab expansions and Applied Materials' equipment integration demand anchor North American load port procurement. The CHIPS and Science Act manufacturing subsidies expand capital equipment budgets at domestic fabrication sites. The Phoenix metro area and Greater Columbus region host the primary greenfield construction activity with cleanroom infrastructure backlogs delaying equipment commissioning.
FOUP Load Port Market Competitive Landscape
Listed automation specialists compete with private Japanese component fabricators across precision handling subsystem integration, producing a tiered market structure where scale advantages concentrate in publicly traded equipment platforms while technical specialization remains fragmented among regional suppliers. Three strategic archetypes dominate: vacuum handling subsystem integrators, magnetic levitation technology developers, and pneumatic cost-engineering specialists. Competitive dynamics center on backward integration into precision motion control components and multi-year AMHS service contract bundling.
Within the vacuum handling tier, Brooks Automation exemplifies platform-scale positioning through captive subsystem integration, while RORZE anchors the magnetic levitation segment with specialized non-contact architectures. Hirata occupies a position in cost-engineered pneumatic solutions for mature-node applications. These three manufacturers represent the dominant competitive anchors across the technology spectrum, with Brooks Automation and RORZE commanding premium positioning at advanced nodes and Hirata defending volume in cost-optimized segments.
| Leading Market Players |
|---|
| MEIKIKOU |
| RORZE |
| TDK |
| GL Automation |
| Hirata |
| Brooks Automation |
| Genmark Automation |
| Hung Ching Development |
| Kensington |
| Others |
Supply & Pricing Matrix
Twenty-six-week lead times for ceramic wafer-lift mechanisms from Japanese precision manufacturers concentrate pricing power among established equipment suppliers while compressing margins for second-tier vendors unable to secure preferential allocation.
Pricing Analysis
Next-generation magnetic levitation systems command 40-60% premiums over pneumatic equivalents, while vacuum-handling configurations occupy a narrowing mid-tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ISO 14644 Class 1 qualified systems capture margin premiums, while non-certified retrofits compete on equipment cost alone. Cost compression in pneumatic segments is intensifying because Southeast Asian foundries prioritize capital expenditure minimization over contamination-control performance. Research laboratories exhibit the lowest price sensitivity due to low-volume, high-customization procurement patterns.
Supply Chain Analysis
Inbound logistics costs from Yokohama to Hsinchu Science Park have tightened container availability for precision linear motion bearing shipments, forcing suppliers to air-freight critical subassemblies. Manufacturing concentration rests on Japan, Taiwan, and Germany for ceramic bearings, precision orifice plates, and permanent magnet arrays. Raw material dependencies draw from rare earth magnet supply chains, high-purity aluminum oxide ceramics, and specialty stainless steel alloys. Single-source vulnerability concentrates in Japanese ceramic component fabricators serving sub-5nm node equipment. Distribution runs through AMHS integrators and direct OEM supply contracts to fab operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FOUP Load Port demand sits in early-cycle expansion as GAA transistor production ramps drive wholesale replacement of mechanical handling architectures across Taiwan and South Korea.
For Market Incumbents: Compound defensive positioning through backward integration into ceramic wafer-lift mechanism production and captive magnet array fabrication, neutralizing supply concentration risks from Japanese component suppliers while locking in margin capture at advanced nodes threatened by emerging magnetic levitation specialists. For New Entrants and Emerging Players: Differentiate on service contract bundling for mid-tier Southeast Asian foundries where incumbent AMHS integration lock-in remains incomplete, targeting cost-optimized pneumatic retrofits in Malaysia and Vietnam with localized maintenance partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial automation parents with under-monetized semiconductor handling divisions, presenting acquisition opportunities where magnetic subsystem IP can be extracted and scaled against the 5-10 year node advancement cycle; watch for inflection when South Korean memory manufacturers announce sub-3nm DRAM production timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Subsystem Integration | Brooks Automation and RORZE anchor premium positioning through captive permanent magnet array production for GAA node equipment. |
| Localized Assembly Partnerships | Foreign vendors compress METI subsidy exclusion risks through joint ventures with Japanese precision manufacturers at Hiroshima clusters. |
| Multi-Year Service Contract Bundling | Taiwan Semiconductor Manufacturing and SK Hynix consolidate fleet maintenance under enterprise AMHS agreements, displacing transactional spare parts procurement. |
| Research Laboratory Multi-Pod Configurations | Materials science and photonics R&D facilities capture margin premiums above semiconductor manufacturing through flexible pod size compatibility. |
| SEMI E15.1 Standardization Investment | Unified mechanical interface specifications reduce qualification timelines for multi-vendor fab tool integration at Samsung Foundry expansions. |
Research Methodology
The analysis maps automatic, semi-automatic, and manual load port configurations, each validated through equipment procurement managers at foundry operators, AMHS integration specialists, cleanroom engineering consultants, and aftermarket service directors. Primary interviews combined with secondary validation from SEMI equipment shipment databases, ISO 14644 certification registries, customs trade records for precision ceramic imports, and foundry capital expenditure disclosures. Bottom-up unit demand modeling triangulated against top-down fab construction pipeline assessments.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include automation level, handling technology type, application cleanliness tier, end-user procurement structure, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis tied to node migration timelines and greenfield fab commissioning schedules. Industry-specific inputs incorporated SEMI E15.1 interface adoption rates and METI subsidy disbursement trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained sub-7nm node investment and stable rare earth magnet supply chains; material deviation in either assumption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market