
 Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market | 2026-2036
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market Analytics
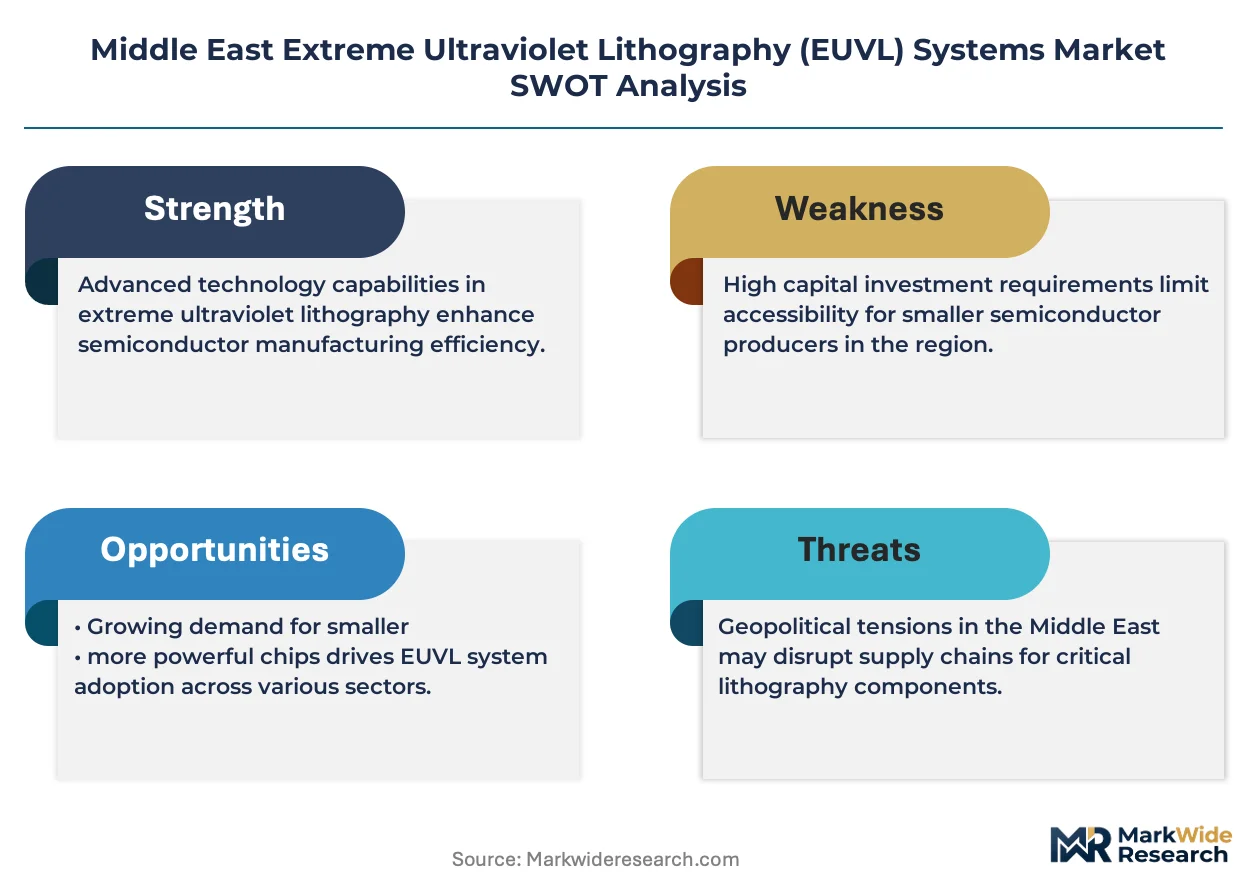
ISO 14644 cleanroom certification is reorganizing which vendors can supply EUVL infrastructure into Middle East fabs. ASML Holding NV dominates lithography tool provision and extends its influence through service-lock-in contracts. Carl Zeiss AG specializes in optical component fabrication for EUVL source assemblies. TRUMPF anchors laser source supply with manufacturing scale that competitors struggle to replicate.
Extreme Ultraviolet Lithography systems employ 13.5 nanometer wavelength light generated by tin plasma excitation to pattern silicon wafers at sub-7 nanometer resolution. The technology relies on vacuum environments and reflective optics because EUV light absorbs in air and conventional lenses. Source Lasers command the steepest capital allocation within product categories due to power scaling requirements. Foundries represent the most concentrated end user segment as Integrated Device Manufacturers in the region remain limited in number.
SFDA and MOHAP frameworks govern occupational exposure limits for hazardous materials used in EUVL source maintenance across Saudi Arabia and the UAE. The EU Green Deal's extraterritorial carbon border provisions pressure Middle East fabs to document supply chain emissions for EU-bound chip exports. Stakeholders must monitor how rapidly local regulators transpose IEC semiconductor equipment standards into binding national requirements.
Market Dynamics
ASML's service-lock-in contracts are consolidating vendor relationships across Middle East foundries, compressing competitive entry points while simultaneously accelerating technology transfer timelines for domestic engineering teams.
Growth Catalysts
- EU AI Act extraterritoriality:Data sovereignty mandates are redirecting AI chip demand toward EUVL-capable domestic fabrication in the UAE and Saudi Arabia.
- Semiconductor cluster formation:Abu Dhabi and Riyadh are concentrating capital allocation for advanced node infrastructure through sovereign wealth deployment.
- IEC 61508 functional safety standards:Local transposition of semiconductor equipment safety frameworks is streamlining import clearance for EUVL systems.
Market Restraints
- Tin supply concentration:Laser-produced plasma EUVL sources depend on high-purity tin feedstock concentrated in Southeast Asian refining operations.
- Optics fabrication bottleneck:Zeiss-grade reflective multilayer mirror production remains limited to single-source supply chains in Germany.
- SFDA hazardous substance protocols:Occupational exposure documentation requirements for tin hydride and xenon handling are extending facility commissioning timelines in Saudi Arabia.
Strategic Opportunities
- Backward integration into source laser components:Local assembly of TRUMPF-style CO2 laser subsystems could reduce import dependency for UAE foundries.
- MOHAP fast-track certification pathways:Dubai's regulatory sandbox for advanced manufacturing equipment is compressing qualification timelines for EUVL infrastructure.
- Desalination-semiconductor convergence:Co-location of EUVL fabs with reverse osmosis facilities addresses ultrapure water requirements while sharing energy infrastructure.
Industry Challenges
- EUV photoresist chemist scarcity:The region lacks experienced formulation specialists for metal oxide resists required at 3nm resolution.
- ISO 14644 Class 1 cleanroom construction:Local contractors have limited track records building vibration-isolated environments for EUVL tool housing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market |
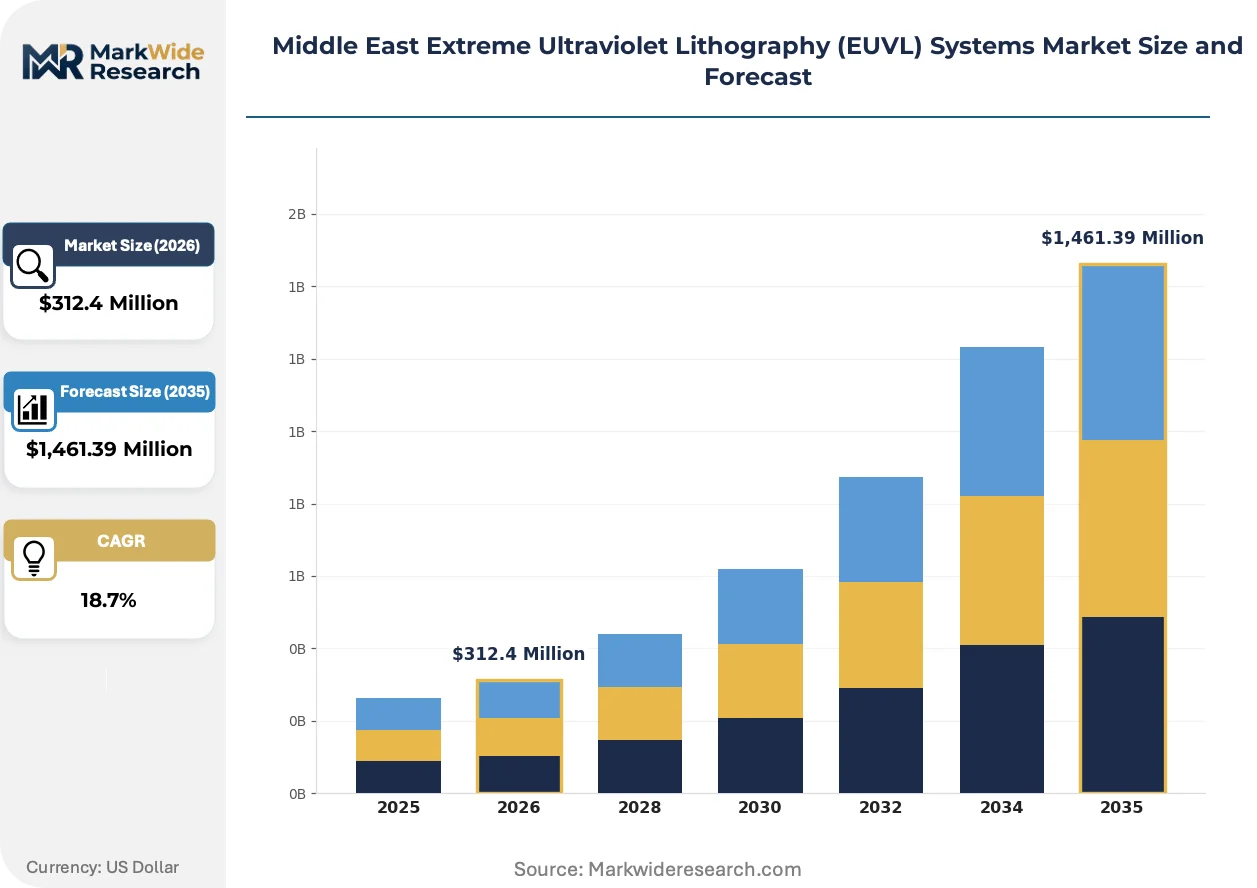
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask/Etch Systems, Wafer Handling, Photomasks, Source Lasers Application: Semiconductor Manufacturing, Flat Panel Displays, Photonics, Advanced Packaging End User: Foundries, Integrated Device Manufacturers, Research Institutions, Fabless Companies Technology: Double Patterning, Immersion Lithography, Optical Lithography, Others |
| Companies Covered | ASML Holding NV, Carl Zeiss AG, TRUMPF, AGC Inc., KLA Corporation, Applied Materials Inc., Canon Inc., Nikon Corporation, SUSS MicroTec SE, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market Evolving Landscape
Reflective optics architecture is displacing conventional refractive systems across patterning workflows, while regulatory frameworks and procurement behaviors are simultaneously reconfiguring vendor-customer relationships in Middle East semiconductor manufacturing.
High-NA EUVL optics are displacing 0.33 numerical aperture systems in leading-edge foundry roadmaps. Saudi Aramco-backed fabrication ventures are prioritizing 0.55 NA tool procurement for 2nm-class production. This optical generation shift is compressing depreciation schedules for installed 0.33 NA capacity and accelerating secondary market formation.
The EU Green Deal's Carbon Border Adjustment Mechanism is imposing emissions documentation requirements on EU-bound semiconductor exports. Middle East fabs must now track Scope 3 supply chain emissions for EUVL tool manufacturing and operation. Abu Dhabi-based foundries are responding by procuring renewable energy certificates for source laser power consumption.
Long-term service contracts are replacing transactional maintenance arrangements across EUVL system procurement. Foundry operators in Riyadh are bundling 10-year source availability guarantees with initial tool purchases, shifting vendor revenue toward recurring service streams. This contractual evolution is most pronounced in UAE-Saudi bilateral technology partnerships where sovereign entities prioritize operational continuity over capital expenditure optimization.
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market Segmentation
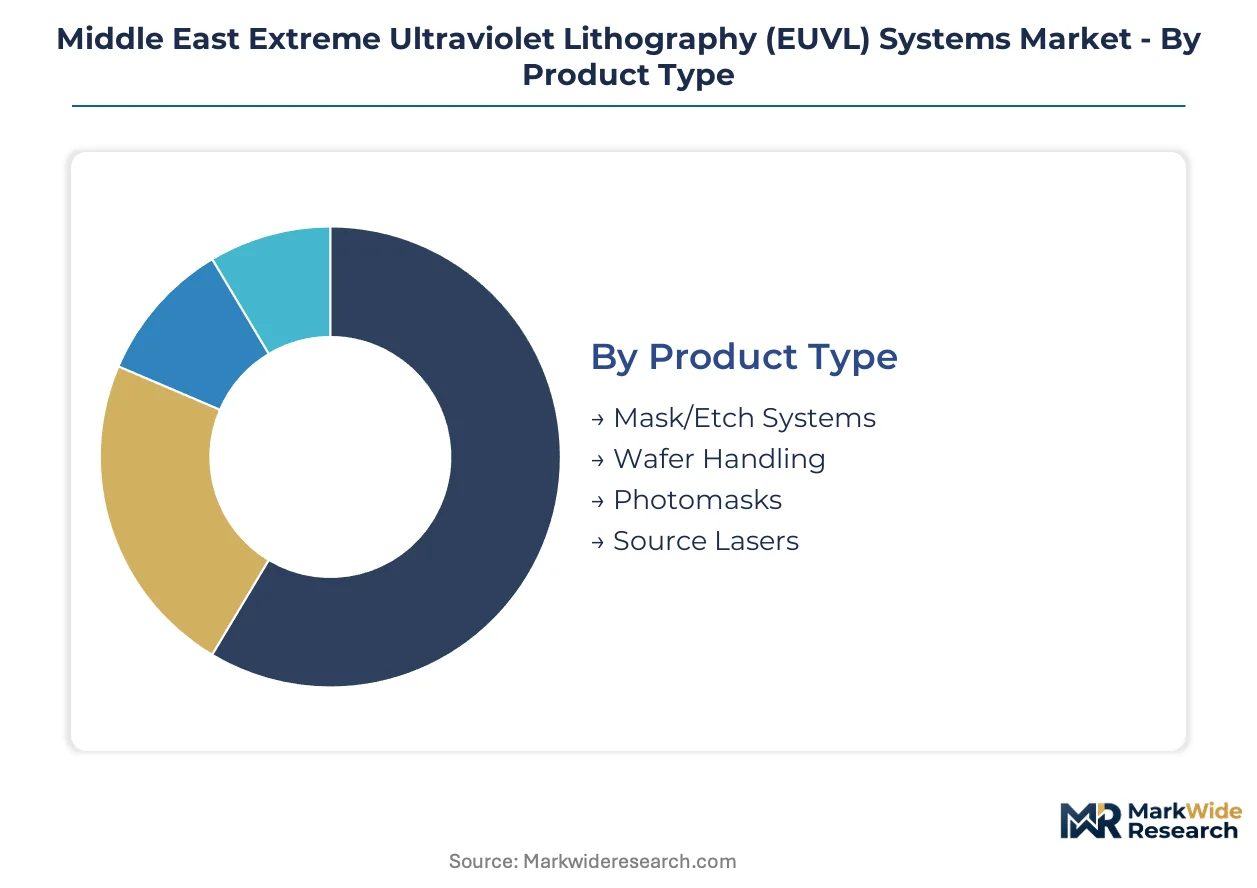
EUVL system procurement in the Middle East diverges sharply by technical subsystem and end-use application. Each segment carries distinct supplier dependencies and regulatory exposure that shape foundry capital allocation decisions.
Product Type:
Substitution pressure concentrates in optical subsystems where reflective multilayer alternatives challenge conventional component architectures.
- Source Lasers:CO2 laser systems generate tin plasma through high-power pulsed excitation at 13.5 nanometer wavelength output. Abu Dhabi foundries allocate the steepest capital share here due to power scaling requirements for high-volume manufacturing. TRUMPF manufacturing scale creates single-source dependency that compresses procurement flexibility.
- Photomasks:Reflective reticles employ molybdenum-silicon multilayer stacks on low-thermal-expansion substrates to pattern at sub-7 nanometer resolution. Riyadh semiconductor clusters prioritize EUV-specific mask procurement over optical lithography alternatives as node targets advance below 3 nanometers. Zeiss-grade fabrication constraints limit qualified supplier pools.
- Mask/Etch Systems:Pattern transfer equipment integrates with EUVL exposure tools for defect-free etching workflows.
- Wafer Handling:Vacuum-compatible robotic systems transport silicon wafers through EUVL process chambers without contamination.
Source Lasers anchors the volume base while Photomasks gains share at the steepest rate.
Application:
Cost tier stratification separates high-unit-value semiconductor fabrication from display manufacturing where EUVL adoption remains experimental.
- Semiconductor Manufacturing:Logic and memory foundries employ EUVL for critical layer patterning at 7 nanometer nodes and below. UAE and Saudi sovereign wealth deployment concentrates entirely in this application tier. EU AI Act data sovereignty mandates accelerate domestic fabrication capacity for AI accelerator chips.
- Advanced Packaging:Chiplet integration and 3D stacking architectures require EUVL for interconnect lithography at fine pitch. Dubai-based packaging houses are piloting EUV-enabled fan-out wafer-level packaging for high-bandwidth memory applications. MOHAP regulatory sandbox compresses qualification timelines for imported tooling.
- Flat Panel Displays:OLED backplane patterning at high resolution represents nascent EUVL demand.
- Photonics:Silicon photonics waveguide fabrication employs EUVL for sub-wavelength feature definition.
Semiconductor Manufacturing commands the capital allocation majority while Advanced Packaging expands most quickly.
End User:
Customer type determines procurement contract structure, with sovereign-backed entities favoring long-term service bundling over transactional purchasing.
- Foundries:Pure-play contract manufacturers offer EUVL-capable wafer processing to fabless chip designers. Abu Dhabi and Riyadh clusters center on foundry business models to serve EU and regional AI chip demand. ASML service-lock-in contracts consolidate vendor relationships across these facilities.
- Integrated Device Manufacturers:Vertically integrated semiconductor companies combine design and fabrication under single ownership. Saudi Aramco-backed ventures are pursuing IDM structures for specialized chip categories including automotive and energy applications. SFDA hazardous substance protocols extend facility commissioning timelines.
- Research Institutions:Universities and national labs operate EUVL tools for process development and workforce training.
- Fabless Companies:Design houses without fabrication assets access EUVL through foundry partnerships rather than direct procurement.
Foundries anchor the volume base while Integrated Device Manufacturers gain share at the steepest rate.
Technology:
Supply concentration in German optics fabrication creates bottleneck conditions for reflective system deployment.
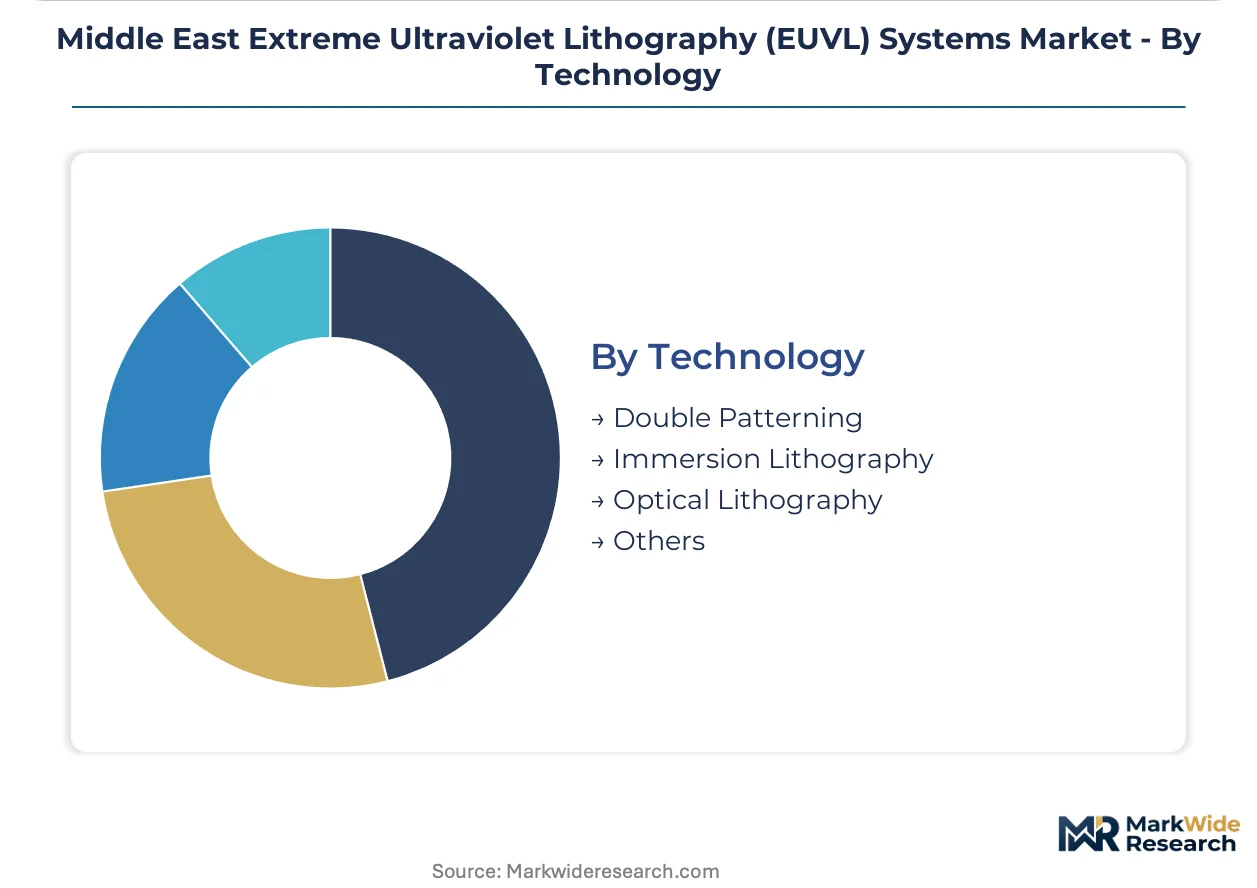
- Double Patterning:Multiple exposure techniques extend optical lithography resolution through overlay precision. Middle East foundries are bypassing this transitional technology in favor of direct EUVL adoption for greenfield facilities. Depreciation risk for installed double-patterning capacity remains minimal in the region.
- Immersion Lithography:Water-based numerical aperture enhancement previously dominated 193 nanometer wavelength systems. UAE-based legacy tool installations retain immersion capacity for mature node production while EUVL handles advanced layers. Technology transition timelines vary by fab vintage.
- Optical Lithography:Conventional deep-ultraviolet systems handle non-critical layers in hybrid patterning workflows.
- Others:Emerging patterning approaches include directed self-assembly and nanoimprint lithography for specialized applications.
Immersion Lithography anchors the volume base while Double Patterning contracts as EUVL displaces transitional approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC Interconnector grid and Red Sea shipping lanes position Middle East semiconductor infrastructure between European and Asian supply chains. Sovereign wealth capital flows through dedicated technology investment vehicles in Abu Dhabi and Riyadh. SFDA and MOHAP regulatory frameworks are transposing IEC semiconductor equipment standards into binding national requirements.
United Arab Emirates
Abu Dhabi's Mubadala Investment Company directs capital toward EUVL-capable foundry infrastructure through GlobalFoundries partnerships. MOHAP fast-track certification pathways compress equipment qualification timelines for advanced manufacturing imports. Dubai's Jebel Ali port cluster serves as the regional entry point for lithography tool logistics and customs clearance operations.
Saudi Arabia
Riyadh's semiconductor cluster formation centers on Saudi Aramco-backed fabrication ventures targeting 2nm-class production. SFDA hazardous substance protocols extend facility commissioning timelines for tin hydride and xenon handling requirements. The King Abdullah Financial District anchors sovereign wealth coordination for technology sector capital deployment.
Israel
Tel Aviv's fabless semiconductor ecosystem generates demand for EUVL foundry services through AI chip design houses. The Israel Innovation Authority provides R&D grants for advanced packaging technologies compatible with EUV-enabled chiplets. Haifa's Matam technology park concentrates design-engineering talent for semiconductor intellectual property development.
Turkey
Istanbul's industrial zones host assembly operations for semiconductor equipment subcomponents serving regional EUVL maintenance networks. The Turkish Standards Institution transposes IEC 61508 functional safety standards into national certification requirements. Ankara's technology development zones attract foreign direct investment for precision manufacturing capability building.
Egypt
The Suez Canal Economic Zone positions Egyptian territory for logistics and light assembly in semiconductor equipment supply chains. The Egyptian Drug Authority governs occupational exposure limits for hazardous materials in manufacturing operations. New Cairo's technology parks host training programs for EUVL equipment maintenance technician certification.
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market Competitive Landscape
Listed leaders compete with private specialists across lithography tool provision and optical component fabrication. The vendor base concentrates around three strategic archetypes: integrated system suppliers, specialized optics fabricators, and laser source manufacturers. Consolidation pressure operates through long-term service bundling contracts rather than asset acquisition. Capacity expansion and technology licensing represent the dominant competitive moves as regional foundries scale operations.
Within the integrated system tier, ASML Holding NV exemplifies the service-lock-in model consolidating vendor relationships across Middle East foundries. Among optics specialists, Carl Zeiss AG occupies a position reflective of single-source dependency for reflective multilayer mirror production. TRUMPF anchors the laser source segment with manufacturing scale that competitors struggle to replicate. These three entities represent distinct strategic archetypes within the EUVL supply structure.
| Leading Market Players |
|---|
| ASML Holding NV |
| Carl Zeiss AG |
| TRUMPF |
| AGC Inc. |
| KLA Corporation |
| Applied Materials Inc. |
| Canon Inc. |
| Nikon Corporation |
| SUSS MicroTec SE |
| Others |
Value Network & Pricing Analysis
TRUMPF's manufacturing scale in CO2 laser source production creates capacity utilization thresholds that simultaneously concentrate supplier pricing power and establish minimum viable order quantities for Middle East foundries. This scale dynamic compresses procurement flexibility for Abu Dhabi and Riyadh clusters while anchoring price floors through dedicated production line commitments.
Pricing Analysis
Volume-discount tiering structures dominate EUVL system procurement, with foundries securing steeper per-unit reductions through 10-year source availability guarantees bundled with initial tool purchases. Pricing stratifies across high-NA tool premiums, standard 0.33 NA configurations, and economy-tier refurbished installations. Cost compression in source laser subsystems is intensifying because TRUMPF's single-source position limits competitive bidding. Integrated Device Manufacturers backed by Saudi Aramco capital exhibit lowest price sensitivity, while Dubai-based packaging houses piloting EUV-enabled fan-out wafer-level applications face acute budget constraints.
Supply Chain Analysis
Inventory lead times for Zeiss-grade reflective multilayer mirrors extend 18-24 months due to single-source fabrication constraints in Germany. Geographic supply concentration centers on Germany for optical components, the Netherlands for integrated lithography systems, and Malaysia for high-purity tin feedstock refining. Raw material dependencies draw from xenon gas reserves, molybdenum-silicon deposition substrates, and ultra-low-expansion glass ceramics. Single-source vulnerability in mirror production creates systemic exposure to export license disruptions. Distribution runs through Jebel Ali port customs clearance operations serving UAE-Saudi bilateral technology partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ASML's service-lock-in contracts generate regulatory entrenchment through IEC 61508 safety standard transposition requirements that lock out unqualified competitors.
For Market Incumbents: Consolidate vendor relationships through extended source availability guarantees that embed SFDA and MOHAP compliance documentation within standard service protocols. Add captive maintenance technician training capacity in Riyadh to preempt emerging entrant challenges from Turkish precision manufacturing specialists. Deepen backward integration into CO2 laser subsystem assembly to reduce TRUMPF dependency exposure. For New Entrants and Emerging Players: Aftermarket service layer gaps in tin hydride handling protocols and xenon recovery systems present immediate white-space opportunities where ASML's bundled pricing under-serves cost-conscious packaging houses. Target Dubai's MOHAP regulatory sandbox for fast-track qualification of localized maintenance operations. Penetrate through ISO 14644 Class 1 cleanroom construction partnerships with UAE contractors lacking EUVL-specific vibration isolation expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-locked lithography tool providers with 10-year contractual visibility. Long-term viability across the projection horizon favors acquisition targets possessing IEC semiconductor equipment standard certification capabilities and established SFDA hazardous substance protocol documentation. Monitor tin supply concentration in Malaysian refining operations as inflection indicator for source laser cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Source Laser Components | UAE foundries reduce TRUMPF import dependency through localized CO2 laser subsystem assembly partnerships. |
| MOHAP Fast-Track Certification Pathway | Dubai's regulatory sandbox compresses equipment qualification timelines for advanced manufacturing imports. |
| Long-Term Service Contract Bundling | Riyadh foundries shift vendor revenue toward recurring streams through 10-year source availability guarantees. |
| High-NA EUVL Tool Procurement | Saudi Aramco-backed ventures prioritize 0.55 NA systems for 2nm-class production roadmaps. |
| Desalination-Semiconductor Co-location | Reverse osmosis facility sharing addresses ultrapure water requirements while consolidating energy infrastructure. |
Research Methodology
Cross-validation between primary interviews with fab operations directors, lithography tool procurement managers, and cleanroom construction specialists anchors the qualitative findings against secondary validation from SEC equipment manufacturer filings, IEC semiconductor standard documentation, and SFDA hazardous substance regulatory notices. Bottom-up triangulation aggregates individual foundry capital expenditure plans while top-down verification cross-checks against sovereign wealth technology investment vehicle disclosures.
Sensitivity analysis frameworks test demand elasticity across the projection horizon under varying scenarios for EU AI Act enforcement intensity and tin feedstock supply disruption. Segmentation dimensions modeled include product type subsystems, application tiers from logic foundries to advanced packaging, end-user archetypes distinguishing sovereign-backed IDMs from pure-play contract manufacturers, and technology generations spanning 0.33 NA to high-NA optical architectures. CAGRs derive from installed base depreciation schedules and replacement cycle timing for transitional lithography capacity.
Underlying assumptions cover sustained sovereign wealth deployment in Abu Dhabi and Riyadh semiconductor clusters, with deviation risk concentrated in SFDA regulatory interpretation shifts for tin hydride occupational exposure limits. Forecasts reflect these conditions without guaranteeing outcome realization. Revision becomes warranted when Malaysian tin refining concentration crosses critical supply security thresholds triggering EU Green Deal Carbon Border Adjustment Mechanism documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Global Semiconductor Machinery Market