
 Power Semiconductor Market | 2026-2036
Power Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Power Semiconductor Market Intelligence
The substitution of traditional silicon with wide-bandgap materials like Silicon Carbide (SiC) is broadening the performance envelope for power devices. Wolfspeed specializes in the production of SiC substrates and high-power components for the automotive sector. Infineon Technologies AG leverages its manufacturing scale to supply a wide range of power solutions to industrial and automotive clients. Meanwhile, STMicroelectronics competes across both silicon and SiC technologies, targeting diverse applications from consumer electronics to energy infrastructure.
A power semiconductor is a discrete device or integrated circuit designed to manage high voltage and current levels in electronic systems. It functions primarily to convert, switch, or control electrical power, often operating at high frequencies to improve efficiency and reduce component size. Silicon Carbide and Gallium Nitride technologies are displacing legacy silicon in high-performance applications. Demand from the electric vehicles and renewable energy sectors now outpaces that from traditional consumer electronics applications.
Efficiency mandates like the EU Green Deal and US EPA vehicle standards create direct demand for superior power management. Concurrently, China's dual carbon goals accelerate investment in grid infrastructure and electric mobility, requiring advanced power components. Product compliance with standards such as the EU's RoHS directive governs material composition and market access. Securing access to SiC wafer supply versus mastering GaN-on-Silicon process technology represents a critical strategic decision for manufacturers.
Market Dynamics
The fundamental dynamic shaping the power semiconductor market is the technological substitution of silicon with wide-bandgap materials. This shift, driven by acute efficiency requirements in the electric vehicle and renewable energy sectors, redefines performance benchmarks and supply chain priorities.
Growth Catalysts
- Electric Vehicle Mandates:Government policies like the US EPA's vehicle emissions standards and the EU Green Deal create direct demand for high-efficiency SiC inverters and onboard chargers to extend vehicle range and reduce charging times.
- Wide-Bandgap Material Maturation:Advances in Gallium Nitride (GaN) and Silicon Carbide (SiC) manufacturing processes are lowering defect rates and enabling larger wafer diameters, which improves device yield and reduces unit costs for high-performance applications.
- Renewable Energy Infrastructure:The global build-out of solar and wind energy projects requires advanced power converters and grid-tied inverters that rely on power semiconductors to manage energy flow efficiently and reliably, a trend accelerated by China's dual carbon goals.
Market Restraints
- High Substrate Cost:The production of high-quality Silicon Carbide boules and wafers remains a complex, energy-intensive process, resulting in substrate costs that are an order of magnitude higher than for traditional silicon, limiting adoption in cost-sensitive applications.
- Supply Chain Bottlenecks:A concentration of SiC wafer production capacity among a few key suppliers creates a significant bottleneck, exposing the entire downstream device manufacturing ecosystem to supply disruptions and price volatility.
- Manufacturing Yield Challenges:Achieving consistently low defect densities across large-diameter SiC and GaN wafers is a persistent technical hurdle, impacting manufacturing yields and constraining the scalable production of reliable, high-power devices.
Strategic Opportunities
- Emerging Market Electrification:National initiatives in countries like India, including the PLI scheme for automotive components, present significant white space for power semiconductors in electric two-wheelers, public transport, and associated charging infrastructure.
- Next-Generation Data Centers:The demand for higher power density and efficiency in artificial intelligence and hyperscale data centers creates a substantial opportunity for GaN-based power supplies that can operate at higher frequencies, reducing energy consumption and physical footprint.
- System-Level Integration:Integrating GaN power stages with driver and control logic into a single package (GaN ICs) offers a pathway to simplified system design, improved performance, and reduced component count for end-users in consumer and industrial markets.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers with deep expertise in wide-bandgap material physics, high-frequency circuit design, and advanced packaging techniques constrains research and development efforts and slows product-to-market timelines for many firms.
- Capital-Intensive Fabrication:The construction and equipping of new fabrication facilities, particularly for 200mm SiC wafers, requires billions of dollars in capital expenditure, creating a high barrier to entry and favoring large, well-capitalized incumbents.
- Reliability and Standardization Gaps:The absence of long-term field data and universally accepted standards for testing the reliability of SiC and GaN devices under harsh conditions creates design uncertainty for engineers in critical automotive and industrial systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Semiconductor Market |
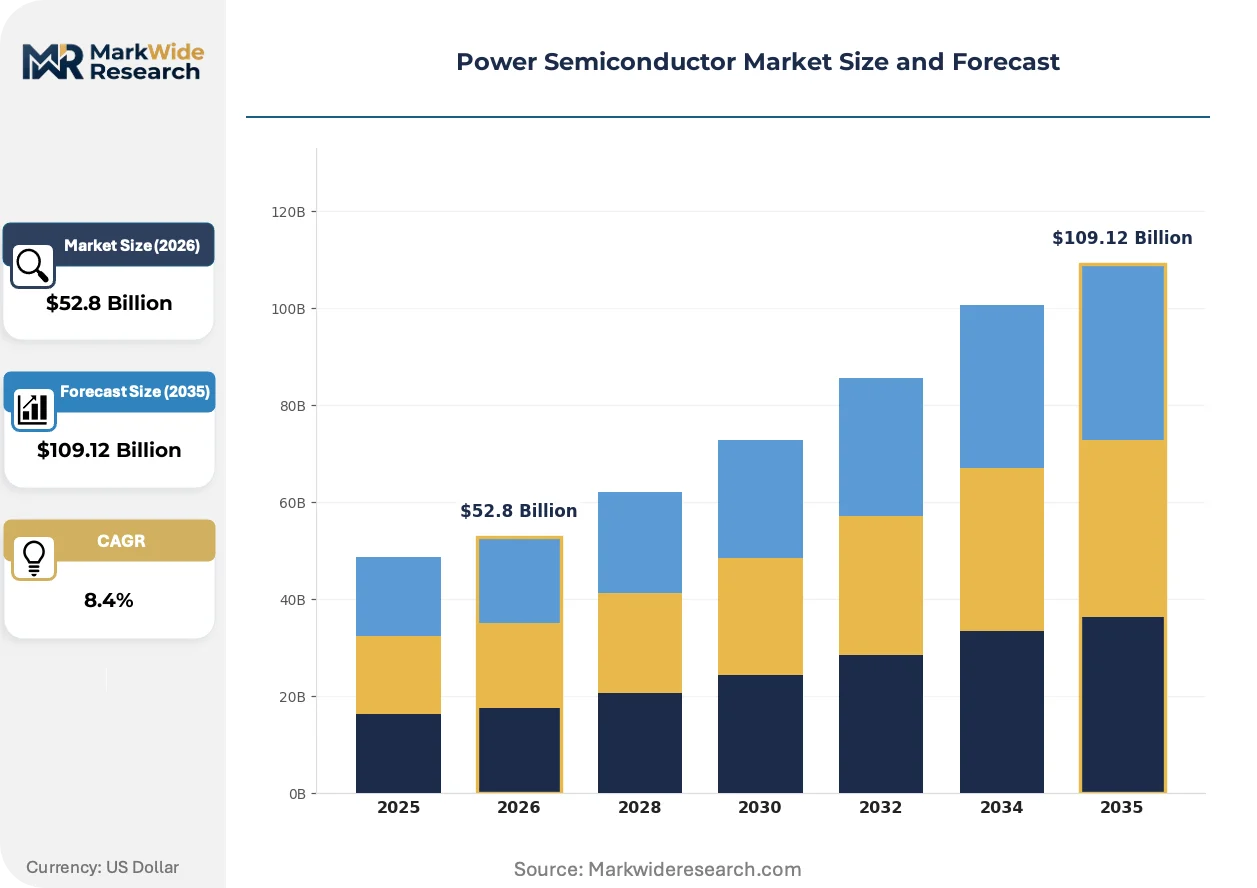
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
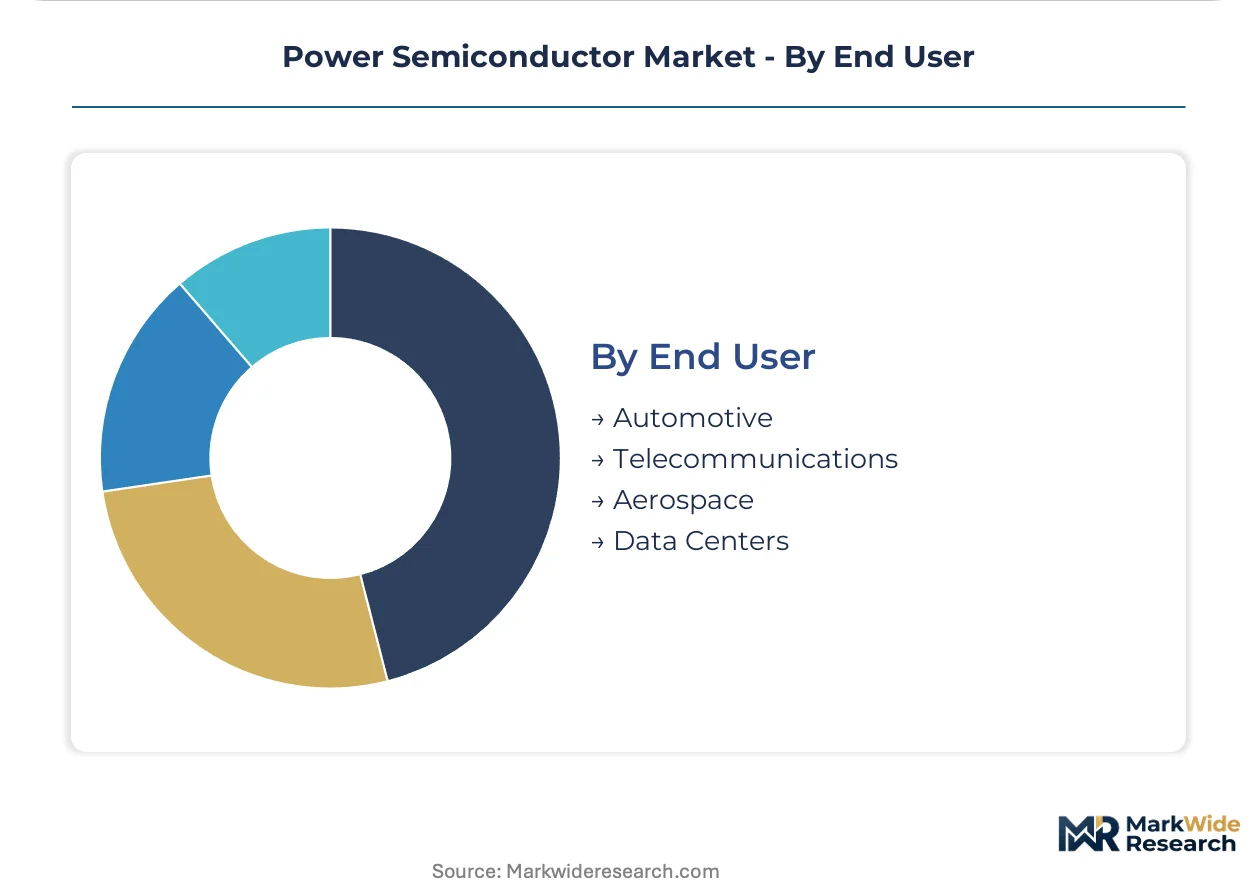
| Segmentation | Product Type: Diodes, Transistors, Thyristors, Modules Technology: Silicon, Gallium Nitride, Silicon Carbide, Hybrid Application: Renewable Energy, Electric Vehicles, Consumer Electronics, Industrial Automation End User: Automotive, Telecommunications, Aerospace, Data Centers |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, Wolfspeed, Onsemi, Texas Instruments, ROHM, Vishay Intertechnology, NXP Semiconductors, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Semiconductor Market Strategic Shifts & Innovations
A transition from component-level specifications to system-level efficiency optimization defines current market evolution. This forces a deeper collaboration between device makers and system designers, particularly in the automotive and industrial sectors where performance gains are paramount.
Gallium Nitride (GaN) technology provides exceptionally fast-switching transistors that enable higher power density. It is being adopted by designers of fast chargers for consumer electronics and power supplies for data centers. Beyond these initial applications, GaN technology is expanding into automotive systems like onboard chargers and LiDAR sensors, where it competes directly with SiC.
China's dual carbon goals represent a powerful policy driver for advanced power semiconductors. The national strategy mandates significant efficiency improvements across grid infrastructure, industrial motors, and the country's vast electric vehicle ecosystem. Consequently, domestic OEMs are accelerating the adoption of SiC and GaN solutions to comply with government directives and secure positions in state-backed projects.
A notable shift from transactional component sales toward collaborative co-design partnerships is underway. Automotive and industrial system builders now engage semiconductor specialists early in the development process to optimize thermal management, power density, and overall system reliability. This trend is most pronounced within the electric vehicle powertrain segment in Germany and the United States.
Power Semiconductor Market Segmentation
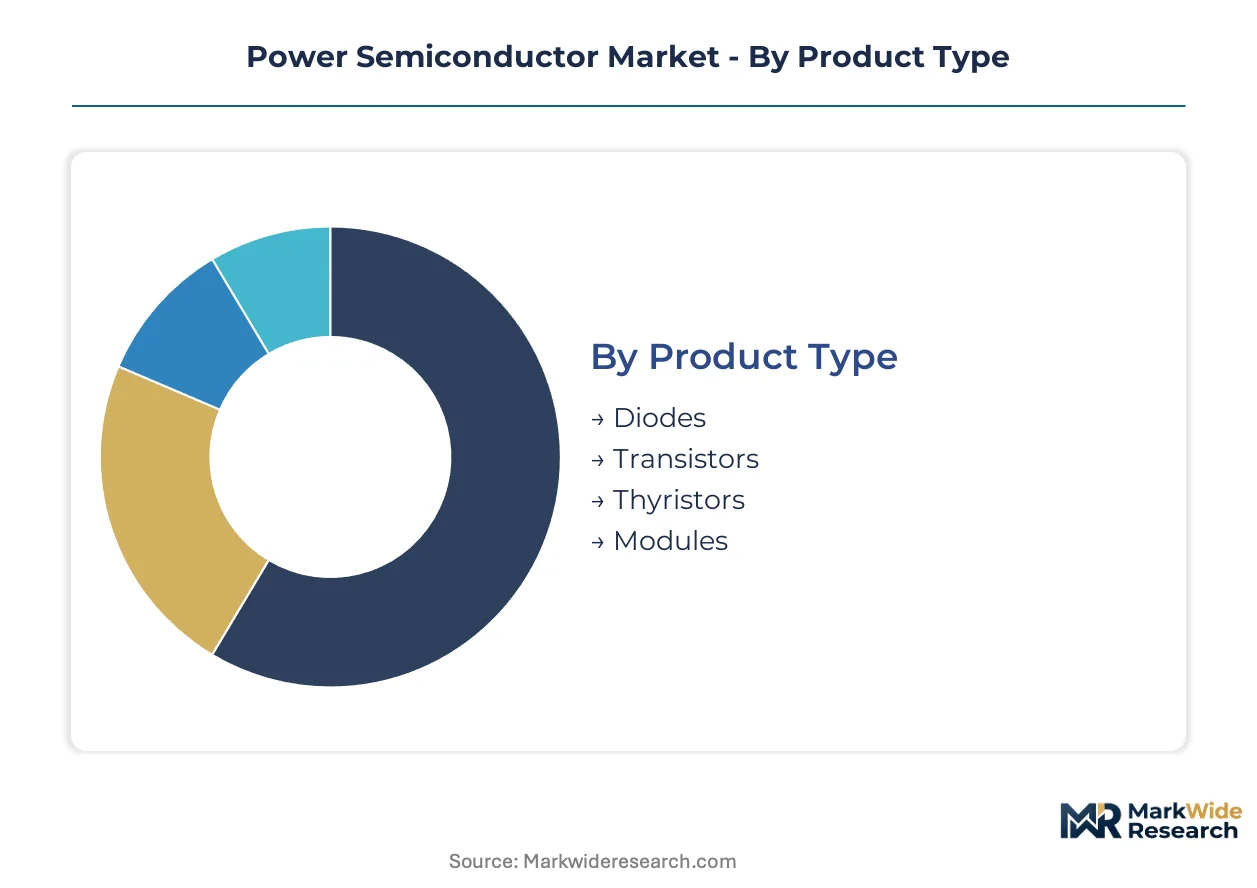
Segmentation within the power semiconductor market highlights the diverse functional requirements and material science driving product development. These classifications reveal where innovation is concentrated and how different applications demand specialized power management solutions for high voltage and current levels.
Product Type:
Product type segmentation highlights the varying regulatory compliance pathways for power semiconductors, impacting market entry and operational standards.
- Transistors:Transistors are semiconductor devices acting as electronic switches or amplifiers, controlling current flow with a small input signal. Demand concentrates in electric vehicles and renewable energy systems, where efficient power conversion is paramount for range and grid stability.
- Modules:Modules integrate multiple power semiconductor devices into a single package, offering higher power density and simplified system design. Automotive applications, particularly inverters for electric vehicles, drive demand for compact, high-reliability power modules.
- Diodes:Diodes allow current flow in one direction, essential for rectification and voltage clamping in power supplies.
- Thyristors:Thyristors are high-power switches used for controlling large AC currents in industrial motor drives and high-voltage DC transmission.
Leading the category by volume: Transistors. Growing fastest: Modules.
Technology:
Technology segmentation reflects the cost-performance trade-offs inherent in power semiconductor manufacturing, influencing adoption across diverse applications.
- Silicon Carbide:Silicon Carbide (SiC) devices operate at higher temperatures, voltages, and frequencies than silicon, enabling superior efficiency and power density. Electric vehicle powertrains and grid-tied renewable energy inverters in China heavily adopt SiC for performance gains.
- Gallium Nitride:Gallium Nitride (GaN) power semiconductors offer ultra-fast switching speeds and low losses, making them ideal for high-frequency power conversion. Data centers and consumer electronics fast chargers in the United States and Europe increasingly utilize GaN solutions.
- Silicon:Silicon remains the foundational material for power semiconductors, offering cost-effectiveness for mainstream industrial and consumer applications.
- Hybrid:Hybrid solutions combine different semiconductor materials, like SiC diodes with Si IGBTs, optimizing performance and cost for specific power management needs.
Silicon Carbide and Gallium Nitride technologies are gaining share fastest, while Silicon maintains a significant volume base.
Application:
Application segmentation delineates power semiconductor usage based on specific customer operational requirements, driving tailored product development.
- Electric Vehicles:Electric vehicles utilize power semiconductors for inverters, onboard chargers, and DC-DC converters, demanding high efficiency and reliability for extended range. Government mandates in the EU and US for emissions reductions directly spur demand in this segment.
- Renewable Energy:Renewable energy systems, including solar inverters and wind turbine converters, rely on power semiconductors for efficient power conditioning and grid integration. China's dual carbon goals accelerate investment in advanced power components for its renewable energy infrastructure.
- Consumer Electronics:Consumer electronics applications include power adapters, LED lighting, and home appliances, where cost-effectiveness and compact size are primary drivers.
- Industrial Automation:Industrial automation employs power semiconductors in motor drives, robotics, and power supplies for precise control and energy optimization in manufacturing.
Electric Vehicles and Renewable Energy applications exhibit the steepest expansion trajectory, propelled by efficiency mandates.
End User:
End user segmentation reflects the varying maturity levels of power semiconductor integration, from established industrial uses to nascent high-growth sectors.
- Automotive:The automotive sector uses power semiconductors extensively in electric powertrains, advanced driver-assistance systems, and infotainment. Demand from German and US automotive OEMs for high-power SiC devices is substantial.
- Data Centers:Data centers require power semiconductors for server power supplies and uninterruptible power supplies, with a focus on high efficiency and density for artificial intelligence workloads. Hyperscale operators in the United States drive demand for GaN-based solutions.
- Telecommunications:Telecommunications infrastructure utilizes power semiconductors in base stations and network equipment for reliable power conversion and management.
- Aerospace:Aerospace applications demand power semiconductors for avionics, power distribution, and motor control, emphasizing extreme reliability and weight reduction.
Automotive and Data Centers are experiencing significant expansion due to electrification and AI processing demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced power semiconductors concentrates heavily in countries actively pursuing electric vehicle adoption and renewable energy expansion. These national strategies create specific market pull for high-efficiency components, especially in automotive and grid infrastructure applications.
China
China's dual carbon goals drive substantial demand for SiC and GaN devices in electric vehicles and renewable energy projects. The country's national strategy accelerates investment in grid infrastructure and electric mobility, requiring advanced power components. Manufacturing hubs in Jiangsu and Guangdong provinces are rapidly adopting wide-bandgap technologies for domestic automotive OEMs.
United States
The United States market sees significant demand for power semiconductors from its electric vehicle sector and hyperscale data centers. US EPA vehicle standards and federal incentives support the development of high-efficiency SiC inverters. Silicon Valley and Texas continue to be innovation centers for GaN-based power supplies and advanced semiconductor fabrication.
Germany
Germany's automotive industry and strong renewable energy sector generate robust demand for high-performance power semiconductors. The EU Green Deal mandates accelerate the integration of SiC modules into electric vehicle powertrains. Bavaria and Baden-Württemberg host major automotive and industrial electronics clusters, driving innovation in power management solutions.
Japan
Japanese manufacturers are integrating advanced power semiconductors into their automotive and industrial automation sectors, focusing on reliability and precision. METI initiatives support research into next-generation SiC and GaN materials for high-power applications. The Kansai region, including Osaka and Kyoto, remains a key area for power device development and manufacturing.
India
India's electrification efforts, particularly in electric two-wheelers and public transport, are creating new demand for power semiconductors. The PLI scheme for automotive components encourages domestic manufacturing and technology adoption in the EV supply chain. Bengaluru and Chennai are emerging as important centers for power electronics design and integration.
Power Semiconductor Market Key Industry Players
Capacity expansion dominates the current landscape, as key players invest heavily to meet the escalating demand for wide-bandgap materials. The market structure exhibits a tiered consolidation, with a few large integrated device manufacturers alongside specialized material suppliers and fabless design houses. Strategic partnerships and technology licensing are also prevalent competitive moves, especially in the rapidly evolving SiC and GaN ecosystems.
On the premium-tier vector, Infineon Technologies AG and STMicroelectronics exemplify comprehensive power semiconductor portfolios, spanning both silicon and wide-bandgap technologies for diverse applications. Wolfspeed, a specialized supplier, anchors the high-performance SiC substrate and device segment. These companies navigate complex supply chains and capitalize on their extensive R&D capabilities to maintain their market positions.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| Wolfspeed |
| Onsemi |
| Texas Instruments |
| ROHM |
| Vishay Intertechnology |
| NXP Semiconductors |
| Mitsubishi Electric |
| Others |
Cost & Logistics Intelligence
Silicon Carbide (SiC) wafer spot prices, though not fully commoditized, directly influence the cost structure of high-performance power modules, cascading through the supply chain into final component pricing for automotive and industrial clients.
Pricing Analysis
The volume-vs-margin split heavily favors advanced wide-bandgap materials, where high-performance SiC and GaN devices command premium pricing due to their efficiency advantages. Pricing stratifies across performance tiers, with SiC and GaN solutions utilizing a value-based model for electric vehicles and data centers. Price differentiation drivers include quality grade, particularly defect density for SiC wafers, and certification levels like automotive-grade AEC-Q101. Pricing pressure currently leans upwards for SiC and GaN components, driven by acute demand outstripping specialized manufacturing capacity. Consumer electronics applications exhibit the most price-sensitive buyer behavior, while aerospace and high-end automotive segments are least sensitive.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns support the delivery of power semiconductors to major manufacturing clusters globally. Geographic supply concentration for SiC wafers centers heavily in Japan and the United States, with significant fabrication also in Germany. The supply chain relies on critical raw materials such as high-purity silicon carbide powder and gallium nitride precursors. Single-source vulnerability in SiC boule production represents a significant structural risk for downstream device manufacturers. The distribution model primarily involves direct sales to large automotive and industrial OEMs, supplemented by specialized electronics distributors serving a broader customer base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, where the limited availability of high-quality Silicon Carbide wafers currently props up pricing and dictates growth trajectories.
For Market Incumbents:Extend existing foundry agreements for SiC and GaN wafer supply to secure long-term material access. This move mitigates the threat of supply disruptions from concentrated raw material producers. Invest aggressively in 200mm SiC wafer manufacturing R&D to improve yields and reduce costs, addressing the capital-intensive fabrication challenge. Pursue strategic acquisitions of specialized GaN process technology firms to expand portfolio capabilities and counter emerging competitors.
For New Entrants and Emerging Players:The EU Green Deal in Europe opens a window for GaN-based power solutions in grid infrastructure and industrial motor drives. Target underserved regional markets like India's electric two-wheeler segment with cost-effective SiC power modules, leveraging national PLI schemes. Focus on system-level integration expertise for GaN ICs, offering simplified design and reduced component count as a go-to-market angle for consumer and data center applications.
For Investors and Strategic Acquirers:Distressed-cycle entries favor patient capital in the United States and Japan, targeting specialized wide-bandgap material suppliers. The long-term viability of this market is strong, driven by the electrification of transport and renewable energy build-out over the next decade. Seek out companies with proprietary SiC substrate growth technology or advanced GaN-on-Silicon process intellectual property. A key signal to watch is the consistent achievement of high manufacturing yields for 200mm SiC wafers, indicating maturing production capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand SiC Wafer Capacity | Increases foundational supply for high-growth EV and renewable energy sectors. |
| Backward Integration into GaN Substrates | Secures critical raw material access and optimizes cost structures for GaN devices. |
| Develop 200mm SiC Wafer Technology | Lowers per-device costs and enables larger-scale production for advanced power modules. |
| Forge Co-Design Partnerships with OEMs | Aligns product development with specific automotive and industrial system requirements. |
| Invest in Advanced Packaging Solutions | Enhances thermal management and power density, improving device performance in harsh environments. |
Research Approach
Multi-period observation of technology adoption rates and policy mandates anchored the trend analysis, supplemented by interviews with R&D directors, automotive procurement heads, and power electronics engineers. Secondary validation drew from company annual reports, government energy policies like China's dual carbon goals, and industry association reports. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data coverage.
The segment-weighting approach informed the market forecast, modeling growth across product type, technology, application, end-user, and regional policy mandates. Compound annual growth rates were derived through a blend of regression analysis and expert consensus, projecting market trajectory across the analysis window. Key industry-specific forecast inputs included electric vehicle production forecasts and renewable energy deployment targets in major economies.
Caveats apply where global trade policies or raw material supply disruptions could materially shift the outlook for wide-bandgap materials. Forecasts reflect assumptions regarding technological maturation and sustained investment in electrification initiatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Micro-Inverter Market
Power Systems
USB Power Adapters Market
Power Systems
Thermal Management Systems Market
Power Systems
Synchrophasors Market
Power Systems
PV Inverter Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Shunt Reactor Market
Power Systems
Hybrid Inverters Market
Power Systems
Battery Balancer Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Charge Pumps Market
Power Systems
Photovoltaic Inverters Market
Power Systems
South America Battery Management System Market
Power Systems
MOSFET and IGBT Gate Driver Market