
 Slide Processing System Market | 2026-2036
Slide Processing System Market Size, Share, and Industry Trends Forecast 2026-2036
Slide Processing System Market Analytics
Aftermarket service revenue is reshaping profitability structures across the Slide Processing System landscape. Leica Biosystems leverages extensive field service networks to capture recurring maintenance contracts. Hamamatsu Photonics anchors its position through deep integration of digital pathology scanners with proprietary image analysis software. ZEISS differentiates via precision optics manufacturing that extends equipment lifecycles and reduces total cost of ownership.
A slide processing system encompasses automated and semi-automated instrumentation for tissue section staining, coverslipping, and slide preparation in histopathology and cytology workflows, typically operating through robotic liquid handling with throughput rates from 100 to 1,000 slides per hour depending on configuration. Automated slide processors command the dominant product type position due to labor cost reduction and reproducibility demands in high-volume clinical settings. Research applications represent the fastest-growing application segment as pharmaceutical toxicology studies and spatial transcriptomics protocols multiply slide preparation requirements. Direct sales channels capture premium margin pools by bundling installation, validation, and training services with capital equipment purchases.
FDA quality system regulation and EU IVDR framework impose stringent design controls and clinical evidence requirements on slide processing systems used in diagnostic workflows. ISO 15189 accreditation standards for medical laboratories further shape procurement criteria by mandating traceability and quality assurance protocols. Stakeholders must monitor evolving digital pathology interoperability standards and artificial intelligence integration pathways that will determine next-generation platform competitiveness.
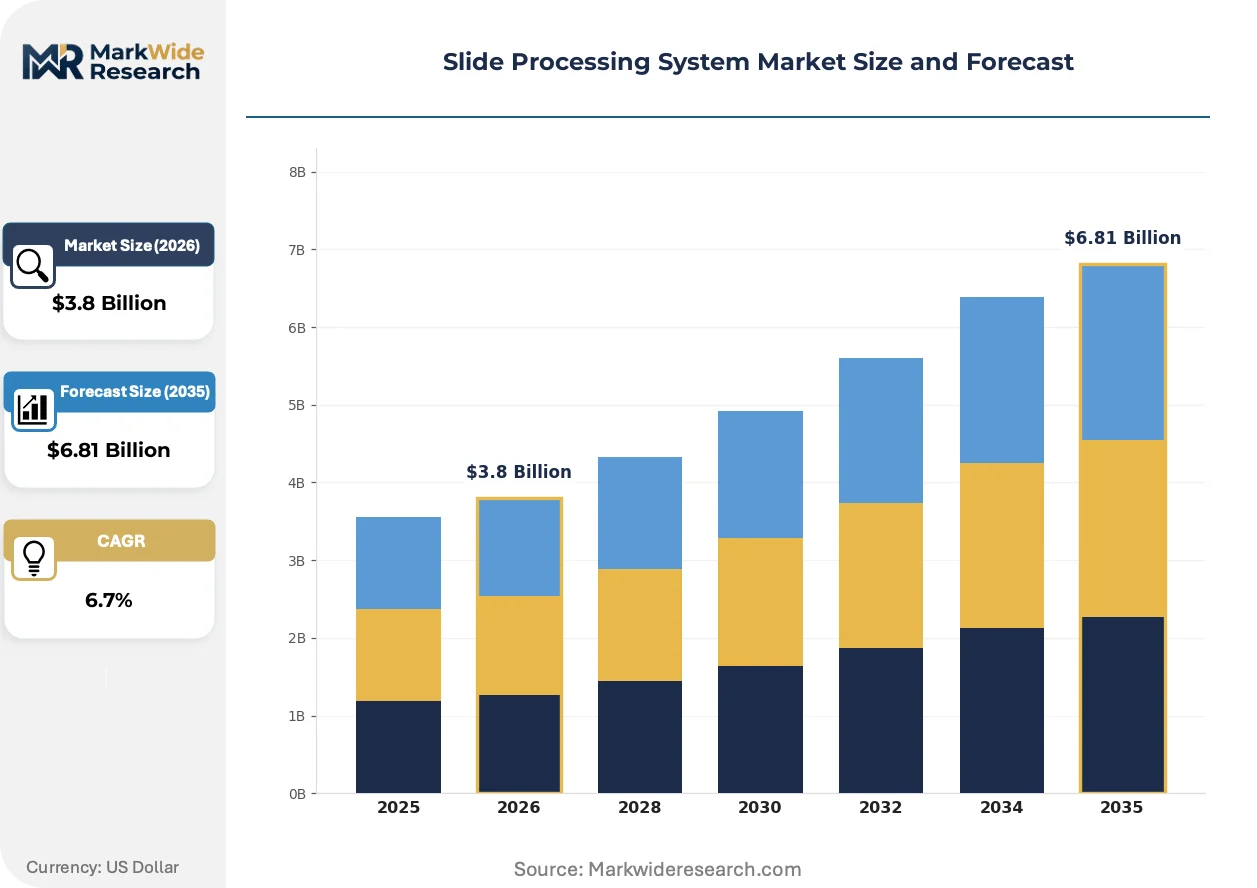
Market Dynamics
Automated slide processing systems are consolidating histopathology workflows as laboratories confront pathologist workforce shortages and rising cancer screening volumes. Integration of staining-to-imaging platforms is compressing capital procurement cycles and reshaping vendor-customer relationships.
Growth Catalysts
- EU IVDR compliance deadlines:European diagnostic laboratories are replacing legacy equipment to meet clinical evidence and traceability mandates, accelerating platform upgrades across Germany, France, and Italy.
- Spatial transcriptomics protocols:Pharmaceutical toxicology studies now require tenfold increases in slide throughput, pulling automated processors into research settings previously served by manual methods.
- Centralized pathology networks:Germany's regional laboratory consolidation is standardizing high-throughput workflows and creating template procurement specifications adopted by neighboring health systems.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component manufacturers control critical lens assemblies, exposing equipment OEMs to single-source vulnerabilities and extended lead times.
- FDA quality system validation costs:Design control documentation and clinical performance studies for diagnostic workflows impose seven-figure compliance burdens that exclude smaller equipment developers.
- Digital pathology scanner substitution:Direct-to-digital frozen section workflows in academic medical centers are bypassing traditional glass slide preparation for select intraoperative applications.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting contract assembly partners to serve South Asian and Middle Eastern diagnostic laboratory markets.
- Artificial intelligence integration pathways:Convergence of automated staining with real-time quality control algorithms is creating premium platform tiers commanding service-anchored pricing.
- Direct-to-laboratory e-procurement channels:Group purchasing organizations are unbundling installation and validation services from capital sales, enabling price-transparent equipment marketplaces.
Industry Challenges
- Histotechnologist certification bottlenecks:ASCP-credentialed specialists are in chronic shortage, limiting laboratory capacity to operate and maintain complex automated staining lines.
- Legacy LIS integration complexity:Proprietary data formats from established slide scanner manufacturers are blocking seamless interoperability with third-party image management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slide Processing System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Slide Processors, Manual Slide Processors, Hybrid Slide Processors, Slide Stainers Application: Pathology, Histology, Cytology, Research End User: Hospitals, Diagnostic Laboratories, Research Institutions, Biopharmaceutical Companies Delivery Mode: Outsourced Services, Direct Sales, Online Sales, Distributor Sales |
| Companies Covered | 3DHISTECH, Hamamatsu Photonics, Olympus Corporation, Leica Biosystems, Koninklijke Philips, ZEISS, PerkinElmer, Nikon Corporation, Visiopharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slide Processing System Market Evolving Landscape
Workflow convergence is collapsing traditional boundaries between tissue processing, staining, and digital imaging. Vendors are repositioning around integrated platform economics rather than standalone equipment sales.
Multiplex immunohistochemistry staining protocols are collapsing the sequential processing steps that previously required separate instruments. Academic medical centers and pharmaceutical contract research organizations are adopting these systems at accelerated replacement cycles. The technology is collapsing capital equipment footprints and reagent consumption while compressing turnaround times for biomarker panel development.
REACH substance restrictions on hazardous reagents in histological stains are forcing reformulation of traditional hematoxylin and eosin protocols. European manufacturers are accelerating development of water-based and biodegradable alternatives to maintain market access. The diagnostic segment is absorbing compliance costs through reagent pricing adjustments while research laboratories delay upgrades pending validation data.
Service contract unbundling is fragmenting traditional vendor-captive relationships. Independent third-party maintenance providers are capturing calibration and preventive service work previously reserved by original equipment manufacturers. This shift is most visible in North American hospital laboratory networks where capital budget constraints favor multi-vendor service agreements over comprehensive manufacturer contracts.
Slide Processing System Market Segmentation
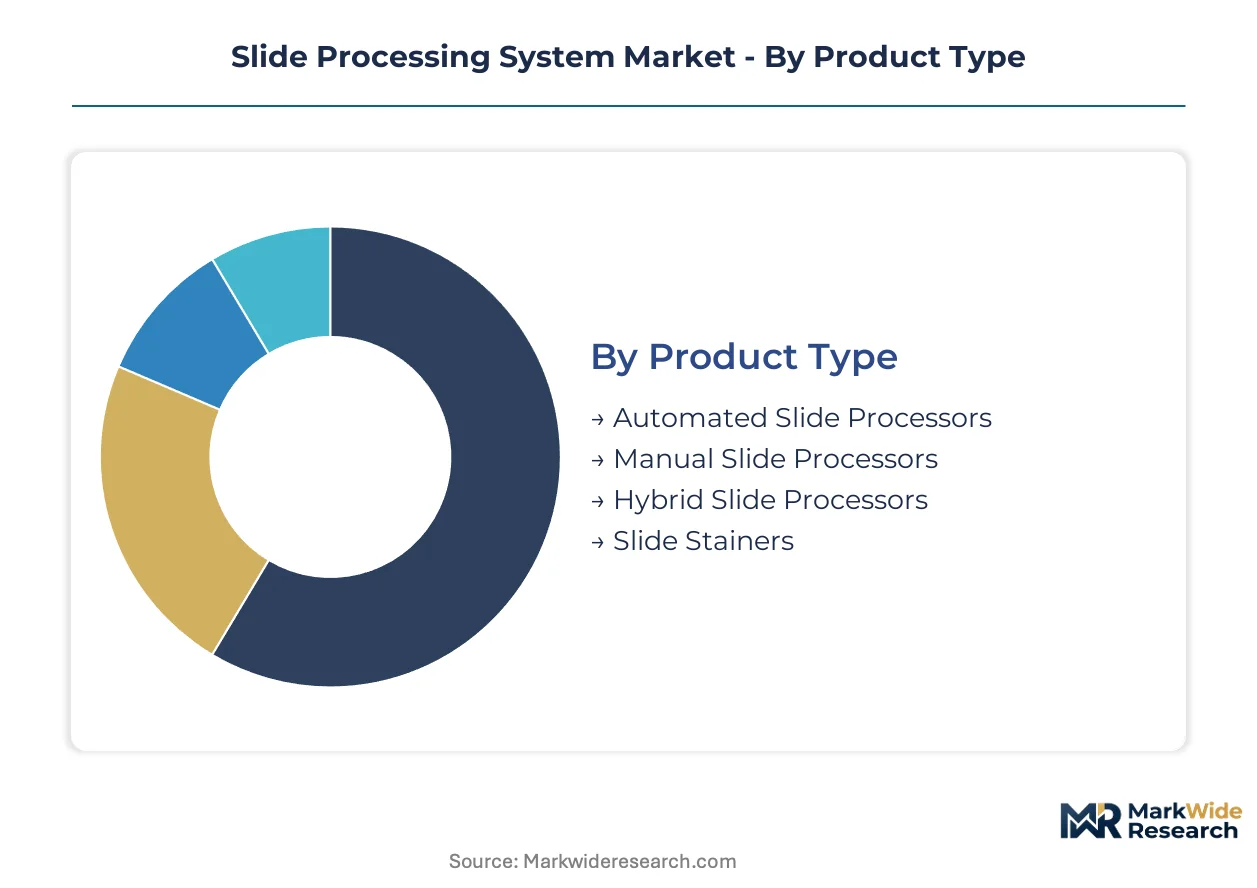
Slide processing system procurement varies sharply across customer archetypes, with service contract structures and validation requirements driving divergent pricing and vendor selection patterns. Equipment specifications that satisfy high-throughput clinical laboratories often overshoot research institution budgets, while hybrid configurations address mid-tier facilities seeking staged automation investments.
Product Type:
After-sales service intensity peaks with automated platforms, where multi-year maintenance contracts and reagent supply agreements generate recurring revenue streams exceeding original equipment margins.
- Automated Slide Processors:Robotic liquid handling systems achieve throughput rates from 100 to 1,000 slides per hour with standardized staining protocols. Clinical laboratories in Germany's centralized pathology networks specify these platforms to meet ISO 15189 traceability mandates and compress histotechnologist staffing requirements.
- Manual Slide Processors:Benchtop units requiring operator intervention for each processing step dominate low-volume settings and educational facilities. Research institutions in India defer automation investments pending PLI scheme domestic manufacturing incentives that promise reduced capital outlays.
- Hybrid Slide Processors:Modular configurations allow graduated automation adoption.
- Slide Stainers:Dedicated instruments for hematoxylin and eosin or special stains.
Automated slide processors hold the largest share; momentum sits with hybrid configurations as laboratories balance capital constraints against throughput targets.
Application:
Cost tier stratification separates premium diagnostic-grade systems from economy research configurations, with pathology applications commanding threefold pricing multiples over basic cytology setups.
- Pathology:Cancer screening workflows demand reproducible staining quality for diagnostic confidence. FDA quality system regulations and EU IVDR clinical evidence requirements shape equipment specifications across US and European hospital laboratories, with compliance documentation adding substantial procurement overhead.
- Research:Spatial transcriptomics protocols and pharmaceutical toxicology studies are expanding slide preparation volumes tenfold. Biopharmaceutical contract research organizations in the United States and Europe are accelerating replacement cycles for multiplex immunohistochemistry-capable systems.
- Histology:Tissue section preparation for diagnostic and research use.
- Cytology:Cell-based specimen processing for cervical cancer screening and liquid-based preparations.
Pathology commands the dominant application position; research is expanding most quickly as drug development pipelines intensify slide throughput demands.
End User:
Customer type determines procurement channel preference, with hospital networks favoring bundled direct sales while independent laboratories gravitate toward distributor relationships with unbundled service terms.
- Hospitals:Integrated health systems prioritize staining-to-imaging platform consolidation to reduce capital procurement cycles. Academic medical centers in North America are piloting direct-to-digital frozen section workflows that bypass traditional glass slide preparation for select intraoperative applications.
- Diagnostic Laboratories:Regional laboratory consolidation in Germany is standardizing high-throughput specifications adopted by neighboring health systems. Commercial laboratories face chronic ASCP-credentialed histotechnologist shortages that limit automated line utilization rates.
- Research Institutions:University and government laboratories with grant-dependent capital budgets.
- Biopharmaceutical Companies:Internal toxicology and biomarker development operations.
Diagnostic laboratories hold the largest share; biopharmaceutical companies are gaining share fastest as outsourced drug development expands internal histopathology infrastructure.
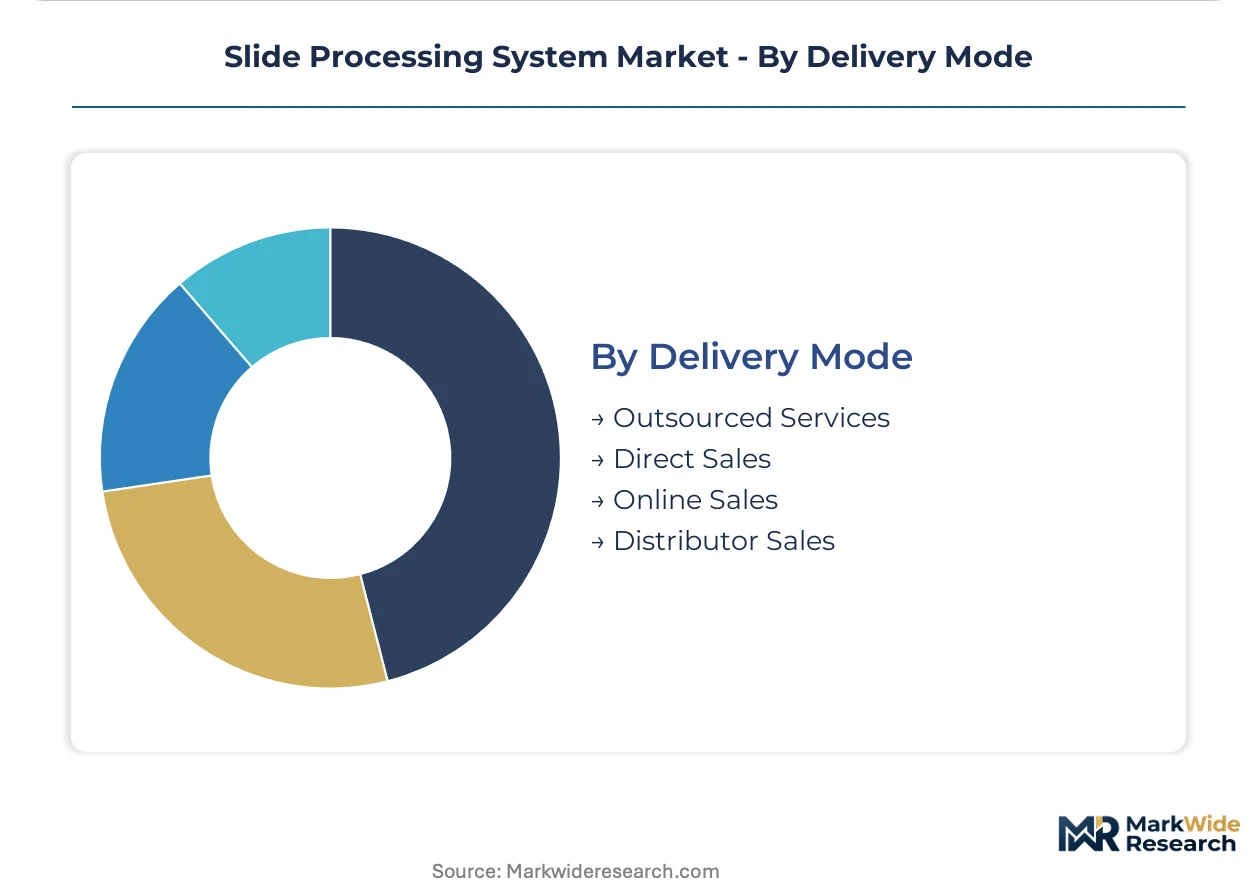
Delivery Mode:
Volume concentration among large health system purchasers is compressing distributor margins and accelerating direct-to-laboratory e-procurement channel development.
- Direct Sales:Manufacturer-led transactions bundling installation, validation, and training services capture premium margin pools. Leica Biosystems and ZEISS leverage extensive field service networks to secure multi-year maintenance contracts alongside capital equipment placement.
- Distributor Sales:Regional medical equipment specialists maintain relationships with mid-tier independent laboratories. Third-party maintenance providers are capturing calibration and preventive service work previously reserved by original equipment manufacturers across North American hospital networks.
- Outsourced Services:Contract slide processing arrangements for overflow capacity.
- Online Sales:Price-transparent equipment marketplaces enabled by group purchasing organization unbundling.
Direct sales holds the largest share; online sales shows the steepest expansion trajectory as procurement transparency initiatives reshape vendor-captive relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics manufacturing concentrates in Germany and Japan, creating supply dependencies for slide processing equipment OEMs seeking lens assemblies and optical components. This geographic clustering shapes equipment availability and lead times across diagnostic laboratory networks.
United States
FDA quality system regulations impose seven-figure validation burdens on diagnostic-grade slide processing systems. Academic medical centers in Boston and the San Francisco Bay Area pilot direct-to-digital frozen section workflows that bypass traditional glass slide preparation. The National Cancer Institute's screening programs drive automated staining line installations in regional hospital networks.
Germany
Centralized pathology networks in North Rhine-Westphalia and Bavaria standardize high-throughput workflow specifications adopted by neighboring health systems. EU IVDR compliance deadlines accelerate platform replacements across diagnostic laboratories in Berlin and Hamburg. REACH substance restrictions force reformulation of traditional hematoxylin and eosin staining protocols.
Japan
METI industrial policy supports precision optics clusters in Nagoya and Osaka that supply critical lens assemblies to equipment manufacturers. PMDA regulatory frameworks align with international standards for in-vitro diagnostic devices. Pharmaceutical toxicology studies in Tokyo and Kansai research corridors multiply slide throughput demands for automated processors.
India
PLI scheme incentives for medical device manufacturing attract contract assembly partners to serve South Asian diagnostic markets. CDSCO regulatory harmonization with international standards streamlines import substitution timelines. Research institutions in Maharashtra and Karnataka defer full automation investments pending domestic production cost reductions.
China
NMPA medical device registration requirements shape procurement criteria for hospital laboratory networks in Shanghai and Beijing. Dual carbon goals accelerate development of water-based staining alternatives to hazardous reagent formulations. Yangtze River Delta manufacturing clusters expand contract production capacity for regional equipment brands.
Slide Processing System Market Competitive Landscape
Optics-integrated platform specialists and field-service-anchored systems providers split the market between premium staining-to-imaging convergence and maintenance-contract profitability. The vendor base clusters around three strategic archetypes: precision optics manufacturers extending equipment lifecycles, extensive service network operators capturing recurring maintenance revenue, and digital pathology integrators bundling scanners with proprietary software. Dominant competitive moves include backward integration into optical component supply and geographic expansion through regional laboratory consolidation partnerships.
Among precision optics manufacturers, ZEISS and Nikon Corporation anchor the premium equipment tier through lens assembly capabilities that reduce total cost of ownership. Hamamatsu Photonics occupies a position exemplifying digital pathology convergence, representing the scanner-software integration archetype. Leica Biosystems sits within the service-intensive tier, leveraging field infrastructure to secure multi-year maintenance contracts alongside capital placements.
| Leading Market Players |
|---|
| 3DHISTECH |
| Hamamatsu Photonics |
| Olympus Corporation |
| Leica Biosystems |
| Koninklijke Philips |
| ZEISS |
| PerkinElmer |
| Nikon Corporation |
| Visiopharm |
| Others |
Value Network & Pricing Analysis
Nagoya's precision optics manufacturing clusters in Japan constrain downstream pricing power for slide processing equipment OEMs seeking German and Japanese lens assemblies. Capacity allocation at these optical component hubs determines equipment availability and lead times across diagnostic laboratory networks, compressing margins for manufacturers without captive supply arrangements.
Pricing Analysis
After-sales service contracts generate lifetime value exceeding original equipment margins in the slide processing system market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic platforms from research-grade configurations and manual benchtop units. Price differentiation rests on ISO 15189 certification tier and bundled field service intensity. Cost compression in mid-tier segments is intensifying because group purchasing organizations are unbundling installation and validation from capital sales. Independent diagnostic laboratories exhibit highest price sensitivity; academic medical centers with grant funding show lowest.
Supply Chain Analysis
Single-source vulnerability between German optical component manufacturers and Japanese precision lens suppliers dominates supply chain risk exposure for equipment OEMs. Manufacturing concentration in Germany, Japan, and China shapes component availability for automated staining platforms. Critical inputs include precision lens assemblies, robotic liquid handling modules, and specialized histological reagents. Tariff exposure on precision optics imports threatens margin stability for North American equipment assemblers. Distribution runs through direct manufacturer sales for hospital networks and regional medical equipment distributors for independent laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slide processing system market is entering a cyclical recovery phase as EU IVDR compliance deadlines force replacement of legacy diagnostic equipment across European laboratory networks.
For Market Incumbents: Build switching-cost moats through deep integration of staining-to-imaging platforms with proprietary image analysis software. Leica Biosystems and ZEISS should expand field service network density to capture multi-year maintenance contracts that anchor customer retention. Threat from direct-to-digital frozen section workflows in academic medical centers demands counterinvestment in real-time quality control algorithms. Capacity addition in India's PLI scheme zones offers cost-competitive assembly options for South Asian market penetration. For New Entrants and Emerging Players: Establish a beachhead in India's contract research organization segment where PLI scheme incentives reduce capital barriers for domestic equipment assembly. Spatial transcriptomics protocols in pharmaceutical toxicology studies represent the most penetrable application white space, with tenfold slide throughput expansion creating demand for mid-tier automated processors. Unbundled third-party maintenance services in North American hospital networks offer a channel entry point bypassing entrenched manufacturer-direct relationships. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because aftermarket service intensity peaks with automated platform installed bases. Acquisition targets should concentrate on precision optics specialists with lens assembly capabilities that reduce total cost of ownership and extend equipment lifecycles. Watch for inflection signals in digital pathology interoperability standard adoption that determines next-generation platform competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance documentation accelerates platform replacements in German diagnostic laboratories. |
| Hospital System Partnership | Integrated staining-to-imaging contracts compress procurement cycles for North American health networks. |
| Software Companion Development | Real-time quality control algorithms create premium platform tiers with service-anchored pricing. |
| Backward Integration into Optics | In-house lens assembly capabilities reduce single-source vulnerability to German and Japanese suppliers. |
| Reimbursement Strategy | Cancer screening program coverage determines automated staining line adoption in regional hospital networks. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with histopathology laboratory directors, biomedical equipment procurement managers, GPO contracts specialists, and ASCP-credentialed histotechnologists informed operational workflow requirements. Secondary sources include FDA 510(k) device clearances, EU IVDR technical documentation databases, ISO 15189 accreditation registries, and hospital capital expenditure disclosures. Bottom-up equipment shipment analysis triangulates against top-down diagnostic laboratory spending estimates.
Calibration against historical replacement cycles and regulatory compliance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include automation level, application type, end-user category, and geographic regulatory cluster. CAGRs derive from equipment installed base growth, reagent consumption patterns, and service contract renewal rates. Forecast inputs incorporate pathologist workforce shortage projections and spatial transcriptomics protocol adoption curves in pharmaceutical research.
Sensitivities concentrate around EU IVDR implementation delays, precision optics supply disruptions, and digital pathology scanner substitution rates. Forecasts reflect documented assumptions about laboratory consolidation trajectories and automation adoption thresholds. Macroeconomic contraction affecting hospital capital budgets, regulatory harmonization setbacks, or breakthrough digital pathology technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Photoresist for Semiconductor Market