
 Automatic Mounter Wafer Equipment Market | 2026-2036
Automatic Mounter Wafer Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Mounter Wafer Equipment Market Outlook
Consolidation among advanced packaging foundries is repositioning procurement leverage toward buyers with multi-fab expansion programs. Disco Corporation leverages its dicing-mounter integration expertise to anchor relationships with memory manufacturers. Tokyo Electron competes through etch-to-mount process continuity in logic device workflows. Lintec Corporation specializes in adhesive tape engineering that sustains yield rates during high-volume wafer thinning operations.
Automatic mounter wafer equipment comprises precision machinery that bonds diced semiconductor dies to carrier substrates using controlled pressure, temperature, and alignment parameters typically achieving placement accuracy within ±10 micrometers. The equipment serves primarily to protect fragile thinned wafers during backgrinding and transport processes in advanced packaging flows. High-speed mounters dominate volume throughput in memory packaging lines where die-per-hour rates determine fab economics. Flexible mounters capture margin pools in heterogeneous integration applications requiring rapid reconfiguration between chiplet architectures. Optical technology leads alignment precision for sub-7nm node devices where visual registration tolerances tighten progressively.
Japan's METI coordinates domestic equipment supply chain security through its semiconductor revitalization framework, directly shaping local procurement preferences for mounter systems. The US CHIPS Program Office imposes domestic content thresholds on subsidized fab construction, altering vendor qualification pathways for non-American suppliers. China's MIIT advances GB standard harmonization for packaging equipment import substitution, creating divergent certification requirements across major demand centers. Stakeholders must monitor how regional subsidy compliance rules fragment equipment specification standards and reshape supplier geographic deployment strategies.
Market Dynamics
Advanced packaging node migration toward 3D stacking and chiplet architectures is restructuring equipment procurement priorities, with placement accuracy requirements tightening from ±15 micrometers to sub-±5 micrometer tolerances for heterogeneous integration workflows.
Growth Catalysts
- Chiplet Architecture Adoption:Disaggregated processor designs multiply die bonding steps per device, expanding mounter utilization rates in logic packaging lines.
- Japan METI Semiconductor Revitalization:Domestic equipment procurement subsidies accelerate replacement cycles for aging mounter fleets at Japanese packaging houses.
- High-Bandwidth Memory Stacks:HBM3E and subsequent generations require precision die stacking that conventional pick-and-place systems cannot achieve, pulling demand toward advanced mounter platforms.
Market Restraints
- Precision Motion Component Concentration:Linear motor and air bearing supply chains concentrate in Germany and Japan, creating single-source vulnerabilities for mounter OEMs.
- Substrate Warpage Limitations:Organic substrate thermal expansion coefficients restrict placement yield at wafer thicknesses below 50 micrometers, capping thinning process economics.
- US CHIPS Act Domestic Content Thresholds:Subsidized fab construction mandates minimum US-sourced equipment percentages, complicating qualification pathways for Asian mounter suppliers.
Strategic Opportunities
- India Semiconductor Mission:Packaging-specific PLI incentives attract mounter vendors to establish local assembly and calibration facilities serving emerging domestic OSAT capacity.
- Photonics Die Bonding:Silicon photonics transceiver manufacturing requires active alignment capabilities that extend mounter addressable market beyond traditional IC packaging.
- AI-Assisted Vision Systems:Machine learning-enhanced alignment algorithms reduce setup times between product changeovers, enabling mounter-as-a-service business models.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-disciplinary engineering combining precision mechanics, thermodynamics, and software control remains difficult to source across Taiwan, Japan, and South Korea packaging hubs.
- Multi-Vendor Integration Complexity:Mounter synchronization with upstream dicing and downstream wire bonding equipment from different OEMs generates protocol incompatibility and yield loss during line commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Mounter Wafer Equipment Market |
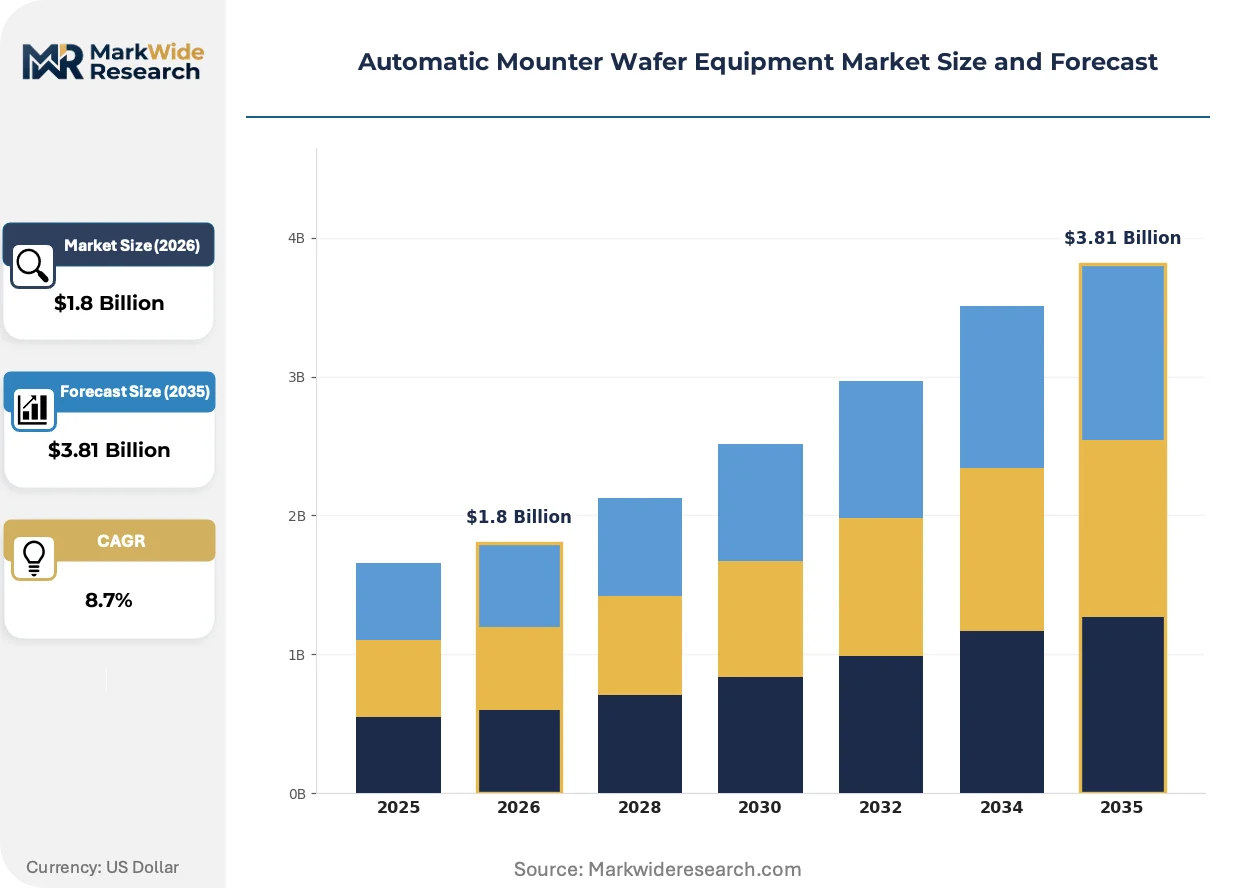
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mounters, High-Speed Mounters, Compact Mounters, Flexible Mounters Technology: Laser Technology, Optical Technology, Magnetic Technology, Pressure Technology End User: Semiconductor Manufacturers, Electronics Assembly Firms, Research Institutions, Foundries Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Automation |
| Companies Covered | Lintec Corporation, Nitto Denko Corporation, Disco Corporation, Takatori Corporation, Longhill Industries Limited, Applied Materials, Tokyo Electron, ASM International, SUSS MicroTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Mounter Wafer Equipment Market Strategic Shifts
Equipment intelligence layers are displacing mechanical precision as the primary competitive axis, with software-defined placement parameters and predictive maintenance modules determining vendor selection criteria in advanced packaging fabs.
Multi-axis linear motor stages with nanometer-resolution encoders are automating sub-micron die placement without mechanical z-axis contact, eliminating die crack defects in thinned silicon handling. Memory manufacturers in South Korea and Taiwan are retrofitting existing mounter footprints with these non-contact systems to extend equipment depreciation schedules. The technology is automating yield recovery processes that previously required manual operator intervention during high-volume production ramps.
China MIIT GB standard harmonization for semiconductor packaging equipment is mandating localized software architectures and maintenance documentation, creating divergent product variants for domestic versus export market deployment. Equipment vendors must maintain parallel firmware branches and certification test protocols, fragmenting engineering resources. Chinese OSATs are responding by prioritizing domestic mounter suppliers with native GB compliance over imported platforms requiring adaptation cycles.
Consolidated procurement through multi-fab expansion programs is compressing vendor qualification timelines and unbundling after-sales service contracts from equipment sales. Taiwan-based foundries now negotiate enterprise-level mounter fleet agreements spanning Hsinchu, Tainan, and Arizona facilities. This pattern concentrates most visible in memory packaging verticals where die-per-hour throughput guarantees dominate contract structures.
Automatic Mounter Wafer Equipment Market Segmentation
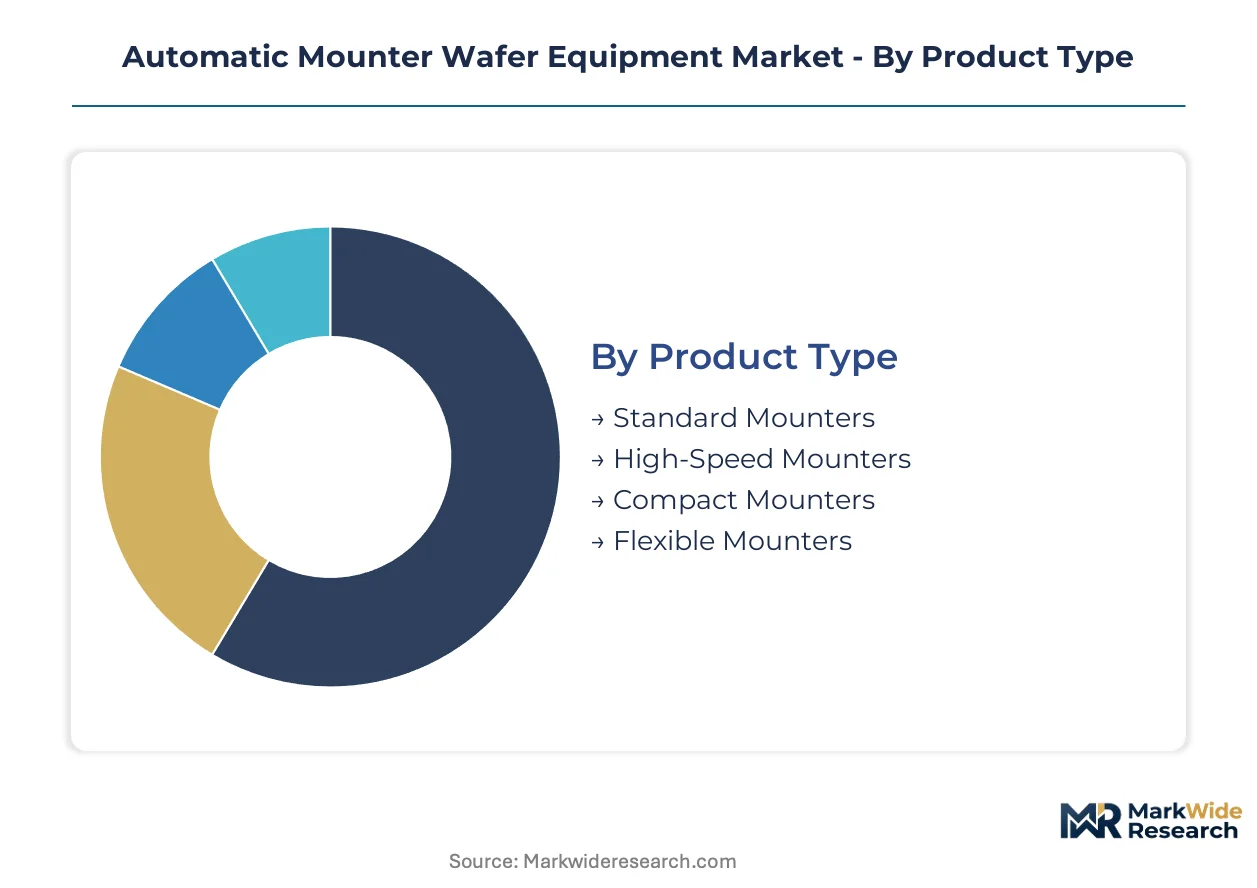
Segmentation in automatic mounter wafer equipment reveals distinct procurement patterns driven by die-per-hour throughput requirements, alignment precision tolerances, and fab integration complexity. Equipment buyers optimize capital allocation across product tiers based on packaging node migration and volume commitments.
Product Type:
Capital intensity varies sharply across mounter configurations, with high-throughput platforms demanding precision motion systems and multi-axis linear motor stages that multiply upfront investment.
- Standard Mounters:These systems deliver placement accuracy within ±10 micrometers using conventional mechanical z-axis contact mechanisms. Demand concentrates among mid-tier OSATs in Malaysia and Vietnam serving consumer electronics packaging lines where die-per-hour rates of 8,000-12,000 satisfy volume economics without premium positioning.
- High-Speed Mounters:Memory manufacturers in South Korea deploy these platforms for die-per-hour rates exceeding 15,000, leveraging non-contact placement heads and predictive thermal compensation to sustain yield during HBM3E stacking operations. The capital commitment typically runs 40-60% above standard configurations.
- Compact Mounters:Space-constrained legacy fabs in Japan retrofit these footprint-optimized systems to extend facility depreciation schedules without cleanroom expansion.
- Flexible Mounters:Rapid reconfiguration capabilities serve heterogeneous integration workflows across Taiwan's advanced packaging foundries.
Most installed capacity flows through high-speed mounters. Expansion is steepest in flexible mounters.
Technology:
Alignment methodology determines yield recovery economics, with optical and laser systems commanding premium positioning against mechanical alternatives.
- Laser Technology:Sub-micron registration accuracy enables thinned wafer handling below 30 micrometers without die crack defects. Foundries in Taiwan's Tainan Science Park prioritize laser-guided systems for chiplet architectures where placement tolerances tighten to sub-±5 micrometers.
- Optical Technology:Machine vision with AI-assisted pattern recognition dominates logic device workflows, reducing setup times between product changeovers by 30-50% compared to rule-based alignment. Japanese packaging houses favor optical platforms for mixed-product lines serving automotive electronics qualification requirements.
- Magnetic Technology:Ferromagnetic substrate handling suits specialty magnetic sensor packaging with limited addressable volume.
- Pressure Technology:Pneumatic placement heads retain cost advantages in mature node packaging with relaxed tolerance specifications.
Optical systems anchor current procurement volumes. Laser platforms are gaining share fastest in advanced packaging conversions.
End User:
Customer scale and integration depth reshape vendor relationship structures, with foundries negotiating enterprise fleet agreements against fragmented OSAT purchasing.
- Semiconductor Manufacturers:Integrated device manufacturers in the US and Japan maintain captive packaging capacity with mounter fleets synchronized to internal wafer fab output. Intel's Arizona and Ohio expansions drive qualification of domestic-content-compliant equipment under CHIPS Act thresholds.
- Foundries:TSMC and Samsung Foundry consolidate procurement across Hsinchu, Tainan, Pyeongtaek, and Taylor facilities, compressing vendor qualification timelines and unbundling service contracts from equipment sales. These enterprise agreements concentrate visible demand for high-speed and flexible mounter platforms.
- Electronics Assembly Firms:Tier-2 OSATs in Southeast Asia prioritize standard mounter configurations with localized maintenance support.
- Research Institutions:University cleanrooms and national laboratories in Germany and the Netherlands acquire compact systems for process development without production volume guarantees.
Foundries command the dominant share of new equipment bookings. Electronics assembly firms show the steepest volume climb from Southeast Asia capacity expansion.
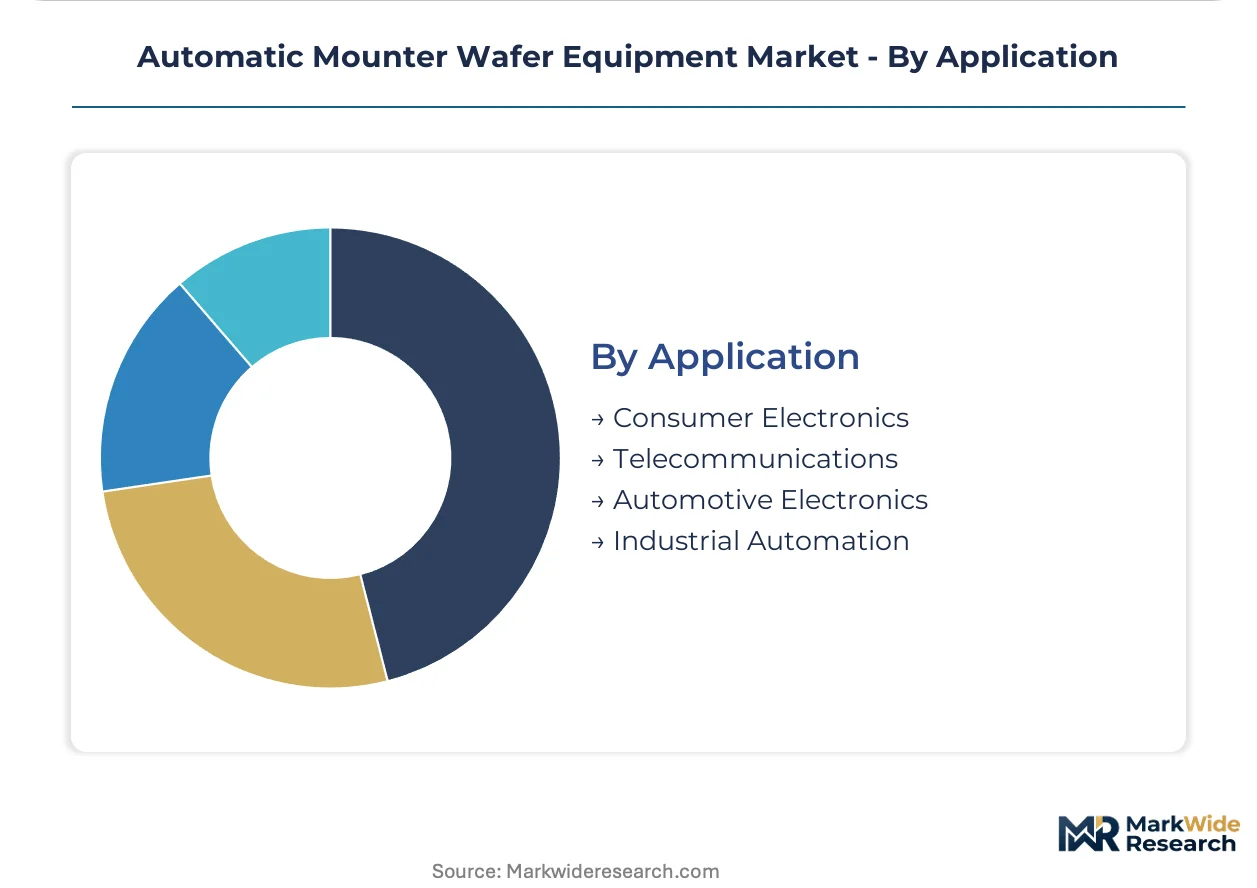
Application:
End-market reliability requirements stratify equipment specifications, with automotive and telecommunications demanding extended qualification protocols.
- Telecommunications:5G baseband and mmWave module packaging drives demand for flexible mounters handling diverse die sizes in single workflows. Ericsson and Nokia supply chain qualification requirements in Finland and Sweden extend vendor audit cycles to 18-24 months.
- Automotive Electronics:AEC-Q100 and ISO 26262 compliance mandates thermal cycling validation for mounter placement repeatability. Bosch and Continental packaging partners in Germany specify 99.97% first-pass yield guarantees with full traceability documentation.
- Consumer Electronics:Smartphone AP and PMIC packaging concentrates volume demand in China and Vietnam OSATs with compressed product lifecycles.
- Industrial Automation:Power module and motor driver packaging requires thicker die handling with specialized pressure technology configurations.
Consumer electronics absorbs the largest equipment base. Automotive electronics is expanding most quickly from electrification-driven semiconductor content growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision mechatronics engineers cluster in Taiwan's Hsinchu Science Park, Japan's Nagoya industrial corridor, and South Korea's Suwon-Giheung belt, anchoring equipment design and field service capabilities for advanced packaging ecosystems.
United States
Intel's Ohio and Arizona fab expansions drive qualification of domestic-content-compliant mounter systems under CHIPS Act procurement thresholds. The Department of Commerce mandates minimum US-sourced equipment percentages for subsidized construction, altering vendor pathways for Asian suppliers. Phoenix and Columbus metro areas concentrate packaging equipment commissioning activity for captive IDM capacity.
Taiwan
TSMC and ASE Group consolidate multi-fab procurement across Hsinchu, Tainan, and Kaohsiung facilities, compressing vendor qualification timelines. The National Science and Technology Council coordinates equipment supply chain security through domestic preference frameworks. Tainan Science Park anchors laser-guided mounter deployment for chiplet architectures requiring sub-±5 micrometer placement tolerances.
Japan
Memory manufacturers in Hiroshima and Mie prefectures retrofit aging mounter fleets under METI semiconductor revitalization subsidies. The Ministry of Economy, Trade and Industry directly shapes local procurement preferences through domestic equipment procurement incentives. Nagoya's precision machinery cluster sustains linear motor and air bearing component supply for regional OEMs.
South Korea
Samsung Electronics and SK Hynix drive die-per-hour throughput requirements exceeding 15,000 for HBM3E stacking operations. The Ministry of Trade, Industry and Energy funds packaging equipment localization through K-Chips initiative grants. Suwon-Giheung and Icheon production corridors concentrate high-speed mounter utilization for memory packaging verticals.
China
Domestic OSATs in Jiangsu and Guangdong provinces prioritize GB standard-compliant mounter platforms for import substitution. MIIT mandates localized software architectures and maintenance documentation, fragmenting engineering resources across product variants. Suzhou and Shenzhen industrial parks concentrate procurement of domestic suppliers with native certification over adapted import platforms.
Automatic Mounter Wafer Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment tiers, creating a bifurcated structure where scale-driven portfolio breadth confronts targeted sub-system expertise. The vendor base stratifies into three archetypes: integrated process equipment conglomerates spanning deposition through packaging, precision machinery specialists anchored in dicing-to-mount workflow continuity, and adhesive materials engineers extending into capital equipment adjacencies. Consolidation pressure intensifies through multi-fab enterprise procurement agreements and unbundled service contract negotiations.
Within the precision machinery specialist tier, Disco Corporation exemplifies dicing-mounter integration expertise, while Tokyo Electron occupies a position spanning etch-to-mount process continuity. Lintec Corporation represents the materials-to-equipment extension archetype, anchoring relationships through adhesive tape engineering capabilities. These three Japanese entities collectively illustrate how sub-system mastery shapes vendor selection criteria in advanced packaging flows.
| Leading Market Players |
|---|
| Lintec Corporation |
| Nitto Denko Corporation |
| Disco Corporation |
| Takatori Corporation |
| Longhill Industries Limited |
| Applied Materials |
| Tokyo Electron |
| ASM International |
| SUSS MicroTec |
| Others |
Value Chain & Pricing Dynamics
Linear motor and air bearing component costs from Germany and Japan flow through mounter OEM bill-of-materials into three-tier pricing structures across premium, standard, and economy levels. Precision motion system scarcity concentrates upstream pricing power with Japanese Nagoya corridor suppliers, compressing margins for mid-tier equipment assemblers serving Southeast Asian OSATs.
Pricing Analysis
The bundled-versus-unbunded service split now dominates contract architecture, with Taiwan-based foundries unbundling after-sales service from equipment sales to compress vendor margins. Pricing stratifies across premium, standard, and economy tiers based on placement accuracy certification and die-per-hour throughput guarantees, with memory manufacturers showing least price sensitivity for HBM3E-qualified platforms. Cost compression in standard mounter tiers intensifies because Malaysian and Vietnamese OSATs prioritize localized maintenance support over precision specifications. Electronics assembly firms in Southeast Asia exhibit highest price sensitivity, driving 30-40% capital expenditure discounts against foundry enterprise agreements.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing extend equipment depreciation schedules at Japanese memory manufacturers under METI revitalization subsidies. Component supply concentrates in Japan, Germany, and Taiwan, with precision motion systems drawing from Nagoya and Stuttgart industrial clusters. Raw material dependencies span high-grade aluminum castings, ceramic bearings, and specialized adhesive tapes from Lintec Corporation and Nitto Denko. Single-source vulnerability in linear motor supply chains creates qualification bottlenecks when German suppliers face capacity constraints. Distribution runs through direct OEM-fabricator relationships for high-speed platforms, while standard configurations reach Southeast Asian OSATs through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic mounter wafer equipment market functions as a stable compounder, with advanced packaging node migration toward chiplet architectures and HBM stacking generating sustained replacement demand across memory and logic fabrication lines.
For Market Incumbents: Anticipate margin compression from unbundled service contracts by deepening captive supply of precision motion components through Nagoya corridor partnerships. Accelerate software-defined placement parameter development to differentiate against emerging Chinese suppliers with native GB standard compliance. Vertical integration into predictive maintenance modules anchors recurring revenue streams as equipment intelligence layers displace mechanical precision as vendor selection criteria. For New Entrants and Emerging Players: India's Semiconductor Mission PLI incentives in Gujarat and Tamil Nadu open a window for packaging-specific mounter assembly and calibration facilities serving emerging domestic OSAT capacity. Target photonics die bonding applications for silicon photonics transceivers, where active alignment capabilities extend addressable market beyond traditional IC packaging with limited incumbent specialization. Pursue machine learning-enhanced vision system partnerships with AI software vendors to reduce setup times and enable mounter-as-a-service business models. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-fab enterprise procurement agreements compress vendor qualification timelines and fragment engineering resources across GB-compliant and export-market product variants. Five-to-ten year viability favors precision machinery specialists with dicing-to-mount workflow continuity and adhesive materials engineering capabilities. Monitor MIIT GB standard harmonization enforcement intensity as inflection indicator for domestic Chinese supplier market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Motion Component Backward Integration | Nagoya corridor partnerships reduce single-source vulnerability for linear motor supply. |
| Software-Defined Placement Parameter Development | AI-assisted vision systems displace mechanical precision as competitive axis in Taiwan foundries. |
| GB Standard Compliance Localization | Parallel firmware branches fragment engineering resources for China market access. |
| Photonics Die Bonding Capability Expansion | Silicon photonics transceiver manufacturing extends addressable market beyond IC packaging. |
| India Semiconductor Mission Facility Establishment | Gujarat and Tamil Nadu PLI incentives attract local assembly serving emerging OSAT capacity. |
Study Parameters
Direct dialogue with packaging equipment procurement directors, precision machinery R&D leads, OSAT operations managers, and semiconductor foundry supply chain executives grounded qualitative assessment in operational reality. Secondary validation drew from METI semiconductor revitalization policy documents, MIIT GB standard harmonization notices, US CHIPS Program Office procurement guidelines, SEC filings of listed equipment vendors, and Taiwan National Science and Technology Council supply chain security frameworks. Bottom-up equipment shipment aggregation and top-down fab capacity expansion modeling triangulated market sizing across the analysis window.
Segment-level outputs reflect disaggregation by product type, alignment technology, end-user category, and application vertical throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, packaging node migration timelines, and regional subsidy program implementation schedules. Industry-specific inputs incorporated HBM3E stacking throughput requirements, chiplet architecture die bonding step multiplication, and domestic content threshold compliance pathways for subsidized fab construction.
Revisions become necessary when METI revitalization subsidy disbursement delays, MIIT GB standard enforcement intensity shifts, or CHIPS Act domestic content threshold adjustments materialize. Practitioners should monitor precision motion component lead time fluctuations, multi-fab enterprise procurement agreement announcements, and AI-assisted vision system regulatory classification developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Global Resist Processing Equipment Market