
 Global Equipment Front End Module (EFEM) Market | 2026-2036
Global Equipment Front End Module (EFEM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Equipment Front End Module (EFEM) Market Analysis
Market Context
Modular robotics architecture is reconfiguring how semiconductor equipment suppliers design EFEM subsystems for tool-to-tool interoperability. Hirata Corporation leverages its precision motion control heritage to dominate Japanese OEM supply chains. Brooks Automation anchors North American presence through its atmospheric and vacuum robotics portfolio. Yaskawa Electric competes with articulated robot platforms optimized for cleanroom payload handling.
Technical Definition and Segment Structure
An Equipment Front End Module is a self-contained atmospheric handling system that interfaces between semiconductor process tools and factory automation, typically incorporating load ports, robots, and environmental isolation rated to ISO Class 1-3 cleanliness. Its primary purpose is to transfer wafers between FOUPs and process chambers while minimizing particle contamination and maximizing throughput. The 300mm EFEM category leads value generation as foundries deploy larger wafer formats for advanced logic and memory nodes. Robotics technology within EFEMs captures concentrated margin pools because precision kinematics and vibration suppression differentiate tool performance. Semiconductor Manufacturers represent the dominant end-user segment, though Automotive OEMs are emerging as a specialized demand channel for power semiconductor fabrication.
Regulatory Framework
Japan's METI enforces semiconductor equipment standards through JIS certification requirements that govern robot positioning accuracy and cleanroom compatibility. The EU F-Gas Regulation and REACH chemical restrictions shape material selection for EFEM seals and lubricants in European deployments. ISO 14644 cleanroom classification standards provide the global baseline for particle control validation. Stakeholders must monitor how dual-use export control expansions affect robot component sourcing from Japanese and Korean suppliers.
Market Dynamics
300mm wafer format migration is compressing EFEM replacement cycles as foundries retool for advanced nodes below 7nm, forcing atmospheric handling equipment suppliers to synchronize roadmaps with lithography and etch tool refresh schedules.
Growth Catalysts
- Advanced Node Expansion:Taiwan and South Korea foundries are scaling 300mm capacity for 3nm and 2nm logic production, requiring EFEM upgrades with higher throughput kinematics and tighter particle control.
- ISO 14644-1 Revisions:Tighter cleanroom classification thresholds for ISO Class 1-2 environments are mandating equipment retrofits in Japanese and Korean fabrication facilities.
- Power Semiconductor Fabrication:Automotive OEM demand for silicon carbide and gallium nitride devices is pulling EFEM procurement into dedicated wide-bandgap wafer lines.
Market Restraints
- Precision Component Supply Concentration:Harmonic drive actuators and ceramic bearings for vacuum-compatible robots concentrate among Japanese suppliers, exposing lead time vulnerability.
- F-Gas Regulation Compliance Costs:EU restrictions on fluorinated greenhouse gases are forcing seal material reformulation, adding validation cycles for European deployments.
- Cleanroom Footprint Constraints:Existing fab layouts limit EFEM physical expansion, restricting modular upgrade paths without chamber reconfiguration.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction are creating first-mover EFEM installation demand in Gujarat and Assam greenfield sites.
- Digital Twin Integration:Convergence of physics-based simulation with live EFEM telemetry is enabling predictive maintenance contracts that unbundle hardware from service revenue.
- Automotive Qualification Pathways:AEC-Q100 and IATF 16949 certification requirements for power device manufacturing are opening specialized EFEM configurations.
Industry Challenges
- Mechatronics Talent Scarcity:Cleanroom robotics calibration and vibration engineering expertise concentrates among aging specialists in Japan and Germany, constraining field service scaling.
- Multi-Tool Integration Complexity:EFEM interoperability with legacy cluster tools from disparate OEMs demands custom kinematic mapping, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Equipment Front End Module (EFEM) Market |
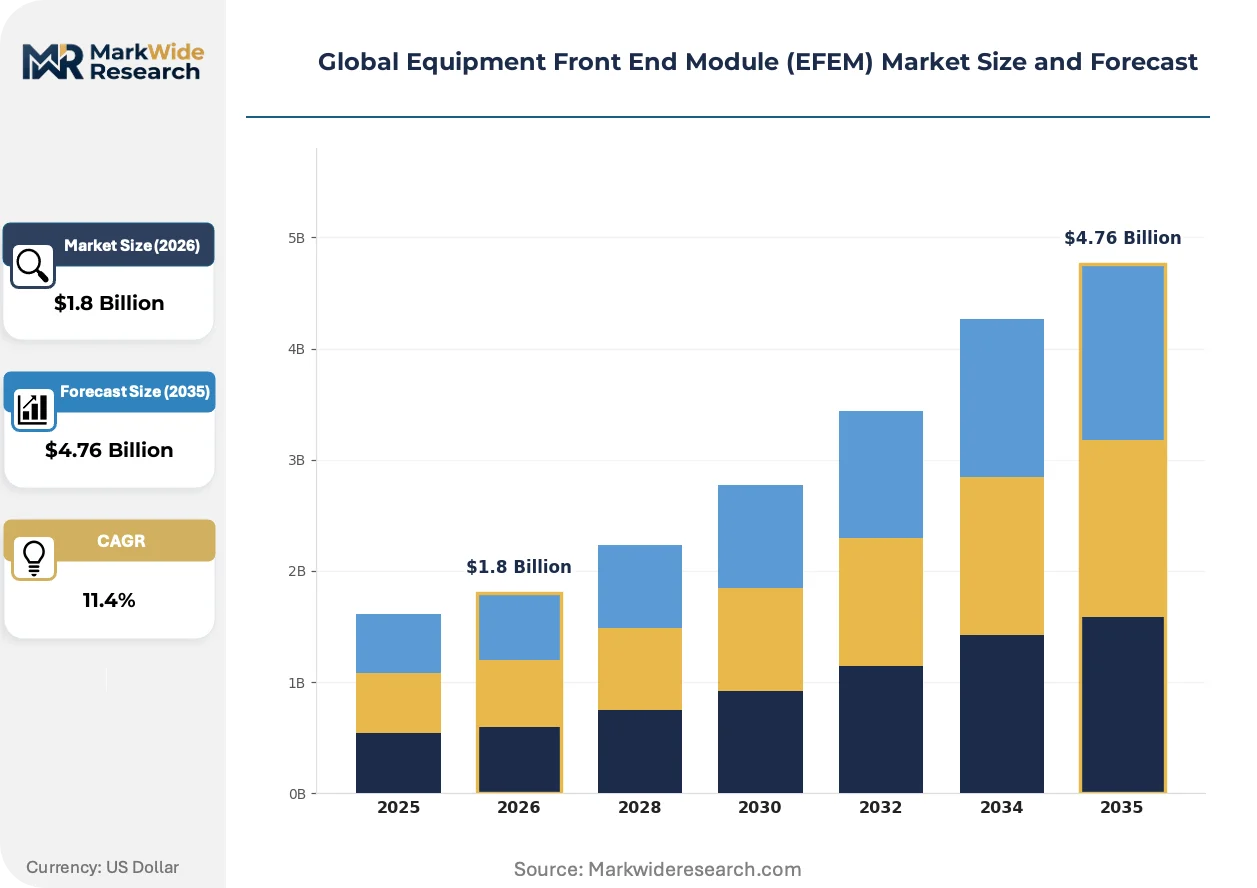
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 200mm EFEM, 300mm EFEM, Hybrid EFEM, Specialty EFEM Technology: Robotics, Automation, Control Systems, Sensors End User: Semiconductor Manufacturers, Electronics Companies, Automotive OEMs, Cleanroom Operators Deployment: On-Premises, Cloud-Based, Hybrid, Dedicated Solutions |
| Companies Covered | Hirata Corporation, Kensington, Robots and Design, Beijing Heqi Precision Technology, Milara, Genmark Automation, Fala Technologies, Brooks Automation, Yaskawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Equipment Front End Module (EFEM) Market Emerging Trajectories
Computational modeling is displacing physical prototyping in EFEM development cycles, compressing time-to-qualification while raising the bar for real-time performance validation in production environments.
Digital twin platforms for atmospheric handling systems are virtualizing robot path planning and particle transport simulation before physical installation. Foundry engineering teams in Taiwan are deploying these tools to validate EFEM configurations against specific process tool kinematic envelopes. This virtualization is compressing site acceptance testing from weeks to days while reducing wafer loss during commissioning.
Japan's METI semiconductor equipment standards are tightening JIS certification requirements for robot positioning repeatability below ±0.1mm in ISO Class 1 environments. Domestic suppliers must recertify existing platforms, creating compliance backlog queues at accredited test facilities. Korean foundries importing Japanese EFEM subsystems are demanding parallel certification documentation to satisfy MFDS equipment validation protocols.
Consolidated procurement consortia among memory manufacturers are displacing single-tool purchasing, with Samsung and SK Hynix negotiating multi-site EFEM framework agreements that standardize on common load port and robot specifications. Equipment suppliers must restructure sales organizations to respond to centralized technical committees rather than individual fab managers. This concentration is most visible in Pyeongtaek and Yongin cluster expansions where standardized EFEM configurations reduce spare parts inventory complexity.
Global Equipment Front End Module (EFEM) Market Segmentation
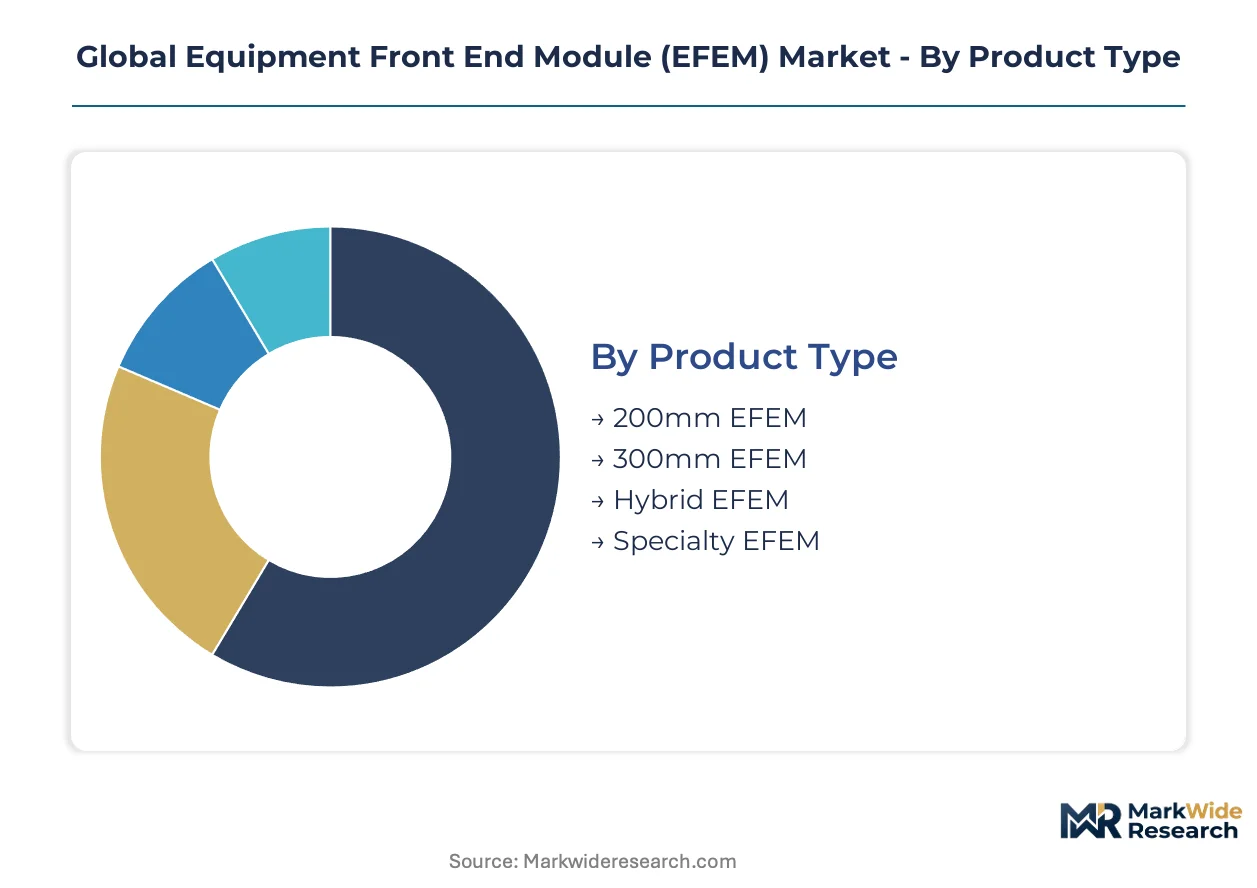
EFEM segmentation reflects how wafer handling requirements diverge across node geometries, automation architectures, and end-user operational models. Each dimension carries distinct procurement patterns and technical validation protocols.
Product Type:
Foundries and memory houses select wafer format modules based on fab generation, node target, and retooling economics.
- 300mm EFEM:Atmospheric handling systems engineered for 300mm FOUPs dominate advanced logic and DRAM production. Taiwan and South Korea foundries are installing these for 3nm and 2nm node ramps, requiring kinematic precision below ±0.1mm and ISO Class 1-2 particle control.
- 200mm EFEM:Legacy-format modules serve mature-node analog, power discrete, and MEMS fabrication. Japanese IDMs retain these for mixed-signal and automotive-qualified production lines where capital efficiency outweighs format migration costs.
- Hybrid EFEM:Dual-format configurable platforms bridge 200mm and 300mm tooling within single tool footprints.
- Specialty EFEM:Custom atmospheric handlers address compound semiconductor, photonics, and research wafer formats outside standard silicon roadmaps.
The dominant share belongs to 300mm EFEM, while Hybrid EFEM is closing the gap fastest as foundries seek format flexibility without full retooling.
Technology:
Component-level technology choices determine throughput ceilings, maintenance intervals, and qualification timelines.
- Robotics:Articulated and SCARA robot platforms execute wafer transport between load ports and process chambers. Japanese suppliers concentrate harmonic drive and ceramic bearing production for vacuum-compatible motion systems.
- Automation:Factory host communication and scheduling software layers coordinate EFEM operation with AMHS and MES infrastructure. Korean foundries demand SECS/GEM compliance and E84 parallel I/O for tool-to-tool interoperability.
- Control Systems:Real-time kinematic controllers manage path planning, collision avoidance, and vibration suppression during wafer handoff.
- Sensors:Optical and capacitive sensing arrays verify wafer presence, orientation, and edge integrity before chamber entry.
Robotics commands the largest technology spend, though Control Systems is expanding most quickly as positioning repeatability requirements tighten below 7nm production thresholds.
End User:
Buyer categories span integrated device manufacturing, outsourced foundry services, and emerging automotive vertical integration.
- Semiconductor Manufacturers:Pure-play foundries and IDMs constitute the core procurement base, specifying EFEM configurations to match lithography and etch tool kinematic envelopes. Samsung and TSMC negotiate multi-site framework agreements that standardize load port and robot specifications across Pyeongtaek, Yongin, and Tainan clusters.
- Automotive OEMs:Tier-1 vehicle manufacturers are building captive silicon carbide and gallium nitride fabrication capacity. These buyers demand AEC-Q100 and IATF 16949 qualified EFEM configurations for power device manufacturing.
- Electronics Companies:Systems houses with internal semiconductor operations purchase EFEMs for captive MEMS and sensor fabrication.
- Cleanroom Operators:Third-party fab management providers procure EFEMs as part of turn-key cleanroom infrastructure packages.
Semiconductor Manufacturers retain the dominant procurement volume, while Automotive OEMs is gaining share fastest as electrification drives vertical integration into power semiconductor fabrication.
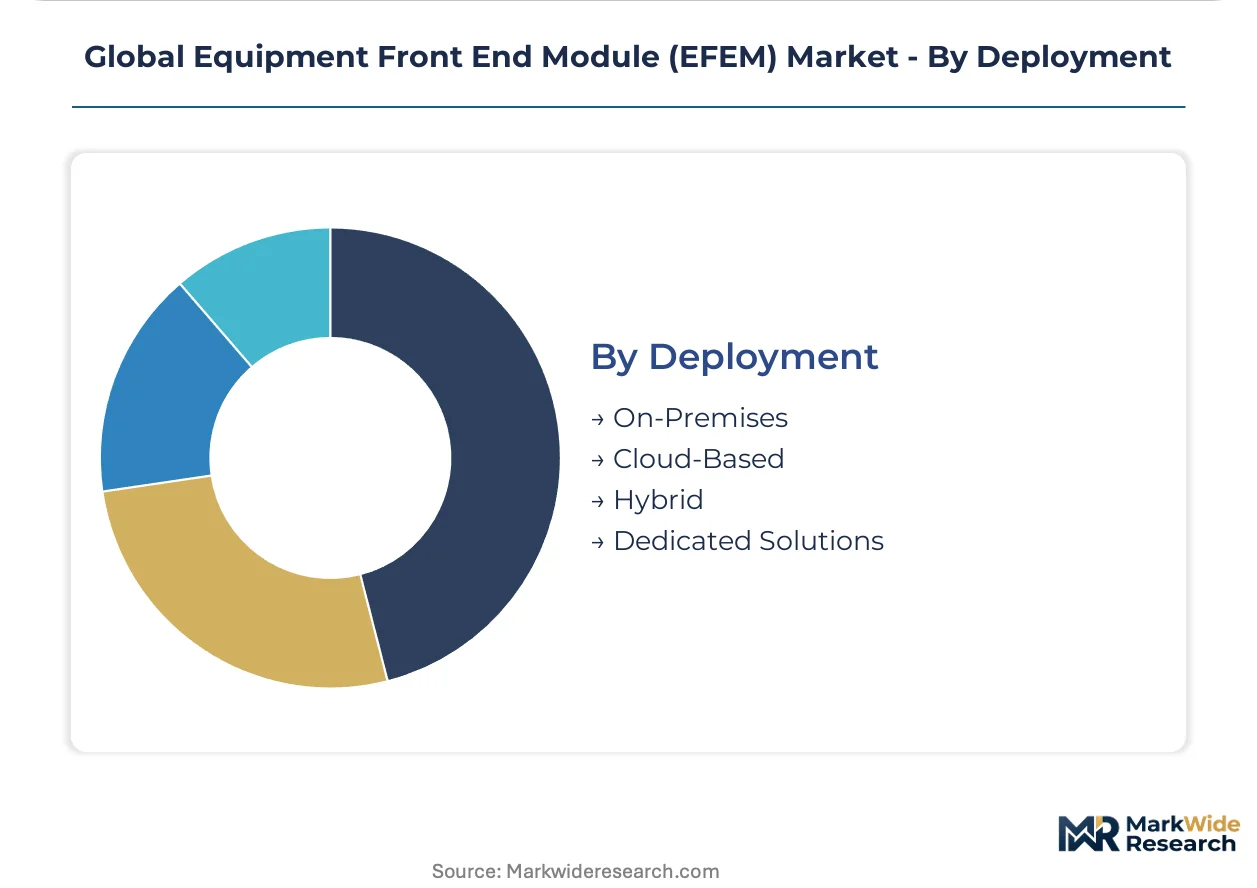
Deployment:
Installation architecture reflects data sovereignty requirements, predictive maintenance maturity, and capital deployment preferences.
- On-Premises:Fully localized EFEM control systems keep all kinematic logic and process data within fab firewalls. Japanese and Korean facilities favor this architecture for intellectual property protection and deterministic latency in robot path execution.
- Dedicated Solutions:Single-purpose EFEM configurations optimized for specific process tool pairings, common in legacy fab retrofits where tool-to-tool variability demands custom kinematic mapping.
- Hybrid:Split architectures run real-time control locally while streaming telemetry to cloud analytics for predictive maintenance model training.
- Cloud-Based:Centralized kinematic planning and optimization algorithms executed remotely, still nascent for production EFEM deployments due to latency constraints.
On-Premises deployment holds the largest installed base, though Hybrid architectures are climbing the fastest as foundries pilot digital twin integration without sacrificing real-time control determinism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment Front End Module procurement concentrates among foundry operators and IDMs in East Asian manufacturing clusters, with secondary demand emerging from automotive power semiconductor fabricators in Europe and North America.
Taiwan
TSMC and UMC are expanding 300mm capacity for 3nm logic production, driving EFEM upgrades with ISO Class 1 particle control. Taiwan's National Science and Technology Council subsidizes advanced packaging equipment through the Chip Implementation Center. The Tainan Science Park hosts the densest concentration of EFEM installations for leading-edge node ramp-ups.
South Korea
Samsung and SK Hynix are negotiating multi-site framework agreements for standardized EFEM configurations across memory fabs. The Ministry of Trade, Industry and Energy enforces MFDS equipment validation protocols for imported Japanese subsystems. The Yongin and Pyeongtaek semiconductor clusters are adding 300mm capacity for DRAM and NAND flash production.
Japan
Japanese IDMs are retrofitting mature-node lines for automotive-qualified mixed-signal production under METI's semiconductor revitalization policy. METI enforces JIS certification requirements for robot positioning repeatability below ±0.1mm. The Kyushu region maintains significant 200mm EFEM infrastructure for power discrete and sensor fabrication.
United States
Intel and GlobalFoundries are expanding domestic 300mm capacity under CHIPS Act incentives, creating EFEM demand for greenfield fabs in Arizona and New York. The Department of Commerce administers export control classifications affecting robot component sourcing. The Phoenix metropolitan area is attracting concentrated EFEM installation activity for advanced logic production.
Germany
Infineon and Bosch are building captive silicon carbide fabrication capacity for automotive electrification, requiring AEC-Q100 qualified EFEM configurations. The EU F-Gas Regulation forces seal material reformulation for European deployments. The Dresden semiconductor cluster is expanding EFEM infrastructure for power semiconductor and sensor manufacturing.
Global Equipment Front End Module (EFEM) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where precision motion control heritage determines access to Japanese and Korean OEM supply chains. The vendor base organizes around three archetypes: precision robotics specialists with cleanroom automation lineages, diversified industrial automation conglomerates with semiconductor divisions, and regional system integrators serving emerging fab markets. Consolidation pressure is intensifying as foundry procurement committees demand multi-site framework agreements, while technology licensing partnerships are proliferating to address mechatronics talent scarcity in field service operations.
Among precision-focused Japanese suppliers, Hirata Corporation and Yaskawa Electric exemplify the heritage-driven archetype that dominates kinematic subsystem supply to East Asian foundries. Brooks Automation represents the North American channel anchor with atmospheric and vacuum robotics portfolios. Beijing Heqi Precision Technology occupies a position within the emerging Chinese supplier tier targeting domestic fab construction under the China Semiconductor Industry Association roadmap.
| Leading Market Players |
|---|
| Hirata Corporation |
| Kensington |
| Robots and Design |
| Beijing Heqi Precision Technology |
| Milara |
| Genmark Automation |
| Fala Technologies |
| Brooks Automation |
| Yaskawa Electric |
| Others |
Supply Flow & Price Mechanics
The Kaohsiung-Osaka air freight corridor carries precision robot components and ceramic bearings from Japanese suppliers to Taiwanese foundries, with freight cost volatility feeding directly into EFEM subsystem pricing and reinforcing the premium commanded by kinematic-certified configurations over standard atmospheric handling units.
Pricing Analysis
Cost-plus contracts with Japanese harmonic drive suppliers index to JIS certification backlog queues and ceramic bearing spot availability, creating pricing stratification across ISO Class 1-certified, ISO Class 2-compliant, and uncertified economy tiers. Price differentiation hinges on positioning repeatability grade and METI validation status. Cost compression in the economy tier intensifies as Chinese suppliers enter 200mm retrofit markets. Memory manufacturers negotiating multi-site framework agreements exhibit lowest price sensitivity; automotive OEMs building captive SiC lines show highest.
Supply Chain Analysis
Contract manufacturing concentrates among Hirata Corporation's precision motion facilities in Japan, Brooks Automation's atmospheric robotics plants in the United States, and Yaskawa Electric's cleanroom automation centers. EFEM production draws from harmonic drive actuators, ceramic bearings, and fluorinated seal materials. Single-source vulnerability concentrates in Japanese harmonic drive supply. Distribution runs through OEM direct sales teams serving foundry procurement committees and regional system integrators for greenfield installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EFEM market sits in early-cycle expansion as 300mm capacity additions for 3nm and 2nm nodes pull atmospheric handling upgrades ahead of traditional replacement schedules.
For Market Incumbents: Build switching-cost moats through digital twin platform subscriptions that virtualize commissioning and predictive maintenance. Deepen backward integration into ceramic bearing supply to offset Japanese supplier lead time volatility. Secure JIS certification capacity at accredited test facilities before METI backlog queues extend. Counter emerging Chinese suppliers by anchoring multi-site framework agreements with Samsung and SK Hynix. For New Entrants and Emerging Players: India's Gujarat and Assam greenfield sites offer geographic underpenetration with PLI scheme-backed demand and limited incumbent field service presence. Target 200mm EFEM retrofits for mature-node automotive qualification lines where capital efficiency outweighs format migration. Pursue partnership routes with domestic system integrators lacking kinematic calibration expertise rather than direct OEM competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial automation conglomerates with underperforming semiconductor divisions lacking cleanroom heritage. Long-term viability centers on mechatronics talent scarcity resolution and digital twin unbundling of hardware from service revenue. Monitor MFDS equipment validation protocol harmonization with JIS standards as inflection signal for Korean import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtual commissioning compresses site acceptance testing from weeks to days at Taiwan foundries. |
| Backward Integration into Ceramic Bearings | Captive supply of vacuum-compatible bearings insulates against Japanese supplier lead time volatility. |
| JIS Certification Capacity Expansion | Accredited test facility investment captures METI compliance backlog before queue extension. |
| Multi-Site Framework Agreements | Standardized load port specifications with Samsung reduce spare parts inventory complexity. |
| Automotive Qualification Pathways | AEC-Q100 certified configurations open captive SiC fabrication at Infineon and Bosch. |
Methodological Framework
Desk research of SEC equipment supplier filings, METI semiconductor equipment standards documentation, and foundry capital expenditure disclosures preceded structured interviews with EFEM product managers at Japanese precision robotics suppliers, procurement leads at Taiwanese foundry operators, cleanroom engineering directors at Korean memory houses, and field service heads at North American atmospheric robotics providers. Secondary validation drew from ISO 14644 cleanroom classification databases, EU F-Gas Regulation implementation reports, and India Semiconductor Mission policy circulars. Bottom-up wafer handling unit demand estimates triangulated against top-down fab capacity expansion projections.
Forecast assumptions held fixed the current JIS-MFDS certification divergence and EU F-Gas seal material restrictions while varying 300mm capacity ramp timing and automotive power semiconductor vertical integration intensity across the analysis window. Segmentation modeling captured wafer format, robotics technology tier, end-user operational model, and deployment architecture. CAGRs derived from equipment procurement lag analysis against lithography tool installation schedules, with inputs from harmonic drive supply capacity and cleanroom construction permitting velocity.
Practitioners should monitor JIS certification queue lengths, MFDS harmonization announcements, and India fab construction milestone delays for early signals of forecast revision. Quarterly review of METI policy circulars, EU F-Gas implementation guidance, and foundry equipment procurement committee minutes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Ion Milling System Market