
 Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market | 2026-2036
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market Analytics
Equipment leasing and foundry-sponsored project finance is reconfiguring how mid-tier semiconductor manufacturers access EUV scanner capacity without full capital ownership. ASML leverages its monopoly on high-NA EUV platforms to sustain pricing power across Asia-Pacific deployment schedules. ZEISS Group anchors the optical supply chain through its exclusive mirror assembly contracts, while TRUMPF competes via its dominance in CO2 laser-driven tin droplet light source systems.
Extreme Ultraviolet Lithography (EUVL) Systems deploy 13.5nm wavelength light generated by laser-produced plasma to pattern silicon wafers at sub-7nm resolution, requiring vacuum chambers and reflective optics because EUV light absorbs in air. Scanner hardware captures the dominant value pool given its multi-hundred-million dollar unit economics and decade-long depreciation cycles. Foundry end users represent the fastest-growing demand segment as Taiwan Semiconductor Manufacturing and Samsung Foundry expand 3nm and 2nm production lines. Software segments for overlay correction and process control sit at higher margins despite smaller revenue bases.
Japan's METI coordinates domestic lithography component subsidies through its semiconductor revival framework, while China's MIIT enforces GB standards and dual carbon goals that constrain imported EUV scanner deployment. South Korea's K-Battery and K-Semiconductor strategies channel tax credits toward domestic EUV infrastructure buildout. Stakeholders must monitor how export control alignments between Dutch, Japanese, and US regulators reshape equipment availability timelines across the region's foundry expansion plans.
Market Dynamics
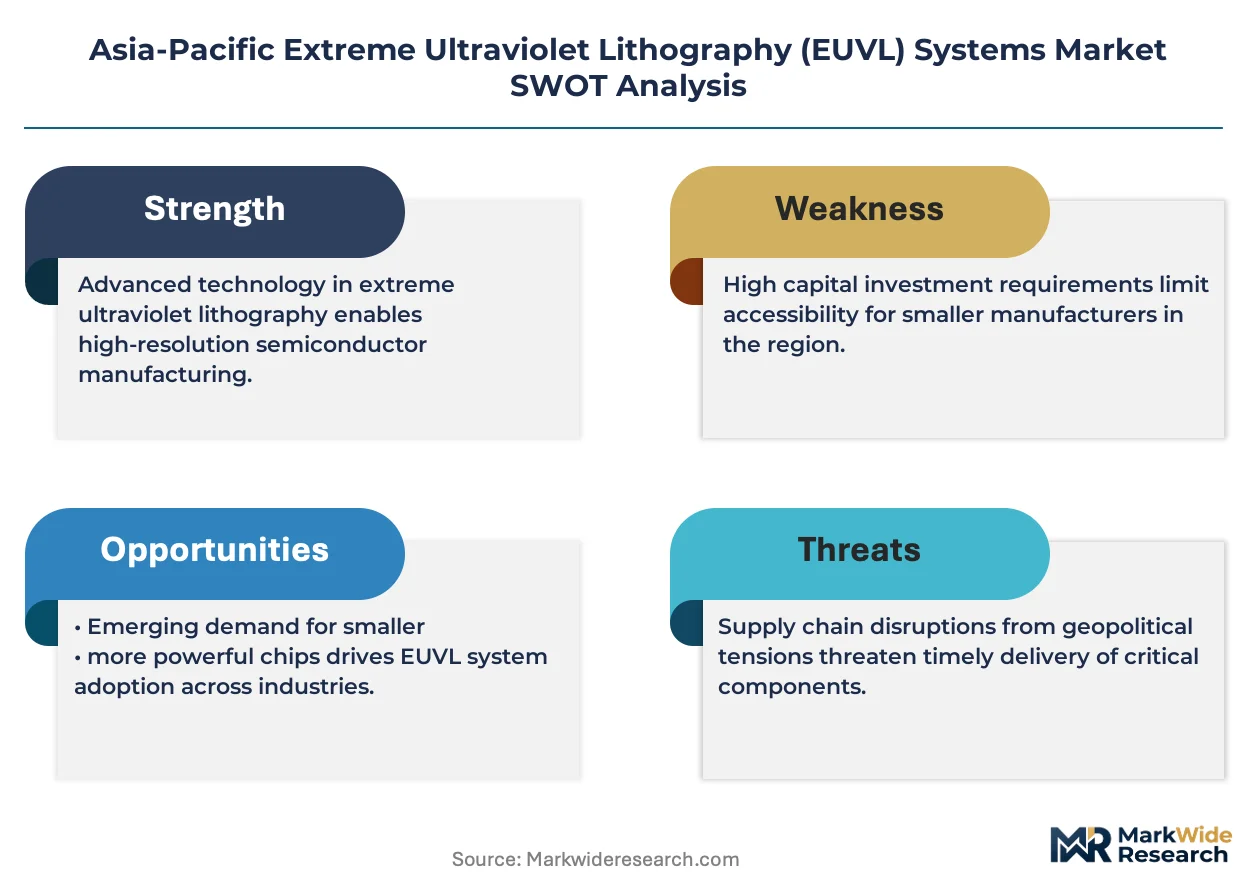
ASML's monopoly on high-NA EUV platforms concentrates supply-side power in a single Dutch vendor, forcing foundries across Taiwan, South Korea, and Japan into decade-long procurement queues and reshaping capital allocation timelines for sub-3nm production ramps.
Growth Catalysts
- Sub-7nm Node Migration:Foundries in Taiwan's Hsinchu corridor are expanding EUV scanner clusters to service AI accelerator and smartphone SoC tape-outs. This process node compression pulls additional light source and optics capacity into the region.
- South Korea's K-Semiconductor Tax Credits:Seoul's fiscal incentives for domestic EUV infrastructure buildout are accelerating Samsung Foundry's Pyeongtaek expansion timelines. Equipment depreciation allowances reduce effective capex burdens for multi-scanner deployments.
- Japan's METI Component Subsidies:Tokyo's semiconductor revival framework channels capital toward domestic mirror polishing and laser source component production. This reshoring push strengthens ZEISS and TRUMPF's regional supplier ecosystems.
Market Restraints
- Hyperconcentrated Optics Supply:ZEISS Group controls exclusive mirror assembly contracts for all high-NA systems, creating single-source fragility in the reflective optics value chain. Any production disruption at Oberkochen reverberates through Asia-Pacific deployment schedules.
- Import Licensing Friction:China's MIIT enforcement of GB standards and dual carbon goals constrains EUV scanner deployment timelines for domestic foundries. Dutch export control alignment with US and Japanese regulators further complicates equipment availability.
- Tin Droplet Source Complexity:CO2 laser-driven plasma generation requires ultra-pure tin supply and precision droplet generators. Input cost volatility for semiconductor-grade tin compounds compresses margins at the light source subsystem tier.
Strategic Opportunities
- Equipment Leasing Models:Foundry-sponsored project finance and third-party lessors are opening EUV capacity access for mid-tier semiconductor manufacturers without full capital ownership. This channel innovation expands addressable demand beyond top-tier spenders.
- Overlay Software Monetization:Process control and computational lithography software segments command premium pricing relative to hardware. Vendors can deepen recurring revenue through subscription-based correction algorithms.
- Japan's Domestic Cluster Expansion:Kumamoto and Hokkaido greenfield sites offer underutilized fab capacity for EUV-equipped logic and memory production. METI subsidies reduce site preparation costs for new market entrants.
Industry Challenges
- Vacuum Chamber Engineering Talent:The specialized skill set for EUV-compatible ultra-high vacuum system design remains concentrated in Dutch and German engineering pools. Asia-Pacific foundries face recruitment competition for this scarce technical function.
- Legacy DUV Integration Complexity:Hybrid fab architectures must synchronize 193nm immersion systems with new EUV lines for multi-patterning fallback. This equipment interoperability demands custom automation interfaces and extended qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market |
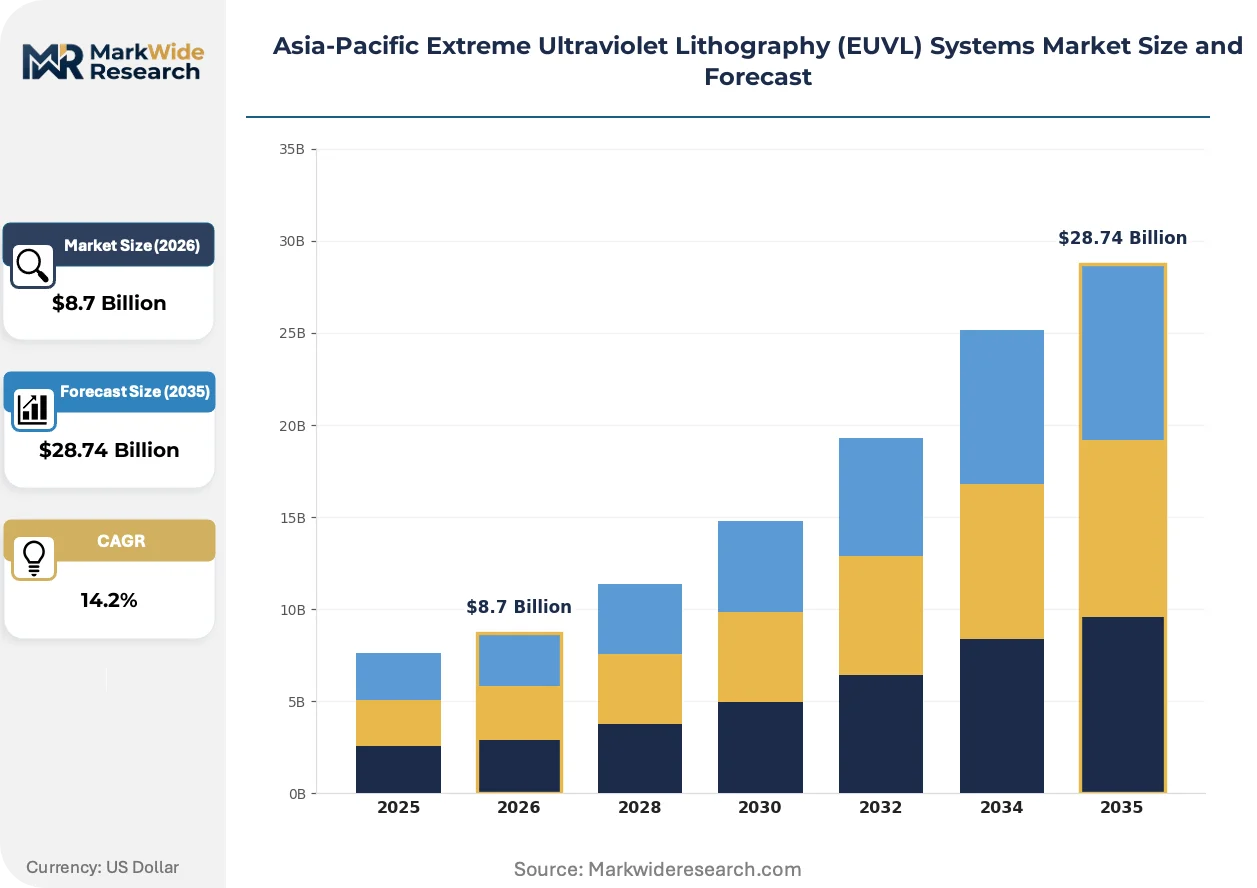
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scanner, Light Source, Mask/Etch Tool, Software End User: Semiconductor Manufacturers, Research Institutions, Foundries, Electronic Companies Technology: Optical Lithography, EUV, X-ray Lithography, Nanoimprint Lithography Application: Integrated Circuits, MEMS, Sensors, Quantum Dot Devices |
| Companies Covered | ASML, ZEISS Group, TRUMPF, Ushio Inc, AGC Inc, Lasertec Corporation, HOYA Corporation, TOPPAN Inc, KLA Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market Evolving Landscape
Scanner architecture is migrating from single-exposure solutions toward multi-patterning hybrids and high-NA successors, compressing resolution limits while amplifying optical subsystem complexity across Asia-Pacific foundry buildouts.
High-NA EUV technology is migrating from 0.33 numerical aperture platforms toward 0.55 NA systems capable of 8nm resolution in a single exposure. Samsung Foundry and TSMC are prioritizing early high-NA slots for 2nm gate-all-around transistor introductions. This capability compression is migrating from leading-edge logic toward memory applications, enabling DRAM cell scaling without quadruple patterning.
Japan's METI semiconductor revival framework is tightening domestic content requirements for lithography component subsidies, mandating local mirror polishing and metrology equipment procurement. This industrial policy is fragmenting previously globalized supply chains into regional compliance zones. South Korean foundries are responding by accelerating K-Semiconductor tax credit claims to secure EUV infrastructure before subsidy windows narrow.
Consolidated procurement consortia are displacing individual foundry negotiations for EUV scanner slots, with Taiwan's Hsinchu Science Park operators pooling volume commitments to ASML. This buyer concentration is compressing pricing leverage for mid-tier entrants and extending delivery queues for non-consortium members. The behavioral shift is most visible in South Korea, where Samsung Foundry and SK Hynix are exploring joint light source subsystem purchasing to match Taiwanese scale economics.
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market Segmentation
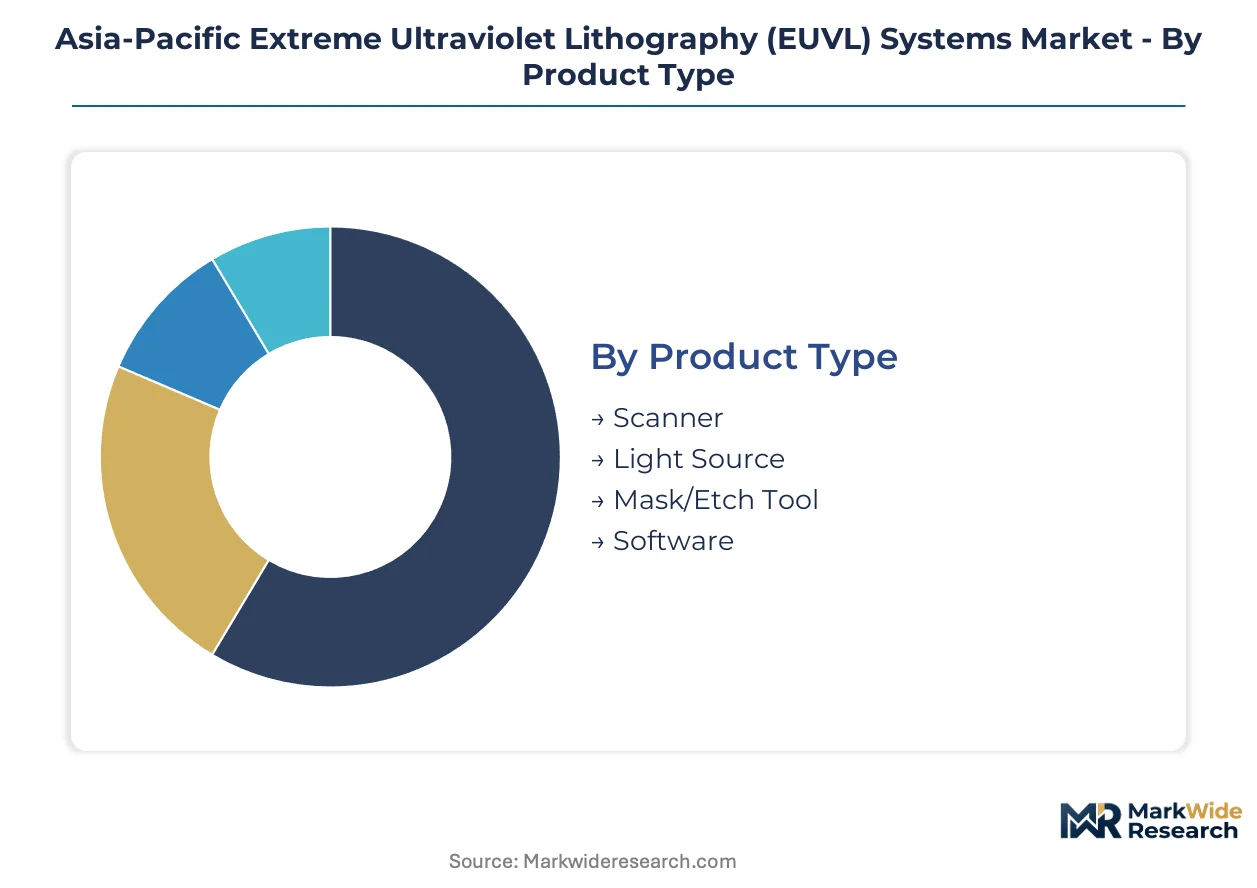
EUVL system segmentation reveals how value pools distribute across hardware tiers, customer types, and process applications. Procurement patterns in Taiwan's Hsinchu corridor and South Korea's Pyeongtaek cluster demonstrate how segment boundaries shift with foundry consolidation and node migration timelines.
Product Type:
Cost tier determines capital allocation priority across EUV subsystem procurement, with depreciation cycles and unit economics driving foundry investment sequencing.
- Scanner:Multi-hundred-million dollar vacuum-integrated platforms pattern silicon wafers at sub-7nm resolution using reflective optics. Taiwan's TSMC and Samsung Foundry in South Korea concentrate procurement for 3nm and 2nm production ramps, with delivery queues extending across decade-long depreciation schedules.
- Light Source:CO2 laser-driven tin droplet plasma generators produce 13.5nm wavelength illumination within vacuum chambers. South Korean foundries are expanding light source subsystem capacity through K-Semiconductor tax credit claims, while input cost volatility for semiconductor-grade tin compounds constrains margin expansion.
- Mask/Etch Tool:Reflective mask inspection and plasma etching equipment qualifies pattern fidelity before wafer exposure.
- Software:Computational lithography and overlay correction algorithms command recurring subscription revenue despite smaller absolute revenue bases.
Scanner holds installed capacity. Software is rotating up the share rankings.
End User:
Customer type concentration shapes equipment availability timelines, with top-tier spenders capturing priority delivery slots through volume commitments and consolidated procurement consortia.
- Foundries:Pure-play and integrated foundry operators deploy EUV clusters for external customer tape-outs at leading-edge nodes. Taiwan's Hsinchu Science Park corridor hosts the world's densest EUV concentration, while Samsung Foundry accelerates Pyeongtaek expansion through South Korean fiscal incentives.
- Semiconductor Manufacturers:IDMs operate captive EUV lines for proprietary logic and memory production. Japan's Kumamoto and Hokkaido greenfield sites offer underutilized fab capacity for new entrants leveraging METI subsidy programs.
- Research Institutions:Academic and national laboratory users access EUV capacity through equipment leasing models and shared facility arrangements.
- Electronic Companies:Systems houses with captive semiconductor divisions pursue limited EUV access for specialized component production.
Foundries dominate current procurement volume. Semiconductor manufacturers are climbing the fastest as IDMs reshore leading-edge production.
Technology:
Process maturity separates volume production platforms from developmental alternatives, with migration timelines determined by resolution requirements and patterning economics.
- EUV:13.5nm wavelength laser-produced plasma lithography enables single-exposure patterning at sub-7nm resolution. Taiwan and South Korean foundries are prioritizing high-NA platform migration for 2nm gate-all-around transistor introductions.
- Optical Lithography:193nm immersion systems persist for mature nodes and multi-patterning fallback in hybrid fab architectures.
- X-ray Lithography:Synchrotron-based proximity printing serves niche MEMS and packaging applications with lower throughput requirements.
- Nanoimprint Lithography:Mechanical pattern replication offers cost advantages for specific memory and photonics applications at relaxed overlay specifications.
EUV commands leading-edge investment. Nanoimprint lithography is gaining share fastest in specialty memory segments.
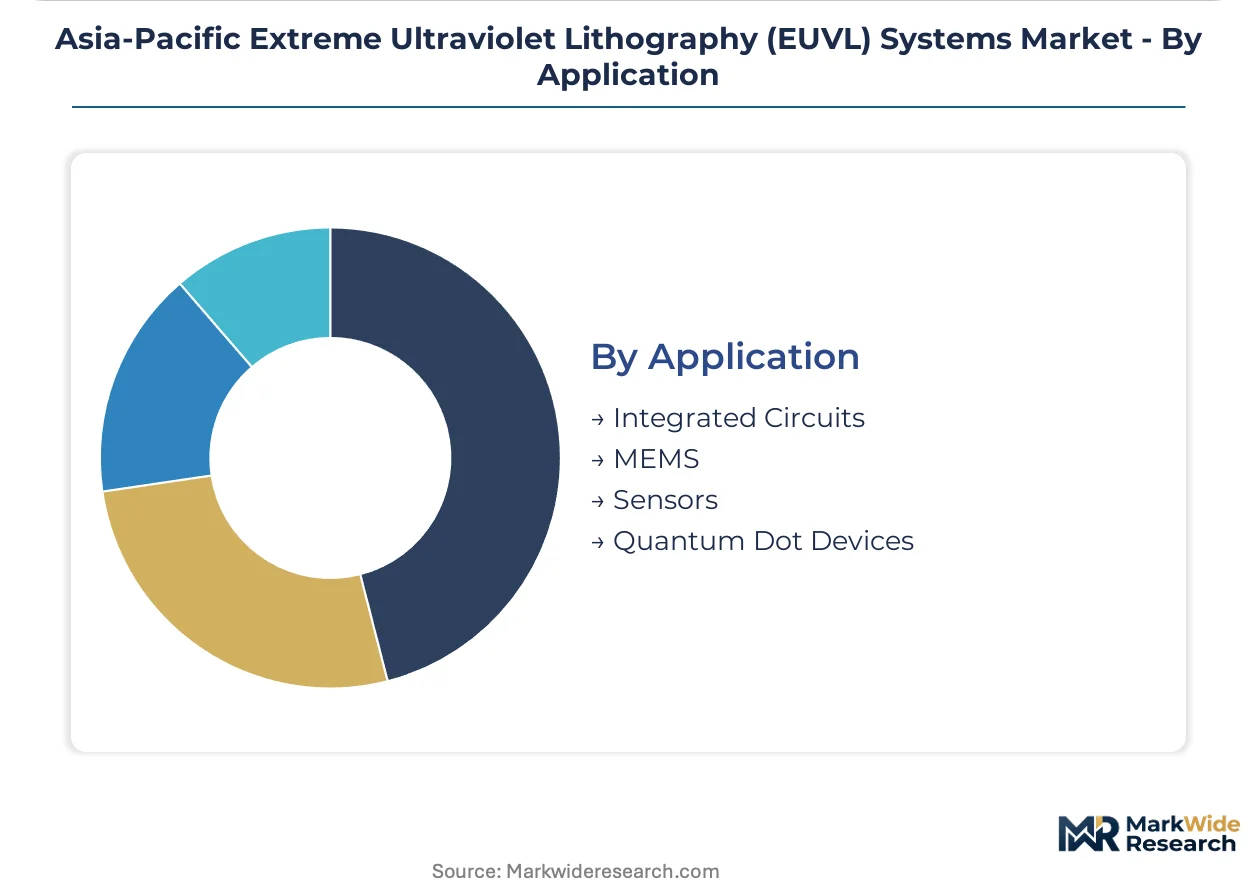
Application:
End-use volume requirements determine EUV scanner utilization rates, with high-unit-demand segments justifying dedicated cluster deployment.
- Integrated Circuits:Logic and memory IC production consumes the dominant share of EUV scanner hours. AI accelerator and smartphone SoC tape-outs in Taiwan's foundry corridor pull additional light source and optics capacity into the region.
- MEMS:Microelectromechanical systems leverage EUV for precision actuator and sensor structures at reduced pitch.
- Sensors:Image sensor and automotive sensing die benefit from EUV-enabled pixel shrink and improved signal-to-noise ratios.
- Quantum Dot Devices:Emerging display and computing applications require atomic-scale pattern control for quantum confinement structures.
Integrated circuits hold installed capacity. Quantum dot devices are rotating up the share rankings as display manufacturers pilot production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry procurement power concentrates in three national clusters where government subsidy programs and science park infrastructure determine equipment deployment velocity. Each jurisdiction channels capital through distinct regulatory mechanisms while competing for limited high-NA scanner allocation.
Taiwan
TSMC's Hsinchu Science Park corridor operates the world's densest EUV installation, with foundry-sponsored project finance enabling multi-scanner cluster expansion for 2nm gate-all-around transistor production. The National Development Council coordinates Science Park infrastructure grants that reduce site preparation costs for leading-edge fab buildouts. Taichung's Central Taiwan Science Park is absorbing secondary EUV capacity as Hsinchu reaches physical saturation.
South Korea
Samsung Foundry and SK Hynix are accelerating Pyeongtaek and Yongin fab expansions through K-Semiconductor tax credit claims that compress equipment depreciation timelines. The Ministry of Economy and Finance administers fiscal incentives requiring domestic content thresholds for light source subsystem procurement. Seoul Capital Area foundries are consolidating procurement consortia to match Taiwanese volume commitments to ASML.
Japan
METI's semiconductor revival framework channels subsidies toward domestic mirror polishing and metrology equipment production, reshoring previously offshore lithography component supply. Kumamoto and Hokkaido greenfield sites offer underutilized fab capacity for EUV-equipped logic and memory production. Tokyo's coordination of JIS standards compliance creates procurement preference zones for domestic vendors.
China
MIIT enforcement of GB standards and dual carbon goals constrains EUV scanner deployment timelines for domestic foundries seeking sub-7nm capability. The Ministry of Industry and Information Technology regulates capital equipment imports through technology transfer requirements that complicate Dutch equipment availability. Yangtze River Delta and Pearl River Delta clusters face extended qualification timelines due to export control alignment friction.
Singapore
GlobalFoundries and other foundry operators leverage Singapore's free trade zone status to stage EUV equipment for regional redistribution without immediate duty exposure. The Economic Development Board coordinates semiconductor infrastructure grants that attract multi-scanner deployments for specialty node production. Woodlands and Pasir Ris wafer fab parks are expanding vacuum-compatible cleanroom capacity to support high-NA transition.
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a supply chain where optics and light source subsystems determine equipment availability timelines. ASML holds exclusive high-NA platform supply, while ZEISS and TRUMPF anchor critical component tiers through single-source contracts. Three archetypes dominate: integrated scanner OEMs, optical subsystem specialists, and process control software vendors. Competitive moves center on capacity reservation agreements and backward integration into tin droplet source manufacturing.
Among Dutch and German equipment anchors, ASML Holding N.V. occupies the integrated platform tier, while ZEISS Group exemplifies optical subsystem concentration. TRUMPF GmbH + Co. KG represents the laser source specialist archetype. These three entities collectively determine Asia-Pacific deployment schedules through exclusive supply relationships that extend delivery queues for non-priority foundry customers.
| Leading Market Players |
|---|
| ASML |
| ZEISS Group |
| TRUMPF |
| Ushio Inc |
| AGC Inc |
| Lasertec Corporation |
| HOYA Corporation |
| TOPPAN Inc |
| KLA Corporation |
| Others |
Value Network & Pricing Analysis
Hsinchu Science Park's multi-scanner cluster density concentrates procurement leverage for Taiwan's foundry operators, compressing unit economics for mid-tier buyers while amplifying ASML's pricing power through decade-long allocation queues.
Pricing Analysis
Cost-plus contracts with semiconductor-grade tin indexation dominate light source subsystem procurement, with TRUMPF and ZEISS anchoring premium tiers through exclusive supply relationships. Price differentiation rests on volume scale and domestic content certification under Japan's METI subsidy framework. Pricing pressure stems from K-Semiconductor tax credit competition between Samsung Foundry and SK Hynix. Mid-tier semiconductor manufacturers exhibit highest price sensitivity, while TSMC's consolidated procurement consortia command least.
Supply Chain Analysis
Supplier-financing facilities from Dutch and German equipment anchors extend payment terms for foundry customers, with Oberkochen mirror polishing capacity and Aachen laser source engineering feeding regional deployment schedules. Geographic supply concentration centers on the Netherlands, Germany, and Japan for high-NA platforms, optical subsystems, and metrology equipment respectively. Raw material dependencies include semiconductor-grade tin compounds, ultra-pure silicon substrates, and specialized vacuum chamber alloys. Single-source vulnerability at ZEISS's mirror assembly tier creates systemic fragility. Distribution runs through foundry-sponsored project finance and third-party equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-high vacuum engineering talent scarcity in Asia-Pacific foundries constrains autonomous EUV infrastructure buildout, tethering deployment timelines to Dutch and German technical labor pools.
For Market Incumbents: Entrench exclusive supplier relationships through capacity reservation agreements with ZEISS and TRUMPF, locking in optical subsystem allocation ahead of high-NA platform ramps. Deepen backward integration into tin droplet source manufacturing to offset semiconductor-grade tin price volatility. Prioritize vacuum chamber engineering recruitment from Oberkochen and Aachen talent pools.
For New Entrants and Emerging Players: Establish a beachhead in Kumamoto and Hokkaido greenfield sites leveraging METI subsidy windows for domestic content compliance. Target overlay software and process control segments where recurring subscription revenue commands premium margins without capital-intensive scanner ownership. Pursue equipment leasing partnerships with Singapore's free trade zone operators for staged regional redistribution.
For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese optical component specialists with JIS standards certification and mirror polishing capabilities. Long-term viability hinges on export control alignment resilience across Dutch, Japanese, and US regulatory frameworks. Monitor MIIT enforcement of GB standards and dual carbon goals as inflection indicators for China-accessible equipment flows.
| Strategic Initiative | Industry Significance |
|---|---|
| High-NA Platform Pre-Allocation | Secures TSMC and Samsung Foundry priority slots ahead of 2nm gate-all-around ramps. |
| Domestic Mirror Polishing Investment | METI subsidies accelerate Japan's reshoring of ZEISS-dependent optical supply tiers. |
| Equipment Leasing Consortium Formation | Mid-tier foundries access EUV capacity without full capital ownership burdens. |
| Overlay Software Subscription Launch | Process control vendors capture recurring revenue from computational lithography algorithms. |
| Tin Droplet Source Backward Integration | Light source OEMs mitigate semiconductor-grade tin compound cost volatility exposure. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with EUV scanner procurement directors, vacuum chamber engineering leads, and METI subsidy program administrators; and secondary validation through ASML and ZEISS SEC filings, Japanese Ministry of Economy trade statistics, and Taiwan National Development Council infrastructure grant disclosures. Bottom-up scanner deployment tallies across Hsinchu, Pyeongtaek, and Kumamoto clusters were triangulated against top-down foundry capex projections.
Forecast inputs incorporated process node migration timelines, high-NA platform availability schedules, and subsidy program renewal windows across the analysis window. Segmentation dimensions modeled include product type tier, end-user concentration, technology maturity, and application volume requirements. CAGRs were derived from equipment depreciation cycle analysis and foundry capacity expansion announcements. Industry-specific inputs encompassed export control alignment scenarios and domestic content threshold trajectories.
Sensitivities concentrate around Dutch-Japanese-US regulatory coordination shifts and semiconductor-grade tin supply disruptions. Forecasts reflect documented assumptions regarding foundry consolidation patterns and science park infrastructure buildout schedules. Macroeconomic contraction, export control fragmentation, or high-NA platform technical delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market