
 China Extreme Ultraviolet Lithography (EUVL) Systems Market | 2026-2036
China Extreme Ultraviolet Lithography (EUVL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
China Extreme Ultraviolet Lithography (EUVL) Systems Market Insights
China's dual carbon goals are shifting capital allocation toward energy-efficient semiconductor fabrication tools. ASML sustains technology leadership through its monopoly on high-NA EUVL source development. SMEE anchors domestic substitution efforts with its immersion lithography heritage. Naura Technology competes in adjacent process equipment, extending its vacuum technology portfolio toward EUVL ecosystem readiness.
Extreme Ultraviolet Lithography (EUVL) Systems deploy 13.5nm wavelength light generated by tin droplet laser-produced plasma, enabling single-exposure patterning at sub-7nm resolution for logic and memory chips. Laser-Based Systems dominate capital expenditure due to source complexity and replacement cycles. Foundry demand within the End User category concentrates procurement power, while Optical Systems technology captures the largest margin pool from Zeiss-manufactured reflective mirrors and ASML's proprietary illumination architectures.
MIIT sets domestic equipment content targets through its integrated circuit industry guidelines, while SAMR enforces antitrust scrutiny on foreign tool suppliers. GB standards for lithography equipment safety and electromagnetic compatibility shape product certification requirements. Stakeholders must monitor Beijing's export control reciprocity measures and their impact on spare parts availability for installed base maintenance.
Market Dynamics
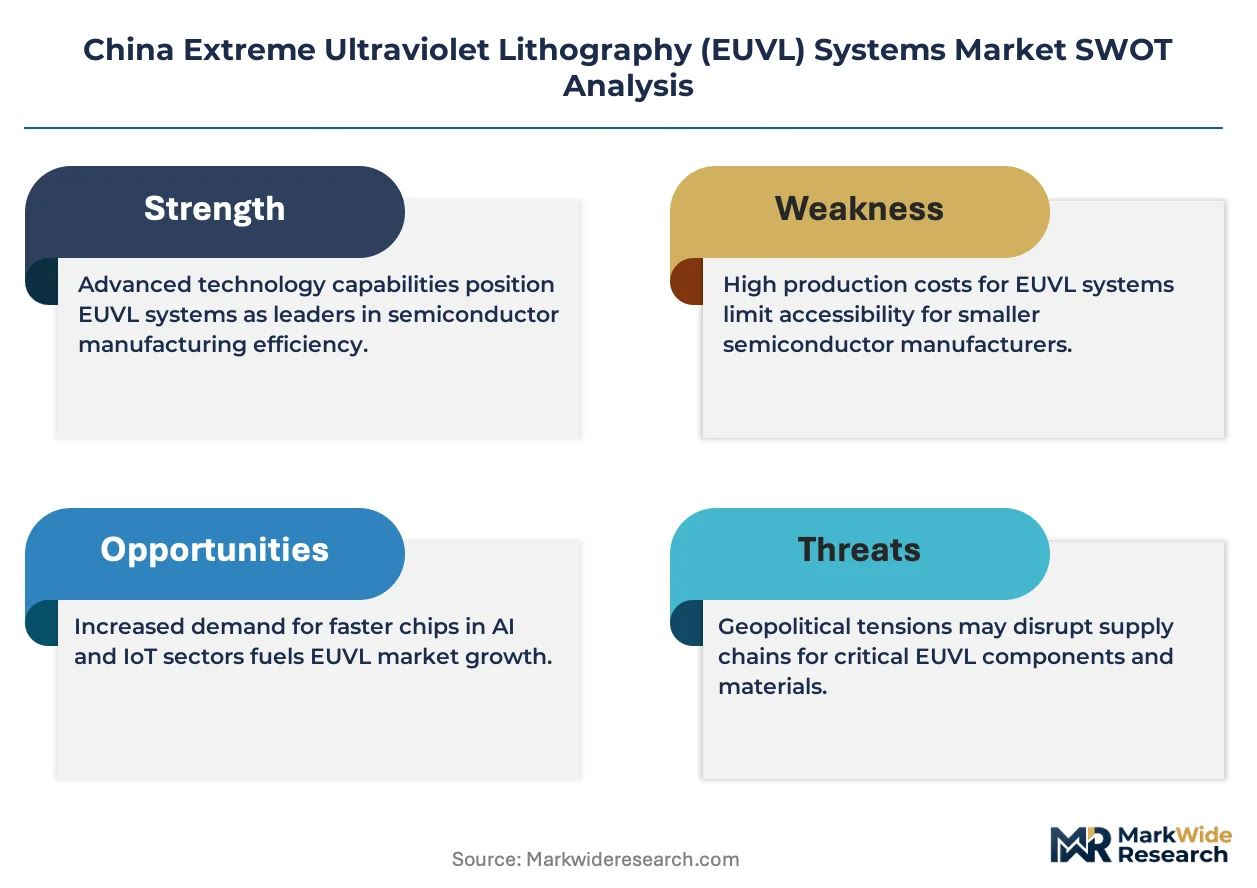
China's domestic lithography supply chain is consolidating around state-directed localization mandates, with MIIT semiconductor equipment targets redirecting capital from foreign tool dependence toward captive EUVL ecosystem development in Shanghai and Beijing clusters.
Growth Catalysts
- MIIT Localization Mandates:Domestic equipment content guidelines compel foundries to prioritize Chinese-sourced lithography components, accelerating capital flows toward SMEE and Naura Technology supply partnerships.
- Sub-7nm Node Migration:Logic and memory producers at SMIC and Hua Hong Semiconductor require EUVL for advanced patterning, creating structural demand pull for high-NA source technology.
- Zhangjiang Hi-Tech Park Concentration:Shanghai's integrated circuit cluster concentrates wafer fab investment, generating procurement scale sufficient to justify dedicated EUVL service infrastructure.
Market Restraints
- Source Component Import Dependence:Tin droplet generators and CO2 laser subsystems remain concentrated with Dutch and German suppliers, exposing maintenance schedules to export control reciprocity risk.
- Reflective Mirror Fabrication Bottleneck:Zeiss maintains exclusive production capability for EUV-grade multilayer mirrors, constraining domestic system assembly timelines regardless of source availability.
- Power Consumption Cost Structure:Laser-produced plasma sources require megawatt-scale electrical input, compressing operating margins against China's dual carbon goals for fab energy intensity.
Strategic Opportunities
- Beijing Zhongguancun Corridor Expansion:State-backed research institutes including the Institute of Microelectronics are co-locating with commercial foundries, creating captive demand for prototype EUVL systems.
- Metrology-Convergence:Integration of computational lithography with in-situ wafer inspection is enabling real-time process control, opening adjacent equipment categories for domestic suppliers.
- Spare Parts Localization Incentives:SAMR antitrust scrutiny on foreign tool vendors is creating procurement preference for Chinese-owned maintenance and refurbishment channels.
Industry Challenges
- Plasma Physics Talent Scarcity:Laser-produced plasma source engineering requires specialized expertise concentrated in European and American research programs, constraining domestic R&D velocity.
- Cleanroom Retrofit Capex Burden:Existing 193nm immersion fabs require vacuum infrastructure and vibration isolation upgrades incompatible with legacy facility designs, extending qualification timelines.
- GB Certification Parallel Tracks:Electromagnetic compatibility and safety standards for lithography equipment lack harmonization with SEMI guidelines, forcing dual compliance expenditure for export-oriented Chinese toolmakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Extreme Ultraviolet Lithography (EUVL) Systems Market |
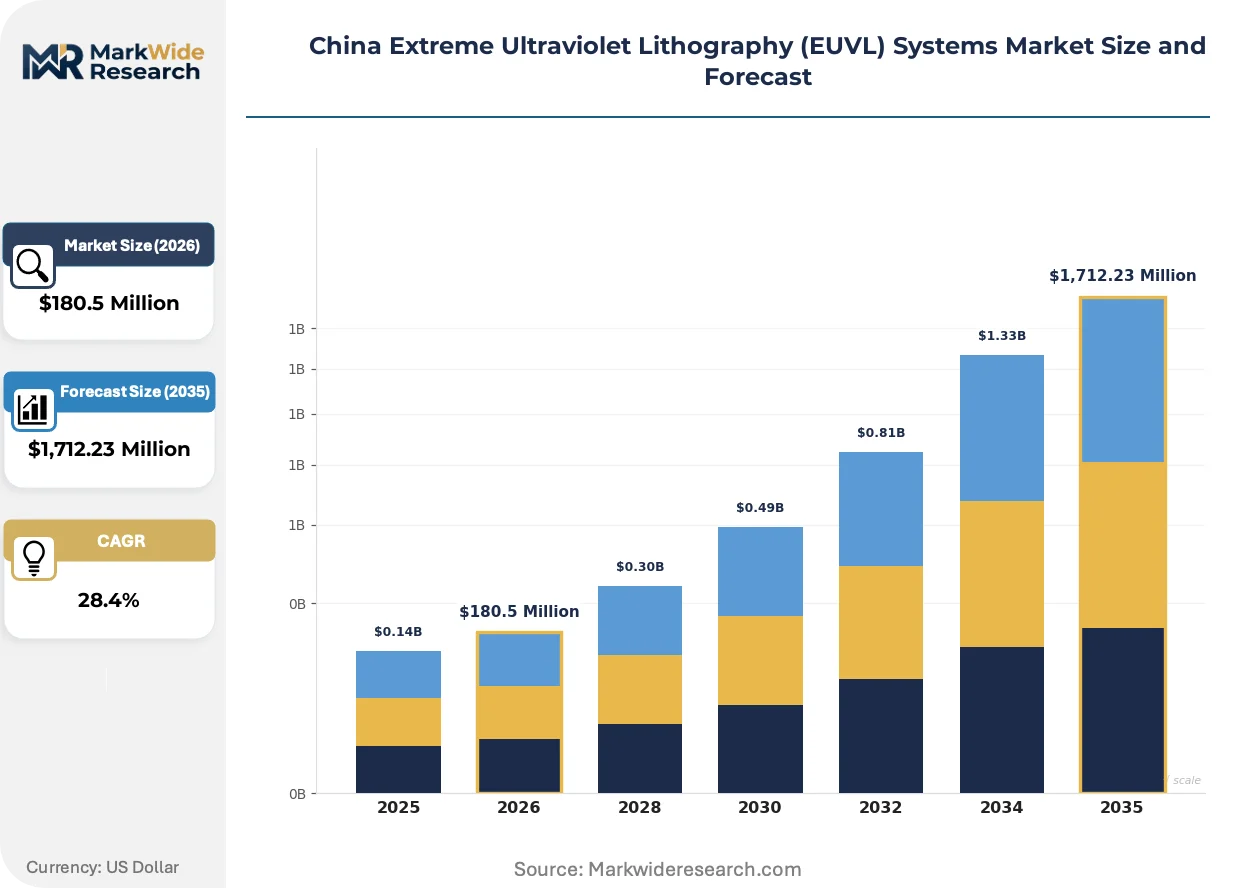
| Market Size in 2026 | $180.5 Million |
| Market Size in 2035 | $1,712.23 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser-Based Systems, Mask/Etch Solutions, Advanced Imaging Tools, Metrology Equipment Application: Semiconductor Manufacturing, Flat Panel Displays, Photovoltaics, Microelectromechanical Systems End User: Foundries, Integrated Device Manufacturers, Research Institutions, Equipment Suppliers Technology: Optical Systems, Radiation Sources, Patterning Techniques, Control Software |
| Companies Covered | ASML, SMEE, Nikon, Canon, KLA Corporation, ZEISS Group, Naura Technology, AMEC, Shanghai Institute of Optics and Fine Mechanics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Extreme Ultraviolet Lithography (EUVL) Systems Market Trends and Innovations
EUVL technology trajectories are compressing around three structural shifts: source architecture consolidation, regulatory reciprocity hardening, and procurement model rationalization among capital-constrained foundries.
High-numerical aperture optical systems are consolidating technical roadmaps across Chinese foundry planning. SMEE and domestic research consortia are prioritizing 0.55NA source development for sub-3nm resolution, displacing incremental 0.33NA upgrades. SMIC's pilot line procurement criteria now specify NA compatibility thresholds, compressing supplier differentiation toward source power stability metrics.
MIIT's integrated circuit industry guidelines are hardening equipment certification requirements for domestic content ratios. Foundry capital expenditure approvals now tie to demonstrated supply chain localization progress, forcing joint development agreements between tool vendors and component suppliers. Zhangjiang-based fabs are responding with dedicated supplier qualification teams expediting GB standard compliance for optical subsystems.
Capital deployment patterns among Chinese foundries are compressing procurement cycles toward integrated source-service bundles. Equipment purchasing teams are unbundling traditional ASML-style comprehensive maintenance contracts, instead negotiating direct spare parts agreements with Chinese distributors. This behavioral shift is most visible at Hua Hong Semiconductor, where procurement specifications now require domestic service response time guarantees as primary vendor selection criteria.
China Extreme Ultraviolet Lithography (EUVL) Systems Market Segmentation
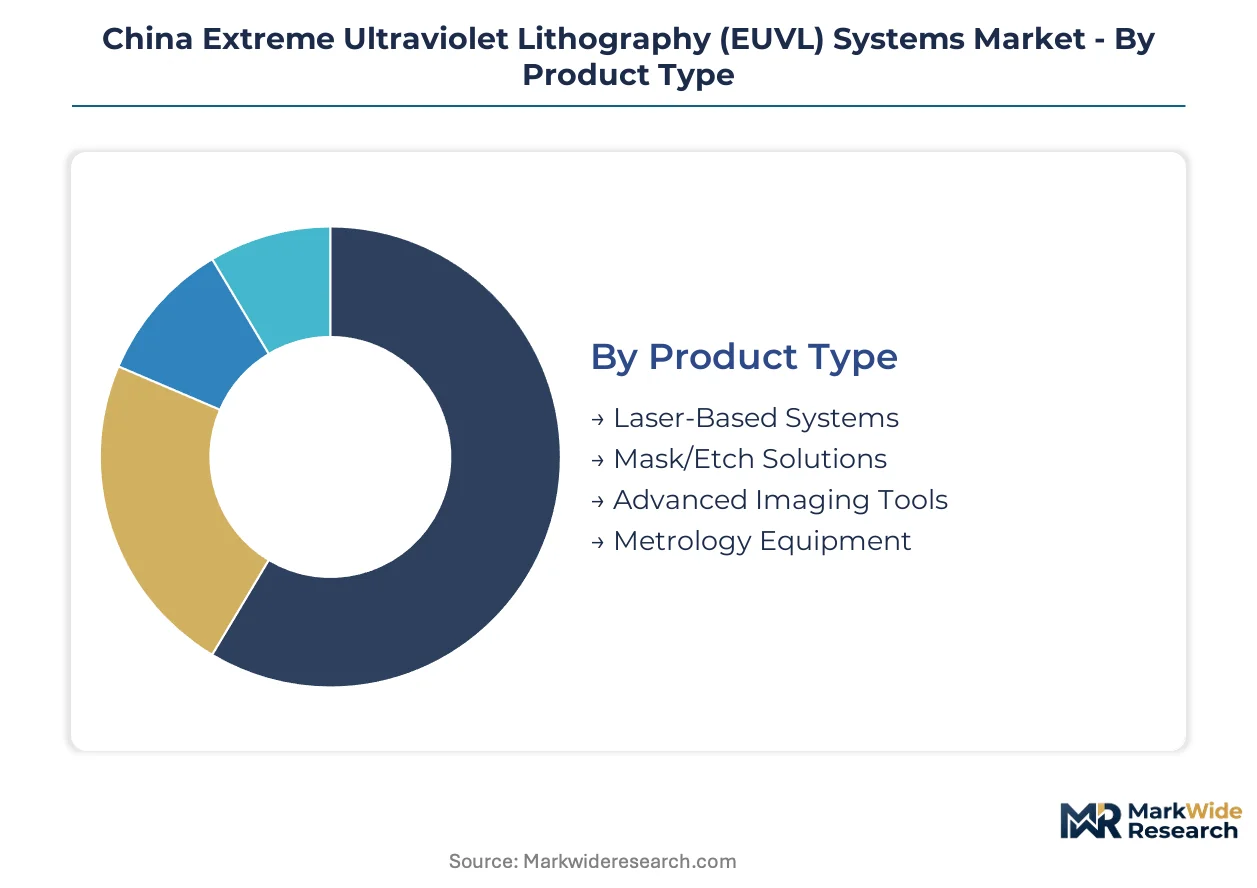
EUVL system procurement patterns in China diverge sharply across product architectures, with replacement cycles and node migration timelines dictating capital allocation priorities. Foundries segment their investments based on source technology maturity, application criticality, and domestic supply chain readiness.
Product Type:
Upgrade cycles concentrate capital expenditure where source complexity and component obsolescence intersect most acutely.
- Laser-Based Systems:These deploy CO2 laser-produced plasma architectures generating 13.5nm wavelength light through tin droplet excitation. Demand clusters at SMIC and Hua Hong Semiconductor facilities in Shanghai's Zhangjiang Hi-Tech Park, where sub-7nm node qualification drives procurement scale.
- Mask/Etch Solutions:EUV-specific reticle handling and plasma etch subsystems enable defect-free pattern transfer at sub-20nm resolution. Procurement concentrates among foundries retrofitting existing 193nm immersion lines, with Beijing's Zhongguancun corridor emerging as a secondary demand hub.
- Advanced Imaging Tools:High-NA projection systems incorporating Zeiss reflective optics support single-exposure patterning at 0.55NA.
- Metrology Equipment:In-situ wafer inspection and overlay measurement tools integrate with EUVL process control loops.
Laser-Based Systems sits at the top of the volume ranking, with Mask/Etch Solutions climbing the fastest.
Application:
Cost tier stratification separates volume applications from emerging segments still qualifying for production deployment.
- Semiconductor Manufacturing:Logic and memory chip fabrication at sub-7nm nodes consumes the dominant share of installed EUVL capacity. MIIT localization mandates redirect capital toward domestic tool qualification at Shanghai foundries.
- Flat Panel Displays:OLED and micro-LED backplane patterning at high resolution creates secondary demand for mid-NA source systems. Display fabs in Beijing and Shenzhen are piloting EUVL for pixel driver integration.
- Photovoltaics:Perovskite and advanced silicon cell metallization patterning represents an emerging application category.
- Microelectromechanical Systems:MEMS sensor fabrication leverages EUVL for high-aspect-ratio structures in automotive and consumer applications.
Semiconductor Manufacturing commands the premium pricing tier, while Flat Panel Displays is expanding most quickly.
End User:
Customer type determines procurement authority, with foundry concentration amplifying negotiating leverage against equipment vendors.
- Foundries:Pure-play contract manufacturers including SMIC and Hua Hong Semiconductor aggregate wafer start volumes sufficient to justify dedicated EUVL service infrastructure. Procurement teams unbundle maintenance contracts to prioritize domestic spare parts channels.
- Integrated Device Manufacturers:IDMs with captive fabrication maintain smaller EUVL fleets for proprietary logic and memory products. Yangtze Memory Technologies exemplifies this segment's capital deployment patterns.
- Research Institutions:State-backed institutes including the Institute of Microelectronics prototype next-generation source architectures.
- Equipment Suppliers:Domestic tool vendors qualify EUVL subsystems for integration into broader process equipment portfolios.
Foundries dominate procurement volume, with Research Institutions gaining share fastest through state-directed R&D funding.
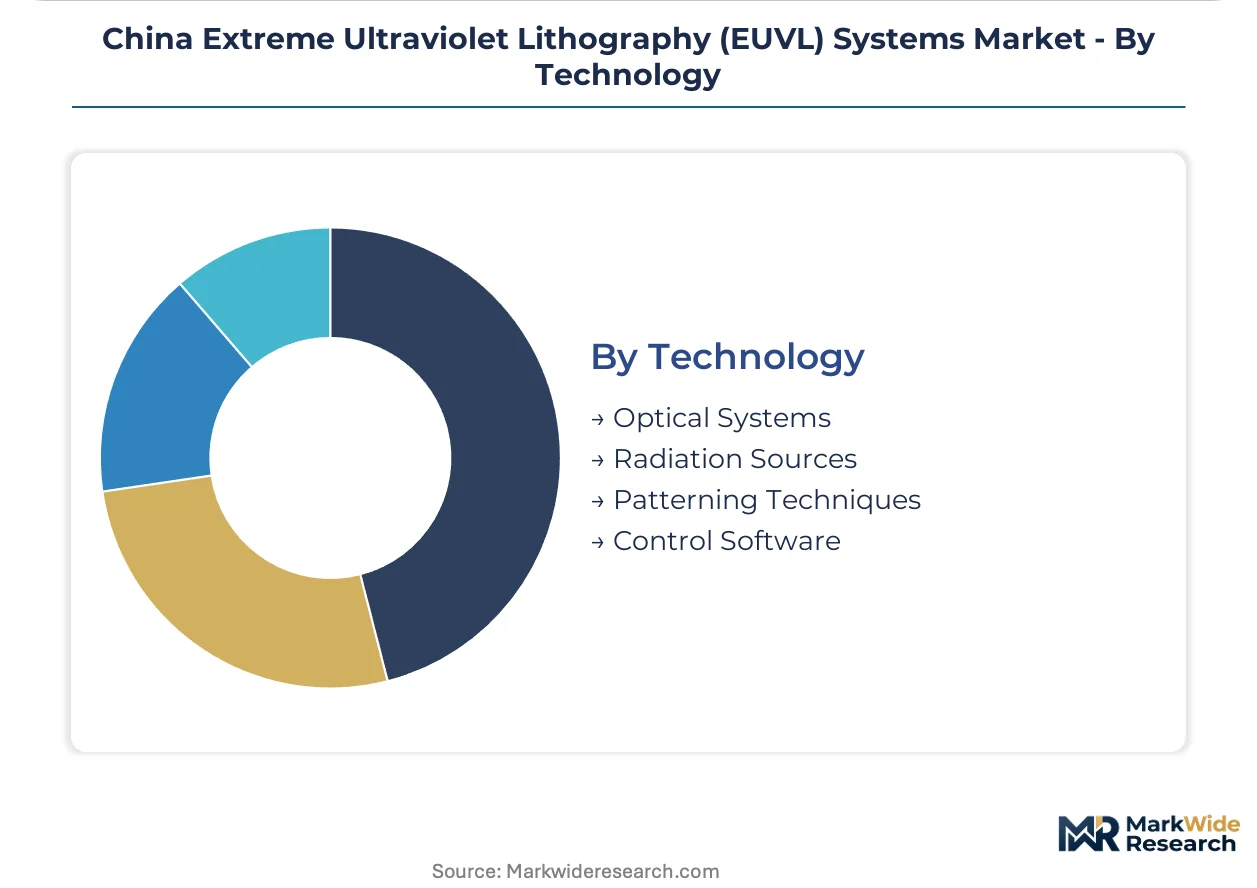
Technology:
Margin concentration follows intellectual property ownership, with optical subsystem vendors capturing value disproportionate to bill-of-materials share.
- Optical Systems:Reflective mirror assemblies and illumination modules manufactured by Zeiss represent the highest-value subsystem category. Multilayer coating deposition and figure error correction constrain domestic replication timelines.
- Radiation Sources:Laser-produced plasma generation systems incorporating tin droplet generators and CO2 lasers constitute the second-largest value pool. Source power stability metrics determine foundry qualification schedules.
- Patterning Techniques:Computational lithography and resolution enhancement technologies bridge source limitations to wafer imaging requirements.
- Control Software:Real-time process automation and machine learning-based overlay correction enable yield optimization.
Optical Systems captures the steepest margin premium, with Radiation Sources showing the sharpest volume trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma physics and optical engineering talent concentrates in Shanghai and Beijing research corridors, anchoring China's EUVL development ecosystem. State-directed funding flows toward these clusters to accelerate domestic lithography capability. Geographic specialization reflects historical semiconductor infrastructure placement and MIIT industrial policy targeting.
Shanghai
SMIC and Hua Hong Semiconductor operate sub-7nm pilot lines driving EUVL procurement volume. MIIT localization mandates compel these foundries to qualify domestic tool suppliers. Zhangjiang Hi-Tech Park concentrates wafer fab investment and dedicated EUVL service infrastructure.
Beijing
The Institute of Microelectronics and Tsinghua University co-locate with commercial foundries in Zhongguancun corridor. SAMR antitrust scrutiny on foreign tool vendors redirects procurement toward Chinese-owned maintenance channels. State-backed research institutes prototype next-generation source architectures here.
Guangdong
Shenzhen display fabs pilot EUVL for OLED and micro-LED backplane patterning. Provincial technology funds support perovskite photovoltaic cell metallization research using advanced lithography. Pearl River Delta electronics manufacturing clusters generate secondary demand for MEMS sensor fabrication tools.
Jiangsu
Yangtze Memory Technologies maintains captive EUVL fleets for proprietary 3D NAND production in Wuxi. Provincial industrial guidance funds vacuum technology suppliers extending toward EUVL ecosystem readiness. Nanjing and Suzhou host precision optics subcontractors serving domestic lithography assembly.
Sichuan
Chengdu-Chongqing semiconductor manufacturing base attracts foundry investment under western development initiatives. Local governments offer power cost subsidies addressing EUVL megawatt-scale energy consumption. Cleanroom construction accelerates to support 2025-2027 node qualification timelines.
China Extreme Ultraviolet Lithography (EUVL) Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's EUVL supply chain. The market structure consolidates around foreign technology leaders with exclusive optical capabilities, while domestic players fragment across component subsystems and service channels. Two strategic archetypes dominate: integrated system vendors controlling source-to-wafer value chains, and specialized component suppliers capturing margin from high-technical-barrier subsystems. Competitive moves center on joint development agreements with state-backed foundries and unbundled service contract negotiations.
Among Dutch and German technology groups, ASML and ZEISS Group exemplify integrated system archetypes with exclusive production capabilities. SMEE and Naura Technology occupy positions within the domestic substitution tier, representing Chinese efforts to replicate foreign lithography expertise. AMEC anchors the adjacent process equipment segment, extending vacuum technology portfolios toward EUVL ecosystem readiness without direct system competition.
| Leading Market Players |
|---|
| ASML |
| SMEE |
| Nikon |
| Canon |
| KLA Corporation |
| ZEISS Group |
| Naura Technology |
| AMEC |
| Shanghai Institute of Optics and Fine Mechanics |
| Others |
Pricing and Supply Chain Analysis
Plasma physics specialists concentrated in Shanghai's Zhangjiang Hi-Tech Park command wage premiums that compress operating margins at domestic tool vendors, widening the pricing spread between ASML's integrated source-service bundles and SMEE's component-tier offerings. Labor-cost differentials between Dutch engineering teams and Chinese domestic talent pools stratify procurement tiers, with foundries absorbing premium pricing for guaranteed uptime versus accepting extended qualification timelines from emerging suppliers.
Pricing Analysis
Integrated source-service bundles dominate capital deployment patterns across Chinese foundries, with procurement teams unbundling traditional comprehensive maintenance contracts to negotiate direct spare parts agreements. Price differentiation separates Zeiss optical subsystems from domestic mirror fabrication attempts, while volume-scale discounts concentrate at SMIC and Hua Hong Semiconductor due to wafer start aggregation. Cost compression in mid-tier radiation sources intensifies because of CO2 laser subsystem import dependence, with research institutions showing highest price sensitivity and sub-7nm logic foundries least willing to trade performance for cost reduction.
Supply Chain Analysis
GB certification requirements for electromagnetic compatibility and safety standards gate domestic supplier qualification timelines, forcing dual compliance expenditure for export-oriented Chinese toolmakers. Geographic supply concentration centers on the Netherlands for tin droplet generators, Germany for reflective mirror assemblies, and the United States for CO2 laser subsystems. Raw material dependencies include high-purity tin for plasma generation, silicon carbide for mirror substrates, and specialized optical coatings. Single-source vulnerability constrains Zeiss mirror fabrication capacity regardless of source availability. Distribution runs through state-backed foundry procurement committees with MIIT localization mandate oversight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China EUVL market compounds steadily as semiconductor localization mandates lock in structural demand for domestic lithography capability regardless of cyclical foundry utilization swings.
For Market Incumbents: Deploy joint development agreements with Zhangjiang-based foundries to secure qualification slots ahead of SMEE's 0.55NA source maturation. Anchor service response time guarantees into contract structures to defend against unbundling pressure from procurement teams at Hua Hong Semiconductor. Deepen backward integration into tin droplet generator refurbishment capabilities to offset spare parts localization incentives.
For New Entrants and Emerging Players: Computational lithography software integration with in-situ metrology offers the most penetrable white-space for domestic entrants lacking optical subsystem fabrication scale. Target Beijing's Zhongguancun corridor research institutes with prototype system leasing arrangements before commercial foundry qualification. Pursue platform partnership strategies with Naura Technology's vacuum equipment installed base to accelerate credibility building.
For Investors and Strategic Acquirers: State-backed semiconductor investment funds are the most active acquirer in this space, prioritizing control over EUVL ecosystem chokepoints ahead of export control reciprocity escalation. Mid-cap precision optics specialists with Zeiss subcontractor heritage represent the highest-probability acquisition archetype for capability gap closure. Monitor SAMR antitrust enforcement intensity against foreign tool vendors as the signal to watch for domestic procurement preference inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Development Agreement with State Foundries | Secures qualification priority for 0.55NA source prototypes at SMIC pilot lines. |
| Backward Integration into Mirror Coating | Reduces Zeiss dependency for multilayer deposition in domestic system assembly. |
| Spare Parts Localization Partnership | Captures SAMR-directed procurement preference for Chinese-owned maintenance channels. |
| Computational Lithography Platform Launch | Bridges source power limitations to wafer imaging requirements at sub-7nm nodes. |
| Research Institute Prototype Deployment | Generates reference installations at Institute of Microelectronics ahead of commercial scale. |
Research Methodology
Direct dialogue with foundry procurement directors, plasma source engineers, optical subsystem vendors, and MIIT policy researchers grounded qualitative assessment, cross-referenced against customs trade data for lithography equipment imports, SAMR antitrust filings, GB standards documentation, and semiconductor industry association equipment spending surveys. Bottom-up triangulation against top-down macroeconomic modeling validated volume estimates.
Bottom-up segmentation modeling across product type, application, end user, and technology dimensions anchored value projections over the analysis window. Analytical frameworks incorporated node migration timelines, localization mandate compliance trajectories, and foundry capital expenditure approval patterns. CAGRs derived from equipment replacement cycles, source power upgrade roadmaps, and domestic qualification velocity assumptions.
The model holds under continued MIIT semiconductor equipment content targets and stable export control reciprocity; deviation in plasma physics talent availability or reflective mirror supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Slide Processing System Market