
 Quantum Annealing Equipment Market | 2026-2036
Quantum Annealing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Annealing Equipment Market Insights
Canadian superconducting foundry capacity is recalibrating as D-Wave Quantum Inc. scales fabrication for next-generation Advantage processors. Fujitsu Limited leverages its Digital Annealer cloud service to anchor enterprise optimization contracts across Asia-Pacific manufacturing clients. NEC Corporation competes through hybrid classical-quantum integration platforms that extend its telecommunications infrastructure into quantum networking trials.
Quantum annealing equipment comprises specialized cryogenic processors that exploit quantum tunneling to escape local minima in combinatorial optimization landscapes, typically operating at temperatures below 20 millikelvin with superconducting niobium flux qubits. These systems solve quadratic unconstrained binary optimization problems for logistics, drug discovery, and financial portfolio management where classical algorithms face exponential scaling barriers. Superconducting qubits dominate current installations due to mature fabrication pipelines, while photonic qubits attract R&D investment for room-temperature operation potential. Optimization Problems generates the largest revenue share among applications, though Machine Learning represents the fastest-expanding use case as variational quantum algorithms mature for neural network training acceleration.
The US NIST quantum-resistant cryptography standards and Japan METI quantum technology innovation strategy jointly shape procurement specifications and funding eligibility for annealing hardware deployments. EU CE marking requirements under the Cybersecurity Act increasingly influence interface and data handling protocols for quantum systems sold into European research consortia. Stakeholders must monitor divergence between national quantum sovereignty initiatives and cross-border cloud access models as regulatory fragmentation threatens interoperability investments.
Market Dynamics
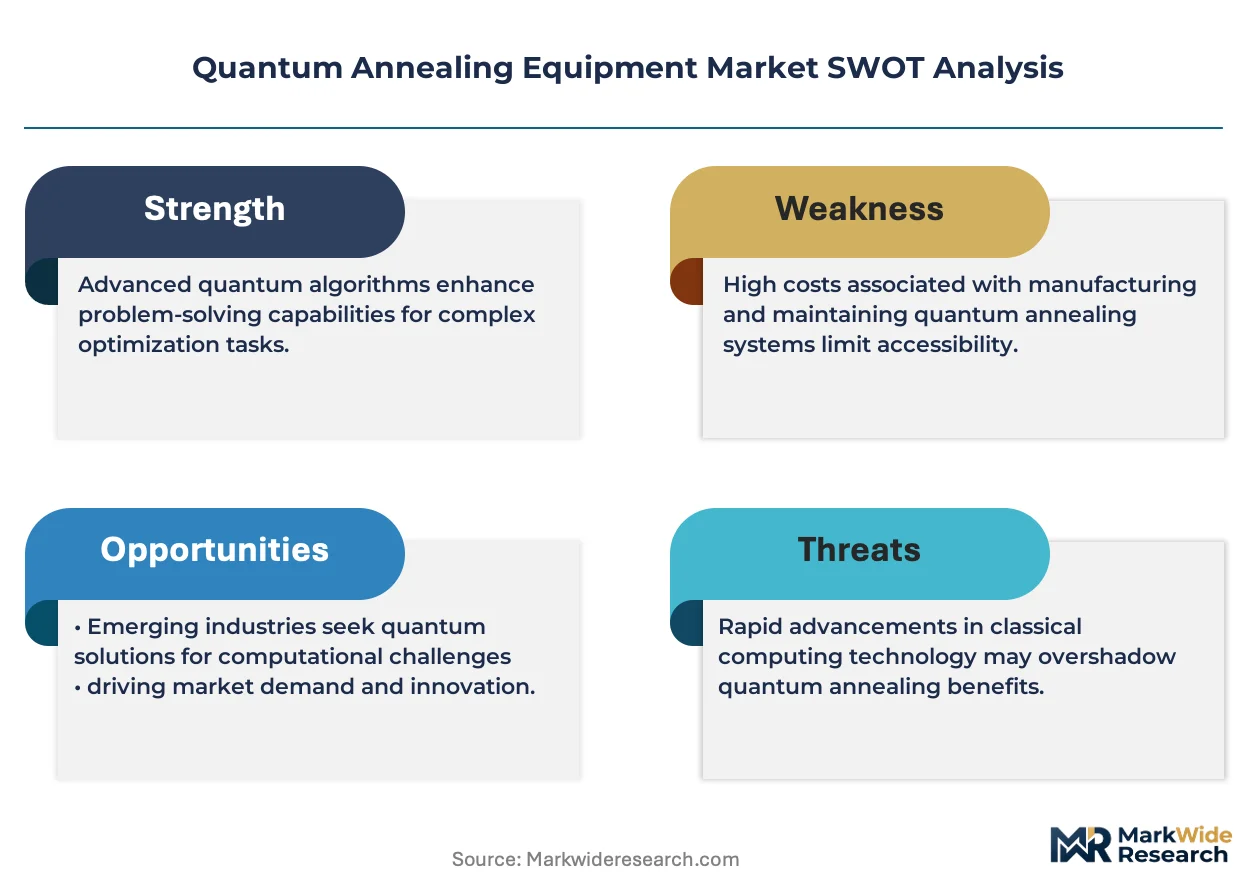
Japan METI quantum technology innovation strategy is redirecting public procurement toward annealing systems that demonstrate post-quantum cryptographic compatibility, forcing vendors to redesign control interfaces and data pipelines before hardware deployment.
Growth Catalysts
- Portfolio optimization demand:Financial institutions in North America and Europe are deploying annealing processors for real-time risk analysis, creating sustained hardware procurement cycles beyond research grants.
- NIST post-quantum cryptography standards:Federal procurement specifications now require quantum-ready infrastructure certification, expanding addressable market for annealing equipment vendors serving government and defense contractors.
- Superconducting fabrication maturity:Cryogenic processor yields have improved through niobium-based flux qubit foundries, reducing unit economics barriers for enterprise buyers previously limited to cloud access.
Market Restraints
- Helium-3 supply concentration:Dilution refrigerator cooling depends on helium-3 sourced primarily from nuclear weapons stockpile decommissioning programs in the United States and Russia, creating input cost volatility and allocation risk.
- Technical coherence limitations:Superconducting qubit annealers require operating temperatures below 20 millikelvin, constraining deployment to facilities with specialized cryogenic infrastructure or cloud-only access models.
- Classical algorithm substitution:GPU-accelerated simulated annealing and tensor network methods continue closing performance gaps on mid-scale optimization problems, delaying quantum hardware purchases for cost-sensitive buyers.
Strategic Opportunities
- Machine learning acceleration:Variational quantum algorithms for neural network training represent an emerging application segment where annealing hardware can demonstrate advantage over classical approaches in specific combinatorial subroutines.
- EU quantum flagship procurement:Horizon Europe funding streams and national quantum programs in Germany, France, and the Netherlands are creating dedicated budgets for annealing system acquisitions by research consortia.
- Photonic qubit convergence:Room-temperature photonic annealing architectures under development could eliminate cryogenic infrastructure requirements, expanding addressable market to enterprise data centers lacking specialized facilities.
Industry Challenges
- Cryogenic engineering talent scarcity:The specialized skill set combining superconducting device physics, dilution refrigerator operation, and quantum control software remains concentrated at a handful of academic institutions and national laboratories.
- CE marking compliance timelines:EU Cybersecurity Act interface requirements and electromagnetic compatibility certification for quantum systems sold into European research consortia extend sales cycles by 12-18 months.
- Legacy ERP integration complexity:Enterprise buyers require annealing systems to interface with existing supply chain optimization software through standardized APIs, forcing vendors to develop middleware layers that delay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Annealing Equipment Market |
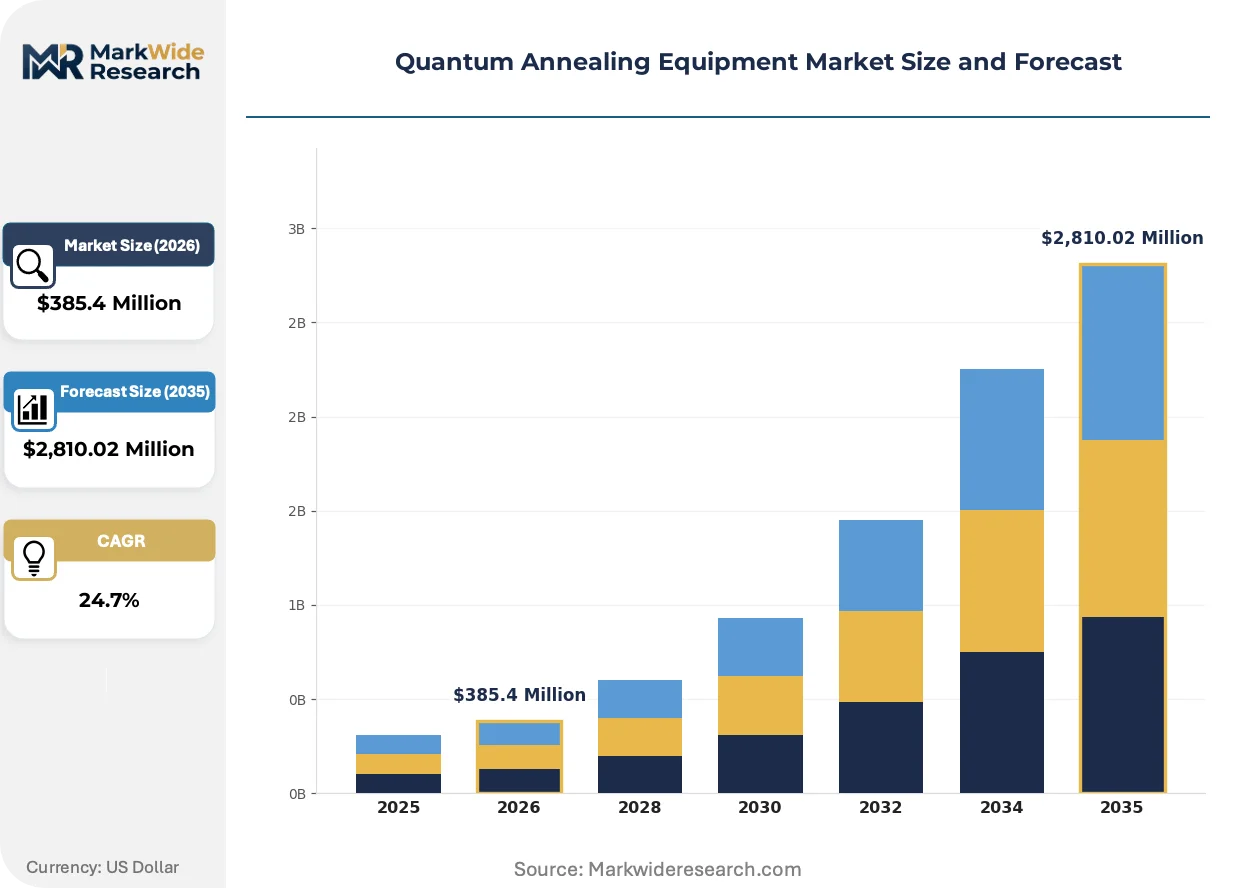
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,810.02 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superconducting Qubits, Photonic Qubits, Trapped Ions, Quantum Dots Application: Optimization Problems, Machine Learning, Material Science, Financial Modeling End User: Aerospace, Defense, Telecommunications, Pharmaceuticals Technology: Integration with Classical Systems, Hybrid Systems, Open Quantum Systems, Quantum Networking |
| Companies Covered | D-Wave Quantum Inc., Fujitsu Limited, NEC Corporation, Hitachi, Ltd., Toshiba Corporation, Rigetti Computing, 1QBit, Fixstars Amplify, NTT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Annealing Equipment Market Trends and Innovations
Hybrid classical-quantum algorithm development is compressing the pathway from hardware procurement to production deployment, as vendors and end-users co-develop problem-specific annealing schedules rather than treating systems as black-box optimizers.
Photonic qubit architectures are decentralizing the geographic distribution of quantum annealing capability. PsiQuantum and Xanadu are advancing room-temperature photonic processors that eliminate dilution refrigerator infrastructure requirements. Pharmaceutical companies and logistics operators without specialized cryogenic facilities are piloting these systems for molecular simulation and routing optimization. This technology is decentralizing deployment from national quantum centers to enterprise data centers, compressing the addressable market expansion timeline.
Japan METI quantum technology innovation strategy and US NIST post-quantum cryptography standards are jointly reshaping procurement specifications. Hardware vendors must now demonstrate cryptographic compatibility and supply chain security attestation to qualify for public funding. Systems integration contracts in Japan and federally funded research in the United States are most affected, with vendors establishing dedicated compliance engineering teams to manage divergent national certification requirements.
Enterprise buyers are consolidating quantum computing spend through cloud service subscriptions rather than capital purchases. Manufacturing clients in Asia-Pacific and financial services firms in North America are favoring usage-based access to annealing processors over on-premise installation. Japan and Germany display the most pronounced shift, with METI-funded consortia and Fraunhofer Institute partnerships structuring multi-year cloud commitments that bundle hardware access with algorithm development support.
Quantum Annealing Equipment Market Segmentation
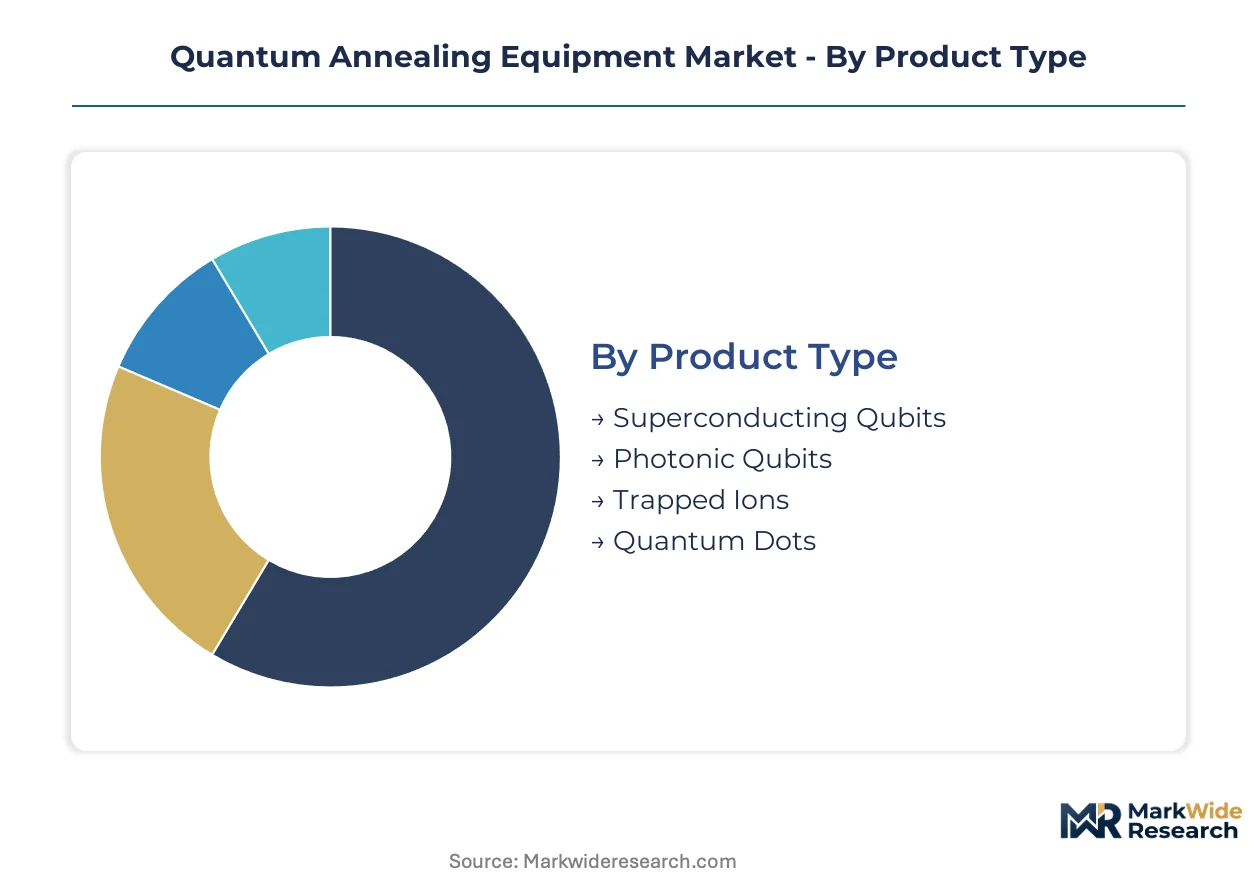
Segmentation in quantum annealing equipment reveals how technical specifications, deployment constraints, and procurement budgets fragment buyer priorities. Vendors must align cryogenic infrastructure requirements, algorithmic compatibility, and integration complexity against distinct customer capabilities.
Product Type:
Buyers differentiate primarily by cooling infrastructure investment tolerance and qubit coherence requirements.
- Superconducting Qubits:Niobium-based flux qubits operate below 20 millikelvin in dilution refrigerators, delivering mature fabrication pipelines and established error correction protocols. Financial institutions in North America and Japan deploy these systems for portfolio optimization, though helium-3 supply volatility constrains scaling.
- Photonic Qubits:Room-temperature operation eliminates cryogenic infrastructure, expanding addressable market to enterprise data centers lacking specialized facilities. PsiQuantum and Xanadu pilots in pharmaceutical and logistics sectors demonstrate feasibility for molecular simulation and routing optimization without dilution refrigerators.
- Trapped Ions:Electromagnetic confinement of charged particles enables longer coherence times than superconducting alternatives, though slower gate speeds limit annealing throughput.
- Quantum Dots:Semiconductor-based spin qubits leverage existing CMOS fabrication, attracting R&D investment for potential integration with classical electronics.
Superconducting qubits lead volumes today; photonic qubits are gaining share fastest.
Application:
Commercial maturity and algorithmic readiness separate deployment-ready use cases from experimental pilots.
- Optimization Problems:Quadratic unconstrained binary optimization for logistics routing, supply chain scheduling, and resource allocation represents the most commercially validated application. Manufacturing clients across Asia-Pacific contract Fujitsu Digital Annealer cloud services for production deployment.
- Machine Learning:Variational quantum algorithms for neural network training acceleration show theoretical promise but remain pre-commercial. Research consortia in Germany and the Netherlands fund algorithm development through Horizon Europe quantum flagship programs.
- Material Science:Molecular simulation for drug discovery and catalyst design attracts pharmaceutical investment, though quantum advantage remains unproven against classical approximations.
- Financial Modeling:Risk analysis and derivative pricing applications compete against GPU-accelerated Monte Carlo methods, delaying hardware procurement for cost-sensitive institutions.
Optimization Problems anchors current revenue; Machine Learning shows steepest expansion trajectory.
End User:
Procurement authority and security classification determine access to cloud versus on-premise deployment models.
- Aerospace:Satellite constellation optimization and flight path planning drive demand, with prime contractors requiring air-gapped systems for classified workloads.
- Defense:NIST post-quantum cryptography standards mandate quantum-ready infrastructure certification, expanding federally funded research and procurement specifications for hardware vendors.
- Telecommunications:NEC Corporation integrates hybrid classical-quantum platforms into network infrastructure trials, extending existing fiber optic assets toward quantum networking.
- Pharmaceuticals:Molecular docking and protein folding simulations attract cloud subscription models from firms lacking cryogenic facilities, particularly in Japan METI-funded consortia.
Defense commands premium pricing; Pharmaceuticals is climbing the fastest.
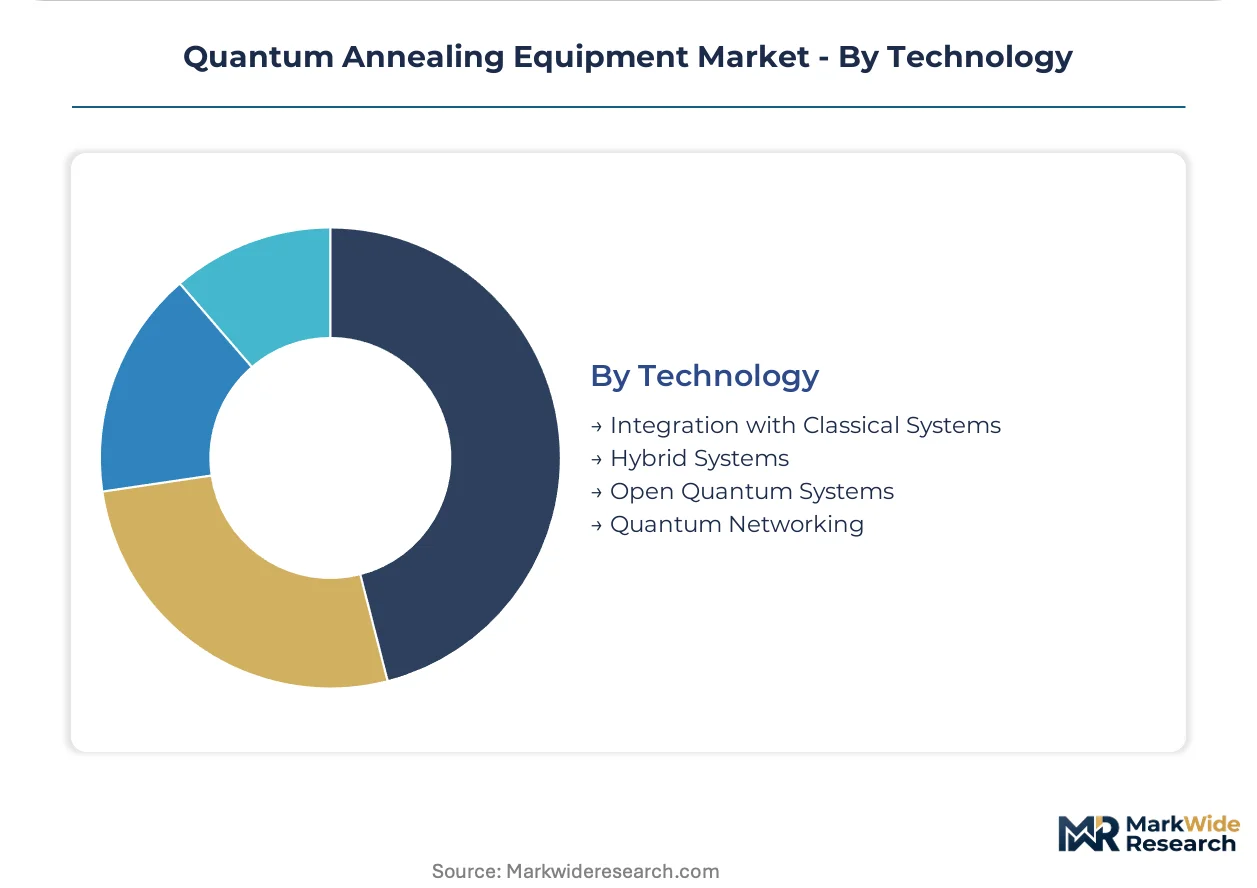
Technology:
Integration architecture choices reflect customer maturity in quantum software development and classical system legacy.
- Integration with Classical Systems:API middleware connecting annealing processors to existing ERP and supply chain software dominates enterprise procurement, though development timelines extend 12-18 months for compliance certification.
- Hybrid Systems:Algorithms partitioning problems between classical pre-processing and quantum annealing cores compress time-to-deployment, with D-Wave and Fujitsu co-developing problem-specific schedules with manufacturing clients.
- Open Quantum Systems:Research platforms enabling custom pulse sequences and annealing schedules attract academic and national laboratory users prioritizing experimental flexibility over stability.
- Quantum Networking:Entanglement distribution for distributed annealing remains pre-commercial, with NEC and Toshiba conducting metropolitan-scale trials in Japan.
Hybrid Systems leads deployment counts; Quantum Networking is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is accelerating equipment migration toward jurisdictions with subsidized cryogenic infrastructure and permissive quantum export controls. Vendors calibrate fabrication location against helium-3 allocation protocols and public procurement qualification timelines.
United States
Defense contractors and federally funded research laboratories anchor hardware demand through NIST post-quantum cryptography procurement mandates. The Department of Energy allocates dilution refrigerator capacity through national laboratory networks. Greater Boston and the San Francisco Bay Area concentrate superconducting foundry development, with D-Wave Quantum Inc. scaling niobium flux qubit fabrication in British Columbia-adjacent supply chains.
Japan
METI quantum technology innovation strategy redirects public funding toward annealing systems with cryptographic compatibility certification. Domestic manufacturers secure preferential helium-3 allocation through trade ministry coordination. Tokyo and Osaka metropolitan areas host hybrid classical-quantum integration trials, with NEC Corporation extending telecommunications infrastructure into quantum networking pilots.
Germany
Horizon Europe quantum flagship streams and Fraunhofer Institute partnerships structure multi-year cloud commitments bundling hardware access with algorithm development. CE marking requirements under the EU Cybersecurity Act extend sales cycles for annealing systems sold into research consortia. Munich and Stuttgart industrial clusters pilot supply chain optimization through cloud-accessible annealing processors.
Canada
Superconducting foundry capacity recalibrates as fabrication scales for next-generation processors. Federal quantum strategy funding supports cryogenic engineering workforce development at University of Waterloo and McGill University. Greater Toronto and Vancouver technology corridors anchor North American supply chain positioning for niobium-based flux qubit manufacturing.
United Kingdom
National Quantum Programme procurement specifications favor hybrid classical-quantum platforms with standardized API middleware for ERP integration. UK Research and Innovation funding streams require vendor compliance with electromagnetic compatibility certification timelines. London financial services firms and Cambridge research clusters drive cloud subscription models for portfolio optimization workloads.
Quantum Annealing Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue room-temperature photonic architectures that eliminate cryogenic infrastructure requirements. The market structure concentrates around superconducting qubit specialists with mature fabrication pipelines and cloud service providers with algorithm development bundling. Three archetypes dominate: cryogenic hardware fabricators, hybrid integration platform vendors, and cloud-native optimization service operators. Competitive moves center on strategic partnerships for ERP middleware development and geographic expansion through national quantum program qualification.
Within the cryogenic hardware tier, D-Wave Quantum Inc. and Fujitsu Limited exemplify divergent scale strategies, with the former anchoring superconducting foundry capacity and the latter leveraging cloud service subscriptions across Asia-Pacific manufacturing clients. NEC Corporation occupies a hybrid integration position, extending existing telecommunications infrastructure toward quantum networking trials. These three entities represent the dominant competitive archetypes: fabrication-scale specialists, cloud-platform bundlers, and infrastructure-extending incumbents.
| Leading Market Players |
|---|
| D-Wave Quantum Inc. |
| Fujitsu Limited |
| NEC Corporation |
| Hitachi, Ltd. |
| Toshiba Corporation |
| Rigetti Computing |
| 1QBit |
| Fixstars Amplify |
| NTT |
| Others |
Pricing and Supply Chain Analysis
Cryogenic engineering talent scarcity in Greater Boston and the San Francisco Bay Area compresses labor-cost differentials into pricing-tier spreads, with superconducting foundry specialists commanding premiums that separate cloud-access subscription models from on-premise hardware deployments.
Pricing Analysis
Distributor margins on dilution refrigerator systems absorb helium-3 supply volatility, compressing channel economics for mid-tier vendors. Three-tier pricing structure across premium, standard, and economy levels separates NIST-certified quantum-ready infrastructure from research-grade platforms without cryptographic compatibility. Pricing pressure stems from GPU-accelerated simulated annealing alternatives closing performance gaps on mid-scale optimization problems. Aerospace and defense contractors show least price sensitivity due to air-gapped security requirements, while pharmaceutical firms lacking cryogenic facilities drive demand for cloud subscription models with compressed per-access economics.
Supply Chain Analysis
CE marking qualification under the EU Cybersecurity Act gates European market access, extending procurement timelines for vendors without established compliance engineering teams. Niobium flux qubit fabrication concentrates in Canada, Japan, and the United States, with helium-3 sourcing anchored in nuclear weapons stockpile decommissioning programs in the United States and Russia. Raw material dependencies encompass superconducting-grade niobium, specialized printed circuit boards, and dilution refrigerator components. Single-source vulnerability in helium-3 allocation creates input cost volatility. Distribution runs through national laboratory networks and cloud service providers bundling hardware access with algorithm development support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through photonic qubit architectures eliminating cryogenic infrastructure, enabling premium pricing for room-temperature deployment against incumbent superconducting systems.
For Market Incumbents: Extend cloud service subscription bundling to compress customer acquisition costs and lock in manufacturing clients across Asia-Pacific before photonic alternatives mature. Secure backward integration into niobium foundry capacity to defend against helium-3 supply shocks. Invest in NIST post-quantum cryptography certification teams to maintain eligibility for federally funded procurement. For New Entrants and Emerging Players: Cloud service providers represent the critical channel partner for bypassing capital-intensive cryogenic infrastructure requirements. Target pharmaceutical firms and logistics operators without specialized facilities through room-temperature photonic pilot programs. Penetrate EU research consortia via Horizon Europe quantum flagship funding streams with middleware-integrated hybrid platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among photonic qubit architecture developers with demonstrated molecular simulation traction. Long-term viability hinges on achieving quantum advantage in specific combinatorial subroutines against classical GPU acceleration. Watch for METI-funded Japanese consortium cloud commitment renewals as inflection indicator for enterprise subscription model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Qubit Platform Development | Room-temperature operation eliminates dilution refrigerator infrastructure, expanding addressable market to enterprise data centers. |
| NIST Certification Investment | Post-quantum cryptographic compatibility qualifies vendors for Department of Energy and defense contractor procurement streams. |
| Hybrid Algorithm Co-Development | Problem-specific annealing schedules with manufacturing clients compress time-to-deployment versus black-box optimizer positioning. |
| Helium-3 Supply Diversification | Alternative cooling architectures reduce dependency on nuclear weapons stockpile decommissioning programs in the United States and Russia. |
| API Middleware Standardization | ERP integration layers accelerate enterprise adoption by bridging legacy supply chain optimization software with quantum processors. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with cryogenic engineering directors, quantum software platform architects, national laboratory procurement officers, and enterprise IT executives at financial institutions and pharmaceutical firms. Secondary validation draws from SEC filings of publicly traded quantum computing vendors, METI quantum technology innovation strategy documentation, NIST post-quantum cryptography standard publications, and Horizon Europe quantum flagship program disclosures. Bottom-up equipment shipment tracking and top-down public funding allocation analysis provide triangulation.
Granularity-level modeling extends to superconducting versus photonic qubit architectures, cloud versus on-premise deployment modes, and defense versus pharmaceutical end-user segments across the projection horizon. CAGRs derive from equipment unit economics, helium-3 supply curve projections, and substitution elasticity estimates against GPU-accelerated classical alternatives. Industry-specific inputs encompass dilution refrigerator capacity utilization rates and METI consortium cloud subscription renewal patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to photonic qubit coherence breakthroughs and helium-3 supply disruption scenarios. Forecasts reflect assumptions on classical algorithm advancement rates and national quantum sovereignty initiative divergence. A model refresh is warranted upon material change in NIST certification timeline or EU Cybersecurity Act interface requirement finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
DUV Lithography Systems Market