
 Laser Micro Perforation Equipment Market | 2026-2036
Laser Micro Perforation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Micro Perforation Equipment Market Outlook
REACH compliance is broadening the cost-of-entry calculus for European suppliers of laser micro perforation systems. Coherent leverages its vertically integrated laser source manufacturing to sustain pricing power across fiber and CO2 platforms. TRUMPF GmbH + Co. KG anchors its position through deep R&D investment in ultrafast beam delivery systems. Han's Laser Technology Industry Group Co., Ltd. competes aggressively on manufacturing scale, extending its reach into emerging Asian packaging hubs.
Laser micro perforation equipment employs focused coherent light to create sub-millimeter apertures in films, foils, and textiles with tolerances below 50 micrometers, enabling controlled gas exchange in modified atmosphere packaging. The primary commercial purpose centers on extending perishable goods shelf life while eliminating mechanical tooling wear. CO2 laser systems dominate flexible packaging applications due to their wavelength absorption efficiency with polymer substrates, while fiber lasers capture electronics and automotive segments where metallic material processing demands higher beam quality. Automatic technology configurations command premium positioning as manufacturers prioritize throughput consistency over manual adjustment flexibility.
The EPA regulates volatile organic compound emissions from polymer processing, pushing converters toward laser alternatives that eliminate chemical etching steps. FDA food-contact material standards shape perforation equipment specifications for breathable lidding films in North American dairy and produce supply chains. ISO 9001 and CE marking requirements filter out smaller equipment builders, consolidating procurement decisions around established platform providers. Stakeholders must monitor evolving extended producer responsibility frameworks, as packaging recyclability mandates will determine which laser wavelengths and process parameters gain regulatory preference in next-generation material specifications.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing deployment timelines as converters retrofit lines to meet 2030 recyclability targets, forcing equipment decisions before full process validation cycles complete.
Growth Catalysts
- Modified atmosphere packaging expansion:Fresh produce distributors in Germany are mandating laser-perforated breathable films to reduce spoilage rates in extended supply chains.
- REACH substance restrictions:Chemical etching alternatives face phase-out pressures across European polymer processing, redirecting capex toward dry laser systems.
- Ultrafast beam delivery maturation:Picosecond pulse architectures now achieve clean polymer ablation without thermal damage zones, opening medical device packaging applications.
Market Restraints
- High-purity optical component costs:German-engineered galvo scanners and ZnSe focusing lenses face 12-18 month lead times, constraining OEM output scaling.
- Substrate material heterogeneity:Multi-layer barrier films with metallized layers create unpredictable absorption profiles, forcing extensive process development per SKU.
- CE marking complexity:Machinery Directive compliance documentation requirements extend sales cycles by 4-7 months for non-European suppliers.
Strategic Opportunities
- Indian flexible packaging buildout:FSSAI shelf-life labeling mandates are driving investment in breathable film capacity among Mumbai and Ahmedabad converters.
- Battery separator film perforation:Lithium-ion cell manufacturers require controlled porosity membranes for electrolyte wetting, creating crossover demand from electronics OEMs.
- EU Green Deal procurement incentives:Member state packaging tax relief programs favor equipment qualifying for reduced carbon footprint certifications.
Industry Challenges
- Multi-physics simulation expertise scarcity:Thermal-fluid modeling of laser-polymer interaction requires rare combinations of optical physics and materials science training.
- Legacy mechanical perforation asset stranding:Converters with recent pin-roller investments face write-down pressure before depreciation cycles complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Micro Perforation Equipment Market |
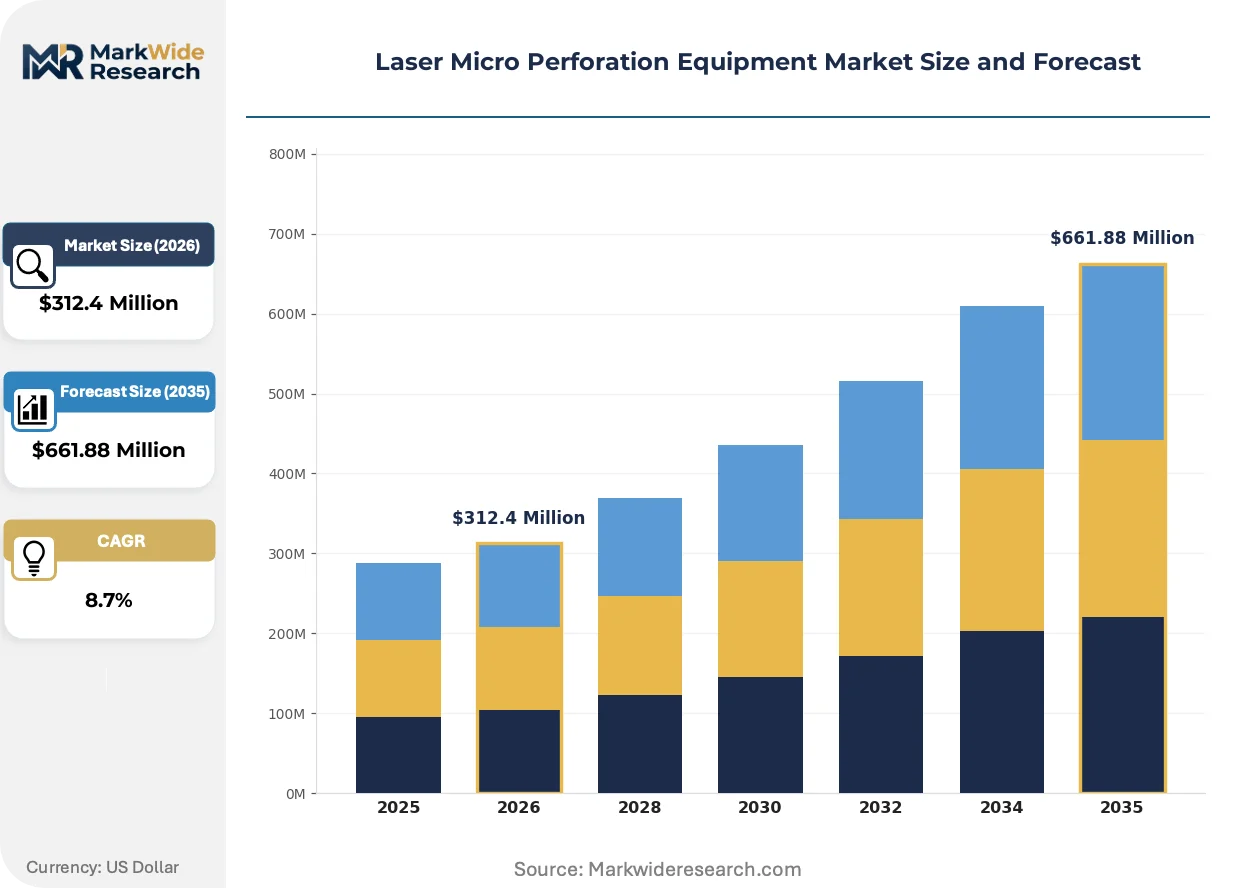
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Lasers, Fiber Lasers, Nd:YAG Lasers, Solid-State Lasers Application: Packaging, Textile, Electronics, Automotive End User: Manufacturers, Retailers, Distributors, Service Providers Technology: Computer Numerical Control, Manual, Automatic, Hybrid |
| Companies Covered | Coherent, TRUMPF GmbH + Co. KG, MLT Micro Laser Technology, Comexi Group, El.En Group, AZCO Corp, Han's Laser Technology Industry Group Co., Ltd., Preco Inc, Synrad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Micro Perforation Equipment Market Strategic Shifts
Beam source integration with real-time machine vision is collapsing the gap between process control and quality assurance, eliminating offline inspection stations from production lines.
Femtosecond fiber laser architectures are unifying cutting and perforation operations into single-pass configurations. Tier-one automotive suppliers in Stuttgart and Wolfsburg are piloting these systems for interior trim components. The convergence is compressing equipment footprints by 40% while eliminating mechanical tooling changeover downtime.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening volatile organic compound thresholds for solvent-based adhesive curing in lamination processes. Wisconsin and California converters face the steepest compliance gradients. The regulatory pressure is accelerating laser-based dry process adoption ahead of mechanical system replacement cycles.
Equipment-as-service contracting is displacing outright purchase models among mid-cap European packaging groups. Monthly fees covering maintenance, beam source replacement, and software updates reduce balance sheet strain. The model is most established in the Benelux region, where private equity-owned roll-up strategies favor operational expenditure structures.
Laser Micro Perforation Equipment Market Segmentation
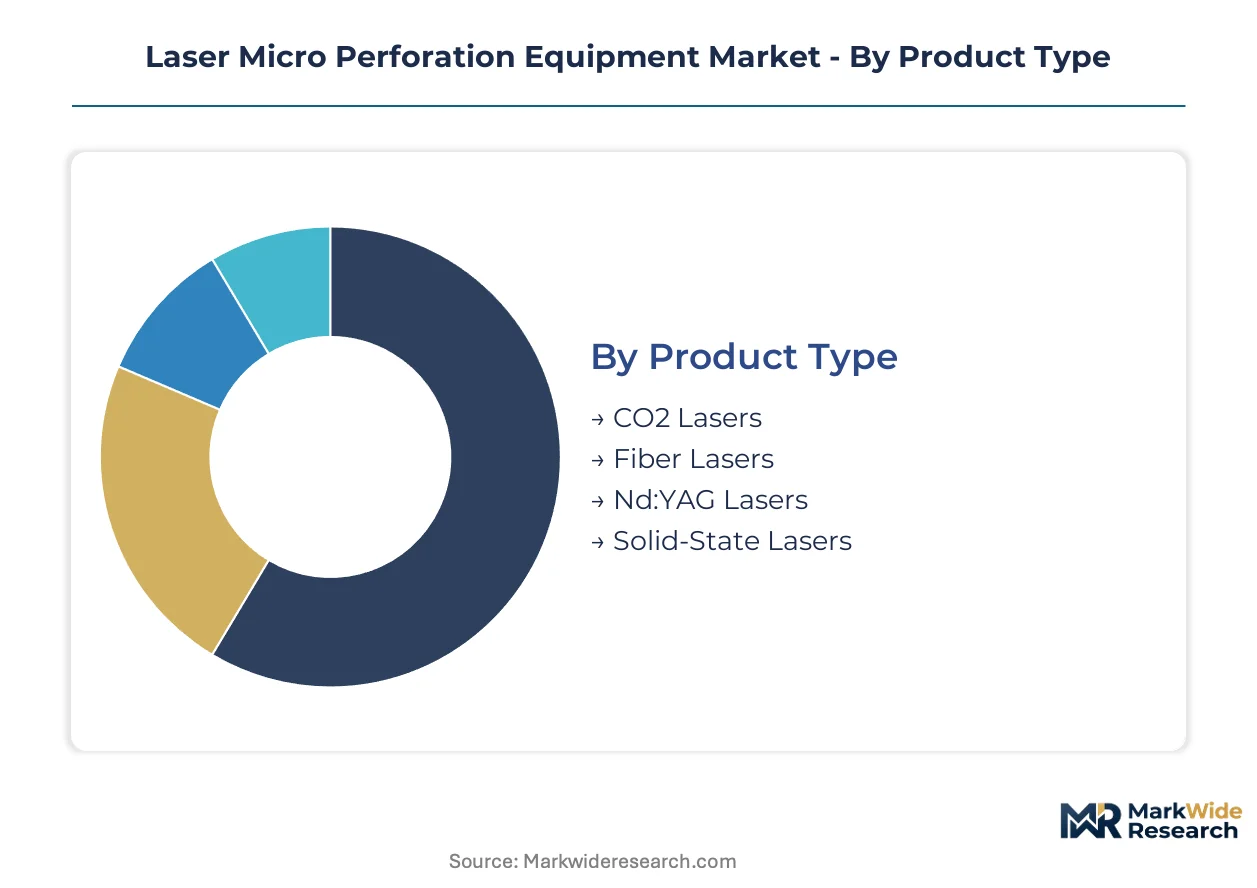
Laser micro perforation equipment procurement follows distinct upgrade cycles across product categories, with wavelength selection and automation level driving replacement timelines. Equipment buyers prioritize compatibility with existing production line footprints while evaluating next-generation beam delivery architectures.
Product Type:
Replacement cycles diverge sharply by laser source maturity, with CO2 platforms facing earlier obsolescence pressure from fiber alternatives in precision applications.
- CO2 Lasers:These gas-discharge systems emit at 10.6 micrometers, delivering optimal absorption efficiency for polymer substrates common in flexible packaging. German fresh produce distributors specify CO2-based equipment for breathable lidding films to meet extended supply chain spoilage reduction targets. Volume placements concentrate in CO2 Lasers; the faster expansion belongs to Fiber Lasers.
- Fiber Lasers:Ytterbium-doped fiber architectures generate beams with superior mode quality and wall-plug efficiency, enabling sub-50-micrometer tolerances in electronics and medical device packaging. Stuttgart automotive suppliers pilot picosecond fiber systems for interior trim perforation to eliminate mechanical tooling changeover.
- Nd:YAG Lasers:Solid-state crystal sources at 1064 nanometers serve niche metallic perforation requirements in battery separator films where thermal management demands precise pulse control.
- Solid-State Lasers:Diode-pumped alternatives offer compact footprints for space-constrained converter facilities in Mumbai and Ahmedabad flexible packaging clusters.
Cost tiers separate mature CO2 investments from premium fiber deployments, with mid-market buyers delaying upgrades pending process validation completion.
Application:
Application mix reflects end-use margin structures, with packaging commanding volume leadership and electronics capturing value concentration.
- Packaging:Modified atmosphere packaging for perishables dominates equipment deployment, with FSSAI shelf-life labeling mandates in India redirecting capex toward laser-perforated breathable films. Mumbai converters expand capacity to serve domestic dairy and produce supply chains.
- Electronics:Lithium-ion battery separator perforation requires controlled porosity membranes for electrolyte wetting, creating crossover demand from cell manufacturers seeking dry process alternatives to chemical etching.
- Textile:Technical fabric breathability specifications drive laser perforation adoption in sportswear and medical textile segments where mechanical punching damages fiber integrity.
- Automotive:Interior trim components in Stuttgart and Wolfsburg production lines integrate femtosecond laser perforation for aesthetic and acoustic management functions.
Packaging absorbs the heaviest equipment placement volume; electronics applications are climbing the fastest as battery manufacturing scales.
End User:
Customer type determines procurement modality, with manufacturers favoring ownership models and service providers gravitating toward equipment-as-service structures.
- Manufacturers:Integrated packaging producers in Benelux private equity roll-ups prefer operational expenditure structures covering maintenance and beam source replacement.
- Retailers:Private-label food chains specify laser-perforated film requirements upstream, indirectly shaping converter equipment specifications without direct capital deployment.
- Distributors:Regional film suppliers aggregate demand across smaller converter bases, consolidating equipment procurement negotiations.
- Service Providers:Toll perforation operators in Wisconsin and California deploy laser systems to capture EPA-driven substitution away from solvent-based processes.
Manufacturers account for dominant placement share; service providers are gaining share fastest through outsourced perforation contracting.
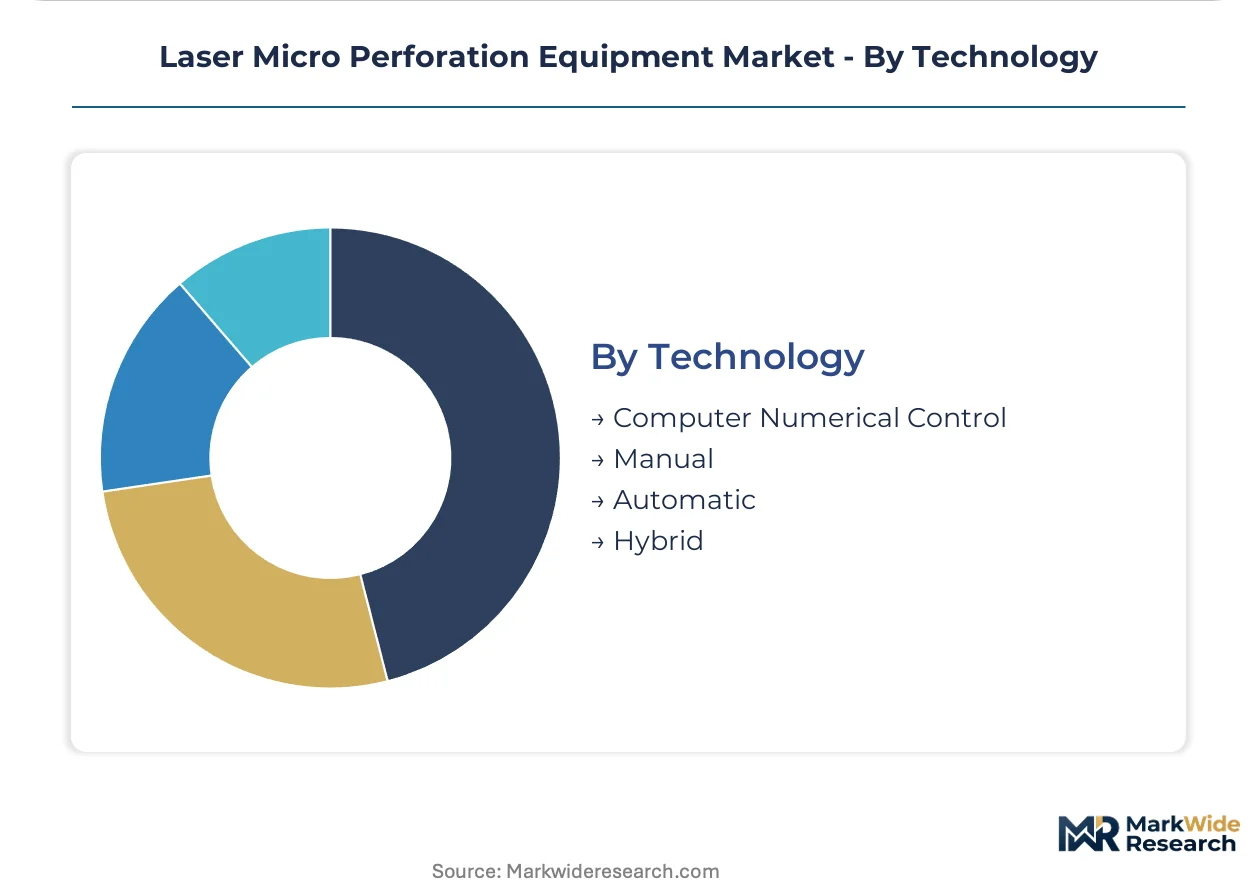
Technology:
Automation level correlates with throughput consistency requirements, with premium positioning attaching to reduced operator intervention architectures.
- Automatic:Real-time machine vision integration enables closed-loop process control, eliminating offline inspection stations from high-volume packaging lines. CE marking documentation requirements extend sales cycles for non-European automatic system suppliers.
- Computer Numerical Control:Programmable motion systems balance flexibility with repeatability, serving mid-tier converters with heterogeneous SKU portfolios.
- Hybrid:Configurations combining manual setup with automated production phases accommodate pilot-line validation before full-scale deployment.
- Manual:Limited to prototype development and specialty short-run applications where adjustment flexibility outweighs throughput priorities.
Automatic configurations command placement priority in Germany; hybrid systems are expanding most quickly among emerging Asian packaging hubs validating process parameters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters concentrate demand for high-specification laser micro perforation equipment, while regulatory pressure across multiple jurisdictions accelerates deployment timelines for compliant packaging infrastructure.
Germany
Fresh produce distributors mandate laser-perforated breathable films to reduce spoilage in extended supply chains. REACH substance restrictions phase out chemical etching alternatives across polymer processing. Stuttgart and Wolfsburg precision engineering clusters pilot femtosecond fiber systems for automotive interior trim applications.
United States
Wisconsin and California converters face steep EPA compliance gradients for solvent-based adhesive curing processes. National Emission Standards for Hazardous Air Pollutants enforcement accelerates laser-based dry process substitution. Toll perforation operators deploy systems to capture regulatory-driven equipment replacement demand.
India
FSSAI shelf-life labeling mandates redirect capital expenditure toward laser-perforated breathable films in domestic dairy and produce supply chains. Mumbai and Ahmedabad flexible packaging clusters expand capacity to serve growing domestic demand. Private-label food chains specify upstream film requirements without direct capital deployment.
China
Battery separator film perforation creates crossover demand from lithium-ion cell manufacturers seeking dry process alternatives. Han's Laser Technology Industry Group leverages manufacturing scale to extend reach into emerging Asian packaging hubs. Domestic converters prioritize equipment compatibility with existing production line footprints.
Netherlands
Equipment-as-service contracting displaces outright purchase models among mid-cap packaging groups. EU Green Deal procurement incentives favor equipment qualifying for reduced carbon footprint certifications. Benelux private equity-owned roll-up strategies favor operational expenditure structures covering maintenance and beam source replacement.
Laser Micro Perforation Equipment Market Competitive Environment
German producers anchor the premium-tier equipment segment; Chinese fabricators hold scale-driven positions in emerging market supply. The vendor structure consolidates around established platform providers with CE marking documentation capabilities. Three archetypes dominate: vertically integrated laser source manufacturers, precision beam delivery specialists, and high-volume equipment fabricators. Strategic moves concentrate on geographic expansion into Indian flexible packaging buildouts and technology licensing for battery separator applications.
Within the precision engineering tier, TRUMPF GmbH + Co. KG and MLT Micro Laser Technology exemplify deep specialization in ultrafast beam delivery architectures. Coherent represents vertically integrated control over laser source manufacturing. Han's Laser Technology Industry Group Co., Ltd. occupies the scale-driven position, leveraging manufacturing breadth to serve emerging Asian packaging hubs. These three anchors illustrate the geographic and capability split defining competitive positioning.
| Leading Market Players |
|---|
| Coherent |
| TRUMPF GmbH + Co. KG |
| MLT Micro Laser Technology |
| Comexi Group |
| El.En Group |
| AZCO Corp |
| Han's Laser Technology Industry Group Co., Ltd. |
| Preco Inc |
| Synrad |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing converter procurement timelines, forcing equipment buyers toward pre-validated platform providers with established CE marking documentation. This supplier consolidation concentrates pricing power among German-engineered OEMs while Chinese fabricators compete on manufacturing scale.
Pricing Analysis
Volume placements concentrate in mature CO2 laser platforms where manufacturing scale enables competitive positioning, while fiber laser systems capture premium margins through ultrafast beam delivery specifications. Price differentiation rests on automation architecture complexity and real-time machine vision integration levels. Cost compression in mid-market tiers intensifies as Han's Laser Technology Industry Group extends manufacturing breadth into emerging Asian packaging hubs. Packaging converters with heterogeneous SKU portfolios exhibit highest price sensitivity; automotive and medical device segments prioritize performance consistency over acquisition cost.
Supply Chain Analysis
Freight cost escalation from German precision engineering clusters to Mumbai and Ahmedabad converter facilities is redirecting procurement toward regional assembly partners. Optical component sourcing draws from German-engineered galvo scanner specialists, ZnSe focusing lens fabricators, and ytterbium-doped fiber suppliers concentrated in China and the United States. Single-source vulnerability in high-purity optical substrates creates procurement risk for OEM output scaling. Distribution runs through direct equipment sales for large integrated manufacturers and equipment-as-service contracting for Benelux mid-cap packaging groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CE marking documentation requirements and extended producer responsibility frameworks are consolidating procurement decisions around established platform providers, forcing smaller equipment builders toward niche specialization or exit.
For Market Incumbents: Hedge against fiber laser substitution by deepening R&D investment in picosecond pulse architectures that unify cutting and perforation operations. Anchor premium positioning through captive supply of high-purity optical components, reducing exposure to 12-18 month lead time volatility in German-engineered galvo scanners. Secure channel control via equipment-as-service contracting structures that lock in recurring revenue from Benelux private equity roll-ups.
For New Entrants and Emerging Players: Toll perforation operators in Wisconsin and California present the most penetrable entry channel, capturing EPA-driven substitution away from solvent-based adhesive curing processes. Target battery separator film applications where lithium-ion cell manufacturers seek dry process alternatives with controlled porosity specifications. Pursue technology licensing arrangements with established OEMs rather than direct platform competition.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated laser source manufacturers with ultrafast beam delivery capabilities and existing CE marking infrastructure. Long-term viability hinges on exposure to Indian flexible packaging buildouts and battery separator crossover demand. Monitor FSSAI enforcement patterns as the inflection signal for emerging market capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Source Manufacturing | Coherent sustains pricing power across fiber and CO2 platforms through captive ytterbium-doped fiber production. |
| Ultrafast Beam Delivery R&D Investment | TRUMPF GmbH + Co. KG anchors premium positioning in Stuttgart automotive interior trim pilot programs. |
| Equipment-as-Service Contracting Model | Benelux private equity roll-ups favor operational expenditure structures covering maintenance and beam source replacement. |
| Geographic Expansion into Indian Flexible Packaging | Mumbai and Ahmedabad converters expand capacity to serve FSSAI-mandated shelf-life labeling requirements. |
| Technology Licensing for Battery Separator Applications | Crossover demand from lithium-ion cell manufacturers creates non-packaging revenue diversification for laser perforation specialists. |
Study Parameters
Document review covered regulatory filings from EPA and ECHA, equipment specification databases, and polymer processing trade publications, complemented by interviews with packaging converter plant managers, OEM procurement teams, aftermarket service heads, and laser source R&D directors. Secondary validation drew from SEC 10-K disclosures, CE marking documentation repositories, and customs trade data for optical component flows. Bottom-up equipment placement tallies were cross-referenced against top-down market sizing from industry association reports.
Historical shipment data was cross-referenced against panel input from equipment manufacturers and end-user procurement leads to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include laser source type, automation level, application category, and regional regulatory cluster. CAGRs were derived from slope analysis of validated placement trajectories, incorporating battery separator demand elasticity and REACH phase-out timelines as industry-specific forecast inputs.
Caveats apply where EPA enforcement gradients, EU extended producer responsibility implementation speeds, or femtosecond fiber laser cost curves could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market