
 Semiconductor and Circuit Manufacturing Market | 2026-2036
Semiconductor and Circuit Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor and Circuit Manufacturing Market Intelligence
ISO 26262 automotive safety qualification is collapsing the supplier pool for mission-critical chipsets. TSMC leverages its 3nm process leadership to anchor premium foundry contracts. Intel sustains massive capital intensity in pursuit of process parity. Samsung Electronics dominates memory output through captive supply of NAND and DRAM wafers.
Semiconductor and circuit manufacturing encompasses the fabrication of integrated electronic components on silicon, gallium nitride, or silicon carbide substrates using photolithography, chemical vapor deposition, and ion implantation to achieve feature sizes below 5 nanometers, primarily serving computation, power conversion, and signal processing needs. Integrated circuits command the largest value pool while sensors and microelectromechanical systems represent the fastest-expanding segments driven by IoT and automotive sensor fusion architectures. Foundries and fabless companies are restructuring procurement patterns as advanced node access becomes the decisive competitive variable.
EPA emissions rules, EU REACH chemical restrictions, and Taiwan's national technology security framework collectively determine where fabs expand and which materials enter production flows. The EU Chips Act and US CHIPS and Science Act are redirecting subsidy eligibility toward domestic fabrication capacity. Stakeholders must monitor which regulatory jurisdictions secure pilot-line commitments for sub-2nm processes.
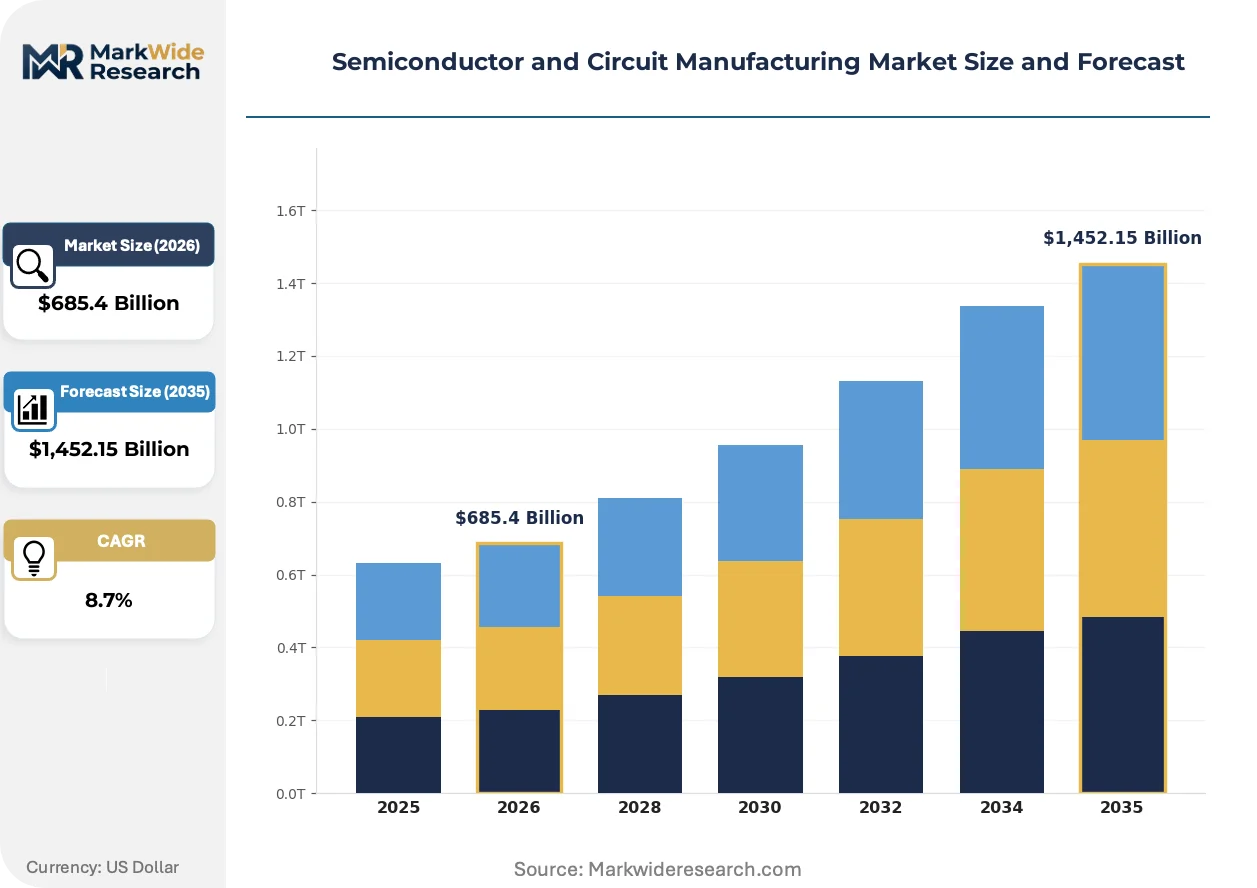
Market Dynamics
Automotive electrification is compressing design cycles for power semiconductors while advanced node access concentrates among a shrinking pool of foundry operators, creating a bifurcation between leading-edge logic and trailing-edge power devices.
Growth Catalysts
- EU Chips Act capital subsidies:The framework is redirecting pilot-line investments toward Dresden, Leuven, and Grenoble clusters, expanding 300mm wafer capacity for automotive-qualified processes.
- Silicon carbide substrate adoption:Electric vehicle traction inverters are pulling 200mm SiC wafer demand, with on-board chargers and DC-DC converters following the same material transition.
- Advanced packaging architectures:Chiplet-based designs are proliferating across AI accelerators and high-performance computing, driving demand for 2.5D and 3D integration technologies.
Market Restraints
- Extreme ultraviolet lithography equipment scarcity:ASML's annual output limits constrain sub-3nm capacity expansion, creating allocation bottlenecks for logic foundries.
- Taiwan Strait concentration risk:Over 90% of leading-edge foundry output resides within a single earthquake and geopolitical exposure zone, amplifying supply disruption vulnerability.
- Fluorinated gas emissions constraints:EU F-Gas Regulation and EPA reporting requirements are restricting etching and chamber-cleaning chemistries, raising compliance costs for legacy fabs.
Strategic Opportunities
- India's semiconductor PLI scheme:The production-linked incentive framework is attracting assembly, test, and packaging investments, creating a secondary hub outside East Asian concentration.
- Automotive sensor fusion integration:LiDAR, radar, and camera signal processing are converging on single system-on-chip architectures, expanding addressable silicon content per vehicle.
- Photonic-electronic monolithic integration:Silicon photonics is merging with CMOS logic on shared substrates, enabling co-packaged optics for data center interconnects.
Industry Challenges
- ISO 26262 functional safety certification timelines:Automotive qualification cycles extend 18-24 months, compressing product windows against accelerating vehicle platform refreshes.
- Legacy 200mm equipment obsolescence:Depreciated toolsets for mature nodes face spare part shortages, constraining capacity expansion for industrial and automotive microcontrollers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor and Circuit Manufacturing Market |
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,452.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, Discrete Semiconductors, Optoelectronics, Sensors, Microelectromechanical Systems Technology: Chemical Vapor Deposition, Photolithography, Ion Implantation, Etching, Thin Film Deposition Application: Consumer Electronics, Telecommunications, Aerospace Systems, Defense Equipment, Industrial Automation End User: OEMs, Contract Manufacturers, Fabless Companies, Foundries, Assembly & Test Providers |
| Companies Covered | SK hynix, Intel, Taiwan Semiconductor Manufacturing Company (TSMC), Micron Technology, GlobalFoundries, NVIDIA Corporation, ASML Holding, Advanced Micro Devices (AMD), Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor and Circuit Manufacturing Market Strategic Shifts & Innovations
Process node leadership is fragmenting across application-specific optimization paths, with diverging requirements for power efficiency, thermal tolerance, and radiation hardness reshaping foundry specialization.
Gallium nitride power devices are fragmenting the silicon MOSFET incumbent position in consumer adapters, data center power supplies, and solar inverters. Tier-one OEMs are qualifying GaN transistors for 650V applications previously dominated by superjunction silicon. The technology is fragmenting vendor consolidation by enabling fabless entrants to compete without captive wafer fabs.
REACH chemical restrictions are forcing material substitutions in photoresists, etchants, and cleaning solvents across European fabrication facilities. ECHA's Substances of Very High Concern list is accelerating per- and polyfluoroalkyl substance phase-outs, requiring process requalification. Memory and logic manufacturers are responding with closed-loop chemical recovery systems and alternative formulation partnerships.
Direct foundry contracting is displacing traditional distributor channels for advanced node access, with fabless designers negotiating multi-year capacity reservations. The model is compressing spot market participation for leading-edge wafers while expanding long-term agreement prevalence. North American AI chip designers are most visibly adopting this procurement restructuring.
Semiconductor and Circuit Manufacturing Market Segmentation
Segmentation reveals how semiconductor manufacturing fragments across competing substrate technologies, process methods, and customer procurement models. Each dimension carries distinct margin structures and capital intensity requirements that reshape competitive positioning.
Product Type:
Discrete semiconductors and optoelectronics face acute substitution pressure from compound material alternatives, while integrated circuit architectures consolidate value capture.
- Integrated Circuits:Monolithic chips fabricated on silicon wafers integrate billions of transistors for logic and memory functions. Data center AI accelerators and smartphone application processors in Taiwan and South Korea concentrate demand, with TSMC's 3nm node access determining procurement priority.
- Sensors:Devices measuring physical, chemical, or biological parameters convert stimuli to electrical signals. Automotive LiDAR and industrial IoT deployments in Germany and Japan pull CMOS image sensor and MEMS microphone volumes, constrained by ISO 26262 qualification timelines.
- Discrete Semiconductors:Individual transistor, diode, and thyristor components handle power switching and rectification.
- Optoelectronics:Light-emitting and detecting devices spanning LEDs, laser diodes, and photodetectors.
- Microelectromechanical Systems:Miniaturized mechanical structures integrated with electronics for motion sensing and acoustic applications.
Integrated circuits anchor the volume base while sensors gain share at the steepest rate.
Technology:
Cost tier stratification separates billion-dollar lithography systems from mature deposition tools serving trailing-edge nodes.
- Photolithography:Optical pattern transfer using deep-ultraviolet or extreme-ultraviolet light sources defines circuit geometries. Logic foundries in Taiwan and the Netherlands compete for ASML's annual EUV tool allocation, with each unit requiring two years from order to installation.
- Chemical Vapor Deposition:Gas-phase precursor reactions create thin dielectric and conductive films. Memory manufacturers in South Korea and China deploy high-volume CVD clusters for 3D NAND stack deposition, driving equipment utilization rates above 85 percent.
- Ion Implantation:Accelerated dopant atoms modify semiconductor electrical properties.
- Etching:Plasma and wet chemical processes remove material to define circuit patterns.
- Thin Film Deposition:Physical vapor deposition and atomic layer deposition create precise material layers.
Photolithography commands the capital intensity peak while etching expands most quickly through 3D architecture proliferation.
Application:
Customer type divergence splits procurement between high-volume consumer platforms and low-volume aerospace qualification requirements.
- Consumer Electronics:Smartphones, personal computers, and wearables consume leading-edge logic and memory. Assembly in Vietnam and India pulls chip shipments from Taiwanese and South Korean fabs, with India's PLI scheme redirecting final device production.
- Industrial Automation:Programmable logic controllers, motor drives, and robotics systems require extended-temperature microcontrollers. German and Japanese machinery OEMs source trailing-edge 200mm wafers, constrained by legacy equipment obsolescence.
- Telecommunications:Baseband processors and radio frequency front-ends enable wireless infrastructure.
- Aerospace Systems:Radiation-hardened and high-reliability components serve satellite and avionics platforms.
- Defense Equipment:Trusted foundry requirements and ITAR restrictions govern secure chip procurement.
Consumer electronics anchors the volume base while industrial automation climbs the fastest on reshoring-driven demand.
End User:
Supply concentration varies dramatically between captive foundry operations and distributed assembly networks.
- Foundries:Merchant wafer fabrication facilities serve multiple fabless customers on shared process nodes. Taiwan and South Korea concentrate leading-edge capacity, with Intel and Samsung pursuing process parity through massive capital programs.
- Fabless Companies:Design-only semiconductor firms outsource manufacturing to merchant foundries. North American AI chip designers negotiate multi-year capacity reservations directly with TSMC, compressing distributor channel participation.
- OEMs:Vertically integrated device manufacturers retain in-house fabrication.
- Contract Manufacturers:Electronics manufacturing services providers assemble systems from procured components.
- Assembly & Test Providers:Outsourced semiconductor assembly and test facilities handle packaging and final verification.
Foundries anchor the volume base while fabless companies expand most quickly through AI accelerator proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and automotive OEMs concentrate procurement power across distinct geographic clusters, each shaped by national industrial policy and local supply chain density.
United States
Cloud hyperscalers and defense primes drive demand for advanced logic and radiation-hardened components. The CHIPS and Science Act directs EPA and Commerce Department oversight toward domestic fab construction. Arizona and Texas host emerging leading-edge fabrication campuses competing for TSMC and Intel pilot-line commitments.
Taiwan
Fabless designers from North America and Europe anchor wafer demand at the most advanced process nodes. The National Technology Security Framework governs export controls and foreign investment screening for critical facilities. Hsinchu Science Park concentrates EUV lithography deployment and 3nm volume production.
South Korea
Memory-intensive AI training workloads pull 3D NAND and high-bandwidth DRAM output. MFDS chemical safety standards and Ministry of Trade, Industry and Energy subsidies shape expansion timelines. Pyeongtaek and Yongin host successive generations of DRAM and NAND fabrication complexes.
Germany
Automotive Tier-1 suppliers source power semiconductors and microcontrollers for electrification platforms. EU REACH chemical restrictions and KBA automotive safety standards extend qualification timelines. Dresden and Magdeburg anchor the European Silicon Saxony cluster for automotive-qualified processes.
Japan
Industrial machinery OEMs and automotive electronics suppliers consume mature-node microcontrollers and sensors. METI supply chain resilience programs and JIS standards govern material sourcing and quality certification. Kyushu's Kumamoto region hosts trailing-edge capacity expansion for automotive and industrial applications.
Semiconductor and Circuit Manufacturing Market Key Industry Players
Player mix skews toward integrated device manufacturers and pure-play foundries with diverging capital intensity models. Market structure concentrates at the leading edge while fragmenting across trailing-edge power and analog segments. Strategic archetypes include captive memory producers, merchant logic foundries, and fabless design houses. Dominant competitive moves center on multi-year capacity reservation agreements and sovereign subsidy capture for greenfield fabrication sites.
Among Asia-Pacific-based fabricators, Taiwan Semiconductor Manufacturing Company exemplifies the pure-play foundry archetype through its process node leadership position. Samsung Electronics occupies a dual role spanning captive memory supply and merchant foundry services. SK hynix represents the memory-specialist tier with concentrated NAND and DRAM output. Intel anchors the integrated device manufacturer category pursuing process parity through massive capital programs.
| Leading Market Players |
|---|
| SK hynix |
| Intel |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Micron Technology |
| GlobalFoundries |
| NVIDIA Corporation |
| ASML Holding |
| Advanced Micro Devices (AMD) |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
ISO 26262 automotive safety qualification gates both supplier admission and price premiums simultaneously, with certification tiers separating qualified foundries from commodity wafer sources while OEMs pay structural premiums for traceable supply chains.
Pricing Analysis
Long-term offtake contracts with silicon wafer indexation anchor pricing for leading-edge logic, while automotive-qualified processes command premiums over consumer-grade equivalents due to extended qualification timelines. Cost compression in trailing-edge mature nodes intensifies as legacy 200mm equipment scarcity constrains capacity expansion against reshoring-driven demand. Fabless AI chip designers exhibit lowest price sensitivity, prioritizing TSMC 3nm access over unit economics, whereas industrial microcontroller buyers face acute margin pressure from distributor channel compression.
Supply Chain Analysis
Port congestion across transpacific trade lanes elevates inbound logistics costs for photolithography equipment sourced from Dutch and Japanese toolmakers, compressing installation schedules for greenfield fabs. Taiwan, South Korea, and the United States concentrate leading-edge wafer fabrication capacity, drawing from neon gas supplies anchored in Ukraine and Ukraine-adjacent sources, high-purity silicon wafers from Japanese and German suppliers, and EUV pellicles from specialized chemical producers. Single-source vulnerability around ASML's annual EUV tool allocation creates allocation bottlenecks for sub-3nm capacity expansion. Distribution runs through direct foundry contracting displacing traditional semiconductor distributors for advanced node access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through ISO 26262 and ITAR qualification creates switching costs that lock automotive and defense OEMs into approved supplier pools.
For Market Incumbents: Compound process node leadership through captive EUV tool allocation commitments, while deepening backward integration into silicon carbide substrate supply to defend against emerging GaN power device substitution. Add 300mm capacity in Dresden or Phoenix to capture EU Chips Act and CHIPS Act subsidy flows before qualification windows close. For New Entrants and Emerging Players: Photonic-electronic monolithic integration represents an under-served service layer where incumbent foundries lack co-packaged optics process development, enabling fabless entrants to target data center interconnect demand without competing for leading-edge logic capacity. Pursue joint development agreements with North American cloud hyperscalers as the most penetrable buyer segment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced packaging and 3D integration sub-segments, favoring acquisition targets with existing bumping and TSV capability over greenfield buildouts. Watch for pilot-line commitment announcements in Leuven, Grenoble, or Dresden as inflection indicators for European subsidy capture viability.| Strategic Initiative | Industry Significance |
|---|---|
| EUV Tool Pre-Allocation Agreement | Secures ASML annual output years ahead of installation, anchoring 3nm volume production timelines. |
| Silicon Carbide Wafer Backward Integration | Captive 200mm SiC substrate supply locks in EV traction inverter qualification pipelines. |
| Automotive Safety Certification Investment | ISO 26262 functional safety qualification opens mission-critical chipset procurement channels. |
| Advanced Packaging Joint Venture | 2.5D and 3D integration partnerships with OSATs enable chiplet-based AI accelerator production. |
| Direct Fabless Capacity Reservation | Multi-year wafer offtake contracts with North American AI designers compress distributor participation. |
Research Approach
A standing panel of foundry operations executives, fabless design house CTOs, automotive Tier 1 procurement directors, and semiconductor equipment sales engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from SEC 10-K filings, TSMC and Samsung capex disclosures, EU Chips Act implementation documents, and customs wafer trade data. Bottom-up wafer demand modeling triangulated against top-down foundry revenue aggregation.
Output consistency was checked against external benchmarks including hyperscaler AI accelerator deployment disclosures, EV production forecasts from vehicle registration databases, and memory bit growth estimates from industry associations. Segmentation dimensions spanned substrate technology, process node tier, end-use application, and regional regulatory cluster across the analysis window. CAGRs were derived from fitted growth curves incorporating equipment lead times, qualification cycle durations, and subsidy disbursement schedules.
Forecasts assume regulatory continuity in EU REACH chemical restrictions, US EPA emissions frameworks, and Taiwan's national technology security regime; material policy shifts would require re-modeling. Specific risks include Taiwan Strait geopolitical disruption, ASML export control expansion, and fluorinated gas phase-out acceleration. Recalibration cycles align with material shifts in subsidy award announcements, pilot-line commitment disclosures, and automotive platform electrification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Solder Paste Market