
 Semiconductor Polishing Pads Market | 2026-2036
Semiconductor Polishing Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Polishing Pads Market Intelligence
The European Union's REACH regulation is recalibrating the cost-of-entry calculus for new material formulations used in polishing pads. DuPont de Nemours Inc. leverages its extensive chemical engineering expertise to develop compliant, high-performance polyurethane pads. In parallel, Cabot Microelectronics Corporation specializes in slurry and pad combinations for advanced node CMP processes. 3M Company sustains its market position through its global manufacturing scale and a diversified product portfolio addressing multiple polishing steps.
A semiconductor polishing pad is a consumable engineered composite, typically made from polyurethane, with controlled porosity and hardness. Its primary function is to work with a chemical slurry to achieve nanometer-level surface planarity on silicon wafers during the Chemical Mechanical Polishing (CMP) process. Polyurethane materials continue to dominate due to their tunable mechanical properties, which are critical for advanced wafer polishing. Demand from large-scale Foundries is the principal driver for pads used in Chemical Mechanical Polishing applications.
Manufacturers must navigate a complex web of environmental and quality standards for market access. Regulations like the EPA's rules on industrial wastewater in the United States and ECHA's oversight in Europe dictate the chemical composition of pads and disposal procedures for used materials. Future profitability will depend on developing next-generation pads that meet stringent planarity requirements for smaller nodes while using more sustainable materials.
Market Dynamics
The relentless pursuit of smaller semiconductor process nodes is the central force shaping the polishing pad market. This drive by advanced logic and memory manufacturers imposes extreme surface planarity requirements, compelling continuous innovation in pad material science and manufacturing precision.
Growth Catalysts
- Policy-Driven Fab Expansion:Government initiatives like the US CHIPS and Science Act and the European Chips Act are directly stimulating the construction of new fabrication plants, creating a locked-in, long-term demand stream for polishing pads and other consumables.
- Advanced Node Scaling:The migration by leading foundries in Taiwan and South Korea to sub-5nm nodes necessitates more complex and numerous Chemical Mechanical Polishing (CMP) steps, increasing the consumption of higher-value, specialized pads per wafer start.
- Heterogeneous Integration:The adoption of 3D-IC and advanced packaging technologies introduces new materials and complex device topographies, requiring novel polishing solutions tailored for materials beyond traditional silicon, such as glass or exotic metals.
Market Restraints
- Material Performance Ceilings:Conventional polyurethane materials are approaching their physical limits in providing the simultaneous stiffness, porosity, and durability required for next-generation planarity, creating a significant R&D hurdle for pad developers.
- Regulatory Compliance Overhead:Adherence to stringent chemical regulations, such as the EU's REACH framework, increases the cost and timeline for developing and qualifying new pad formulations, acting as a barrier to entry.
- Input Cost Volatility:The market's dependence on petroleum-derived precursors for polyurethane production exposes manufacturers to price fluctuations in the global petrochemical market, which can compress operating margins.
Strategic Opportunities
- Sustainable and Recyclable Materials:Developing pads from bio-based polymers or creating effective recycling programs for used pads offers a strong value proposition to large semiconductor manufacturers focused on reducing their environmental footprint.
- Fixed-Abrasive Pad Development:Pads with abrasives embedded directly into the matrix represent a significant opportunity to simplify the CMP process, reduce slurry consumption, and improve defect control for specific applications. *Service and Consumable Bundling: Offering integrated solutions that bundle pads with proprietary slurries and conditioners, optimized for specific applications, allows suppliers to capture more value and create stickier customer relationships with foundries.
Industry Challenges
- Process Integration Complexity:Ensuring a new pad design is compatible with a fab's existing ecosystem of dozens of unique slurry formulations and post-CMP cleaning chemistries is a major technical and logistical challenge.
- Intellectual Property Navigation:The dense landscape of patents covering pad designs, groove patterns, and material compositions creates a complex environment for new entrants and requires careful IP strategy from all participants.
- Metrology and Quality Control Demands:Achieving the required nanometer-scale uniformity across a large-diameter pad demands significant capital investment in advanced manufacturing process controls and sophisticated optical inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Polishing Pads Market |
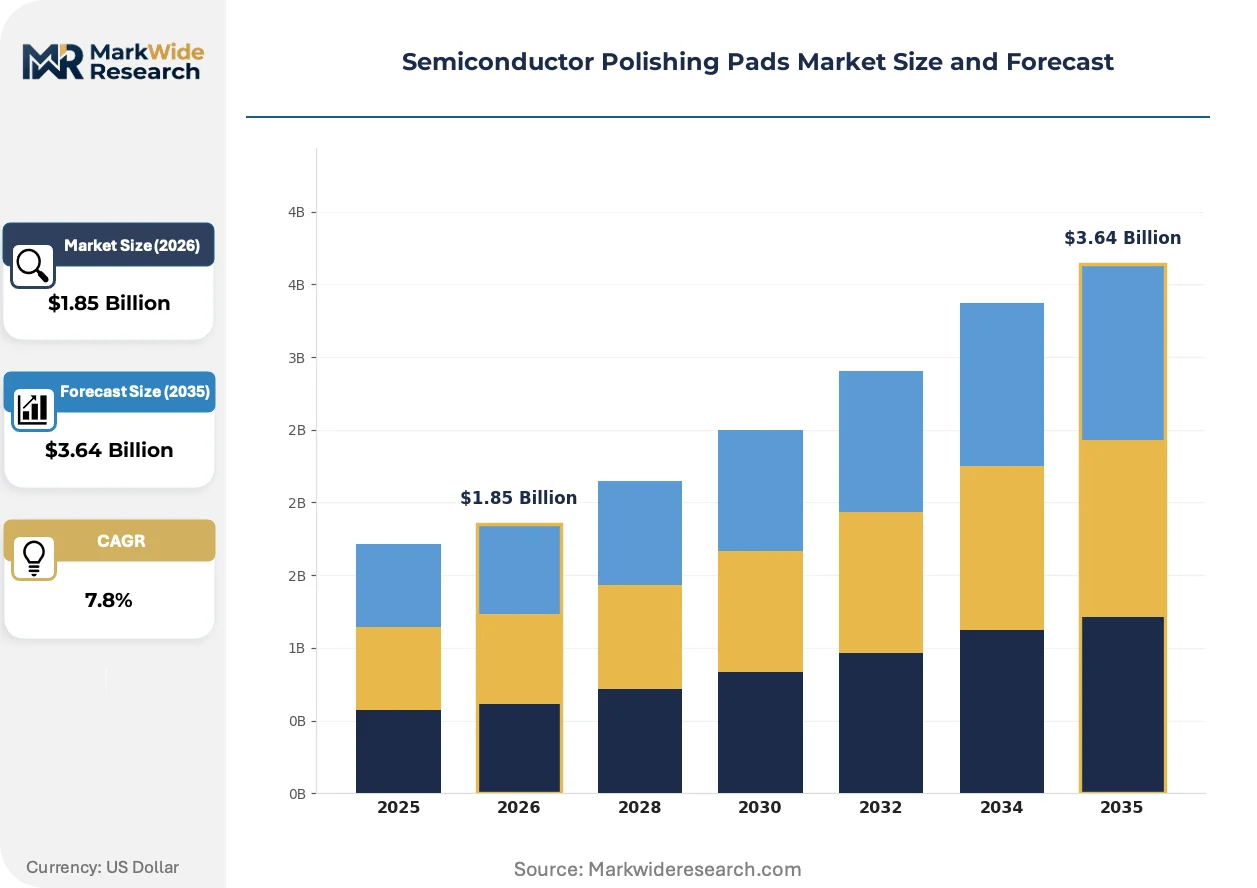
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Chemical Mechanical, Optical, Glass End User: Foundries, Integrated Device Manufacturers, Outsourced Semiconductor Assembly, Packaging Application: Wafer Polishing, Chemical Mechanical Polishing, Surface Preparation, Backend Processing Material: Polyurethane, Polyethylene, Polyester, Others |
| Companies Covered | 3M Company, DuPont de Nemours Inc., Entegris Inc., Cabot Microelectronics Corporation, Fujibo Holdings Inc., Shin-Etsu Chemical Co., Ltd., SK enpulse Co., Ltd., Merck Group, Logitech International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Polishing Pads Market Strategic Shifts & Innovations
The evolution of semiconductor polishing pads is inextricably linked to the semiconductor industry's dual pressures of architectural complexity and heightened environmental scrutiny. These forces are fundamentally altering material science priorities and the nature of supplier-foundry collaborations.
Fixed-Abrasive Technology
Pads with integrated abrasive particles provide mechanical action directly at the wafer surface, a function traditionally performed by the slurry. Advanced logic device manufacturers are adopting this technology for specific, critical polishing steps where defectivity and process control are paramount. This technology is absorbing the primary mechanical role of the slurry, simplifying the overall CMP process and reducing chemical consumption.
Sustainability-Driven Formulation
The EPA’s stringent rules on industrial wastewater in the United States are compelling fabs to re-evaluate all chemical inputs. This regulatory pressure directly impacts the selection criteria for consumables that contribute to the effluent stream. Consequently, pad manufacturers are actively developing and marketing formulations with reduced levels of persistent chemicals to align with the sustainability goals of US-based semiconductor fabs.
Integrated Consumable Systems
A clear behavioral shift is underway as leading-edge foundries increasingly prefer to source pre-qualified, integrated systems of pads and slurries from a single supplier. This model supplants the traditional approach of purchasing components separately and streamlines the complex process of tool and material qualification. This trend is most evident in the high-volume manufacturing environments of Taiwan, where reducing time-to-yield is a primary competitive driver.
Semiconductor Polishing Pads Market Segmentation
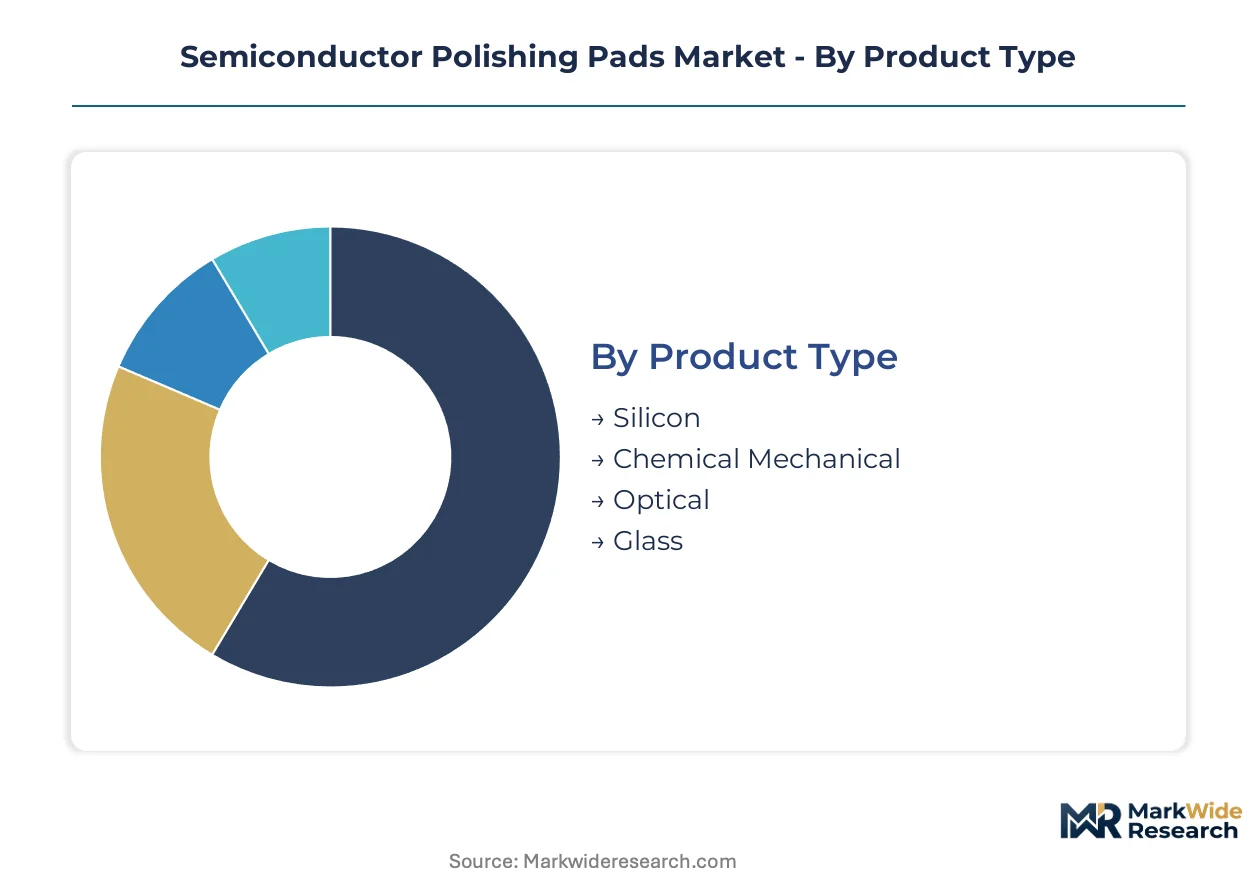
The semiconductor polishing pads market segments reflect the diverse technical requirements of wafer fabrication. Each category highlights specific material compositions, end-user profiles, and critical application areas essential for achieving nanometer-level surface planarity. Understanding these distinctions is crucial for suppliers to align product development with foundry demands.
Product Type:
The product type segmentation reveals the spectrum from highly specialized pads for specific materials to more standardized offerings for general processes.
- Silicon:These pads are specifically designed for polishing silicon wafers, the foundational material for most semiconductors. Demand concentrates in advanced logic and memory manufacturing facilities in Taiwan and South Korea, driven by the need for ultra-flat surfaces on large-diameter wafers.
- Chemical Mechanical:Chemical Mechanical pads facilitate the CMP process by working in conjunction with slurries to remove material and achieve global planarity. Leading foundries utilize these pads extensively for critical planarization steps in sub-5nm node production, necessitating precise material removal rates and low defectivity.
- Optical:Optical polishing pads are engineered for precision finishing of optical components, such as lenses and prisms, where surface quality is paramount.
- Glass:These pads are tailored for polishing glass substrates, increasingly relevant in advanced packaging and display technologies.
Leading the category by volume: Silicon. Growing fastest: Chemical Mechanical.
End User:
End-user segmentation highlights distinct customer profiles and their varying procurement strategies and volume requirements across the semiconductor manufacturing ecosystem.
- Foundries:Foundries, such as TSMC and Samsung Foundry, are the largest consumers of polishing pads, driving demand for high-volume, high-performance consumables. Their principal driver is the need for consistent process control across billions of dollars of wafer starts.
- Integrated Device Manufacturers:IDMs like Intel and Micron integrate design, manufacturing, and packaging, requiring pads optimized for their proprietary processes. The US CHIPS Act is stimulating new IDM fab investments, directly increasing material procurement.
- Outsourced Semiconductor Assembly:OSAT companies focus on assembly and testing, utilizing pads for specific back-end processes and advanced packaging applications.
- Packaging:This segment includes manufacturers specializing in advanced packaging solutions, where polishing pads achieve planarity for complex 3D-IC structures.
Foundries consistently gain share fastest across the end-user landscape.
Application:
The application segment distinguishes pads based on their specific function within the complex stages of semiconductor wafer processing, from initial preparation to final finishing.
- Chemical Mechanical Polishing:CMP applications represent the core demand for polishing pads, crucial for achieving nanometer-scale planarity across multiple layers of a wafer. The migration to sub-5nm nodes by leading foundries necessitates more numerous and precise CMP steps.
- Wafer Polishing:This broad application encompasses all polishing steps designed to achieve a smooth, defect-free surface on semiconductor wafers. Advanced logic manufacturers prioritize defect reduction and tight uniformity in this segment for critical device performance.
- Surface Preparation:Pads for surface preparation are used to clean and condition wafers before critical deposition or lithography steps.
- Backend Processing:Backend processing applications involve polishing steps after the front-end-of-line fabrication, often for advanced packaging or thinning.
Chemical Mechanical Polishing applications show the steepest expansion trajectory.
Material:
Material segmentation differentiates polishing pads by their fundamental composition, directly influencing their mechanical properties, durability, and chemical compatibility in CMP processes.
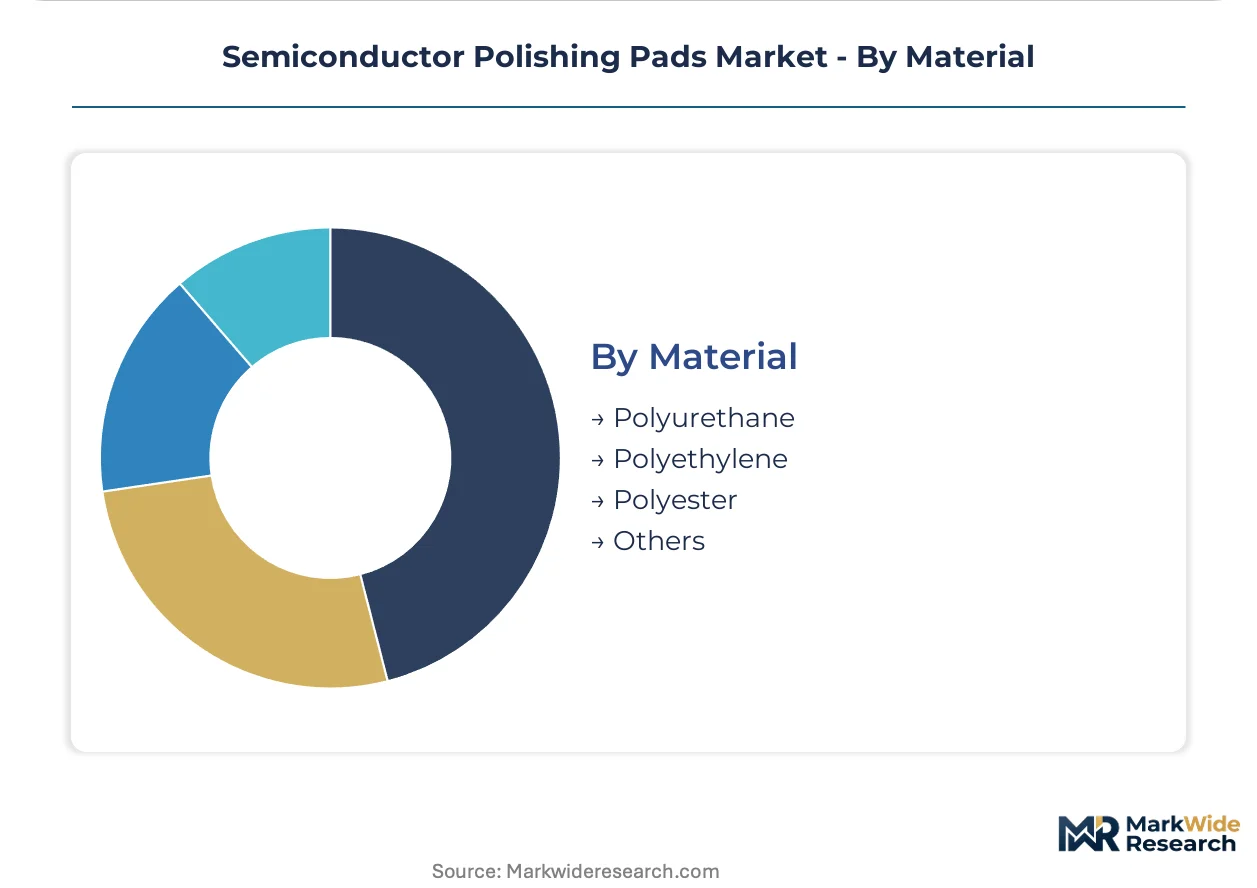
- Polyurethane:Polyurethane materials dominate the market due to their tunable mechanical properties, including hardness and porosity, essential for controlled material removal. DuPont de Nemours Inc. leverages its expertise in high-performance polyurethane pads to meet stringent planarity requirements.
- Others:This category includes emerging or specialized materials, such as those derived from bio-based polymers or advanced composites, developed for niche applications or enhanced sustainability. Future profitability depends on developing these next-generation materials.
- Polyethylene:Polyethylene pads offer specific characteristics for certain polishing applications, often chosen for their chemical resistance or cost-effectiveness.
- Polyester:Polyester-based pads are utilized in applications requiring different mechanical stiffness or abrasive retention properties compared to polyurethane.
Polyurethane materials are climbing most quickly in adoption for advanced nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for semiconductor polishing pads concentrates heavily in established manufacturing centers globally. Leading foundries and Integrated Device Manufacturers drive substantial procurement volumes. This geographic focus creates distinct regional market dynamics for suppliers.
United States
The United States market sees significant demand from new IDM fab investments. The US CHIPS and Science Act stimulates substantial construction of advanced semiconductor manufacturing facilities. EPA's rules on industrial wastewater influence material selection for sustainable pad formulations. Arizona and New York are emerging as major hubs for new semiconductor manufacturing facilities.
Taiwan
Foundries in Taiwan drive immense demand for advanced polishing pads due to sub-5nm node scaling. The government's strong support for the semiconductor industry reinforces this growth trajectory. Taiwan's industrial policies focus on maintaining its leadership in advanced chip manufacturing. Hsinchu Science Park remains a global epicenter for leading-edge foundry operations.
South Korea
South Korea's advanced logic and memory manufacturers require specialized pads for complex CMP steps. The nation's strategic initiatives support the domestic semiconductor ecosystem development. Government programs aim to secure a resilient supply chain for critical materials. Gyeonggi Province hosts major production facilities for high-volume wafer fabrication.
Germany
Germany's demand for polishing pads is influenced by increasing automotive and industrial semiconductor production. The European Chips Act aims to boost domestic manufacturing capabilities across the continent. ECHA's oversight within the EU dictates chemical composition and disposal procedures for new pad formulations. Saxony, particularly Dresden, is a significant cluster for microelectronics production.
Netherlands
The Netherlands plays a crucial role in the semiconductor equipment supply chain, indirectly affecting pad demand. Its innovation ecosystem fosters the development of advanced materials and processes. EU regulations, including REACH, influence the qualification of new material formulations. The Eindhoven Brainport region is a hub for high-tech manufacturing and R&D activities.
Semiconductor Polishing Pads Market Key Industry Players
United States producers anchor one tier; Asian specialists hold another significant position in the semiconductor polishing pads market. The competitive landscape is structured with a few large, diversified chemical companies alongside specialized material science firms. These entities often focus on either high-performance solutions for advanced nodes or cost-effective offerings for mature processes. Portfolio diversification and strategic partnerships are dominant competitive moves.
Within the advanced materials segment, DuPont de Nemours Inc. exemplifies a chemical engineering powerhouse developing compliant, high-performance polyurethane pads. Cabot Microelectronics Corporation occupies a position specializing in integrated slurry and pad combinations for advanced node CMP processes. Shin-Etsu Chemical Co., Ltd. represents a major Asian chemical company with a strong presence in semiconductor materials. These players focus on product differentiation through material innovation and process optimization, aiming for nanometer-level surface planarity. They continuously invest in research and development to meet the stringent requirements of next-generation semiconductor manufacturing.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours Inc. |
| Entegris Inc. |
| Cabot Microelectronics Corporation |
| Fujibo Holdings Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| SK enpulse Co., Ltd. |
| Merck Group |
| Logitech International SA |
| Others |
Cost & Logistics Intelligence
Backward integration into specialized material science anchors a strong supply position for chemical engineering firms, influencing their pricing power for high-performance polyurethane pads. This control over raw material inputs directly shapes market competitiveness.
Pricing Analysis
The market exhibits a clear volume-versus-margin split, with high-volume foundries securing contract-based long-term offtake agreements. Price differentiation stems from quality grade and the customization level required for advanced node CMP processes. Pricing softness reflects input cost volatility of petroleum-derived precursors. Foundries demonstrate the least price sensitivity due to critical process control, while OSAT companies are more sensitive.
Supply Chain Analysis
Regional distribution centers facilitate direct sales to major fabrication plants, optimizing delivery for time-sensitive consumables. Geographic supply concentrates in Taiwan, South Korea, and the United States, reflecting the location of leading foundries and IDMs. The supply chain draws from polyurethane precursors and specialized abrasive particles. A structural risk involves regulatory restrictions like the EU's REACH framework, impacting material sourcing and formulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor polishing pads market is fundamentally a vertical-integration race, with players aggressively pursuing upstream control over novel material formulations. This strategic imperative aims to secure supply and differentiate offerings for advanced nodes.
For Market Incumbents:
Extend R&D efforts into bio-based polymers to overcome conventional polyurethane material performance ceilings. Consolidate market share through strategic partnerships with leading foundries, ensuring long-term supply contracts. Invest in capacity addition within US and European regions to capitalize on policy-driven fab expansion. This mitigates risks from evolving environmental regulations.
For New Entrants and Emerging Players:
Online platforms for material qualification present an entry point to target niche applications in advanced packaging and specialized materials beyond traditional silicon. OSAT companies represent the most penetrable segment for innovative solutions. Focus on developing integrated consumable systems that bundle pads with proprietary slurries. This streamlines qualification for smaller, agile customers.
For Investors and Strategic Acquirers:
Exit pathways concentrate in specialized material science firms offering proprietary pad formulations. The market demonstrates long-term viability with sustained demand for advanced nodes over the next decade. Target acquisition profiles include companies with robust intellectual property in sustainable materials or fixed-abrasive technology. The signal to watch is the adoption rates of fixed-abrasive pads in critical CMP steps.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand R&D in Bio-based Polymers | Addresses environmental regulations and meets sustainability goals of semiconductor fabs. |
| Invest in Advanced Metrology | Ensures nanometer-scale uniformity for large-diameter pads, critical for quality control. |
| Form Integrated Consumable Partnerships | Offers pre-qualified pad and slurry systems, streamlining material qualification for foundries. |
| Secure Long-Term Supply Contracts | Guarantees consistent material flow for high-volume manufacturing, stabilizing input costs. |
| Develop Fixed-Abrasive Pad Technologies | Simplifies CMP processes and reduces slurry consumption for advanced logic device manufacturers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, complemented by primary interviews. Conversations included fab process engineers, R&D directors, procurement leads, and environmental compliance officers. Secondary validation drew from ECHA reports, EPA wastewater guidelines, company 10-K filings, and semiconductor industry association reports. A robust bottom-up and top-down triangulation approach ensured data consistency.
Granularity at the product type, end-user, application, material, and geographic region levels informed the forecast framework across the analysis window. CAGRs were derived from linear regression and compound annual growth calculations. The model integrated industry-specific inputs such as wafer start volumes and process node migration rates. This approach provided a detailed market trajectory.
Inputs from industry reports and company disclosures were available through the study window; gaps in emerging material qualification data introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical stability and raw material supply. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Medical Component Manufacturing Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market