
 Europe Electronic Manufacturing Services Market | 2026-2036
Europe Electronic Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electronic Manufacturing Services Market Insights
Modular system integration is consolidating buyer preference across European EMS engagements, as OEMs seek bundled design-to-manufacture partnerships rather than fragmented component sourcing. Zollner Elektronik AG leverages its vertical manufacturing depth to anchor high-mix, low-volume contracts across German-speaking markets. Asteelflash Group competes through its pan-European facility network, sustaining proximity advantages for just-in-time automotive programs. Scanfil Oyj differentiates via its Nordic engineering heritage, specializing in ruggedized industrial and medical electronics.
Europe Electronic Manufacturing Services denotes third-party provision of printed circuit board assembly, full system integration, functional testing, and lifecycle management for electronic hardware, typically executed under ISO 13485 or IATF 16949 quality regimes depending on end-use sector. The discipline serves industrial automation, mobility, healthcare, and telecommunications by converting design specifications into volume-manufactured, certified electronic systems. PCB Assembly occupies the largest revenue share among service types, reflecting persistent demand for multilayer and flexible circuit fabrication across automotive and medical verticals. Box Build segments are gaining structural momentum as OEMs outsource increasingly complex electromechanical subsystems, concentrating margin pools in integrated enclosure and cable harness assembly. Medical Devices within product type categories command premium positioning, where CE marking under the EU MDR and specialized cleanroom protocols elevate barriers to supplier entry.
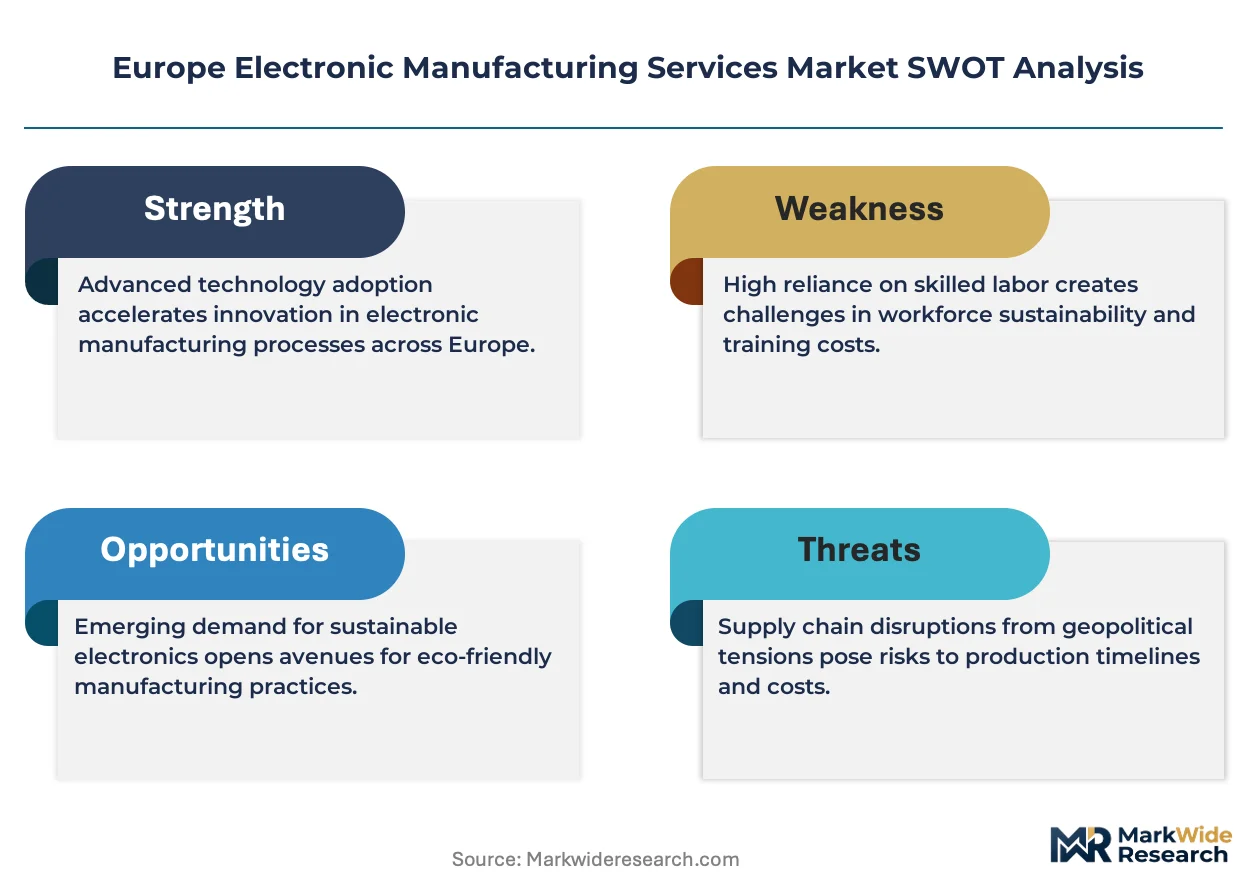
EMA, ECHA, and the EU AI Act collectively shape compliance burdens and qualification thresholds for EMS providers serving regulated European industries. REACH restrictions on substance composition and the F-Gas Regulation on process emissions directly influence material selection, soldering chemistry, and facility certification requirements across the value chain. The CSRD disclosure framework is extending accountability demands onto tier-one manufacturers, compelling EMS partners to document Scope 3 emissions and circularity metrics. Stakeholders must evaluate whether their supplier audit protocols adequately capture emerging ESG verification requirements before contract renewal cycles intensify competitive screening.
Market Dynamics
Modular system integration is consolidating buyer preference across European EMS engagements, as OEMs seek bundled design-to-manufacture partnerships rather than fragmented component sourcing. The EU Green Deal and CSRD disclosure framework are accelerating facility certification requirements and Scope 3 emissions documentation across the value chain.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation are accelerating demand for energy-efficient manufacturing processes and low-emission soldering chemistry across automotive and industrial verticals.
- Electric powertrain outsourcing:Automotive OEMs in Germany and France are expanding outsourced electronics production for electric powertrains, concentrating contract awards in Bavaria and Baden-Württemberg.
- Medical device premiumization:CE marking under the EU MDR and specialized cleanroom protocols elevate barriers to supplier entry, concentrating margin pools among qualified EMS providers serving diagnostic and therapeutic device manufacturers.
Market Restraints
- Specialized substrate volatility:Multilayer and flexible PCB substrate costs fluctuate with copper and epoxy resin supply disruptions, compressing margins for high-mix, low-volume contract manufacturers.
- REACH compliance friction:ECHA substance restrictions on soldering chemistry and flame retardants force continuous reformulation cycles, extending qualification timelines for new material introductions.
- Regional supply concentration:Germany's industrial corridor around Bavaria and Baden-Württemberg concentrates qualified EMS capacity, creating geographic single-source risk for just-in-time automotive programs.
Strategic Opportunities
- Nordic medical expansion:Sweden and Finland present underpenetrated demand for ruggedized industrial and medical electronics, leveraging existing Nordic engineering heritage and cleanroom infrastructure.
- Box Build integration:OEM outsourcing of complex electromechanical subsystems creates white space in integrated enclosure and cable harness assembly, shifting margin capture from component supply to system integration.
- CSRD-driven ESG verification:The CSRD disclosure framework compels tier-one manufacturers to document circularity metrics, creating qualification advantages for EMS partners with verified Scope 3 emissions tracking.
Industry Challenges
- IATF 16949 certification timelines:Automotive EMS contracts require IATF 16949 quality regime compliance, with audit cycles and corrective action periods extending 12-18 months for new facility qualifications.
- Legacy MES integration:Box Build complexity demands integration with customer manufacturing execution systems, creating friction where legacy ERP architectures lack standardized API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electronic Manufacturing Services Market |
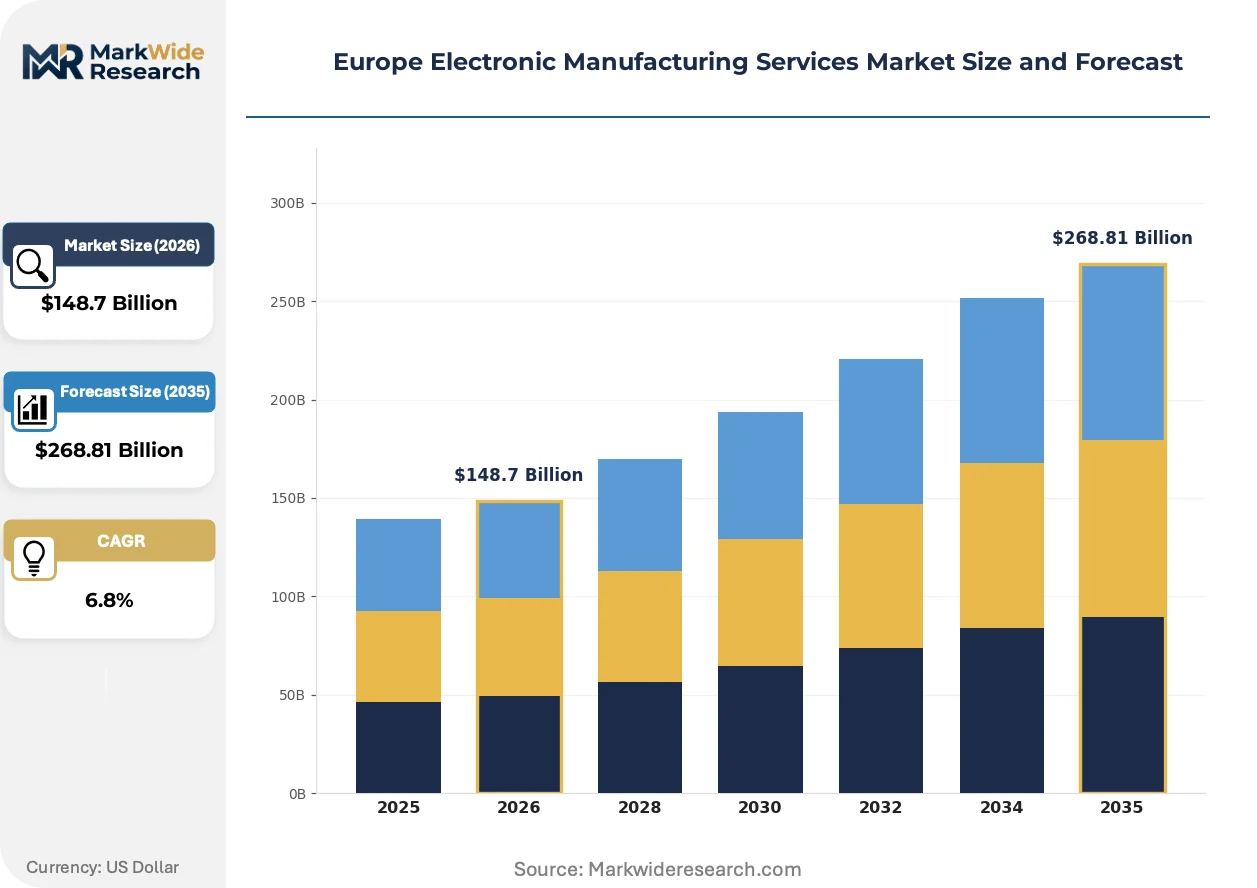
| Market Size in 2026 | $148.7 Billion |
| Market Size in 2035 | $268.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: PCB Assembly, Box Build, Testing, Prototyping Product Type: Consumer Electronics, Medical Devices, Industrial Equipment, Automotive Components End User: OEMs, Contract Manufacturers, System Integrators, Telecom Companies Technology: Surface Mount Technology, Through-Hole Technology, Hybrid Technology, Robotics |
| Companies Covered | Zollner Elektronik AG, Asteelflash Group, Foxconn Technology Group, Scanfil Oyj, NOTE AB, Flex Ltd., Enics AG, TT Electronics plc, Jabil Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electronic Manufacturing Services Market Trends and Innovations
Digital thread architecture is reshaping how European EMS providers manage design-to-manufacture handoffs, compressing NPI cycles and enabling real-time quality telemetry across distributed production networks.
Advanced SMT placement systems with AI-driven component recognition are consolidating process control in high-mix environments. Automotive and medical OEMs in Germany and France are deploying these systems at scale for electric powertrain and diagnostic device programs. The technology is consolidating defect detection upstream, reducing downstream functional testing burden and warranty exposure.
The EU AI Act imposes conformity assessment requirements on AI-enabled manufacturing equipment, forcing EMS providers to document algorithmic transparency and risk management protocols. Industrial automation and medical device segments face the steepest compliance gradients. German automotive programs are responding by segregating AI-driven inspection systems into standalone quality modules with auditable decision trails.
Buyer concentration around design-to-manufacture partnerships is displacing fragmented component sourcing contracts. Automotive OEMs in France and Germany now bundle PCB assembly, enclosure integration, and lifecycle management under single-supplier frameworks. This pattern is most visible in Bavaria, where Tier-1 suppliers have consolidated vendor panels from twelve to four qualified EMS partners since 2022.
Europe Electronic Manufacturing Services Market Segmentation
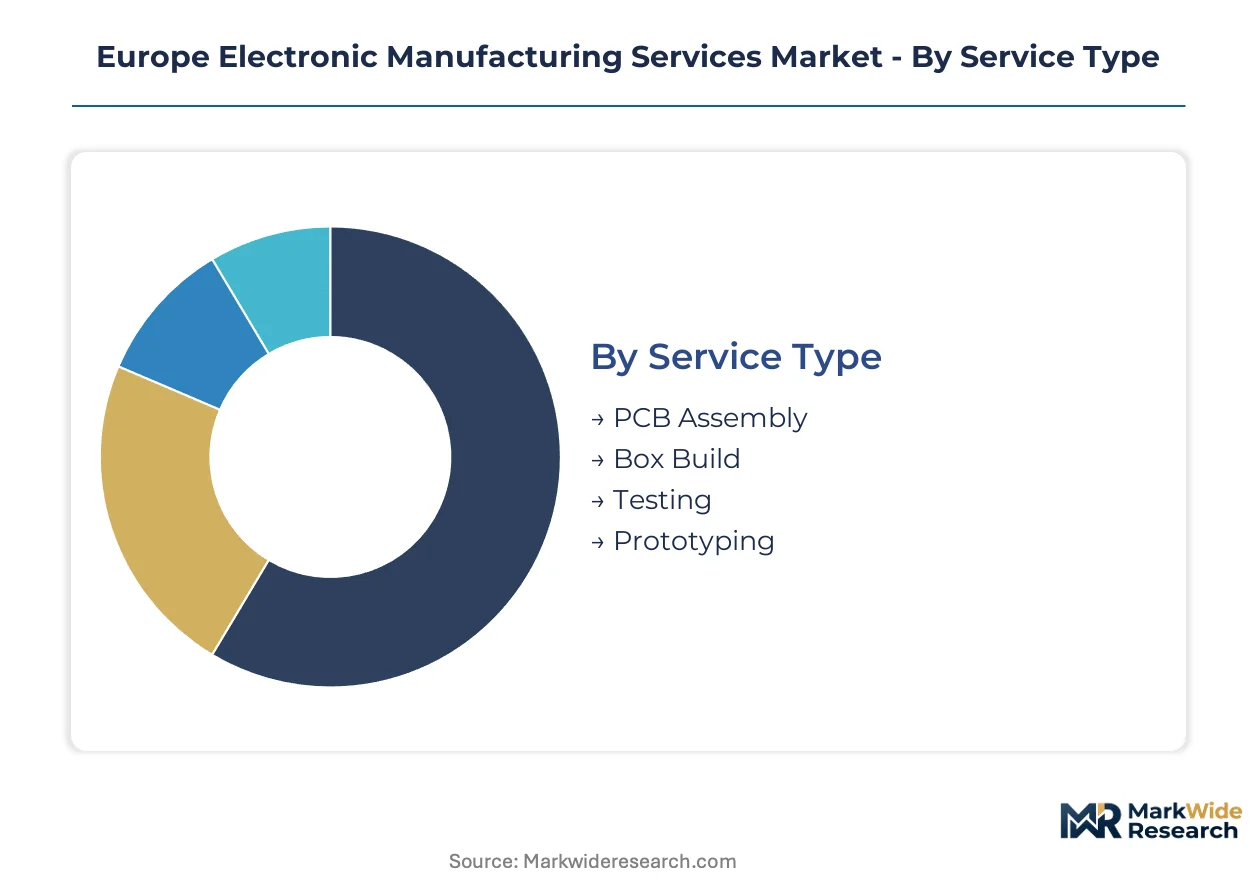
Segmentation in European EMS reveals how OEM procurement preferences diverge across technical complexity tiers and regulatory exposure levels. Contract structures vary sharply between high-volume automotive programs requiring IATF 16949 certification and medical engagements demanding EU MDR compliance with specialized cleanroom protocols.
Service Type:
Customization intensity spans from standardized PCB fabrication to fully bespoke system integration, with margin capture escalating along this spectrum.
- PCB Assembly:Multilayer and flexible circuit fabrication dominates revenue pools across automotive and medical verticals. German automotive OEMs in Bavaria concentrate demand here for electric powertrain modules, with REACH compliance on soldering chemistry extending qualification cycles.
- Box Build:Integrated enclosure assembly and cable harness integration commands premium positioning as OEMs outsource increasingly complex electromechanical subsystems. French and German Tier-1 suppliers have consolidated vendor panels toward single-source frameworks capturing full system integration.
- Testing:Functional verification and burn-in protocols serve ISO 13485 and IATF 16949 quality regimes.
- Prototyping:New product introduction cycles compress through digital thread architecture linking design to manufacture.
Leading the category by volume: PCB Assembly. Expanding most quickly: Box Build.
Product Type:
Margin stratification tracks regulatory burden, with certified medical and automotive segments commanding price premiums over consumer electronics.
- Medical Devices:CE marking under EU MDR and cleanroom protocols elevate supplier entry barriers, concentrating margin pools among qualified EMS providers serving diagnostic and therapeutic manufacturers. Nordic engineering heritage supports ruggedized device production for Swedish and Finnish healthcare technology firms.
- Automotive Components:Electric powertrain electronics drive outsourcing expansion among German and French OEMs, with production concentrating in Baden-Württemberg industrial corridors for just-in-time delivery.
- Industrial Equipment:Automation controllers and sensor modules serve factory modernization programs.
- Consumer Electronics:Standardized assembly faces margin compression from substrate cost volatility.
Highest margin capture: Medical Devices. Steepest volume growth: Automotive Components.
End User:
Procurement scale and technical integration depth separate enterprise OEM engagements from intermediary distribution channels.
- OEMs:Direct relationships dominate high-complexity programs, with German automotive and French medical device manufacturers bundling design-to-manufacture partnerships under consolidated supplier frameworks.
- System Integrators:Intermediate demand aggregation serves industrial automation and telecommunications infrastructure deployment.
- Contract Manufacturers:Secondary outsourcing layers handle overflow capacity and geographic redundancy.
- Telecom Companies:Network equipment assembly follows standardized specifications with volume scale economics.
Deepest technical integration: OEMs. Fastest procurement expansion: System Integrators.
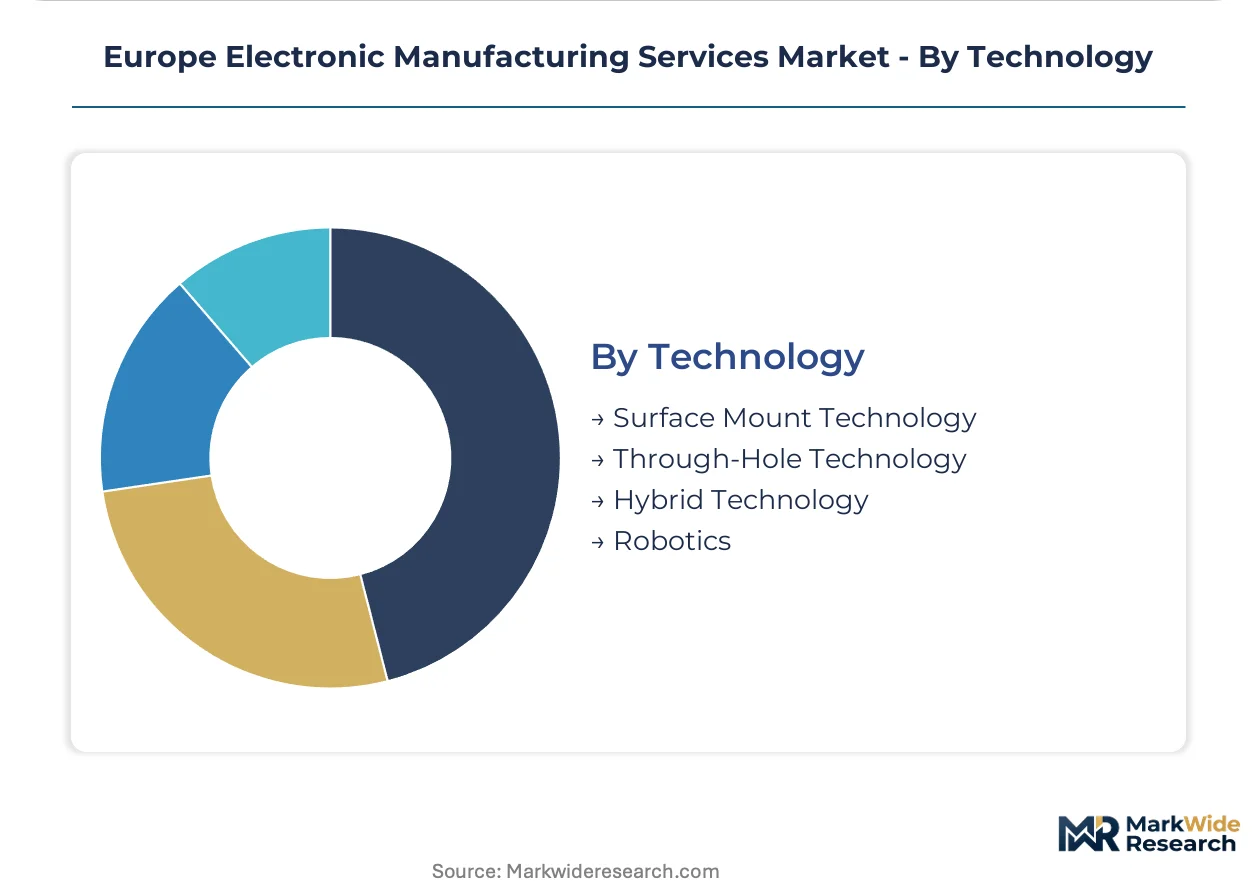
Technology:
Process sophistication and capital intensity differentiate placement accuracy capabilities across European facility networks.
- Surface Mount Technology:AI-driven component recognition systems consolidate defect detection upstream in high-mix environments, with German automotive and medical OEMs deploying these at scale for electric powertrain and diagnostic programs.
- Robotics:Automated material handling and precision assembly reduce labor cost exposure while improving repeatability metrics for cleanroom medical production.
- Through-Hole Technology:Legacy connector and power component mounting persists in industrial and automotive applications.
- Hybrid Technology:Mixed SMT and through-hole processes accommodate specialized component form factors.
Widest deployment base: Surface Mount Technology. Fastest capability investment: Robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany's industrial corridor while demand spreads across automotive and medical clusters in France, the Nordics, and Central Europe. The EU Green Deal and CSRD framework are reshaping facility certification requirements across manufacturing networks.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are expanding outsourced electronics production for electric powertrains. The KBA enforces IATF 16949 compliance timelines that extend 12-18 months for new facility qualifications. Stuttgart anchors high-mix, low-volume contract manufacturing for Tier-1 automotive suppliers.
France
Medical device manufacturers in Île-de-France are consolidating vendor panels toward single-source design-to-manufacture frameworks. ANSM oversees CE marking under the EU MDR for diagnostic and therapeutic electronics. The Paris-Saclay cluster attracts EMS investment for cleanroom-certified production.
Sweden
Industrial automation OEMs are sourcing ruggedized electronics for factory modernization programs. The Swedish Medical Products Agency aligns with EU MDR protocols for healthcare technology exports. Stockholm-Uppsala hosts engineering-intensive EMS operations serving Nordic medical device firms.
Finland
Therapeutic device manufacturers are qualifying EMS partners for specialized cleanroom protocols under EU MDR. Fimea regulates medical electronics certification for export markets. The Helsinki-Espoo corridor leverages Nordic engineering heritage for diagnostic equipment production.
Italy
Industrial equipment OEMs in Lombardy are outsourcing automation controllers and sensor modules. REACH restrictions from ECHA force continuous reformulation cycles for soldering chemistry in PCB assembly. Milan-Turin hosts mid-scale EMS facilities serving European industrial automation demand.
Europe Electronic Manufacturing Services Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with pan-European facility networks. Tier-1 automotive and medical OEMs have consolidated vendor panels from twelve to four qualified partners since 2022. Three archetypes dominate: German-speaking high-mix specialists, Nordic engineering-centric providers, and global scale operators with regional European footprints. M&A activity targets box-build capabilities while strategic partnerships address CSRD-driven ESG verification requirements.
Among German-speaking fabricators, Zollner Elektronik AG exemplifies vertical manufacturing depth for high-mix, low-volume contracts. Asteelflash Group occupies a position within the pan-European network archetype, sustaining proximity advantages for just-in-time programs. Scanfil Oyj anchors the Nordic engineering heritage tier, representing specialization in ruggedized industrial and medical electronics.
| Leading Market Players |
|---|
| Zollner Elektronik AG |
| Asteelflash Group |
| Foxconn Technology Group |
| Scanfil Oyj |
| NOTE AB |
| Flex Ltd. |
| Enics AG |
| TT Electronics plc |
| Jabil Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into PCB substrate fabrication anchors supply position and pricing power for European EMS providers serving IATF 16949 automotive programs. Zollner Elektronik AG and Asteelflash Group leverage captive multilayer circuit production to buffer margin erosion from copper and epoxy resin volatility, while Tier-1 OEM procurement panels reward this integration with preferential contract terms.
Pricing Analysis
Margin tightening in high-mix, low-volume tiers traces to REACH-mandated soldering chemistry reformulation cycles extending qualification timelines. Contract-based long-term offtake agreements dominate automotive engagements, with price differentiation separating IATF 16949-certified facilities from standard industrial assembly. Certification level and volume scale drive tiering, with Bavarian automotive OEMs least price-sensitive due to just-in-time dependency, while consumer electronics buyers face acute cost compression.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and French automotive manufacturers, with distribution running through consolidated vendor panels reduced from twelve to four qualified partners since 2022. Raw material flows draw from Germany, China, and Taiwan for multilayer substrates, semiconductor components, and precision connectors. Single-source vulnerability concentrates in Baden-Württemberg's industrial corridor, where qualified cleanroom capacity for EU MDR medical production remains geographically constrained.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European EMS is consolidating around a vertical-integration race, with box-build capabilities and Scope 3 emissions documentation emerging as the decisive downstream and upstream levers for contract capture.
For Market Incumbents: To counter vendor panel consolidation by Tier-1 automotive OEMs, deepen backward integration into cable harness and enclosure assembly while accelerating CSRD-compliant emissions tracking infrastructure. Prioritize IATF 16949 certification maintenance across existing facilities to defend qualification status during contract renewal cycles. For New Entrants and Emerging Players: Begin with underpenetrated Nordic medical device production, where ruggedized electronics demand outpaces qualified cleanroom capacity in Sweden and Finland. Target diagnostic equipment manufacturers in the Stockholm-Uppsala corridor with EU MDR-compliant prototyping services as the initial go-to-market wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale box-build specialists with verified automotive qualifications. Long-term viability hinges on facility networks spanning multiple European regulatory jurisdictions. Monitor REACH substance restriction announcements as the critical inflection signal for material reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Box Build Capability Acquisition | Captures margin migration from component supply to integrated electromechanical subsystem assembly for automotive OEMs. |
| CSRD Emissions Verification Infrastructure | Qualifies Tier-1 supplier status under EU disclosure frameworks mandating Scope 3 documentation. |
| IATF 16949 Certification Expansion | Opens Bavaria and Baden-Württemberg electric powertrain contract pools with 12-18 month audit timelines. |
| Nordic Medical Cleanroom Investment | Addresses diagnostic device demand in Sweden and Finland where qualified capacity remains constrained. |
| AI-Driven SMT Placement Deployment | Consolidates defect detection upstream for German automotive and medical OEMs under EU AI Act conformity requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with EMS procurement directors, Tier-1 automotive supplier quality managers, medical device regulatory affairs leads, and ECHA compliance officers validated segment assumptions. Bottom-up facility capacity assessments combined with top-down OEM outsourcing spend estimates across the analysis window.
Data-stream reconciliation integrated production volume databases with contract award tracking and certification registry analysis. Segmentation dimensions spanned service type, product category, end-user archetype, and technology tier across the projection horizon. CAGRs derived from facility utilization rates, OEM outsourcing ratio trends, and regulatory compliance cost trajectories specific to REACH and EU MDR implementation.
Underlying measurement precision varies by segment; automotive and medical device categories carry tighter precision than consumer electronics given consolidated buyer concentration. Forecasts reflect assumptions around electric powertrain outsourcing acceleration and CSRD disclosure timeline adherence. Periodic stress-testing of base assumptions is recommended given substrate cost volatility and regulatory amendment risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market