
 PCB Photoresist Market | 2026-2036
PCB Photoresist Market Size, Share, and Industry Trends Forecast 2026-2036
PCB Photoresist Market Intelligence
Capital-intensity divergence between integrated resist suppliers and specialty chemical houses is bifurcating competitive tiers. DuPont leverages captive monomer synthesis and resin production to sustain margin capture across the photoresist stack. JSR Corporation anchors its position through deep R&D spending on ArF and EUV-adjacent polymer platforms. Tokyo Ohka Kogyo competes via geographic dominance in East Asian PCB fabrication clusters.
PCB photoresist denotes a photosensitive polymer formulation—typically comprising a resin, photoactive compound, and solvent—designed to undergo selective solubility change upon patterned UV or laser exposure, enabling precise copper trace definition in multilayer board fabrication. Dry film photoresist dominates volume in high-throughput rigid board manufacturing where lamination speed and thickness uniformity matter, while liquid photoresist captures precision applications in advanced HDI and flexible circuits. UV exposure technology leads installed equipment bases, though laser direct imaging is displacing conventional mask alignment in prototype and quick-turn PCB operations.
REACH registration requirements and RoHS substance restrictions in Europe compel reformulation of legacy diazonaphthoquinone systems toward halogen-free, low-toxicity alternatives. China's GB standards and NMPA chemical control frameworks impose parallel compliance burdens on imported and domestically produced resist materials. Japan's METI chemical management protocols add a third regulatory layer for suppliers serving automotive and telecommunications end users. Stakeholders must monitor convergence between semiconductor-grade resist purity benchmarks and PCB-grade cost structures as substrate complexity escalates.
Market Dynamics
Photoresist formulation chemistry is splitting into two parallel tracks as HDI substrate complexity forces purity upgrades while commodity rigid boards resist cost inflation. This bifurcation is reshaping R&D allocation across the supplier base.
Growth Catalysts
- 5G base station deployment:Massive MIMO antenna arrays require ultra-fine line width control, pulling high-resolution dry film formulations into telecommunications PCB stacks.
- China's dual carbon goals:Domestic fab expansion under MIIT industrial policy is localizing photoresist supply chains to reduce import dependency for strategic electronics materials.
- Laser direct imaging:LDI systems eliminate photomask costs and reduce turnaround time, accelerating adoption in quick-turn prototype shops serving automotive electronics development cycles.
Market Restraints
- Monomer supply concentration:Specialty epoxy and acrylic resin precursors concentrate among Japanese and Korean chemical houses, exposing formulators to feedstock allocation risk.
- REACH registration costs:ECHA compliance burdens for novel photoactive compounds exceed development budgets for mid-tier European resist suppliers, freezing product pipelines.
- Technical resolution ceiling:Conventional UV-curable systems face hard limits below 5-micron feature sizes, constraining penetration into semiconductor packaging substrates.
Strategic Opportunities
- India PCB manufacturing:PLI scheme incentives for electronics manufacturing are attracting greenfield fab investments that will require localized photoresist supply partnerships.
- Halogen-free mandate expansion:RoHS substance restrictions are spreading beyond Europe into Middle Eastern and Southeast Asian import standards, creating first-mover advantage for compliant formulations.
- AI-driven process control:Machine vision integration with exposure equipment is decomposing the traditional resist-expose-develop workflow into real-time adaptive loops.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in photochemistry and polymer rheology is retiring faster than universities produce replacements, compressing R&D throughput.
- Cleanroom capex requirements:Semiconductor-grade purity specifications demand ISO Class 5 manufacturing environments that obsolete legacy PCB-grade production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCB Photoresist Market |
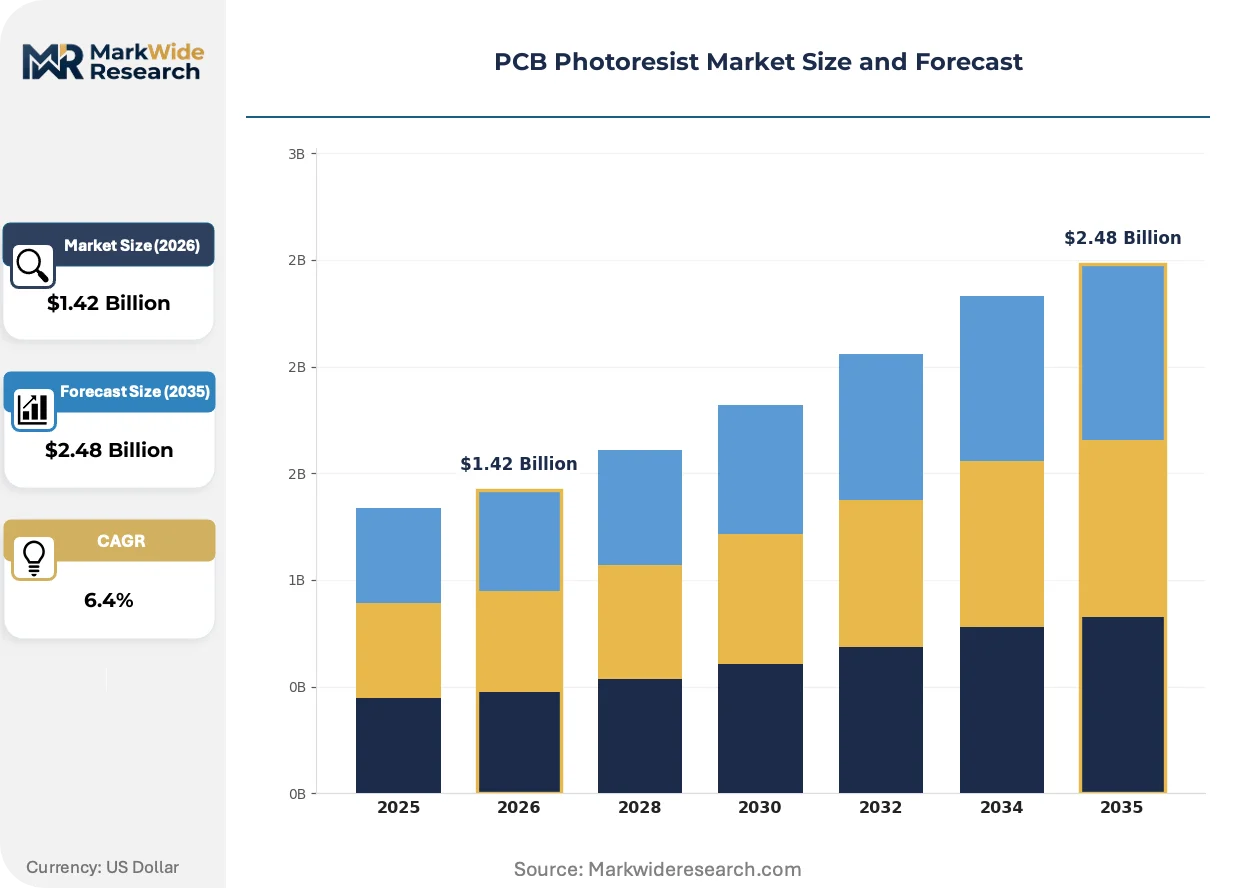
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Dry Film Photoresist, Liquid Photoresist Application: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment End User: OEMs, Contract Manufacturers, PCB Manufacturers, Research Laboratories Technology: UV Exposure, Laser Exposure, Electron Beam Exposure, X-ray Exposure |
| Companies Covered | DuPont, JSR Corporation, Tokyo Ohka Kogyo, Shin-Etsu Chemical, Fujifilm Electronic Materials, Merck Group, Sumitomo Chemical, LG Chem, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCB Photoresist Market Strategic Shifts & Innovations
Process integration and materials purity are converging as substrate complexity erodes the traditional boundaries between PCB fabrication and semiconductor packaging. Equipment vendors and chemical suppliers are co-developing solutions rather than selling discrete components.
Laser direct imaging technology is decomposing the conventional photomask-based exposure workflow in high-mix PCB operations. Quick-turn prototype shops in Germany and Taiwan are retrofitting LDI modules onto existing coating lines to eliminate tooling costs and compress delivery schedules. This displacement is compressing demand for chromium photomask blanks and the emulsion resist systems that coat them.
REACH authorization requirements are forcing reformulation of legacy diazonaphthoquinone photoinitiators across European supply chains. ECHA's sunset date enforcement is accelerating substitution with sulfonium salt and iodonium salt alternatives that carry higher raw material costs. Automotive PCB suppliers serving German OEMs are absorbing margin compression to maintain CE marking compliance and avoid supply disruption penalties.
Consolidated procurement contracts are displacing spot purchasing in high-volume PCB fabrication. Tier-one electronics manufacturing services in China are negotiating multi-year photoresist supply agreements with volume commitments and technical service bundling. This shift is squeezing smaller domestic Chinese resist distributors who lack formulation expertise to support direct mill integration.
PCB Photoresist Market Segmentation
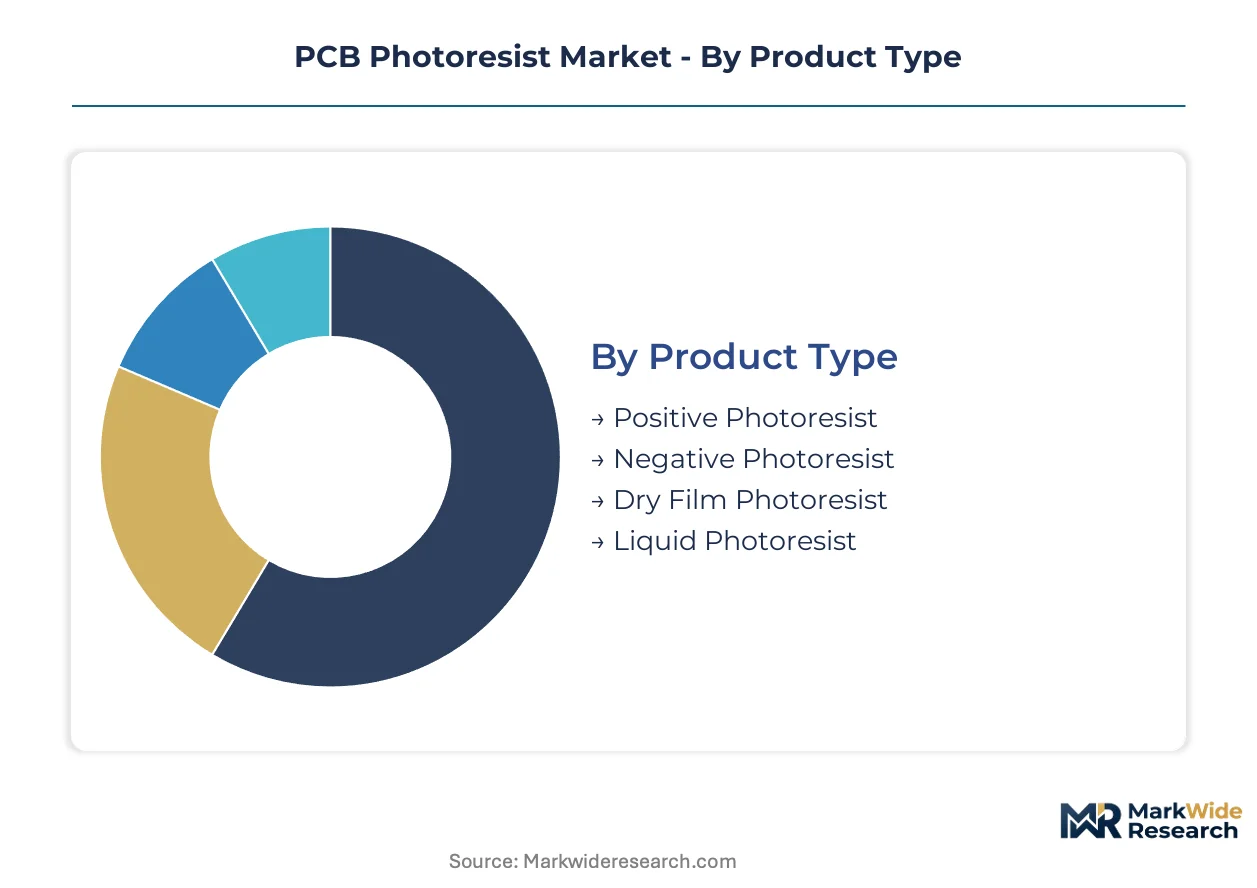
PCB photoresist segmentation reveals how formulation chemistry, exposure technology, and end-use specifications create distinct commercial battlegrounds. Each dimension carries different margin structures, regulatory burdens, and customer concentration patterns that reshape supplier strategy.
Product Type:
REACH and RoHS compliance timelines in Europe are forcing divergent reformulation investments across photoresist chemistries, with halogen-free mandates hitting negative-tone systems hardest.
- Dry Film Photoresist:Laminated polymer sheets combine epoxy or acrylic binders with diazonaphthoquinone photoinitiators in controlled thickness layers. Massive MIMO antenna arrays for 5G telecommunications infrastructure in China and South Korea are pulling high-resolution dry film formulations into multilayer rigid board stacks. ECHA's sunset date enforcement for legacy photoinitiators is accelerating substitution costs for European suppliers.
- Liquid Photoresist:Spin- or spray-applied formulations enable sub-10-micron feature control for flexible circuit and advanced HDI substrates. Quick-turn prototype shops in Taiwan and Germany favor liquid systems for laser direct imaging retrofit compatibility. METI chemical management protocols in Japan add purity documentation burdens for automotive electronics suppliers.
- Positive Photoresist:Diazo-based systems dominate legacy UV exposure lines with straightforward aqueous development.
- Negative Photoresist:Cross-linking chemistries resist solvent attack, suiting chemical milling and etch-resistant applications.
Dry film photoresist handles the majority of throughput; liquid photoresist is gaining share fastest in advanced packaging crossover applications.
Application:
Cost tier stratification separates commodity rigid board demand from premium HDI and flexible circuit specifications.
- Telecommunications:Base station and data center infrastructure demands ultra-fine line width control below 25 microns for high-frequency signal integrity. China's MIIT industrial policy is localizing supply chains for strategic 5G equipment, concentrating demand among domestic PCB fabricators in Shenzhen and Suzhou clusters.
- Automotive:ADAS sensor modules and power electronics require thermal stability and halogen-free certification for German OEM supply chains. CE marking compliance and KBA type approval processes in Germany are absorbing margin compression to avoid supply disruption penalties.
- Consumer Electronics:Smartphone and wearable devices drive flexible circuit demand with tight bend-radius specifications.
- Industrial Equipment:Motor drives and power supplies tolerate thicker copper traces with less stringent resolution requirements.
Telecommunications commands the largest absolute volume; automotive represents the steepest expansion trajectory as electrification multiplies board content per vehicle.
End User:
Procurement concentration patterns split between consolidated mill-direct contracts and fragmented distributor relationships.
- PCB Manufacturers:Tier-one fabricators in China's Pearl River Delta negotiate multi-year supply agreements with volume commitments and technical service bundling. Consolidated procurement is squeezing smaller domestic distributors who lack formulation expertise to support direct mill integration.
- Contract Manufacturers:Foxconn and Jabil-scale EMS providers specify resist systems across their supplier networks, creating specification lock-in effects. India's PLI scheme incentives are attracting greenfield fab investments that will require localized photoresist supply partnerships.
- OEMs:Original equipment manufacturers in aerospace and medical devices impose custom qualification protocols.
- Research Laboratories:University and corporate R&D facilities drive small-batch demand for experimental formulations.
PCB manufacturers absorb the dominant share of volume; contract manufacturers are expanding most quickly as EMS consolidation accelerates.
Technology:
Equipment installed base and capital replacement cycles determine exposure technology adoption curves.
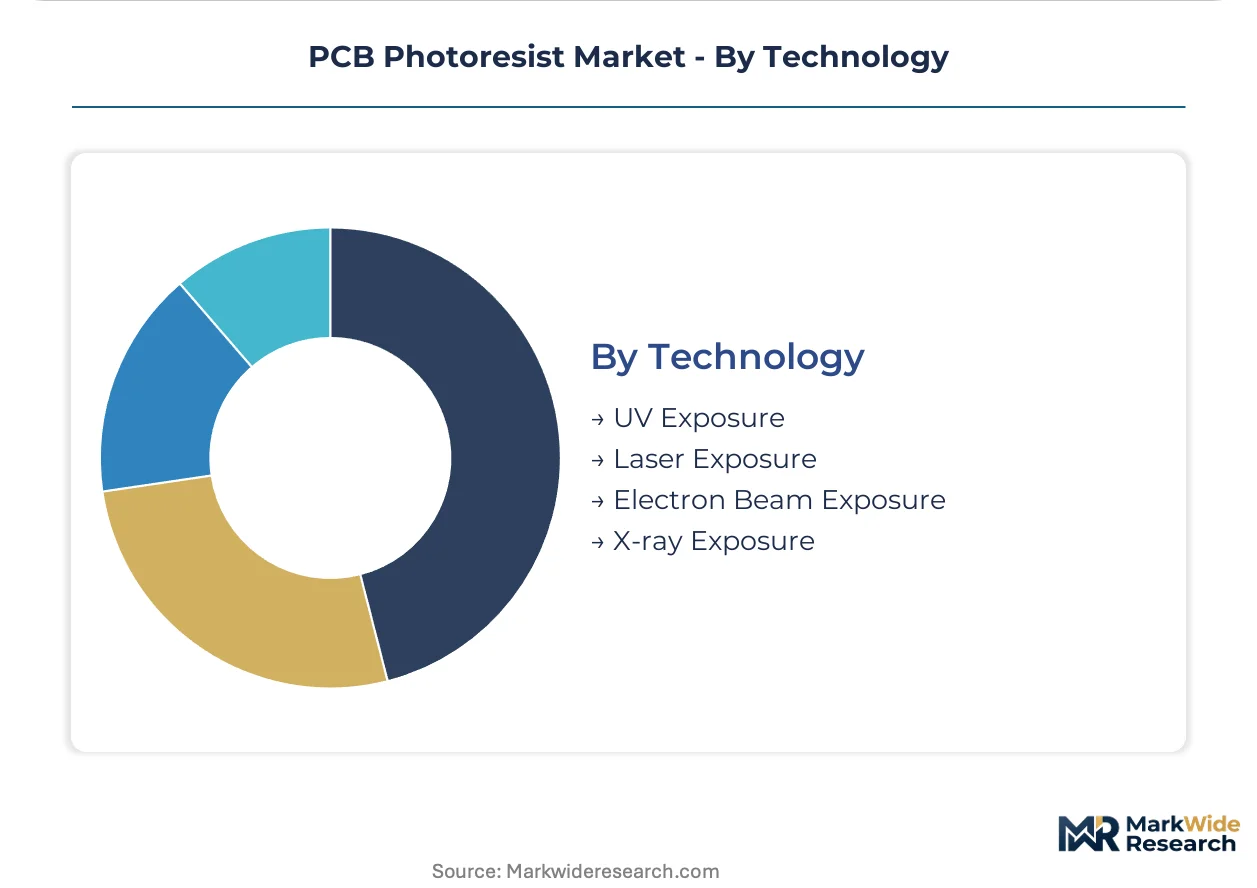
- UV Exposure:Mercury lamp and LED-based systems dominate installed equipment bases with mature mask-alignment workflows. High-volume rigid board facilities in China retain UV lines for throughput economics despite resolution limitations.
- Laser Direct Imaging:Diode-pumped solid-state and UV laser systems eliminate photomask costs and compress turnaround times. Quick-turn prototype shops in Germany and Taiwan are retrofitting LDI modules onto existing coating lines, displacing demand for chromium photomask blanks.
- Electron Beam Exposure:Maskless patterning achieves sub-micron resolution for semiconductor packaging substrates.
- X-ray Exposure:Synchrotron and compact source systems serve specialized MEMS and thick-film applications.
UV exposure retains the largest installed base; laser direct imaging is climbing the fastest on new equipment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: China deploys photoresist predominantly in high-volume rigid board fabrication, while Germany and Japan concentrate demand in automotive-grade HDI substrates requiring halogen-free certification.
China
Domestic PCB output dominates global volume, with MIIT industrial policy accelerating localization of photoresist supply chains under dual carbon goals. GB standards and NMPA chemical control frameworks impose compliance burdens on both imported and domestically produced materials. Shenzhen and Suzhou clusters concentrate demand from 5G telecommunications infrastructure fabricators.
Germany
Automotive electronics suppliers absorb premium photoresist volumes for ADAS sensor modules and power electronics. REACH authorization and RoHS substance restrictions enforced by ECHA and KBA type approval processes compel reformulation toward halogen-free alternatives. Bavaria-based fabricators serving German OEMs absorb margin compression to maintain CE marking compliance.
Japan
METI chemical management protocols add purity documentation burdens for suppliers serving automotive and telecommunications end users. Deep R&D spending on ArF and EUV-adjacent polymer platforms anchors supplier positioning. Tokyo-Ohka-Kogyo's geographic dominance in East Asian fabrication clusters reinforces domestic supply security.
South Korea
Massive MIMO antenna arrays for 5G infrastructure pull high-resolution dry film formulations into multilayer rigid board stacks. Specialty epoxy and acrylic resin precursors concentrate among domestic chemical houses, exposing formulators to feedstock allocation risk. Seoul Capital Area fabrication clusters drive technical specification setting.
United States
Quick-turn prototype shops retrofit laser direct imaging modules onto existing coating lines to eliminate tooling costs and compress delivery schedules. EPA and OSHA frameworks govern chemical handling, though federal semiconductor policy increasingly influences PCB-grade material sourcing. Greater Boston and Pacific Northwest R&D facilities drive experimental formulation demand.
PCB Photoresist Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence bifurcating competitive positioning. Integrated resist suppliers command margin capture across the photoresist stack through captive monomer synthesis, while specialty chemical houses compete via formulation expertise and geographic proximity to fabrication clusters. Two dominant competitive moves define current dynamics: multi-year supply agreements with volume commitments and technical service bundling, and co-development partnerships between equipment vendors and chemical suppliers.
Within the integrated leader tier, DuPont and JSR Corporation exemplify contrasting strategic anchors: DuPont leverages backward integration into resin production, while JSR Corporation occupies a position defined by deep R&D spending on advanced polymer platforms. Tokyo Ohka Kogyo sits within the geographic dominance archetype, anchoring supplier presence in East Asian fabrication clusters. These three companies represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| DuPont |
| JSR Corporation |
| Tokyo Ohka Kogyo |
| Shin-Etsu Chemical |
| Fujifilm Electronic Materials |
| Merck Group |
| Sumitomo Chemical |
| LG Chem |
| Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
REACH sunset date enforcement gates both supplier qualification and price differentiation simultaneously, forcing European formulators to absorb reformulation costs while Asian competitors capture margin on legacy chemistries. Buyers in automotive and telecommunications segments face tiered certification requirements that stratify pricing across halogen-free and conventional formulations.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-one PCB fabricators and integrated resist suppliers, compressing spot market liquidity for mid-tier distributors. Three-tier pricing structure across premium, standard, and economy levels reflects purity grade, volume scale, and technical service bundling. Pricing pressure stems from REACH registration cost absorption by European suppliers serving German automotive OEMs. Contract manufacturers exhibit highest price sensitivity due to consolidated procurement mandates, while research laboratories tolerate premium pricing for experimental formulations.
Supply Chain Analysis
Inventory buffers for specialty epoxy and acrylic resin precursors stretch lead times when Japanese and Korean chemical houses allocate feedstock to semiconductor-grade customers. Geographic supply concentration centers on China, Japan, and South Korea, with formulation expertise clustering in East Asian fabrication hubs. Raw material dependencies draw from diazonaphthoquinone photoinitiators, sulfonium salt alternatives, and captive monomer synthesis streams. Single-source vulnerability concentrates in Japanese resin precursor suppliers. Distribution runs through mill-direct contracts with technical service integration, squeezing independent distributors lacking formulation support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement among tier-one electronics manufacturing services has shifted buyer power toward specification lock-in, fragmenting smaller distributors who cannot support direct mill integration with technical expertise.
For Market Incumbents: Shield margin capture through captive monomer synthesis and resin production, mirroring DuPont's backward integration model. Accelerate halogen-free formulation R&D to preempt ECHA sunset date enforcement. Defend against laser direct imaging displacement by co-developing resist-exposure equipment bundles with LDI vendors. For New Entrants and Emerging Players: Anchor in India's PLI scheme electronics manufacturing incentives, where greenfield fab investments lack localized photoresist supply partnerships. Target quick-turn prototype shops in Germany and Taiwan retrofitting LDI modules, as these buyers prioritize turnaround speed over incumbent brand loyalty. Pursue technical service bundling as primary go-to-market angle. For Investors and Strategic Acquirers: ECHA's sunset date enforcement for diazonaphthoquinone photoinitiators reshapes the acquisition landscape toward compliant formulation capabilities. Five-to-ten year viability favors suppliers with REACH-registered halogen-free chemistries and MIIT policy alignment in China. Target acquisition archetype: regional formulators with automotive certification and direct mill relationships. Watch for feedstock allocation disruptions from Japanese and Korean resin precursor suppliers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive resin production secures margin capture across the photoresist stack for integrated suppliers. |
| Halogen-Free Formulation Transition | REACH and RoHS compliance creates first-mover advantage in European automotive supply chains. |
| Laser Direct Imaging Co-Development | Equipment-chemical partnerships decompose traditional resist-expose-develop workflows into adaptive loops. |
| India Localization Partnership | PLI scheme greenfield fabs require domestic photoresist supply to reduce import dependency. |
| Multi-Year Supply Agreement with Volume Commitments | Consolidated procurement contracts squeeze spot-market distributors lacking technical service capabilities. |
Research Approach
The analysis maps dry film photoresist, liquid photoresist, positive tone systems, and negative tone systems, each validated through formulation chemists, PCB fabrication plant managers, procurement leads at tier-one EMS providers, and distribution channel partners. Primary interviews triangulate with secondary sources including customs and trade data, MIIT industrial policy filings, ECHA registration databases, and SEC 10-K disclosures from integrated chemical suppliers. Bottom-up volume estimates cross-check against top-down market sizing across the analysis window.
Consistency checks validate outputs against external benchmarks for segment-level growth trajectories. The analytical framework models product type, application, end user, and exposure technology dimensions throughout the forecast period. CAGRs derive from regression analysis of historical shipment data and elasticity estimates for 5G infrastructure deployment and automotive electrification content expansion. Industry-specific inputs include laser direct imaging adoption curves and REACH reformulation cost schedules.
Material uncertainties — feedstock allocation disruptions, regulatory timeline shifts, and technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about policy continuity and equipment replacement cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market