
 Wet Based Wafer Cleaning Equipment Market | 2026-2036
Wet Based Wafer Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Based Wafer Cleaning Equipment Market Analytics
Aftermarket service revenue is narrowing as original equipment manufacturers pull refurbishment and consumables management in-house. SCREEN Holdings Co., Ltd. leverages its installed base in single-wafer spray tools to capture recurring parts revenue. Applied Materials, Inc. sustains a broad process equipment portfolio that bundles cleaning with deposition and etch platforms. Lam Research Corporation dominates plasma-assisted cleaning modules through tight integration with its etch product lines.
Wet based wafer cleaning equipment refers to systems that remove particulate, metallic, and organic contaminants from semiconductor wafers using liquid chemistries, typically operating at temperatures between 20°C and 180°C with megasonic or spray nozzle delivery to achieve surface cleanliness below 10¹⁰ atoms/cm². Single wafer platforms lead in advanced node fabrication where cross-contamination risks prohibit batch processing, while batch wafer systems retain cost advantages for mature nodes and photovoltaides applications. Chemical cleaning technology anchors the largest installed base, though megasonic cleaning is displacing conventional methods in critical front-end-of-line steps where finer particle removal thresholds apply.
EPA effluent guidelines in the United States restrict perfluorinated compound discharge from semiconductor wet benches, while REACH in Europe mandates substitution of hazardous solvents in cleaning formulations. China's MEE enforces wastewater treatment standards that elevate capital requirements for new fabs in the Yangtze River Delta. Japan's METI coordinates JIS standards for ultrapure water systems that feed directly into cleaning tool specifications. Stakeholders must monitor how regional chemical restriction timelines reshape equipment chemistry compatibility requirements and spare parts inventories across their installed bases.
Market Dynamics
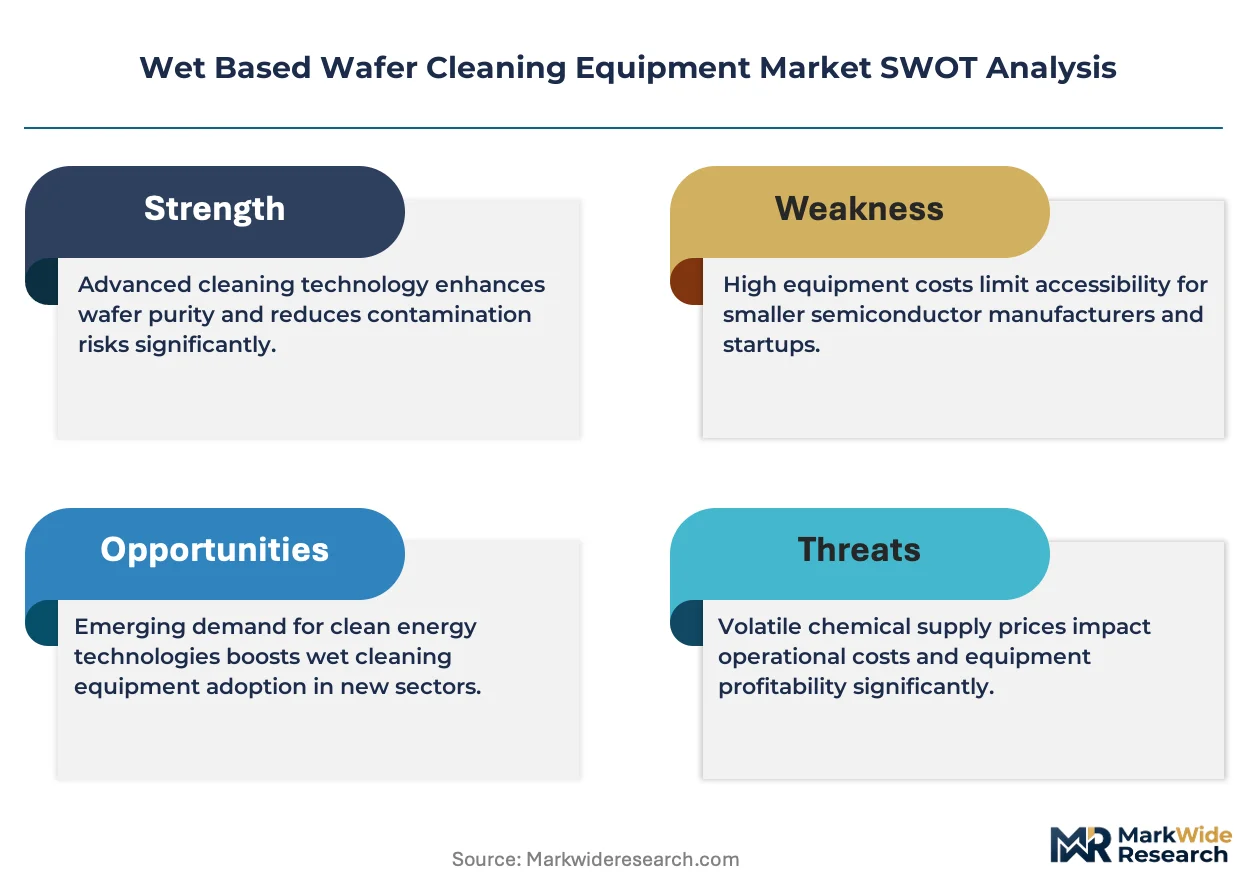
Node shrinkage below 7nm is collapsing particle tolerance thresholds, forcing single-wafer spray architectures to displace batch immersion systems in logic foundry capex plans across Taiwan and South Korea.
Growth Catalysts
- Sub-7nm node expansion:Advanced logic foundries in Taiwan and South Korea are scaling capacity for 3nm and 2nm processes, mandating single-wafer cleaning platforms that eliminate cross-wafer contamination risks inherent to batch processing.
- REACH chemical substitution mandates:ECHA's restrictions on perfluorinated solvents and N-methyl-2-pyrrolidone are accelerating equipment retrofits compatible with aqueous and supercritical CO2 alternatives.
- Photovoltaics capacity buildouts:Solar cell manufacturers in Malaysia and Vietnam are adopting batch wet benches for silicon wafer texturing, extending equipment utilization beyond semiconductor front-end applications.
Market Restraints
- High-purity chemical supply concentration:Ultrapure hydrogen peroxide and hydrofluoric acid production clusters in Japan and Germany expose fabs to input cost volatility and maritime logistics disruptions.
- EPA effluent compliance burden:US semiconductor facilities face capital-intensive wastewater treatment upgrades to meet perfluorinated compound discharge limits, extending project approval timelines.
- Technical limitation in 3D architectures:Conventional megasonic cleaning generates cavitation damage in high-aspect-ratio finFET and gate-all-around structures, constraining process window flexibility.
Strategic Opportunities
- India's semiconductor subsidy program:The country's PLI scheme and designated fab incentives in Gujarat and Karnataka are attracting first-mover equipment vendors to establish local service infrastructure.
- Carbon-neutral chemistry convergence:Supercritical CO2 cleaning modules combined with closed-loop solvent recovery systems align with China's dual carbon goals and Europe's CSRD reporting requirements.
- Direct-to-fab consumables logistics:Chemical management as-a-service models bypass traditional distributor networks, capturing recurring revenue through real-time inventory monitoring at Hsinchu and Pyeongtaek clusters.
Industry Challenges
- Process engineer scarcity:Expertise in megasonic frequency optimization and chemistry-surface interaction modeling concentrates among veteran technicians at SCREEN and Tokyo Electron alumni networks.
- Legacy tool integration complexity:Brownfield fabs in Japan and the United States face mechanical interface mismatches when retrofitting 200mm batch systems with single-wafer spray modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Based Wafer Cleaning Equipment Market |
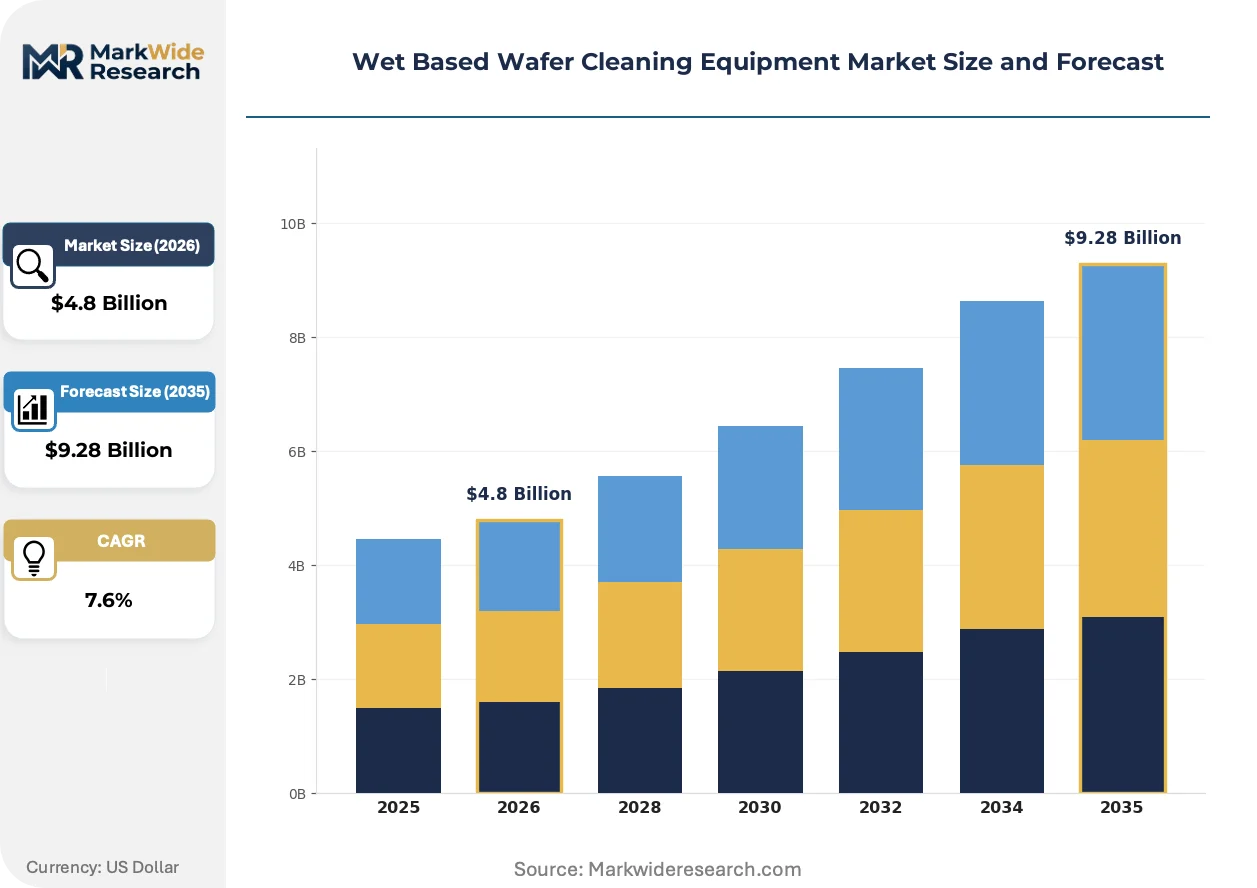
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wafer, Batch Wafer, Inline Wafer, Customized Solutions Technology: Megasonic Cleaning, Cold Cleaning, Chemical Cleaning, Plasma Cleaning Application: MEMS, Photovoltaics, Semiconductor Fabrication, R&D End User: Foundries, IDMs, Research Institutes, Third-Party Service Providers |
| Companies Covered | SCREEN Holdings Co., Ltd., Applied Materials, Inc., Lam Research Corporation, Tokyo Electron Limited, ACM Research, Shibaura Mechatronics Corporation, Veeco Instruments Inc., Modutek Corporation, Akrion Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Based Wafer Cleaning Equipment Market Evolving Landscape
Equipment architectures are converging around closed-loop chemical recovery and in-situ metrology integration, compressing both operating expenditure and process control variance for high-volume manufacturers.
Megasonic cleaning with frequency-agile transducer arrays is collapsing the distinction between particle removal efficiency and surface damage prevention. Taiwan-based logic foundries are adopting 1-3 MHz sweep-mode systems for sub-20nm particle clearance on cobalt and ruthenium interconnect layers. This frequency modulation capability is collapsing the need for separate pre-clean and post-clean process steps, reducing tool footprint requirements by consolidating unit operations.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and perfluorooctanoic acid derivatives are forcing formulation overhauls across European semiconductor supply chains. Equipment vendors must recertify seal materials and pump compatibilities for aqueous amine and ionic liquid alternatives. German and French fabs are responding by embedding chemistry qualification protocols directly into equipment procurement specifications, extending vendor validation cycles.
Aftermarket service unbundling is fragmenting traditional OEM revenue streams. Foundry operators in South Korea are establishing captive refurbishment centers for spray nozzles and megasonic transducers, displacing original manufacturer service contracts. This insourcing trend is most visible at Samsung's Pyeongtaek complex, where internal metrology labs now perform particle counter calibration and chemistry concentration verification previously outsourced to equipment suppliers.
Wet Based Wafer Cleaning Equipment Market Segmentation
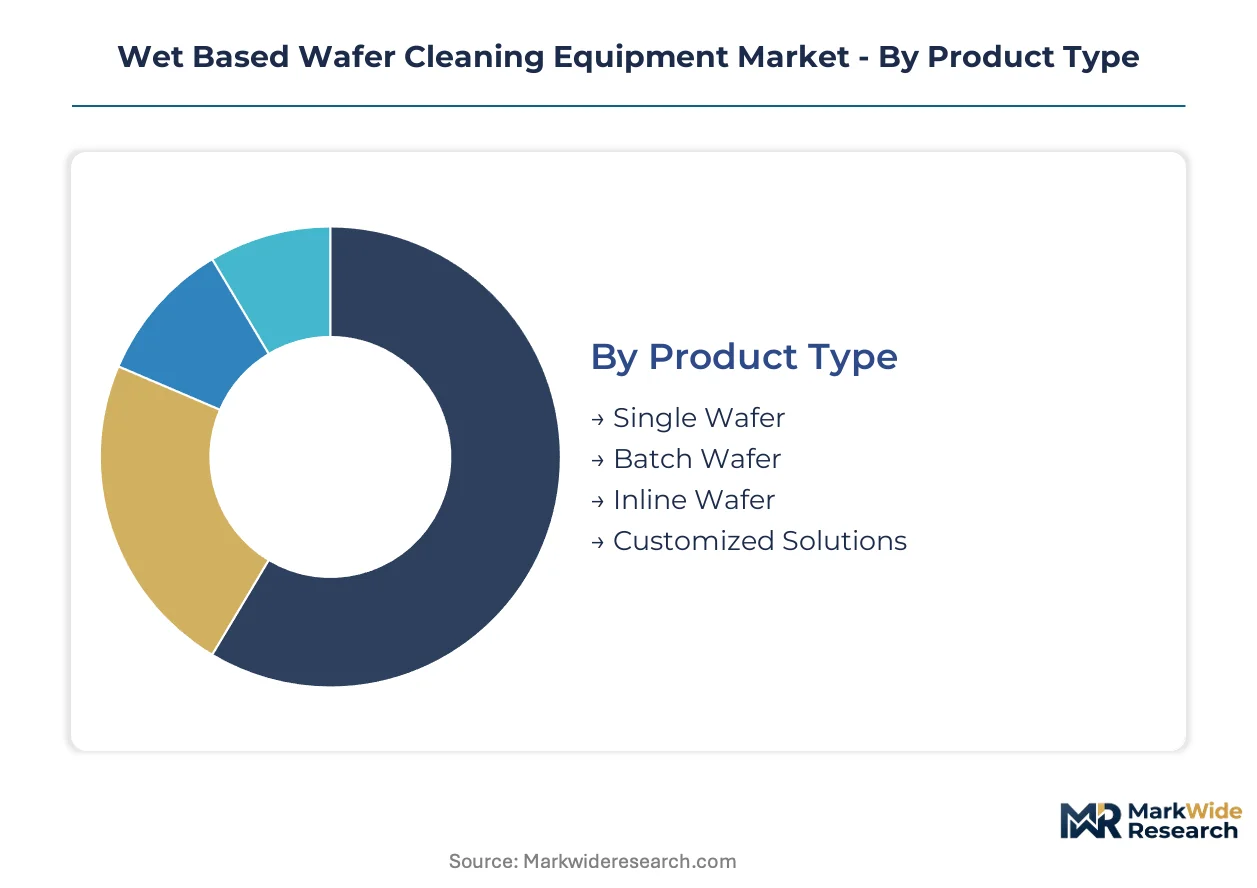
Equipment configurations in this market diverge sharply by contamination control requirements. Node complexity and batch economics dictate whether fabs deploy single-wafer precision or high-throughput immersion systems.
Product Type:
Equipment architectures span from precision single-wafer platforms to high-volume batch systems, with selection driven by particle tolerance thresholds and capital efficiency trade-offs.
- Single Wafer:These platforms process wafers individually through spray or immersion nozzles, eliminating cross-contamination risks critical for sub-7nm logic production. Taiwan's Hsinchu Science Park corridor concentrates demand as foundries expand 3nm and 2nm capacity.
- Batch Wafer:Multiple wafers process simultaneously in shared chemical baths, delivering cost advantages for mature nodes above 28nm. Solar cell manufacturers in Malaysia and Vietnam are extending utilization into photovoltaides texturing applications.
- Inline Wafer:Continuous-flow systems integrate cleaning directly into automated production lines for high-volume commodity chips.
- Customized Solutions:Purpose-built configurations address specialized substrate materials or unique fab layout constraints.
The dominant share belongs to Single Wafer equipment, while Batch Wafer systems are gaining share fastest through photovoltaides adoption.
Technology:
Cleaning methodologies compete on particle removal thresholds, surface damage prevention, and chemistry compatibility with emerging materials.
- Megasonic Cleaning:Frequency-agile transducer arrays generate controlled cavitation for sub-20nm particle removal without damaging delicate cobalt and ruthenium interconnect layers. Taiwan-based logic foundries are adopting 1-3 MHz sweep-mode systems.
- Chemical Cleaning:Wet chemistry processes using hydrogen peroxide, hydrofluoric acid, and sulfuric acid mixtures anchor the largest installed base. REACH restrictions on perfluorinated solvents are forcing seal material recertification for aqueous alternatives.
- Cold Cleaning:Low-temperature chemistries reduce thermal stress on advanced packaging substrates.
- Plasma Cleaning:Dry plasma processes complement wet methods for stubborn organic residues.
Chemical Cleaning retains the largest footprint, though Megasonic Cleaning is climbing the fastest as frequency modulation capabilities consolidate process steps.
Application:
End-use requirements range from atomic-level cleanliness for logic devices to cost-optimized processing for energy conversion applications.
- Semiconductor Fabrication:Front-end-of-line wafer processing demands surface cleanliness below 10¹⁰ atoms/cm² for transistor formation. South Korea's Pyeongtaek semiconductor complex drives capacity expansion for advanced memory and logic.
- Photovoltaics:Silicon wafer texturing and surface preparation for solar cells utilize batch wet benches with relaxed particle specifications. Malaysian and Vietnamese manufacturing clusters are scaling capacity aggressively.
- MEMS:Microelectromechanical systems require gentle cleaning of released mechanical structures without stiction or damage.
- R&D:Pilot lines and university fabs test emerging chemistries and process integrations.
Semiconductor Fabrication commands the dominant position, while Photovoltaides is expanding most quickly through Southeast Asian capacity buildouts.
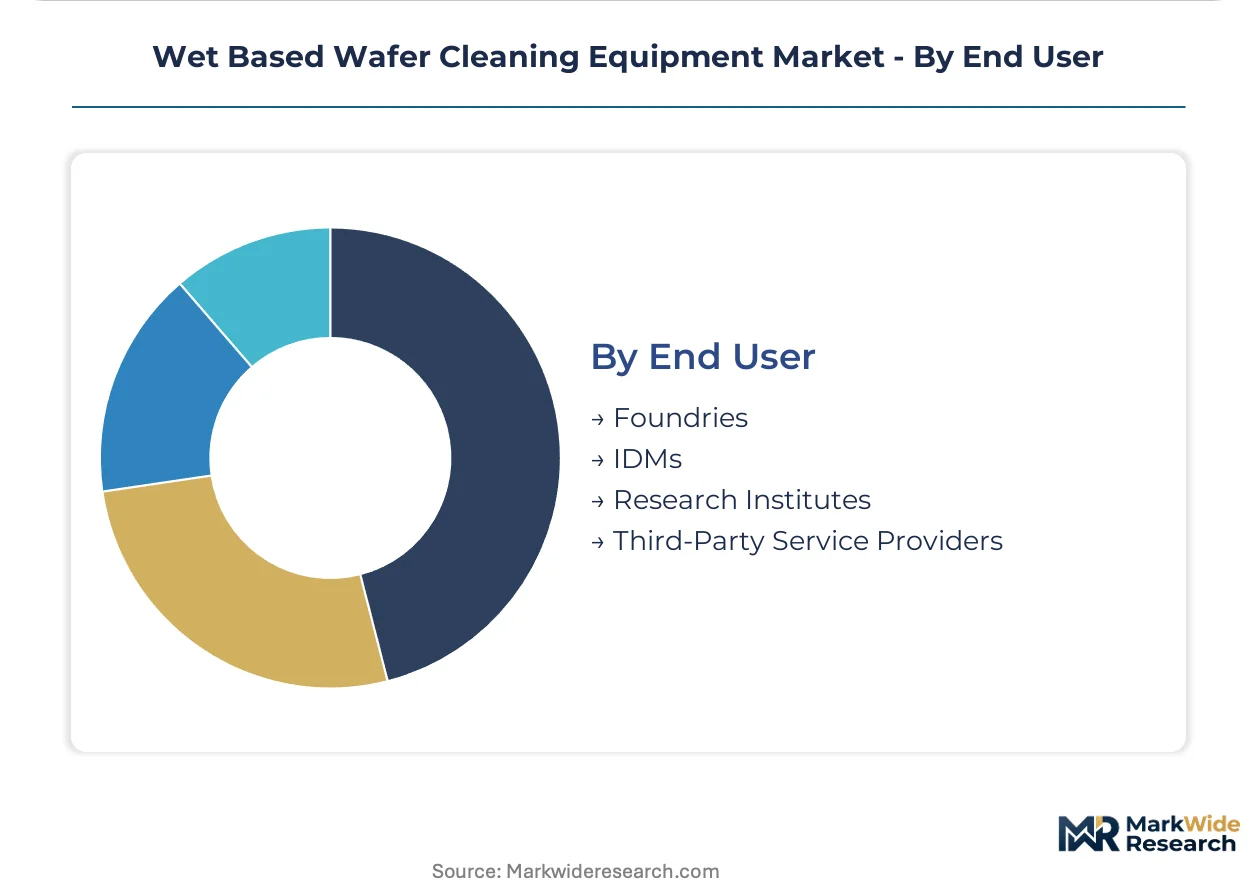
End User:
Customer procurement patterns differ sharply between captive fab operators and outsourced service providers, with implications for equipment specification and service contracting.
- Foundries:Pure-play contract manufacturers like those in Taiwan's Hsinchu corridor specify single-wafer platforms with integrated metrology for multi-customer qualification requirements.
- IDMs:Integrated device manufacturers balance captive production with external sales, often maintaining mixed tool fleets across technology nodes.
- Research Institutes:National laboratories and university cleanrooms prioritize flexibility over throughput for process development.
- Third-Party Service Providers:Outsourced cleaning operations serve fabs lacking in-house wet bench capacity or handling overflow demand.
Foundries hold the dominant share, while IDMs are closing the gap fastest through memory sector consolidation and advanced packaging investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan consumes single-wafer platforms at intensities unmatched elsewhere, while China and Southeast Asia favor batch systems for cost-sensitive photovoltaides and mature-node semiconductor production.
Taiwan
TSMC and United Microelectronics Corporation are expanding 3nm and 2nm foundry capacity, mandating particle removal thresholds below 10¹⁰ atoms/cm². The National Development Council coordinates semiconductor subsidies under the Chips Act framework. Hsinchu Science Park anchors the densest concentration of single-wafer spray tool installations globally.
South Korea
Samsung Electronics and SK Hynix are scaling gate-all-around transistor production, driving demand for megasonic frequency-agile cleaning modules. The Ministry of Trade, Industry and Energy enforces K-REACH chemical registration for alternative solvent formulations. Pyeongtaek's semiconductor complex hosts captive refurbishment centers that displace original equipment manufacturer service contracts.
China
Yangtze Memory Technologies and SMIC are building 28nm and above domestic capacity, balancing batch wet benches with selective single-wafer adoption. The Ministry of Ecology and Environment enforces wastewater discharge standards that elevate capital requirements for new fabs. The Yangtze River Delta cluster concentrates both greenfield construction and chemistry substitution trials aligned with dual carbon goals.
United States
Intel and GlobalFoundries are reshoring advanced logic and memory fabrication, importing single-wafer architectures from East Asian equipment vendors. The EPA enforces effluent guidelines restricting perfluorinated compound discharge from semiconductor wet benches. Arizona's Phoenix metro area and New York's Hudson Valley host the primary greenfield construction sites with extended project approval timelines.
Japan
Kioxia and Micron Japan maintain mixed tool fleets across legacy and advanced nodes, sustaining demand for both batch and single-wafer retrofits. METI coordinates JIS standards for ultrapure water systems feeding directly into cleaning tool specifications. Hiroshima and Yokkaichi anchor memory-focused manufacturing clusters with stringent chemistry qualification protocols.
Wet Based Wafer Cleaning Equipment Market Competitive Landscape
Capability concentration sits with specialized cleaning equipment architects; scale advantage sits with diversified process equipment conglomerates. The market structures around three tiers: pure-play wet cleaning specialists, integrated process equipment platforms, and captive service operations emerging at major foundries. Competitive moves center on chemistry qualification bundling and aftermarket service unbundling as equipment vendors defend recurring revenue streams against customer insourcing.
Within the integrated platform tier, SCREEN Holdings Co., Ltd. and Applied Materials, Inc. exemplify divergent strategic positions. SCREEN represents the pure-play archetype with installed base leverage for recurring parts revenue, while Applied Materials occupies a diversified portfolio position that bundles cleaning with deposition and etch platforms. Lam Research Corporation anchors the plasma-assisted cleaning segment through tight integration with etch product lines.
| Leading Market Players |
|---|
| SCREEN Holdings Co., Ltd. |
| Applied Materials, Inc. |
| Lam Research Corporation |
| Tokyo Electron Limited |
| ACM Research |
| Shibaura Mechatronics Corporation |
| Veeco Instruments Inc. |
| Modutek Corporation |
| Akrion Systems LLC |
| Others |
Value Network & Pricing Analysis
Overcapacity in batch wet bench manufacturing across Malaysia and Vietnam is compressing margins for mature-node equipment while tightening supply for frequency-agile megasonic transducers used in Taiwan's 3nm fabs. This utilization divergence creates asymmetric pricing power between commodity batch systems and precision single-wafer platforms.
Pricing Analysis
Long-term offtake contracts dominate procurement for advanced single-wafer spray tools, with foundries in Hsinchu and Pyeongtaek locking multi-year supply agreements to secure megasonic transducer allocation. Pricing stratifies across premium, standard, and economy tiers based on frequency modulation capability and integrated metrology sophistication. Cost compression in batch systems is intensifying because photovoltaides manufacturers in Southeast Asia prioritize capital efficiency over particle thresholds. IDMs exhibit the highest price sensitivity due to mixed-node portfolios, while pure-play foundries accept premium pricing for contamination control assurance.
Supply Chain Analysis
Contract manufacturing for precision cleaning modules concentrates at specialized fabricators in Japan, South Korea, and Taiwan, with SCREEN and Tokyo Electron alumni networks controlling critical megasonic frequency optimization expertise. Equipment production draws from concentrated sources of high-purity quartz, fluoropolymer seals, and piezoelectric ceramics. Single-source vulnerability in hydrogen peroxide supply from Japanese and German production clusters exposes fabs to maritime logistics disruptions. Distribution runs through direct OEM-fab relationships for advanced nodes, with distributor networks serving photovoltaides and R&D segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wet based wafer cleaning equipment market is entering a cyclical recovery driven by foundry capex normalization following memory sector inventory digestion. Equipment utilization rates at Hsinchu and Pyeongtaek clusters signal renewed capacity expansion intent.
For Market Incumbents: Harden chemistry qualification bundling by embedding aqueous amine compatibility protocols directly into equipment specifications, preempting REACH-mandated retrofit cycles. Deepen captive supply of megasonic transducer arrays through backward integration into piezoelectric ceramic sourcing, reducing exposure to single-source Japanese suppliers. Defend service revenue streams against Samsung's Pyeongtaek insourcing model by offering real-time chemistry concentration monitoring as-a-service. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Karnataka fab corridors, where PLI subsidies are attracting first-mover equipment vendors without entrenched incumbent relationships. Target photovoltaides batch wet bench segments in Vietnam and Malaysia, where particle tolerance thresholds remain relaxed and price competition favors new entrants. Pursue supercritical CO2 cleaning module development to capture carbon-neutral chemistry convergence demand from China's Yangtze River Delta. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across single-wafer spray architectures as frequency-agile transducer R&D demands escalate. The five-to-ten-year viability window favors equipment vendors with installed base leverage for recurring parts revenue over pure technology developers. Acquisition targets should demonstrate chemistry-surface interaction modeling capabilities and established foundry qualification protocols. Monitor EPA effluent guideline enforcement timelines as an inflection indicator for aqueous chemistry substitution capex.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Supply | Captive piezoelectric ceramic sourcing mitigates Japanese supply concentration risk for SCREEN and Applied Materials. |
| Chemistry-as-a-Service Launch | Real-time inventory monitoring at Hsinchu and Pyeongtaek captures recurring revenue displaced by foundry insourcing. |
| Supercritical CO2 Module Development | Closed-loop solvent recovery aligns with China's MEE wastewater standards and Europe's CSRD reporting requirements. |
| India Local Service Infrastructure | Gujarat and Karnataka fab incentives create first-mover advantage without entrenched competitor relationships. |
| Frequency-Agile Transducer R&D Expansion | 1-3 MHz sweep-mode capabilities consolidate pre-clean and post-clean steps for TSMC's 2nm cobalt interconnect layers. |
Research Methodology
Operator-level perspectives from fab process engineers, equipment procurement managers, megasonic transducer technicians, and chemistry qualification specialists anchored the qualitative base for this study. Primary interviews with SCREEN and Tokyo Electron alumni networks informed megasonic frequency optimization expertise concentration. Secondary validation drew from EPA effluent guideline filings, ECHA REACH restriction updates, Japan's METI JIS standard publications, and SEC 10-K equipment vendor disclosures. Bottom-up wafer throughput modeling and top-down foundry capex aggregation were triangulated against chemistry consumption data.
Scenario-bracketing around EPA enforcement timelines, REACH substitution deadlines, and China's dual carbon goal implementation framed the analytical approach across the projection horizon. Segmentation dimensions modeled include equipment architecture, cleaning technology, application node complexity, end-user procurement pattern, and regional regulatory cluster. CAGRs were derived from equipment shipment tracking and chemistry consumption intensity ratios. Forecast inputs incorporated megasonic transducer replacement cycles and batch-to-single-wafer transition velocities at named foundry complexes.
Stress conditions across EPA effluent compliance costs, hydrogen peroxide supply disruptions, and 3D architecture cleaning damage thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding node shrinkage velocity and chemistry substitution timelines. Semiconductor equipment cyclicality, maritime logistics volatility, and process engineer scarcity constitute primary revision risks. Quarterly review of foundry capex announcements and MEE enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Dry Reactor Market