
 Smartphone Biometric Sensors Market | 2026-2036
Smartphone Biometric Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Biometric Sensors Market Analytics
South Korean component foundries is restructuring capacity allocation toward ultrasonic sensor substrates. Shenzhen Goodix Technology Co., Ltd. dominates capacitive fingerprint module shipments to Android OEMs. Synaptics Incorporated leverages its optical under-display portfolio to anchor premium-tier supply agreements. Fingerprint Cards AB specializes in slim-form-factor sensors for budget smartphone segments.
Smartphone biometric sensors are solid-state or MEMS-based transducers that convert physiological characteristics into electrical signals for identity verification, with optical variants using CMOS image arrays at 500+ ppi resolution and ultrasonic variants emitting acoustic pulses to map subdermal ridge structures. Their primary commercial purpose is to replace password-based authentication with inherence factors that resist credential theft. Fingerprint sensors still occupy the largest volume position across all price tiers, while facial recognition modules are capturing margin pools in flagship devices. Ultrasonic technology is displacing optical under-display solutions in premium handsets due to superior moisture tolerance and spoof resistance.
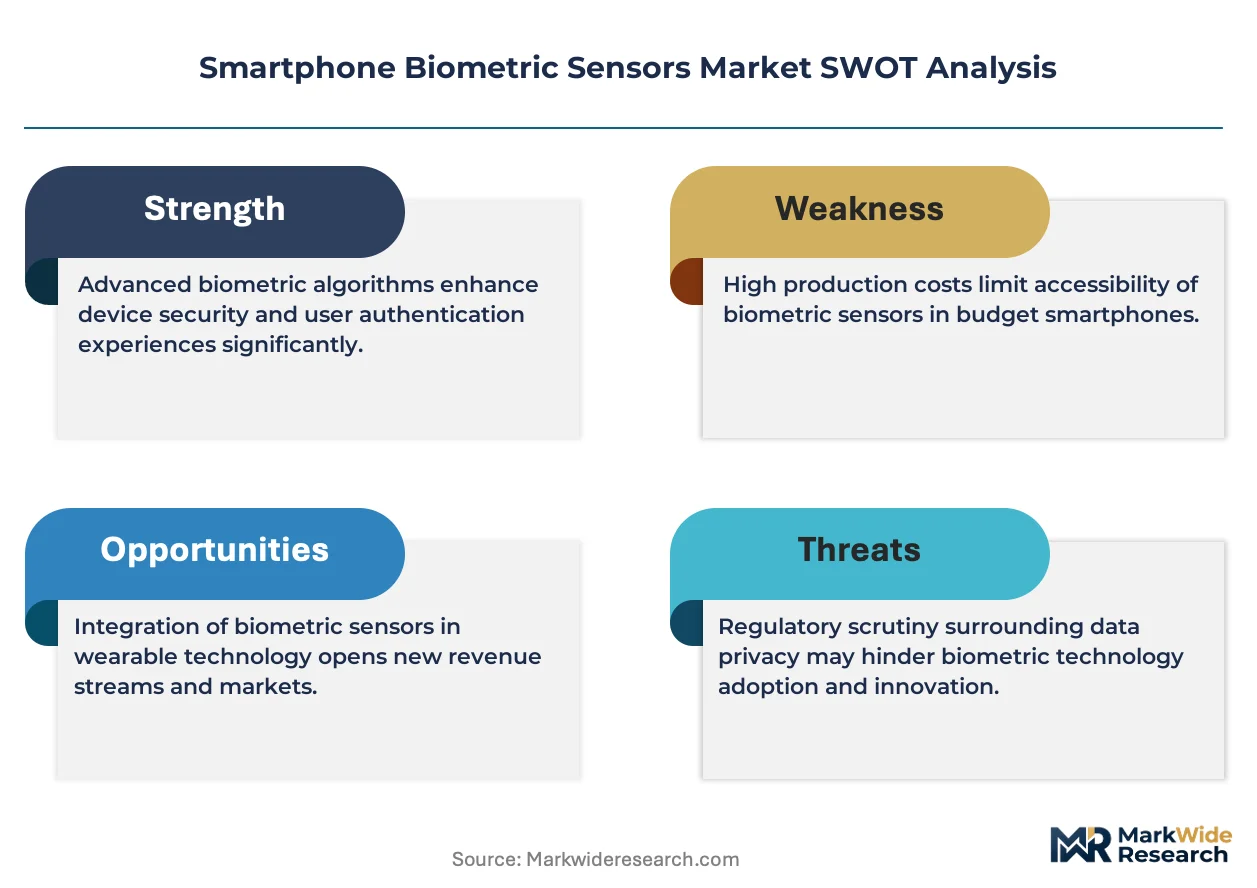
FDA guidance on biometric data in health-adjacent applications, China's MIIT personal information protection standards for mobile devices, and the EU AI Act's risk classification for remote biometric identification collectively shape hardware certification requirements and OEM go-to-market timelines. India's BIS compulsory registration order for electronic components adds another compliance layer for sensor module imports. Stakeholders must monitor which authentication modality—fingerprint, face, or iris—gains preference in next-generation payment security frameworks.
Market Dynamics
Ultrasonic fingerprint sensing is restructuring competitive positioning across premium smartphone tiers, displacing optical under-display modules as OEMs prioritize moisture tolerance and liveness detection in authentication hardware.
Growth Catalysts
- India's Digital Public Infrastructure:Government-mandated Aadhaar-linked mobile banking applications are compelling domestic OEMs to integrate certified fingerprint modules across sub-$200 handsets.
- EU AI Act Risk Classification:Tiered compliance requirements for remote biometric identification systems are accelerating hardware-level encryption investments in facial recognition subsystems.
- Mobile Payment Platform Expansion:Super-app ecosystems in Southeast Asia are driving sensor integration into mid-tier devices previously limited to PIN authentication.
Market Restraints
- Substrate Supply Concentration:Piezoelectric material refinement for ultrasonic emitters depends on South Korean and Japanese specialty chemical foundries with limited capacity expansion.
- MIIT Certification Timelines:China's biometric data protection mandates impose 6-9 month hardware validation cycles that compress OEM product launch windows.
- Optical Module Inventory Overhang:Legacy CMOS-based under-display sensors face accelerated obsolescence as ultrasonic penetration deepens in $400+ price bands.
Strategic Opportunities
- Indonesia's Unbanked Population:National financial inclusion targets are creating first-time smartphone demand with mandatory biometric registration for digital wallet activation.
- Health-Adjacent Authentication:FDA guidance on pulse oximetry-adjacent sensors is opening convergent hardware designs combining fingerprint and blood oxygen verification.
- BIS Compulsory Registration:India's import certification requirements for electronic components are incentivizing local module assembly joint ventures with sensor IC suppliers.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Ultrasonic sensor calibration requires specialized MEMS transducer expertise concentrated in South Korean and Taiwanese R&D centers.
- Multi-Modal Integration Complexity:Simultaneous fingerprint and facial recognition subsystems demand thermal management solutions that extend industrial design cycles by 4-6 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Biometric Sensors Market |
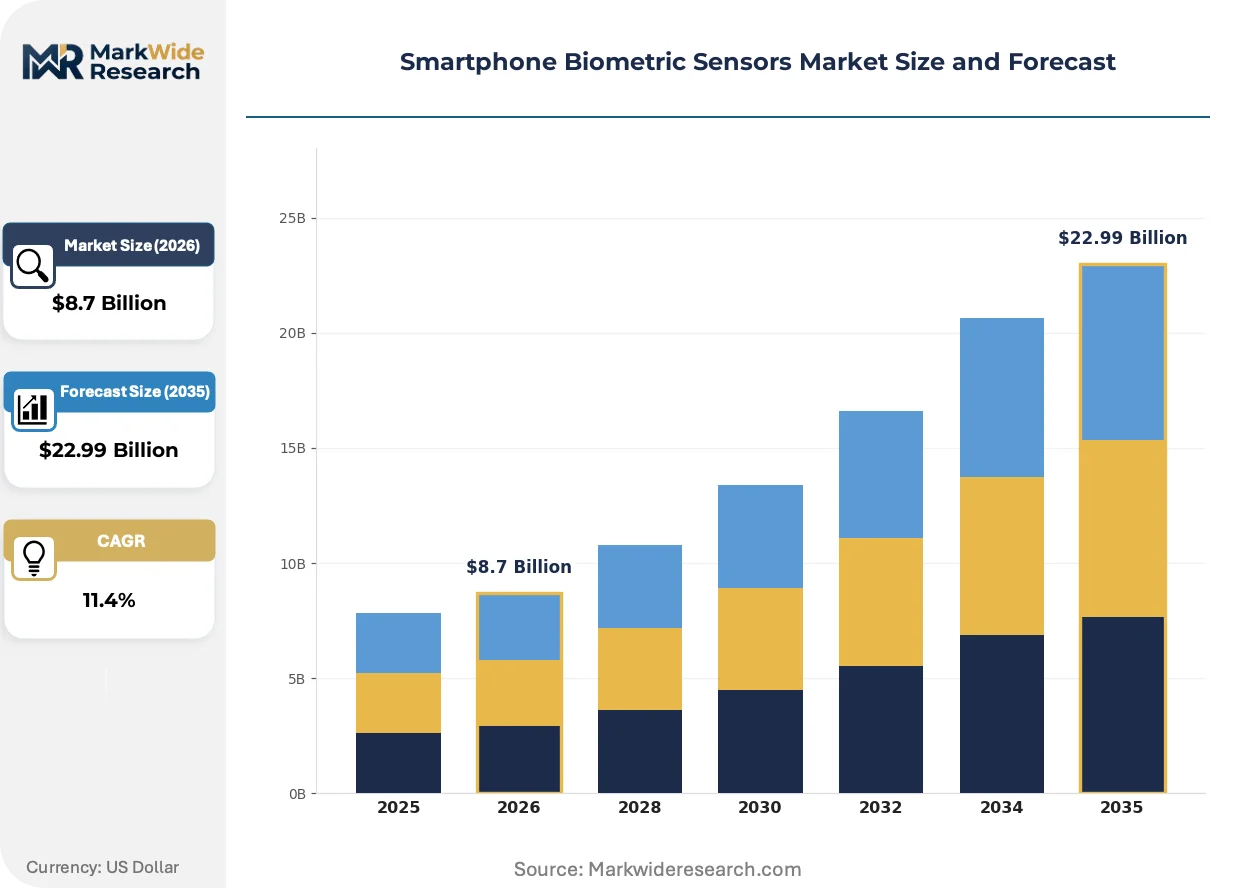
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Fingerprint, Facial Recognition, Iris Recognition, Voice Recognition Technology: Optical Sensors, Capacitive Sensors, Ultrasonic Sensors, Infrared Sensors Application: Mobile Payments, Device Security, User Authentication, Access Control End User: Consumers, Enterprises, Government, Healthcare |
| Companies Covered | Shenzhen Goodix Technology Co., Ltd., Synaptics Incorporated, Fingerprint Cards AB, Egis Technology Inc., CrucialTec, Apple Inc., Infineon Technologies, NEC Corporation, NEXT Biometrics Group ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Biometric Sensors Market Evolving Landscape
Authentication hardware is bifurcating into premium ultrasonic modules and cost-optimized optical alternatives, with regulatory pressure on data security accelerating encryption co-processor integration across all tiers.
Ultrasonic fingerprint sensing is electrifying premium smartphone authentication by emitting acoustic pulses that map subdermal ridge structures through display glass. Flagship OEMs in South Korea and China are adopting this technology at 18-month refresh cycles. The shift is electrifying demand for piezoelectric substrate suppliers while compressing optical sensor margins in devices above $500.
China's MIIT personal information protection standards for mobile devices are mandating hardware-isolated secure enclaves for biometric template storage. This industrial consequence requires sensor module vendors to redesign ASIC architectures before market entry. Premium-tier facial recognition deployments face the steepest compliance costs, with OEMs extending certification timelines by two quarters.
Enterprise mobility managers are consolidating authentication procurement around FIDO2-certified hardware modules that interoperate across device fleets. Channel relationships with direct OEM supply agreements are displacing traditional component distributor networks for volume orders above 500,000 units. This concentration is most visible in North American and European corporate refresh programs where IT security teams specify compliance-grade sensors upfront.
Smartphone Biometric Sensors Market Segmentation
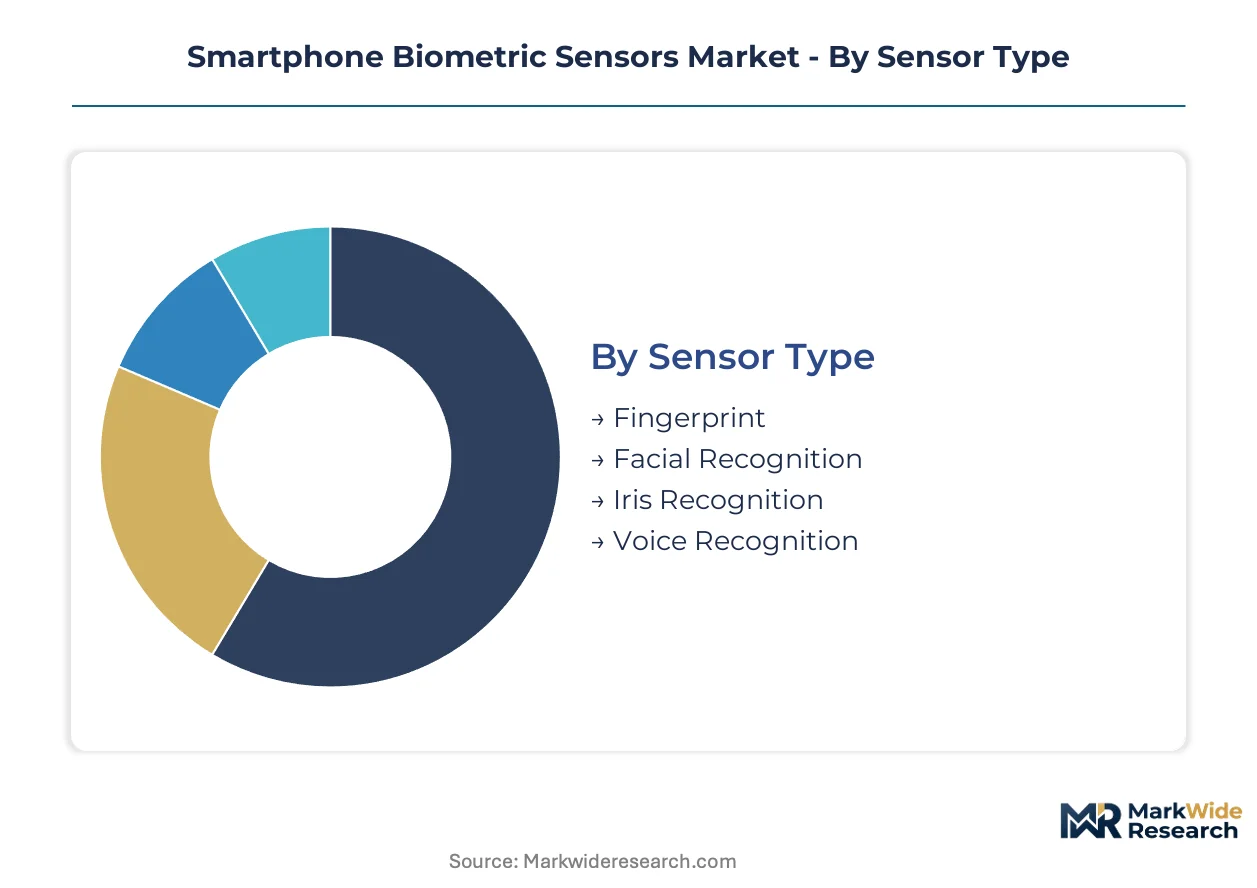
Smartphone biometric sensors fragment across four distinct axes that shape procurement patterns and module specifications. Technology selection determines hardware cost structures, while application requirements dictate encryption and liveness detection standards.
Sensor Type:
Technology maturity and spoof resistance characteristics differentiate authentication modalities across price tiers and use cases.
- Fingerprint:Capacitive and ultrasonic variants dominate volume shipments, with under-display optical modules serving mid-tier handsets. India's Aadhaar-linked banking applications are compelling domestic OEMs to integrate certified capacitive modules across sub-$200 devices.
- Facial Recognition:Structured light and time-of-flight 3D sensing arrays enable liveness detection for payment-grade security. EU AI Act risk classification for remote biometric identification is accelerating hardware-level encryption investments in flagship-tier deployments.
- Iris Recognition:Near-infrared CMOS sensors map unique vascular patterns for high-security enterprise and government deployments.
- Voice Recognition:Microphone array signal processing enables hands-free authentication, primarily in automotive-integrated smartphone ecosystems.
Mature deployment sits with Fingerprint. Newer deployment is concentrated in Facial Recognition.
Technology:
Transduction mechanisms determine moisture tolerance, substrate requirements, and integration complexity with display stacks.
- Optical Sensors:CMOS image arrays at 500+ ppi resolution capture epidermal ridge patterns through display glass. Inventory overhang in legacy under-display modules is accelerating price compression as ultrasonic alternatives penetrate $400+ price bands.
- Capacitive Sensors:Silicon-based electrode arrays detect electrical conductivity differences between ridges and valleys. Shenzhen Goodix Technology Co., Ltd. dominates module shipments to Android OEMs across budget and mid-tier segments.
- Ultrasonic Sensors:Piezoelectric emitters generate acoustic pulses that map subdermal structures with superior spoof resistance. South Korean component foundries are restructuring capacity allocation toward ultrasonic sensor substrates to meet 18-month flagship refresh cycles.
- Infrared Sensors:VCSEL and flood illuminator combinations enable depth mapping for facial authentication in low-light conditions.
Volume leadership belongs to Capacitive Sensors. Steepest expansion trajectory is registered by Ultrasonic Sensors.
Application:
Use case requirements vary in security grade, latency tolerance, and regulatory compliance burden.
- Mobile Payments:FIDO2-certified hardware with liveness detection satisfies super-app ecosystem requirements in Southeast Asia. Super-app ecosystems are driving sensor integration into mid-tier devices previously limited to PIN authentication.
- Device Security:Hardware-isolated secure enclaves for biometric template storage satisfy China's MIIT personal information protection standards.
- User Authentication:Single-factor and multi-modal configurations balance convenience against spoofing risk for consumer device unlock.
- Access Control:Enterprise mobility deployments specify compliance-grade sensors with centralized template management.
Regulatory pressure concentrates in Mobile Payments. Feature expansion is most visible in Device Security.
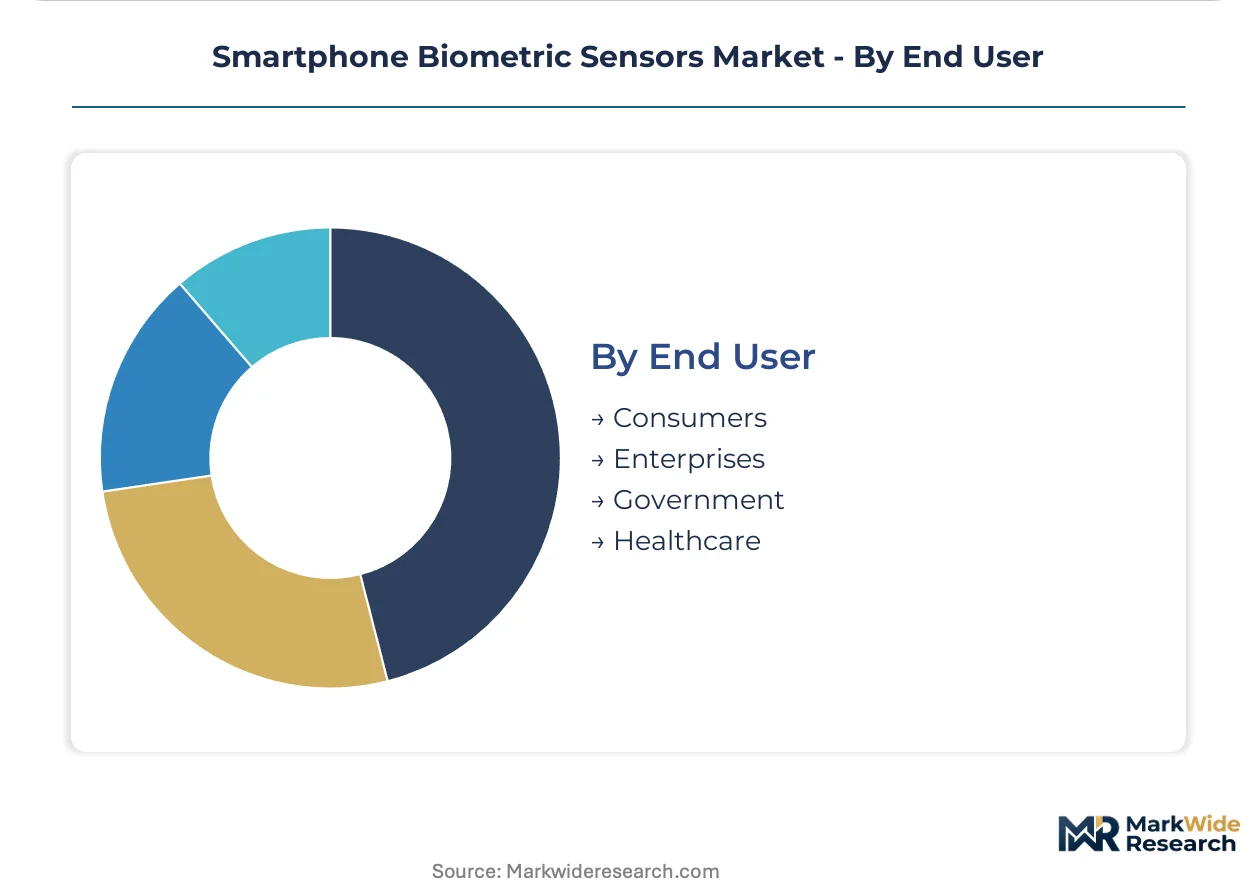
End User:
Procurement authority and security specification stringency diverge sharply across customer categories.
- Consumers:Convenience-driven adoption prioritizes unlock speed and form factor integration over certification grade.
- Enterprises:IT security teams specify FIDO2-certified hardware modules upfront for fleet interoperability in North American and European corporate refresh programs.
- Government:National digital identity programs mandate certified modules with template protection against forensic extraction.
- Healthcare:FDA guidance on biometric data in health-adjacent applications is opening convergent hardware designs combining fingerprint and blood oxygen verification.
Procurement consolidation is strongest in Enterprises. Regulatory tailwinds favor Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piezoelectric substrate refinement anchors the smartphone biometric sensor supply chain in South Korean specialty chemical foundries, while module assembly concentrates in Chinese coastal manufacturing clusters and Indian import-substitution zones.
China
MIIT personal information protection standards mandate hardware-isolated secure enclaves for biometric template storage, compelling Shenzhen-based module vendors to redesign ASIC architectures before market entry. The Pearl River Delta manufacturing corridor hosts capacitive fingerprint module assembly operations serving domestic Android OEMs.
South Korea
Flagship OEMs adopt ultrasonic fingerprint sensing at 18-month refresh cycles, electrifying demand for domestic piezoelectric substrate suppliers. The country's national semiconductor regulator coordinates with component foundries restructuring capacity allocation toward ultrasonic sensor substrates.
India
Aadhaar-linked mobile banking applications compel domestic OEMs to integrate BIS-certified fingerprint modules across sub-$200 handsets. BIS compulsory registration requirements for electronic components incentivize local module assembly joint ventures in Karnataka and Tamil Nadu manufacturing corridors.
United States
FDA guidance on biometric data in health-adjacent applications shapes hardware certification requirements for convergent sensor designs. Enterprise mobility managers in North American corporate refresh programs specify FIDO2-certified hardware modules with centralized template management.
Indonesia
National financial inclusion targets create first-time smartphone demand with mandatory biometric registration for digital wallet activation. Super-app ecosystems drive sensor integration into mid-tier devices previously limited to PIN authentication in Jakarta and Surabaya metropolitan procurement zones.
Smartphone Biometric Sensors Market Competitive Landscape
Global majors compete with regional champions across sensor technology portfolios and OEM supply agreements. The vendor base separates into three tiers: premium ultrasonic specialists, mid-tier optical module suppliers, and budget capacitive fabricators. Strategic archetypes include display-stack integrators, secure-element co-processor designers, and foundry-dependent substrate specialists. Capacity expansion into ultrasonic piezoelectric materials and strategic partnerships for FIDO2 certification acceleration represent the dominant competitive moves.
Among Asia-Pacific module suppliers, Shenzhen Goodix Technology Co., Ltd. and Synaptics Incorporated occupy positions spanning capacitive and optical under-display portfolios, while Fingerprint Cards AB exemplifies the slim-form-factor specialization archetype for budget smartphone segments. These three entities represent distinct strategic postures: the Shenzhen-based Co., Ltd. structure anchoring high-volume Android OEM relationships, the Incorporated suffix signaling integrated circuit design heritage, and the AB designation indicating Nordic capital-market access for R&D-intensive sensor miniaturization.
| Leading Market Players |
|---|
| Shenzhen Goodix Technology Co., Ltd. |
| Synaptics Incorporated |
| Fingerprint Cards AB |
| Egis Technology Inc. |
| CrucialTec |
| Apple Inc. |
| Infineon Technologies |
| NEC Corporation |
| NEXT Biometrics Group ASA |
| Others |
Value Network & Pricing Analysis
India's Aadhaar-linked banking mandates are compressing procurement timelines for sub-$200 handset OEMs, forcing module vendors to absorb certification costs while maintaining wafer-thin margins on capacitive fingerprint shipments. This demand-side pressure propagates upstream through substrate suppliers and ASIC foundries, fragmenting pricing power across tiered supplier relationships.
Pricing Analysis
Warranty and FIDO2 certification bundling now separates premium ultrasonic modules from unbundled optical alternatives in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FIDO2-certified hardware commanding substantial premiums over baseline PIN-replacement modules. Cost compression in optical under-display inventory is intensifying because ultrasonic penetration in $400+ devices accelerates obsolescence. Government procurement programs exhibit lowest price sensitivity due to mandated security specifications, while budget smartphone OEMs in Southeast Asia face acute margin pressure.
Supply Chain Analysis
Specialized MEMS transducer engineers in South Korean and Taiwanese R&D centers constrain capacity expansion for ultrasonic sensor calibration. Manufacturing concentrates in China's Pearl River Delta for capacitive module assembly, South Korea for piezoelectric substrate refinement, and India's Karnataka corridor for BIS-certified import substitution. Raw material dependencies draw from Japanese specialty chemical foundries for piezoelectric materials, Taiwanese silicon foundries for ASIC fabrication, and Chinese glass substrate suppliers for display integration. Single-source vulnerability in South Korean piezoelectric emitters elevates supply risk. Distribution runs through direct OEM supply agreements displacing traditional component distributors for volume orders above 500,000 units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piezoelectric substrate capacity bottlenecks in South Korean specialty chemical foundries prop pricing premiums for ultrasonic modules, sustaining margin pools unavailable to optical competitors.
For Market Incumbents: Deploy backward integration into piezoelectric material refining to secure substrate supply against South Korean capacity constraints. Consolidate FIDO2 certification pipelines to defend against emerging secure-element co-processor designers entering from adjacent semiconductor markets. Anchor premium-tier supply agreements through exclusive 18-month refresh cycle partnerships with flagship OEMs. For New Entrants and Emerging Players: The $150-$250 price-point gap between premium ultrasonic and economy capacitive modules offers white-space targeting for hybrid optical-ultrasonic architectures. Indonesia's unbanked population financial inclusion mandates represent the most penetrable geography, with mandatory biometric registration creating first-time smartphone demand. Pursue joint venture assembly partnerships with Indian BIS-registered facilities to bypass import certification timelines. For Investors and Strategic Acquirers: The window for entry favors secure-element co-processor designers with hardware-isolated enclave IP ahead of MIIT compliance deadline acceleration. Long-term viability hinges on ultrasonic technology maturation beyond premium flagships into mid-tier penetration. Watch South Korean foundry capacity allocation announcements as inflection indicator for substrate supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Piezoelectric Substrate Capacity Expansion | South Korean foundry restructuring toward ultrasonic emitters secures supply for 18-month flagship refresh cycles. |
| FIDO2 Certification Acceleration | Hardware module interoperability across enterprise fleets satisfies North American IT security procurement specifications. |
| Local Assembly Joint Ventures | India's BIS compulsory registration requirements incentivize Karnataka and Tamil Nadu manufacturing corridor partnerships. |
| Multi-Modal Sensor Integration | Convergent fingerprint and blood oxygen verification designs align with FDA health-adjacent authentication guidance. |
| ASIC Architecture Redesign | Hardware-isolated secure enclaves satisfy China's MIIT personal information protection standards for template storage. |
Research Methodology
Multi-period observation of ultrasonic penetration rates, capacitive module shipment volumes, and certification timeline compression anchored the trend analysis, supplemented by interviews with sensor module procurement managers at Android OEMs, ASIC design leads at secure-element vendors, piezoelectric substrate specialists at South Korean foundries, and regulatory compliance officers navigating MIIT and BIS frameworks. Secondary validation drew from MIIT personal information protection standard filings, BIS compulsory registration orders, FDA guidance documents on biometric data, EU AI Act risk classification texts, and SEC disclosures from listed component suppliers. Bottom-up module shipment aggregation triangulated against top-down smartphone production forecasts.
Segment-weighting across sensor type, technology, application, and end-user dimensions calibrated value and volume outputs over the projection horizon. Technology trajectories modeled optical-to-ultrasonic displacement curves, regulatory compliance cost burdens, and geographic adoption patterns across India's Aadhaar-linked banking, Indonesia's financial inclusion targets, and China's MIIT mandates. CAGRs derived from fitted adoption curves incorporating 18-month flagship refresh cycles and 6-9 month hardware validation timelines.
Inputs from South Korean foundry capacity announcements, Indian BIS registration databases, and Chinese MIIT certification records were available through the study window; gaps in real-time OEM inventory positions and confidential substrate pricing introduce uncertainty bands around ultrasonic penetration forecasts. Material deviation in South Korean piezoelectric capacity allocation, Indian BIS registration timeline extensions, or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Torque Sensor Market