
 Semiconductor Manufacturing Equipment Market | 2026-2036
Semiconductor Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Manufacturing Equipment Market Analysis
Aftermarket service revenue is narrowing the margin gap against original equipment sales as tool complexity extends maintenance contracts. Applied Materials leverages its installed base across deposition and etch platforms to capture recurring revenue streams. Tokyo Electron sustains dominance in thermal processing and coat-develop-track systems through deep integration with logic foundries. ASML Holding NV anchors the lithography segment with extreme ultraviolet systems that define node advancement roadmaps.
Semiconductor manufacturing equipment encompasses the precision machinery used to fabricate integrated circuits on silicon wafers, including lithography systems operating at 13.5 nanometer EUV wavelengths, plasma etch chambers, and thin-film deposition tools operating under high-vacuum conditions. These systems enable patterning, material modification, and layer stacking to produce microprocessors, memory devices, and power semiconductors. Lithography equipment commands the highest capital intensity per unit as foundries pursue sub-3 nanometer resolution. Deposition equipment grows fastest as three-dimensional transistor architectures multiply film stack complexity. Cleanroom equipment remains mature with replacement-driven demand tied to fab construction cycles.
FDA oversight applies to semiconductor components destined for medical devices, while EPA regulations govern chemical handling in fabrication processes and REACH restricts hazardous substances in European supply chains. Japan's METI coordinates export controls on advanced manufacturing tools through multilateral agreements. Taiwan's domestic regulators enforce fab construction standards alongside water and energy use permits that constrain expansion timelines. Stakeholders must monitor how bilateral technology restrictions reshape equipment eligibility across major fabrication geographies.
Market Dynamics
Node shrinkage below 3 nanometers is forcing foundries to retool entire fabrication lines, concentrating capital deployment among lithography, deposition, and metrology platforms that define yield economics at atomic-scale precision.
Growth Catalysts
- CHIPS Act disbursements:US fabs are accelerating construction timelines as Department of Commerce funding unlocks land acquisition and utility infrastructure commitments for greenfield sites in Arizona and Texas.
- Automotive MCU demand:Electric vehicle powertrains and ADAS architectures are multiplying die-per-vehicle counts, pulling 28nm and 40nm capacity expansion across legacy node equipment.
- EUV pellicle maturation:Improved membrane durability is extending scanner uptime, reducing the frequency of source module maintenance cycles that previously constrained wafer output.
Market Restraints
- Neon gas supply concentration:Ukrainian purification facilities supply over half of semiconductor-grade neon; geopolitical disruption forces fabs to absorb 300-400% price spikes or fund alternative sourcing infrastructure.
- Extreme ultraviolet source power limits:ASML's tin droplet generators face theoretical ceiling constraints below 600W, capping throughput gains for high-NA systems targeting 2027 insertion.
- Japan METI export licensing:Multilateral coordination on 14nm and below tool shipments to specific fabrication geographies creates order fulfillment delays and contract renegotiation overhead.
Strategic Opportunities
- India semiconductor mission:Modified incentive structures under the PLI scheme are attracting display driver and power semiconductor fabs to Gujarat and Karnataka, creating greenfield equipment procurement windows.
- Hybrid bonding adoption:3D stacking of memory-on-logic dies is migrating from HBM packaging into mainstream CPU architectures, multiplying lithography and etch steps per finished wafer.
- Refurbishment channel formalization:Secondary markets for 200mm and mature-node tools are consolidating through certified reseller networks that extend asset life for analog and power device manufacturers.
Industry Challenges
- Vacuum technician scarcity:Cryogenic pump maintenance and chamber leak detection require specialized training pipelines that universities and vocational programs have not scaled to match fab construction velocity.
- Metrology-integration complexity:Multi-beam electron microscopes and optical scatterometry tools must feed real-time data into AI-driven process control loops, straining legacy MES architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Manufacturing Equipment Market |
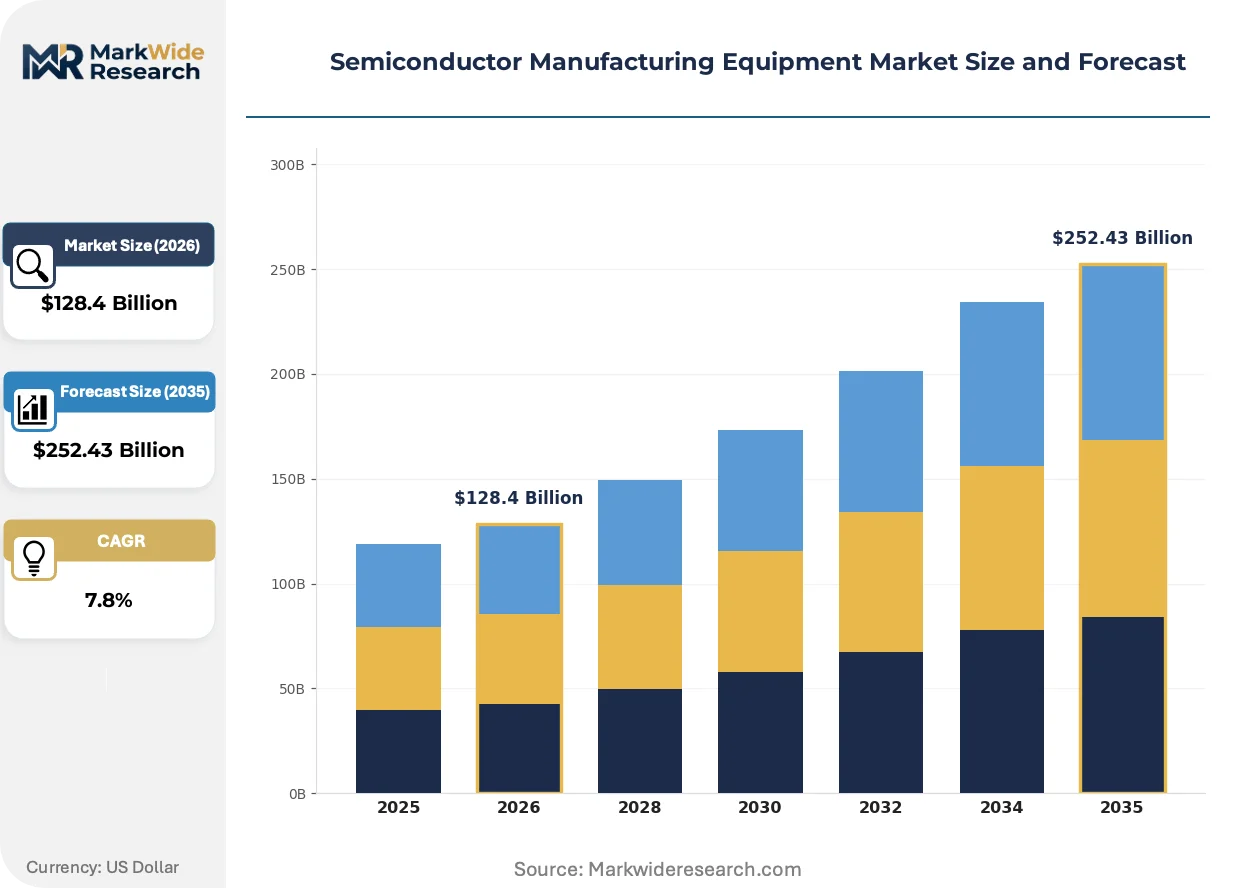
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $252.43 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithography Equipment, Etching Equipment, Deposition Equipment, Cleanroom Equipment Technology: Photolithography, Electron Beam Lithography, Chemical Vapor Deposition, Atomic Layer Deposition End User: Foundries, Integrated Device Manufacturers, Memory Manufacturers, Fabless Companies Application: Consumer Electronics, Automotive Electronics, Industrial Electronics, Telecommunications |
| Companies Covered | Tokyo Electron, Advantest, ASML Holding NV, Teradyne, SCREEN Semiconductor Solutions, Applied Materials, KLA, ASM International, Lam Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Manufacturing Equipment Market Emerging Trajectories
Atomic-scale process control is migrating from offline sampling to in-situ monitoring, compressing feedback loops that previously required hours of wafer quarantine and destructive testing.
High-NA EUV lithography is migrating from research consortium demonstrations into pilot production at Intel's Oregon development fab, with numerical aperture expansion from 0.33 to 0.55 enabling single-expose patterning at 8nm pitch. Foundry adoption timelines concentrate on 2027-2028 for A10 node insertion, displacing multi-patterning EUV sequences that currently dominate 3nm production.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing wet chemistry suppliers to reformulate etchants and cleans used in BEOL dielectric processing. Equipment OEMs must validate alternative chemistries without compromising selectivity ratios, with logic foundries in Ireland and Germany facing the tightest substitution deadlines under ECHA sunset dates.
Consolidated procurement consortia are displacing individual fab purchasing for non-critical subsystems, with TSMC, Samsung, and Intel jointly negotiating chamber components and robotics modules to compress supplier margins. This concentration is most visible in vacuum hardware and gas delivery systems, where standardized specifications enable volume aggregation that smaller IDMs cannot replicate.
Semiconductor Manufacturing Equipment Market Segmentation
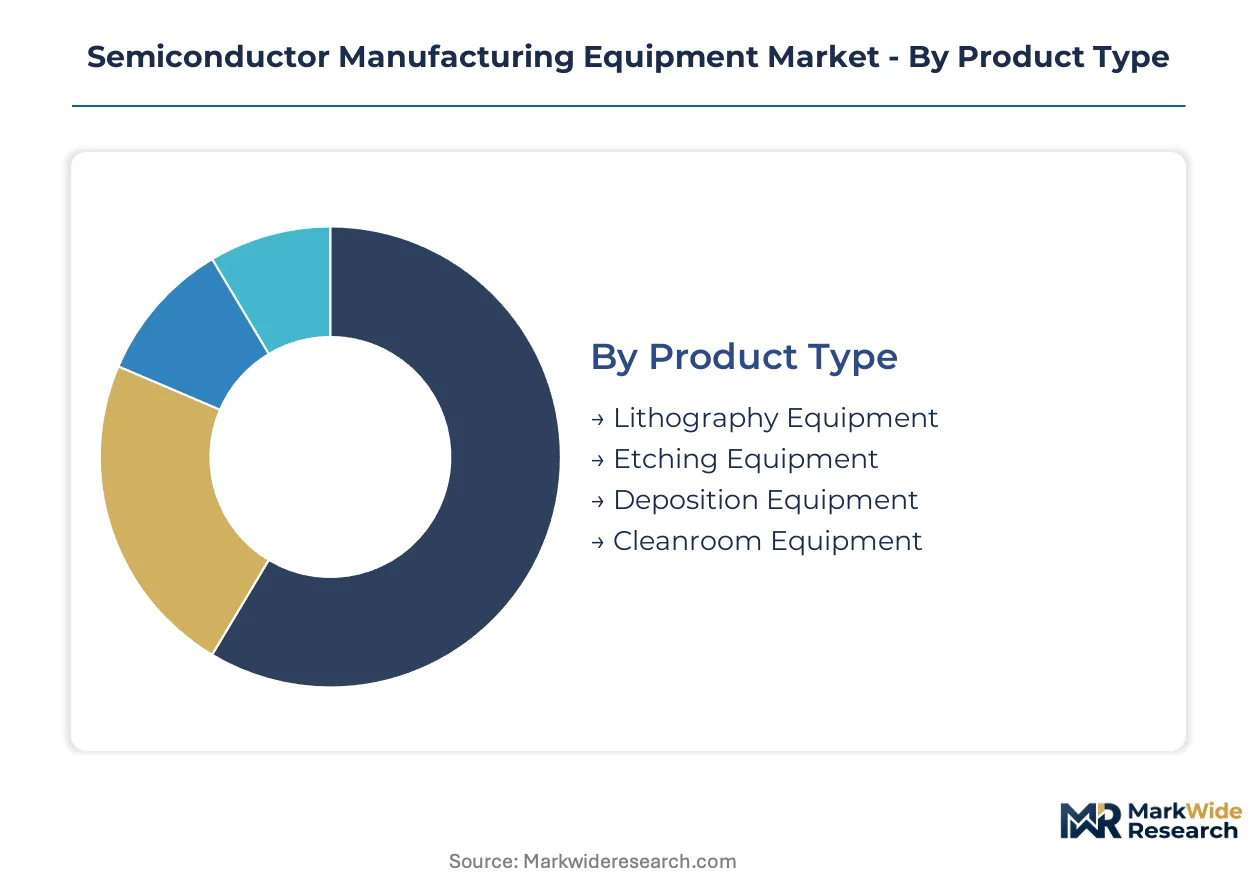
Equipment segmentation in semiconductor manufacturing tracks capital deployment cycles that range from decade-long lithography platforms to annual cleanroom refresh schedules. Understanding these velocity differences allows suppliers to align service models with replacement timing and foundries to stage procurement across technology roadmaps.
Product Type:
Lithography systems operate on the longest depreciation cycles, often spanning fifteen years with mid-life source upgrades, while cleanroom infrastructure turns over fastest as contamination standards tighten node-to-node.
- Lithography Equipment:Systems pattern silicon wafers using extreme ultraviolet wavelengths at 13.5 nanometers, requiring vacuum chambers and precision optics that consume the largest share of fab capital budgets. Demand concentrates at TSMC's Taiwan facilities and Intel's Arizona expansion as both pursue sub-3 nanometer production timelines constrained by scanner delivery queues.
- Deposition Equipment:Thin-film deposition tools build transistor gate stacks and interconnect layers through chemical vapor deposition and atomic layer deposition processes operating under high vacuum. Logic foundries in Taiwan and memory manufacturers in South Korea are multiplying film stack complexity for three-dimensional architectures, expanding chamber counts per fab.
- Etching Equipment:Plasma etch chambers remove material selectively to carve finFET and gate-all-around transistor geometries with atomic-scale precision.
- Cleanroom Equipment:Air filtration, chemical delivery, and wafer handling systems maintain Class 1 particle environments.
Lithography Equipment dominates installed base. Deposition Equipment is where expansion concentrates.
Technology:
Cost tiers separate mask-based patterning from direct-write systems, with photolithography commanding premium pricing at leading nodes while electron beam serves low-volume prototyping and photomask fabrication.
- Photolithography:Optical and extreme ultraviolet systems project circuit patterns through reticles onto photoresist-coated wafers, with numerical aperture and wavelength determining resolution limits. Foundries in Taiwan and South Korea are driving insertion of high-NA EUV at 0.55 numerical aperture for single-expose patterning below 8 nanometer pitch.
- Chemical Vapor Deposition:CVD reactors deposit conformal dielectric and metal films through gas-phase precursor reactions, serving both logic and memory production with high throughput.
- Electron Beam Lithography:Direct-write systems pattern wafers without masks using focused electron beams, enabling nanometer-scale resolution at low throughput.
- Atomic Layer Deposition:ALD tools build films one atomic layer per cycle, delivering precise thickness control for high-aspect-ratio structures.
Photolithography dominates installed base. Chemical Vapor Deposition is expanding most quickly.
End User:
Customer type determines procurement scale and technology timing, with foundries placing largest individual orders at leading nodes while IDMs spread investment across diversified product portfolios.
- Foundries:Pure-play contract manufacturers such as TSMC and Samsung Foundry operate at the highest capital intensity, deploying EUV lithography and advanced deposition clusters to serve fabless chip designers. Taiwan and South Korea anchor procurement volume as these companies expand 3 nanometer and 2 nanometer capacity.
- Memory Manufacturers:DRAM and NAND flash producers including Samsung, SK Hynix, and Micron drive demand for high-throughput etch and deposition platforms as 3D stacking multiplies process steps per wafer.
- Integrated Device Manufacturers:IDMs such as Intel and Texas Instruments combine design and fabrication, spreading equipment investment across logic, analog, and power product lines.
- Fabless Companies:Design houses without fabrication capacity influence equipment demand indirectly through foundry capacity reservations and technology roadmapping.
Foundries dominate installed base. Memory Manufacturers are where expansion concentrates.
Application:
End-use application shapes equipment specifications, with automotive electronics pulling mature-node tools for reliability certification while consumer electronics drives fastest node migration.
- Consumer Electronics:Smartphones, tablets, and personal computers require leading-edge logic and memory chips, concentrating demand for EUV lithography and advanced packaging equipment. Taiwan and South Korea fabrication complexes serve Apple, Qualcomm, and MediaTek processor requirements.
- Automotive Electronics:Electric vehicle powertrains and advanced driver assistance systems multiply microcontroller and power semiconductor content, pulling 28 nanometer and 40 nanometer capacity expansion across legacy node equipment.
- Telecommunications:5G baseband processors and network infrastructure chips require mixed-signal and RF specialty processes.
- Industrial Electronics:Factory automation and power management applications favor mature-node analog and discrete devices.
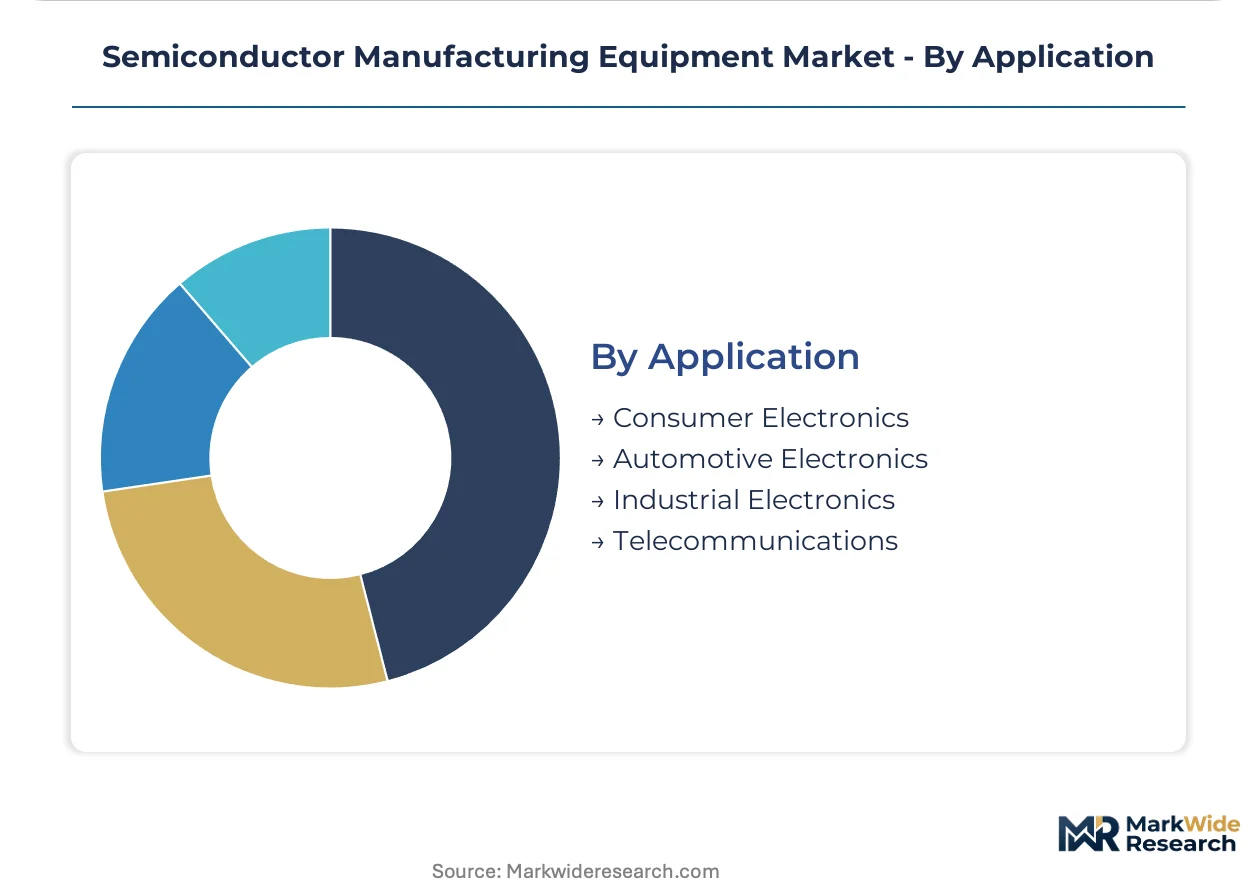
Consumer Electronics dominates installed base. Automotive Electronics is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply by geography: Taiwan and South Korea concentrate leading-edge lithography investments, while the United States and China prioritize legacy-node capacity expansion and supply chain resiliency respectively.
United States
CHIPS Act disbursements are accelerating fab construction in Arizona and Texas, with Intel and TSMC breaking ground on advanced node facilities. EPA regulations govern chemical handling in these new fabrication complexes. Phoenix anchors the Southwest cluster where utility infrastructure commitments are unlocking land acquisition timelines.
Taiwan
TSMC's fabrication complexes drive the highest lithography equipment density globally, with EUV scanner queues extending delivery timelines. Domestic regulators enforce water and energy use permits that constrain expansion velocity. Hsinchu Science Park concentrates the island's most advanced process development and equipment qualification activity.
South Korea
Samsung Foundry and SK Hynix are multiplying deposition chamber counts for three-dimensional memory architectures. MFDS oversight applies to semiconductor components destined for medical devices in adjacent electronics sectors. Pyeongtaek anchors the memory manufacturing belt where 3D NAND stacking is driving etch platform procurement.
Japan
Tokyo Electron and SCREEN Semiconductor Solutions anchor domestic equipment supply chains serving global foundry customers. METI coordinates export controls on advanced manufacturing tools through multilateral agreements. Kyoto-Osaka corridor concentrates thermal processing and coat-develop-track system development.
China
Domestic foundries are expanding mature-node capacity at 28nm and above as tool access restrictions constrain leading-edge development. MIIT allocates subsidies for localization of deposition and etch platforms. Shanghai and Beijing anchor the Yangtze River Delta and northern clusters where SMIC and Hua Hong are qualifying indigenous equipment.
Semiconductor Manufacturing Equipment Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Lithography and metrology platforms consolidate around a handful of technology owners, while deposition and etch equipment fragments across specialized chamber designers and integrated process module suppliers. Three archetypes dominate: precision optics specialists, vacuum process platform builders, and process control analytics providers. Competitive moves center on backward integration into critical subsystems and geographic expansion through localized service hubs.
Among Dutch and Japanese precision equipment builders, ASML Holding NV and Tokyo Electron occupy positions that exemplify the capability-concentrated tier, while Applied Materials represents the diversified platform archetype spanning multiple process steps. These three anchors illustrate how lithography supremacy, thermal processing dominance, and breadth across deposition and etch create distinct competitive moats.
| Leading Market Players |
|---|
| Tokyo Electron |
| Advantest |
| ASML Holding NV |
| Teradyne |
| SCREEN Semiconductor Solutions |
| Applied Materials |
| KLA |
| ASM International |
| Lam Research |
| Others |
Supply Flow & Price Mechanics
Japanese and German precision optics suppliers capture disproportionate margin pools downstream as lithography system OEMs negotiate multi-year source module contracts. Equipment buyers face compressed bargaining leverage when scanner delivery queues extend, transferring pricing power upstream toward vacuum chamber and laser source manufacturers.
Pricing Analysis
Long-term offtake agreements dominate lithography equipment procurement, with foundries committing to multi-scanner orders years ahead of fab completion. Price differentiation hinges on EUV source power tier and metrology integration depth, with high-NA configurations commanding premium positioning. Cost compression in mature-node deposition tools is intensifying as Chinese domestic suppliers expand ALD chamber availability. Memory manufacturers exhibit highest price sensitivity due to cyclical capital intensity, while logic foundries prioritize yield assurance over unit cost.
Supply Chain Analysis
High-purity neon feedstock draws from Ukrainian purification facilities and Russian crude gas separation plants, creating geographic concentration risk. Specialized ceramic components and precision motion systems rely on Japanese and German supplier networks. Single-source vulnerability around tin droplet generators for EUV light production constrains ASML's scanner output scalability. Distribution runs through direct OEM-fab relationships for critical platforms, with secondary channels handling refurbishment and mature-node tool resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement consortia as TSMC, Samsung, and Intel jointly negotiate chamber components, compressing supplier margins across non-critical subsystems.
For Market Incumbents: Harden service contract penetration across installed deposition and etch platforms to offset equipment sales cyclicality. Backward integration into vacuum pump refurbishment capabilities defends against emerging third-party service providers. Prioritize certification investment for REACH-compliant wet chemistry handling systems as European substitution deadlines tighten. For New Entrants and Emerging Players: Establish a beachhead in India semiconductor mission greenfield sites where indigenous equipment qualification creates procurement windows for deposition and etch platforms. Target certified refurbishment networks for 200mm mature-node tools serving analog and power device manufacturers. Lead with localized service hubs and spare parts inventory commitments rather than technology differentiation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metrology and process control specialists that consolidated during the last downturn. Five-to-ten year viability favors equipment OEMs with recurring revenue streams exceeding forty percent of total sales. Watch EUV pellicle durability improvements as the signal indicating scanner uptime inflection and aftermarket service demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Pilot Production | Intel's Oregon development fab validates single-expose patterning at 8nm pitch for foundry adoption. |
| Backward Integration into Vacuum Subsystems | Applied Materials expands captive supply of cryogenic pumps to reduce lead time volatility. |
| REACH-Compliant Chemistry Validation | Tokyo Electron qualifies PFAS-free etchants for ECHA sunset deadlines in Ireland and Germany. |
| Hybrid Bonding Process Module Development | Lam Research positions etch platforms for 3D memory-on-logic stacking beyond HBM packaging. |
| India Greenfield Equipment Localization | ASM International establishes ALD chamber assembly for Gujarat display driver fab requirements. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with fab engineering directors, equipment procurement managers, vacuum technician training program leads, and aftermarket service heads. Secondary validation drew from SEMI equipment billings data, SEC 10-K filings of listed OEMs, CHIPS Act disbursement disclosures, and ECHA REACH authorization registers. Bottom-up unit deployment estimates were triangulated against top-down capital expenditure forecasts across the analysis window.
Calibration against historical lithography scanner delivery schedules and deposition chamber shipment patterns anchored the projection framework. Segmentation dimensions modeled include equipment type, technology node tier, end-user category, and regional regulatory cluster. CAGRs were derived from equipment intensity ratios per wafer capacity and foundry technology roadmaps. Forecast inputs incorporated EUV source power evolution timelines and hybrid bonding adoption curves for 3D architectures.
Stress conditions across neon gas supply disruption, METI export licensing delays, and high-NA EUV insertion timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry capital commitment velocity and memory manufacturer capacity discipline. Quarterly review of scanner delivery queue lengths and vacuum technician certification program throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Lithography Systems Market