
 Stencil Lithography Market | 2026-2036
Stencil Lithography Market Size, Share, and Industry Trends Forecast 2026-2036
Stencil Lithography Market Analytics
Equipment leasing and pay-per-use models for stencil lithography tools are reshaping competitive entry barriers for smaller foundries and research institutions. EV Group leverages its European installed base to sustain recurring service revenue across nanoimprint installations. Nikon Corporation anchors its position through deep ultraviolet optics specialization that extends into stencil-compatible illumination systems. SUSS MicroTec SE competes on substrate handling automation that integrates with multiple lithography modes.
Stencil lithography employs a physical mask with apertures to transfer patterns onto substrates without optical projection, typically achieving resolution below 100 nanometer through direct mechanical or proximity exposure. The method serves semiconductor prototyping, MEMS fabrication, and nanostructure research where photomask costs for low-volume production prove prohibitive. E-beam lithography dominates precision-demanding applications where direct-write flexibility offsets throughput limits, while nanoimprint lithography leads in cost-sensitive nanostructure replication for optoelectronics. UV lithography occupies the mature volume tier serving fabrication facilities with established mercury lamp infrastructure and standardized photoresist protocols.
FDA oversight of diagnostic nanodevices and EPA emissions rules for fab chemistry influence stencil lithography demand in biomedical and domestic manufacturing applications respectively. ISO cleanroom standards and SEMI equipment guidelines shape tool certification requirements that OEMs and foundries must satisfy for market access. Stakeholders should monitor how REACH chemical restrictions and emerging PFAS regulations alter photoresist formulations and mask cleaning chemistries ahead of qualification cycles.
Market Dynamics
Semiconductor foundries are accelerating stencil lithography adoption as EUV mask costs escalate for sub-7nm prototyping, while China's dual carbon goals force fabs toward lower-energy patterning methods that reduce process thermal loads.
Growth Catalysts
- Dual Carbon Goals (China):MEE emissions rules are compelling domestic fabs to replace high-energy optical systems with stencil-based proximity exposure that cuts per-wafer energy consumption.
- MEMS Fabrication:Automotive sensor manufacturers in Germany and Japan are adopting stencil lithography for piezoelectric actuator prototyping where photomask economics fail.
- Advanced Node Prototyping:Taiwan's semiconductor cluster is deploying stencil tools for rapid process validation before committing to million-dollar EUV mask sets.
Market Restraints
- Photomask Material Costs:Silicon nitride membrane substrates for stencil masks remain concentrated among Japanese suppliers, creating input cost volatility during supply shocks.
- Throughput Limitations:Mechanical contact exposure cannot match stepper speeds, restricting stencil lithography to low-volume runs below 10,000 wafer equivalents annually.
- Substitution by Nanoimprint:EV Group's nanoimprint systems are capturing optoelectronics nanostructure replication where stencil methods previously dominated cost-sensitive segments.
Strategic Opportunities
- Biomedical Nanodevices:FDA diagnostic device pathways are opening for stencil-patterned biosensors, creating a regulated channel with premium pricing power.
- Quantum Dot Patterning:Convergence of stencil lithography with atomic layer deposition is enabling single-quantum-dot placement for photonic computing applications.
- Equipment Leasing Models:Pay-per-use contracts are lowering entry barriers for research institutions in South Korea and the Netherlands, expanding the addressable customer base beyond capital-rich foundries.
Industry Challenges
- Cleanroom Certification Timelines:ISO 14644-1 Class 1 compliance for stencil tools requires 18-24 month qualification cycles that delay revenue recognition for OEMs.
- Mask Defect Detection:Automated aperture inspection systems lack the throughput to match production stencil consumption, forcing manual quality protocols that bottleneck fab workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stencil Lithography Market |
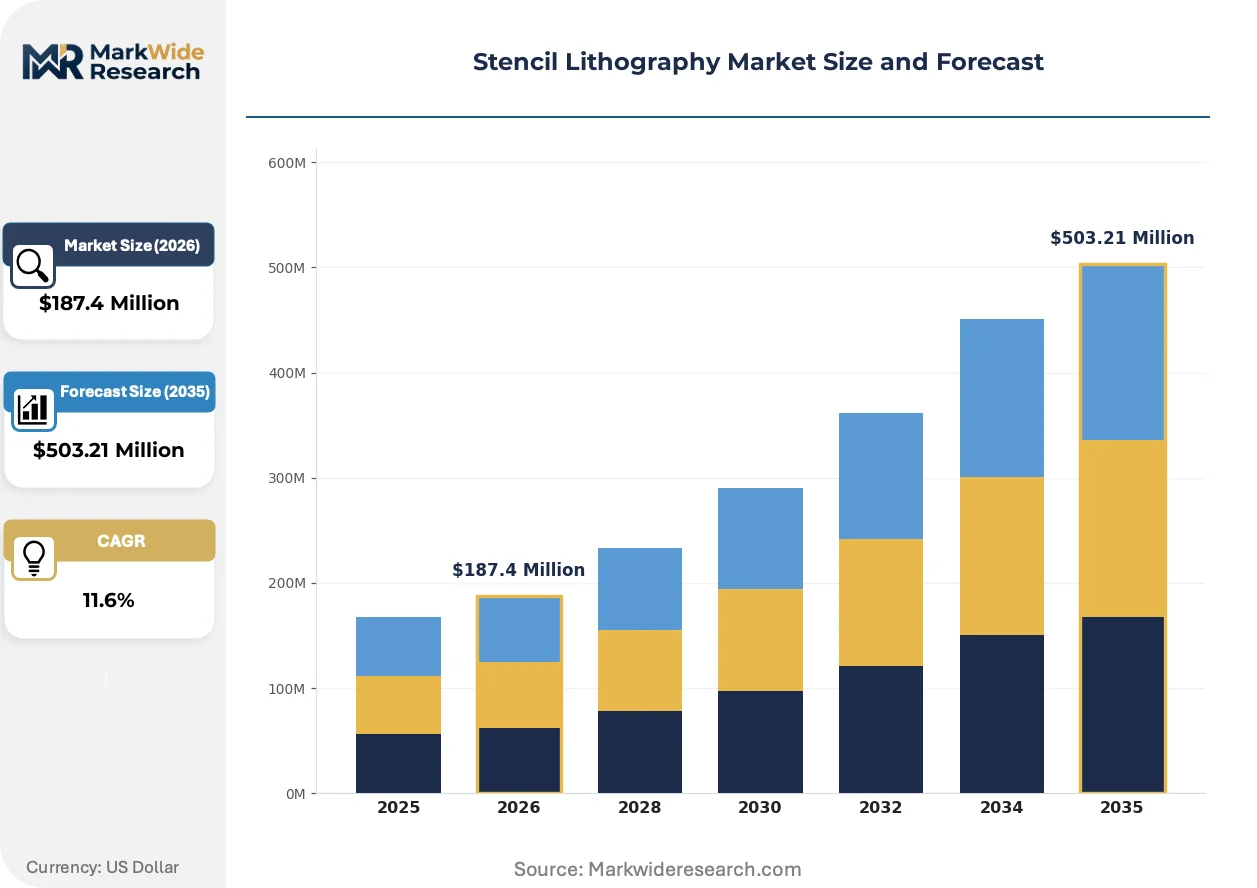
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: UV Lithography, E-Beam Lithography, Nanoimprint Lithography, Hybrid Lithography Application: Semiconductors, MEMS, Nanostructures, Optoelectronics Material: Silicon Wafers, Photoresists, Metals, Dielectrics End User: OEMs, Foundries, Research Institutions, Fabrication Facilities |
| Companies Covered | ASML Holding N.V., Nikon Corporation, Canon Inc., EV Group, Nanonex Corporation, NIL Technology ApS, Raith GmbH, SUSS MicroTec SE, Vistec Electron Beam GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stencil Lithography Market Evolving Landscape
Stencil lithography is undergoing functional expansion beyond semiconductor prototyping into biomedical and quantum applications, driven by mask fabrication advances and regulatory pressure on energy-intensive alternatives.
Hybrid stencil-e-beam systems are hybridizing process flows by combining mechanical mask patterning with localized electron beam trimming. Memory manufacturers in South Korea are piloting this approach for 3D NAND contact layer development, compressing the iteration cycle from months to weeks by eliminating full mask respins for design tweaks.
REACH chemical restrictions are forcing reformulation of photoresist chemistries used in stencil mask cleaning cycles. ECHA's 2024 PFAS limitations are particularly acute for fluorinated solvents in membrane preparation, pushing German equipment suppliers toward aqueous-based cleaning protocols that extend mask lifetime but require redesigned process chambers.
Research institutions are consolidating procurement through shared cleanroom consortia rather than individual tool ownership. The Netherlands' NanoLabNL and Japan's AIST facilities now pool stencil lithography access across university and corporate users, with usage fees replacing capital expenditure in funding models most visible across European nanofabrication networks.
Stencil Lithography Market Segmentation
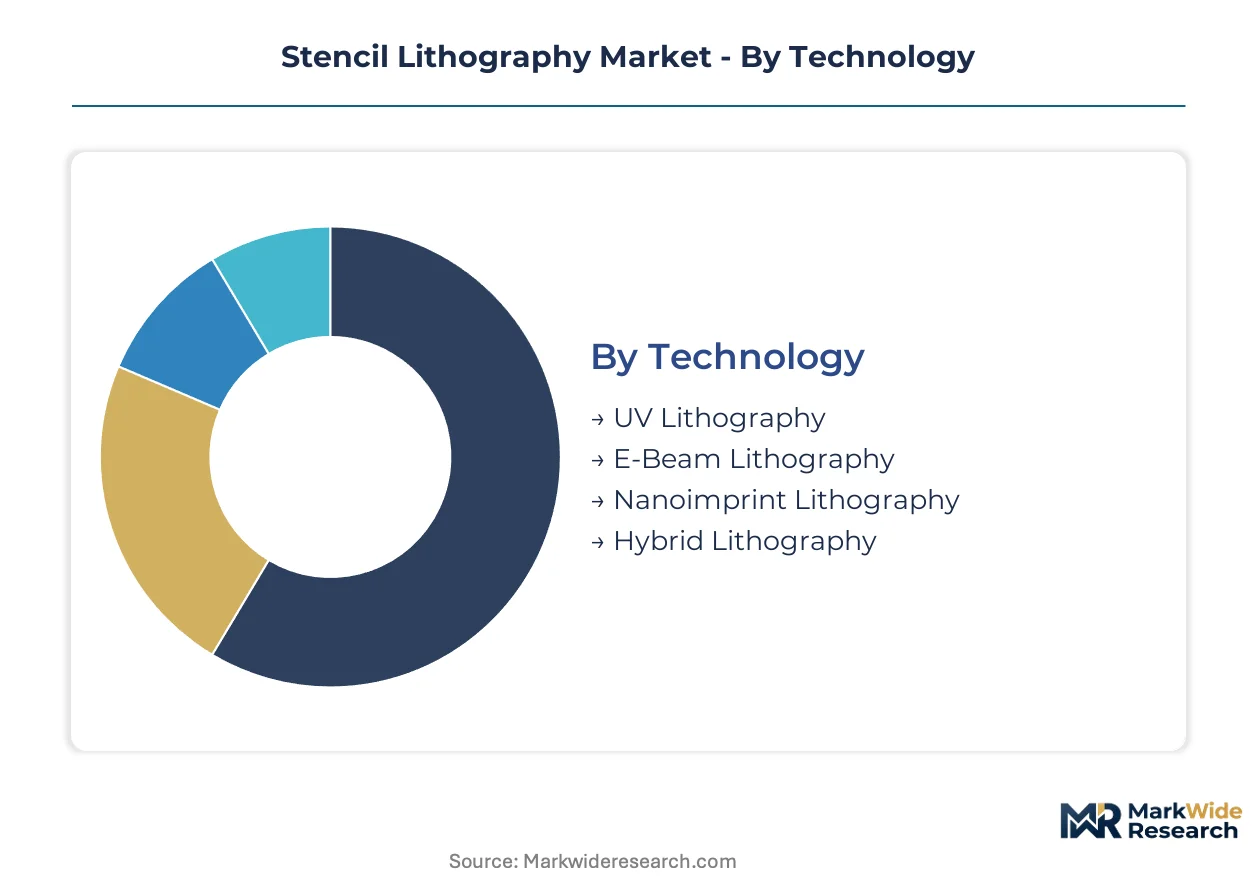
Stencil lithography market segmentation reveals distinct service intensity profiles across technology platforms and user types. Equipment complexity and mask replacement frequency create divergent aftermarket revenue streams that reshape vendor profitability calculations.
Technology:
After-sales-service intensity varies sharply across lithography modalities, with mask refurbishment and chamber maintenance driving recurring revenue differentiation.
- UV Lithography:Mercury lamp systems dominate volume fabrication with standardized photoresist protocols. Taiwan's semiconductor cluster sustains demand for proximity UV exposure tools that balance resolution against throughput in mature node prototyping.
- E-Beam Lithography:Direct-write electron beam systems achieve sub-10 nanometer precision through focused spot scanning without physical masks. German automotive sensor manufacturers leverage e-beam flexibility for piezoelectric actuator iteration where photomask economics fail.
- Nanoimprint Lithography:Mechanical pattern replication using master templates. EV Group's installed base generates substantial service contracts across European nanofabrication networks.
- Hybrid Lithography:Combines stencil mask patterning with localized electron beam trimming for design tweak flexibility. South Korean memory manufacturers pilot this approach for 3D NAND contact layer development.
UV Lithography holds the largest share; momentum sits with Hybrid Lithography.
Application:
Cost tier stratification separates premium prototyping applications from volume nanostructure replication segments.
- Semiconductors:Advanced node prototyping and process validation before million-dollar EUV mask commitments. China's MEE emissions rules compel domestic fabs toward lower-energy stencil methods.
- MEMS:Microelectromechanical systems fabrication for automotive and consumer sensors. Japan's AIST facilities pool stencil access across corporate and university users.
- Nanostructures:Research-scale patterning for academic and government laboratories. The Netherlands' NanoLabNL consortium replaces individual tool ownership with usage-based funding models.
- Optoelectronics:Quantum dot placement and photonic component patterning where nanoimprint methods increasingly displace stencil approaches.
Semiconductors command the highest equipment pricing; Nanostructures are climbing the fastest.
Material:
Customer type concentration determines procurement scale, with foundries negotiating volume contracts against research institutions seeking flexible access terms.
- Silicon Wafers:Standard substrates for semiconductor and MEMS applications with established supply chains.
- Photoresists:Light-sensitive polymers requiring reformulation under REACH chemical restrictions and ECHA PFAS limitations.
- Metals:Electrode and interconnect materials patterned through stencil apertures for sensor electrodes.
- Dielectrics:Insulating layers in multilayer device stacks where atomic layer deposition convergence enables single-quantum-dot placement.
Silicon Wafers anchor volume demand; Photoresists face the steepest regulatory pressure.
End User:
Geography shapes equipment deployment patterns, with East Asian manufacturing clusters exhibiting distinct procurement behaviors versus European research networks.
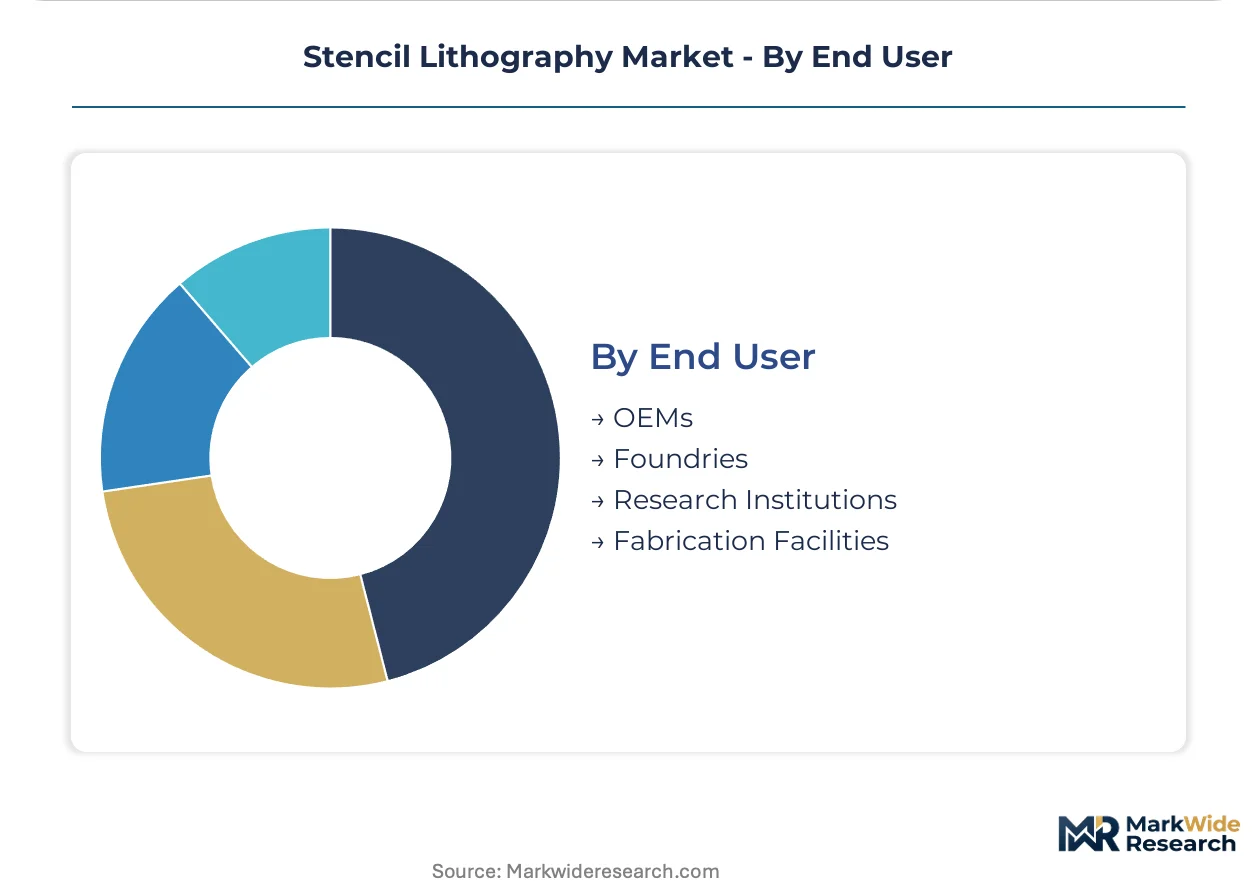
- OEMs:Original equipment manufacturers integrating stencil tools into production lines for captive component supply.
- Foundries:Contract manufacturers serving fabless semiconductor designers with rapid prototyping services.
- Research Institutions:Universities and government laboratories accessing shared cleanroom consortia rather than individual ownership.
- Fabrication Facilities:Dedicated production sites with ISO 14644-1 Class 1 compliance requirements extending qualification timelines.
Foundries represent the largest installed base; Research Institutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates among foundries in Taiwan, South Korea, and China alongside research consortia in Germany and the Netherlands. Each geography exhibits distinct regulatory pressures and cluster dynamics that reshape stencil lithography deployment patterns.
Taiwan
Semiconductor foundries in Hsinchu Science Park deploy stencil tools for EUV mask validation before committing to million-dollar photomask sets. The National Development Council's advanced manufacturing incentives support prototyping infrastructure investments. Tainan and Taichung facilities extend stencil access to fabless designers seeking rapid iteration cycles.
South Korea
Memory manufacturers in Yongin and Icheon pilot hybrid stencil-e-beam systems for 3D NAND contact layer development. The Ministry of Trade, Industry and Energy prioritizes domestic lithography equipment sourcing under its K-Semiconductor Belt initiative. Seoul National University and KAIST pool stencil access through shared nanofabrication centers.
China
Domestic fabs in Shanghai and Beijing replace high-energy optical systems with stencil-based proximity exposure to comply with MEE emissions rules under dual carbon goals. MIIT localization mandates accelerate procurement of indigenous patterning equipment. Wuxi and Hefei clusters integrate stencil tools into MEMS sensor production lines.
Germany
Automotive sensor manufacturers in Stuttgart and Munich adopt stencil lithography for piezoelectric actuator prototyping where photomask economics fail. ECHA's 2024 PFAS limitations force reformulation of fluorinated solvents in membrane preparation. Fraunhofer institutes in Dresden and Erlangen operate shared cleanroom facilities with usage-based access models.
Netherlands
Research institutions consolidate procurement through NanoLabNL consortiums spanning Delft, Eindhoven, and Twente. The Dutch Research Council's nanofabrication infrastructure grants replace individual tool ownership with pooled access fees. ASML's Veldhoven headquarters anchors regional optics expertise that extends into stencil-compatible illumination component supply.
Stencil Lithography Market Competitive Landscape
Channel-controlling players compete with product-specialist players across equipment sales, mask supply, and service contracts. The vendor base spans three tiers: lithography system integrators, substrate handling automation suppliers, and mask fabrication specialists. Two strategic archetypes dominate: European precision equipment manufacturers and East Asian optics conglomerates. Competitive moves concentrate on strategic partnerships for hybrid system development and geographic expansion through research consortium installations.
Within the precision equipment tier, EV Group and SUSS MicroTec SE represent European specialists with established service revenue models across nanoimprint and stencil installations. Nikon Corporation anchors the optics-integrated segment through deep ultraviolet illumination expertise. These three exemplify divergent positioning: EV Group leverages recurring service contracts, SUSS MicroTec SE competes on substrate handling automation, and Nikon extends optical system specialization into proximity exposure compatibility.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Nikon Corporation |
| Canon Inc. |
| EV Group |
| Nanonex Corporation |
| NIL Technology ApS |
| Raith GmbH |
| SUSS MicroTec SE |
| Vistec Electron Beam GmbH |
| Others |
Value Network & Pricing Analysis
Shanghai-Yokohama container freight corridors absorb volatile bunker fuel surcharges that cascade through silicon nitride membrane supply chains, compressing margins for Japanese mask substrate suppliers while amplifying price spreads between ISO-certified OEM tools and research-grade installations.
Pricing Analysis
Cost-plus contracts with quarterly silicon wafer indexation dominate equipment procurement between foundries and lithography OEMs. Three-tier pricing structure across premium, standard, and economy levels separates EUV-compatible hybrid systems from proximity UV tools and refurbished research units. Pricing pressure stems from nanoimprint substitution in optoelectronics segments where stencil methods previously held cost advantage. Research institutions exhibit highest price sensitivity due to pooled consortium funding models, while Taiwan foundries prioritize throughput specifications over unit cost.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese membrane substrate producers ease working capital constraints for German equipment manufacturers during 18-month qualification cycles. Silicon nitride membrane fabrication concentrates in Japan, silicon wafer supply anchors in Taiwan and South Korea, and precision motion systems source from Germany. Photoresist chemistry reformulation under ECHA PFAS restrictions creates single-source vulnerability for fluorinated solvent alternatives. Distribution runs through direct OEM sales for foundry-tier volumes and regional distributor networks for research institution procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through shared cleanroom consortia that consolidate procurement across multiple research institutions, fragmenting individual vendor relationships while amplifying volume leverage for pooled equipment access.
For Market Incumbents: Pre-empt nanoimprint displacement in biomedical nanodevice segments by securing FDA diagnostic pathway partnerships before EV Group extends its nanoimprint service contracts. Deepen backward integration into silicon nitride membrane production to offset Japanese supplier concentration risk. Anchor recurring revenue through multi-year service contracts that lock in refurbishment schedules before research consortia finalize pooled procurement terms.
For New Entrants and Emerging Players: Build out equipment leasing infrastructure targeting South Korean and Dutch research consortia where pay-per-use models replace capital expenditure. The Netherlands' NanoLabNL and Seoul National University shared facilities represent the most penetrable entry points. Lead with aqueous-based mask cleaning system sales that address ECHA PFAS compliance gaps in existing German equipment installations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming lithography equipment divisions lacking service revenue scale. Long-term viability hinges on recurring aftermarket income rather than front-loaded equipment sales. Monitor MIIT localization mandate enforcement intensity in China as inflection indicator for indigenous equipment procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Development | Combines stencil patterning with e-beam trimming for 3D NAND iteration cycles at South Korean memory manufacturers. |
| PFAS-Compliant Chemistry Transition | Aqueous cleaning protocols extend mask lifetime while satisfying ECHA 2024 fluorinated solvent restrictions. |
| Consortium Access Model Expansion | Pooled cleanroom procurement across Netherlands NanoLabNL replaces individual tool ownership with usage fees. |
| MEMS Sensor Production Integration | Automotive piezoelectric actuator prototyping in Stuttgart and Munich adopts stencil methods where photomask economics fail. |
| Quantum Dot Placement Convergence | Atomic layer deposition integration enables single-quantum-dot patterning for photonic computing applications. |
Research Methodology
Operator-level perspectives from fab process engineers, equipment procurement managers, cleanroom facility directors, and photoresist formulation chemists anchored the qualitative base. Primary interviews combined with secondary validation from SEMI equipment shipment databases, MEE emissions compliance filings, and ECHA chemical restriction notices. Bottom-up equipment unit estimates triangulated against top-down foundry capex allocation patterns.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated adoption pathways. Segmentation dimensions spanned technology modality, application sector, material type, and end-user archetype across the analysis window. CAGRs derived from equipment replacement cycles, node migration timelines, and regulatory compliance phase-in schedules. Forecast inputs incorporated EUV mask cost escalation trajectories and dual carbon policy enforcement intensity.
Stress conditions across membrane substrate supply disruption, REACH chemical reformulation delays, and research funding contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about equipment qualification timelines and consortium procurement adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market