
 Solder Paste Market | 2026-2036
Solder Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Solder Paste Market Intelligence
The European Union's Restriction of Hazardous Substances (RoHS) directive is expanding the research and development investment required for market entry. This shift toward lead-free formulations benefits large, diversified chemical firms. Henkel AG & Co. KGaA leverages its global scale and extensive material science expertise to offer compliant solutions. Indium Corporation differentiates through its focus on high-performance pastes for advanced applications like semiconductor packaging.
Solder paste is a material used in electronics manufacturing to connect components to printed circuit boards. It consists of a suspension of microscopic solder spheres within a flux vehicle, with formulations defined by alloy composition and particle size. Its primary function is to form reliable electrical and mechanical joints during the reflow soldering process. Lead-free product types now command the largest market share, driven by regulatory mandates, while the consumer electronics application segment remains the principal source of volume demand.
Compliance with chemical regulations like the EU's REACH framework and China's GB standards is a critical prerequisite for market access. These rules, alongside quality benchmarks like ISO 9001, dictate allowable alloy compositions and manufacturing practices. Formulators must therefore navigate a complex matrix of performance requirements and evolving environmental legislation. The key decision for manufacturers is how to invest in novel alloy research to meet the demands of next-generation electronics.
Market Dynamics
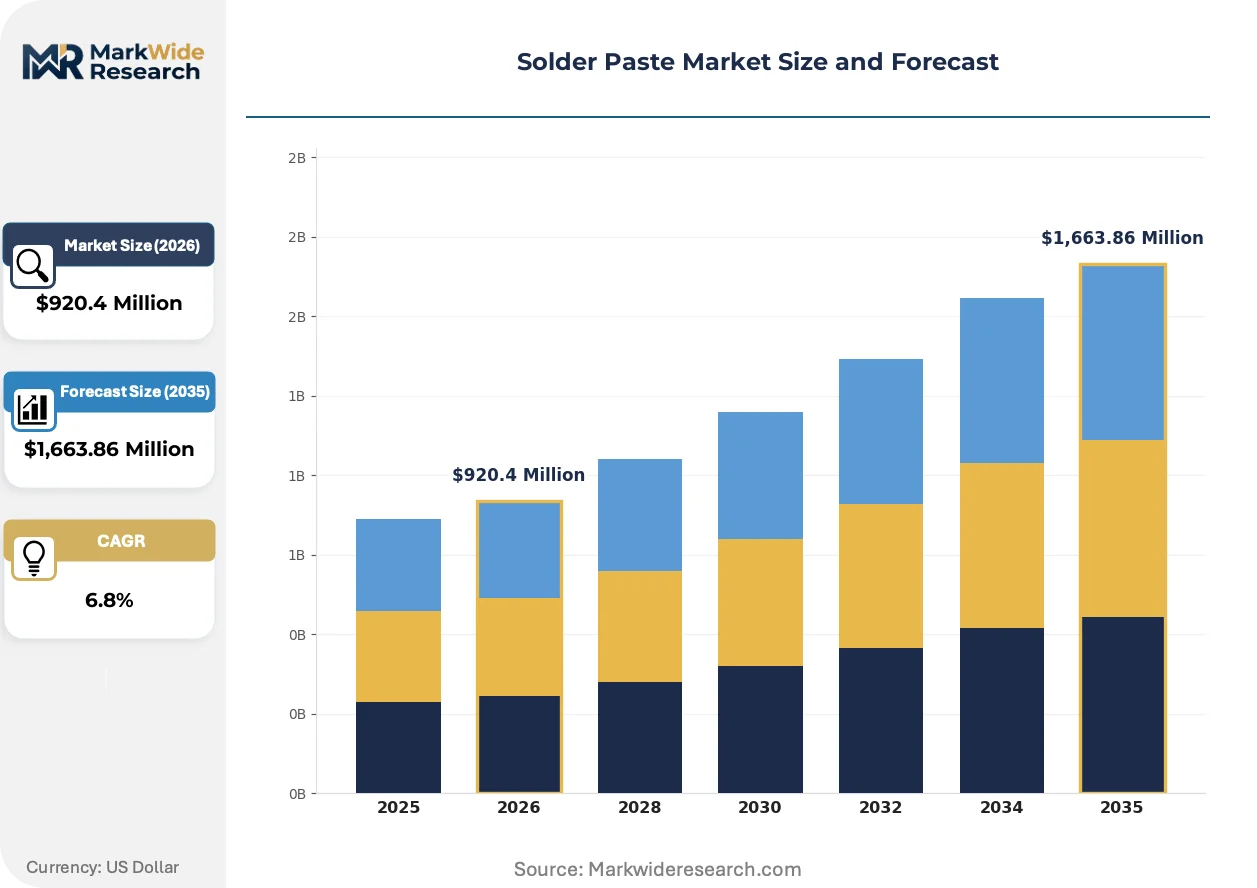
The solder paste market is defined by the dual pressures of electronics miniaturization and stringent environmental regulations. The transition to lead-free alloys, mandated by frameworks like the EU's RoHS directive, dictates material science innovation and investment priorities for all formulators.
Growth Catalysts
- 5G Infrastructure:Demand for high-frequency electronics for 5G base stations necessitates advanced solder pastes with superior signal integrity and thermal management properties.
- Automotive Electronics:The proliferation of ADAS and EV battery management systems creates substantial volume demand for high-reliability solder formulations that can withstand harsh operating conditions.
- RoHS Directive:The EU's RoHS framework continues to compel the global transition away from leaded solders, expanding the market for compliant lead-free alternatives.
Market Restraints
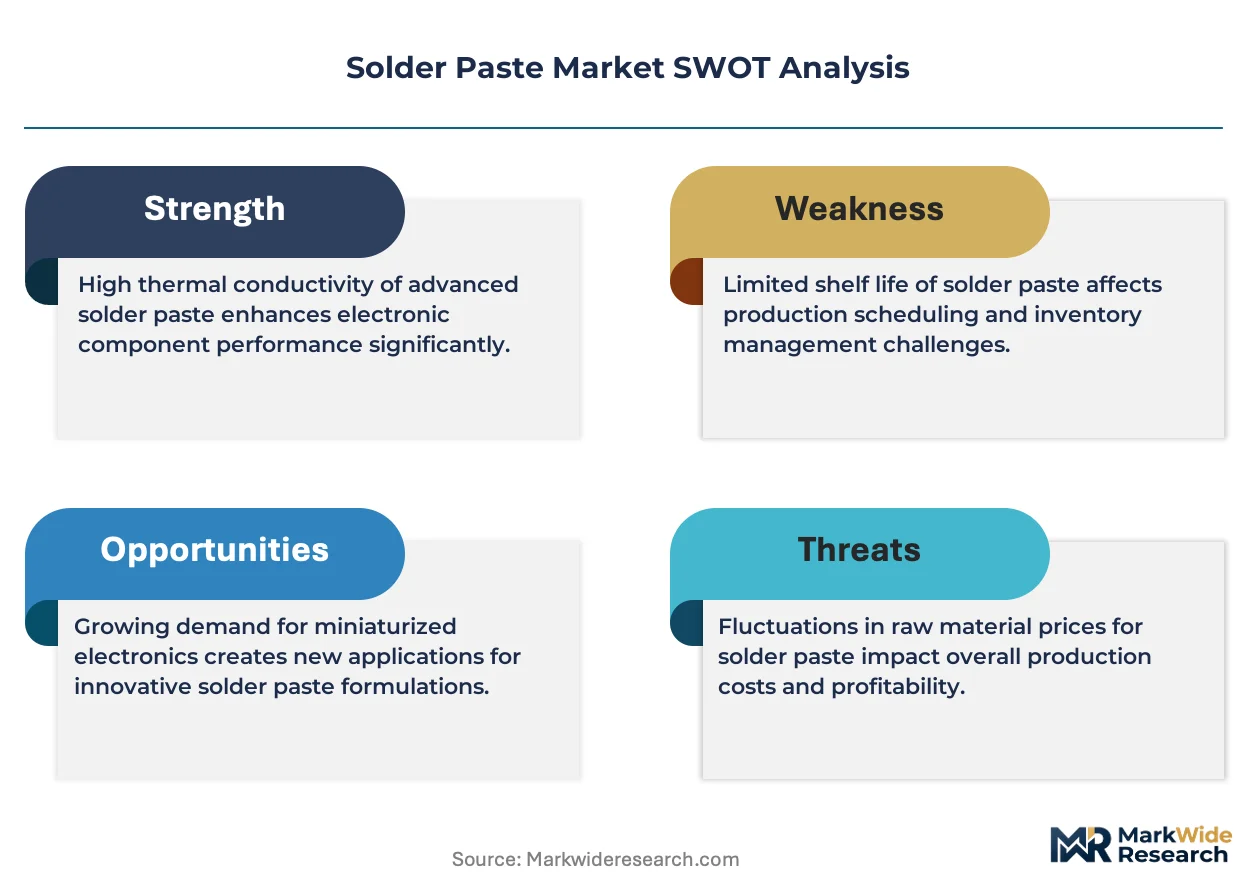
- Input Cost Volatility:Price fluctuations in tin and silver, primary components of lead-free alloys, directly impact manufacturing costs and compress margins for paste formulators.
- Technical Hurdles:Higher reflow temperatures for many lead-free solders increase thermal stress on electronic components and complicate manufacturing process control.
- Concentrated Powder Supply:The supply of high-purity metal powders is concentrated among a few global producers, creating potential supply chain bottlenecks for paste manufacturers.
Strategic Opportunities
- Low-Temperature Solders:Bismuth- and indium-based alloys for heat-sensitive components and flexible electronics represent a significant growth area outside of traditional tin-based chemistries.
- Emerging Assembly Hubs:Expanding electronics manufacturing in Vietnam and Mexico creates new geographic markets for suppliers beyond traditional centers in China.
- Advanced Packaging Materials:The shift to System-in-Package designs in semiconductors demands new pastes with ultra-fine particle sizes and specific rheological properties.
Industry Challenges
- Regulatory Compliance Maze:Formulators must navigate a complex and divergent set of chemical regulations, including the EU's REACH and China's GB standards, increasing compliance costs.
- Fine-Pitch Printing Defects:Miniaturization toward finer component pitches increases the difficulty of stencil printing, raising the risk of costly defects like solder bridging and voiding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solder Paste Market |
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,663.86 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Free, Leaded, Halogen-Free, No-Clean, Water Soluble Application: Consumer Electronics, Telecommunication Equipment, Industrial Machinery, Aerospace Systems, Defense Electronics Alloy Composition: Sn-Ag-Cu, Sn-Pb, Sn-Cu, Sn-Bi, Sn-Ag End User Industry: OEMs, Electronics Contract Manufacturers, Printed Circuit Board Assemblers, Tier-1 Suppliers |
| Companies Covered | Element Solutions Inc., AIM Solder Technologies LLC, Henkel AG & Co. KGaA, Interflux Electronics N.V., KOKI Company, Ltd., Indium Corporation, Senju Metal Industry Co., Ltd., MULTICORE Soldering Products Ltd., Nihon Superior Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solder Paste Market Strategic Shifts & Innovations
Solder paste evolution is driven by the twin demands of performance miniaturization and material sustainability. Formulators are developing next-generation materials to meet tighter process windows for advanced electronics while adhering to a growing list of restricted substances.
Nanoparticle-infused solder pastes improve mechanical strength and thermal conductivity for demanding applications. The automotive and aerospace sectors are adopting these for high-reliability electronics where failure is not an option. This development is modularizing the formulation process, enabling paste properties to be precisely tuned by adjusting nanoparticle additives for specific end-uses.
The EU's REACH regulation imposes stringent registration and evaluation requirements on all chemical substances within solder paste formulations. This mandate increases the R&D burden and documentation overhead for producers, creating higher barriers to market entry. Specialty and high-performance paste segments are most affected, as formulators must now justify every alloy and flux additive to sell within Europe.
Electronics OEMs are consolidating their supplier base for critical materials to enhance supply chain resilience and ensure quality consistency. This trend disadvantages smaller, regional players in favor of large, global formulators capable of supporting manufacturing in China, Vietnam, and Mexico. The shift is most pronounced in the high-volume consumer electronics sector, where scale and global logistics are paramount.
Solder Paste Market Segmentation
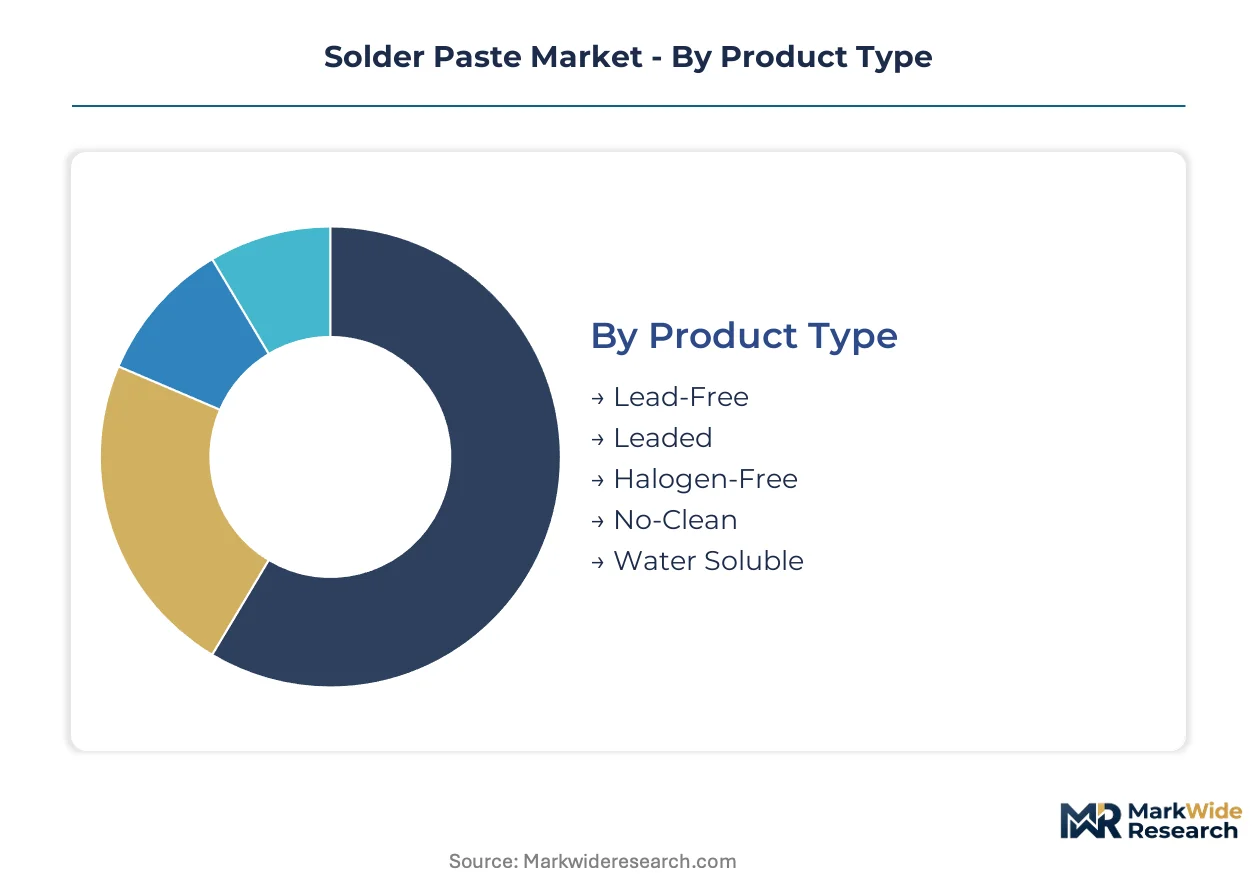
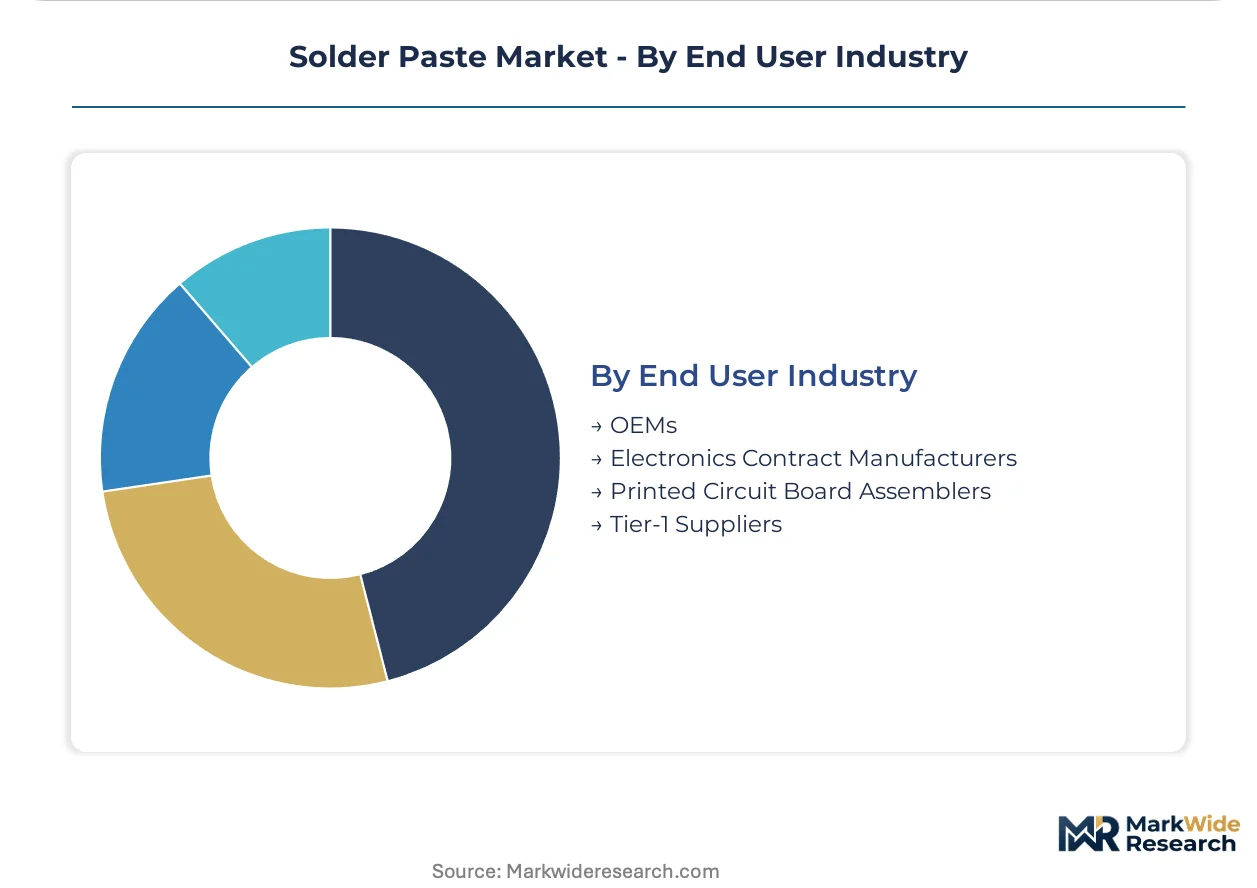
The solder paste market segments across multiple dimensions, reflecting the diverse material science, application demands, and regulatory landscapes. Understanding these classifications is critical for manufacturers to align product development with specific industry requirements and market trends.
Product Type:
The supply concentration for solder paste product types reflects the specialized material science required for each formulation.
- Lead-Free:Composed primarily of tin with silver and copper additions, these formulations avoid hazardous lead, meeting environmental mandates. Consumer electronics assembly in Germany and Japan drives adoption, compelled by stringent environmental regulations like RoHS.
- No-Clean:These pastes contain flux residues that do not require post-soldering cleaning, simplifying manufacturing processes. Electronics Contract Manufacturers in China and Mexico increasingly utilize no-clean pastes to reduce production costs and improve throughput.
- Halogen-Free:These formulations exclude halogenated compounds, meeting stricter environmental standards for electronic components.
- Water Soluble:Flux residues from these pastes are easily removed with water-based cleaning processes, often used in specific industrial applications.
- Leaded:Containing tin and lead, these traditional pastes offer lower melting points but face declining demand due to global regulatory restrictions.
Today's leader: Lead-Free. Tomorrow's challenger: Halogen-Free.
Application:
Application segments dictate specific performance requirements and volume demands for solder paste formulations.
- Consumer Electronics:This segment encompasses high-volume production of smartphones, laptops, and wearables, requiring cost-effective and reliable paste solutions. Mass production facilities in Vietnam and China drive substantial volume, prioritizing high throughput and minimal defect rates.
- Automotive Electronics:Solder pastes for this segment must withstand extreme temperatures and vibrations, crucial for ADAS modules and EV battery management systems. Tier-1 suppliers in Germany and South Korea demand high-reliability formulations for safety-critical components.
- Telecommunication Equipment:This segment includes base stations and network infrastructure, requiring pastes with superior signal integrity for high-frequency applications.
- Industrial Machinery:Pastes for industrial controls and automation equipment need durability and consistent performance in harsh operating environments.
- Aerospace Systems:This demanding sector requires ultra-high reliability pastes capable of performing under extreme thermal cycling and mechanical stress.
Consumer Electronics continues to drive the largest volume, while Automotive Electronics exhibits the steepest expansion trajectory due to electrification trends.
Alloy Composition:
The alloy composition directly influences the material cost and processing characteristics of solder paste.
- Sn-Ag-Cu:This lead-free alloy, often referred to as SAC, provides excellent mechanical strength and thermal fatigue resistance. Advanced packaging applications in Taiwan and Singapore increasingly specify Sn-Ag-Cu for its robust performance.
- Sn-Bi:Bismuth-tin alloys offer lower melting points, making them suitable for temperature-sensitive components and flexible substrates. Emerging applications in flexible electronics manufacturing in China and the US are driving innovation for Sn-Bi formulations.
- Sn-Pb:Traditional tin-lead alloys offer good wettability and low cost, but their use is restricted by environmental regulations.
- Sn-Cu:These lead-free alloys are a cost-effective alternative to SAC, used in less demanding applications.
- Sn-Ag:Tin-silver alloys provide good mechanical properties and are suitable for specific high-reliability applications.
Innovation in alloy composition focuses on developing novel low-temperature solutions and enhancing reliability for high-performance applications.
End User Industry:
Customer type defines the procurement patterns and technical support requirements for solder paste suppliers.
- Electronics Contract Manufacturers:These firms specialize in assembling electronic products for various brands, requiring diverse paste formulations for different client specifications. Large-scale EMS providers in Mexico and Malaysia drive significant volume, seeking consistent supply and technical support.
- OEMs:Original Equipment Manufacturers design and produce their own electronic devices, often demanding custom paste formulations for proprietary processes. Major consumer electronics OEMs in South Korea and Japan often engage directly with paste formulators for tailored solutions.
- Printed Circuit Board Assemblers:These specialized companies focus solely on the assembly of PCBs, utilizing solder paste as a core material in their processes.
- Tier-1 Suppliers:These suppliers provide major sub-assemblies to larger manufacturers, especially in the automotive and aerospace sectors, requiring high-reliability pastes.
The shift toward consolidated supply chains favors larger end-users capable of global procurement and technical collaboration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of skilled engineering talent across key electronics manufacturing hubs drives solder paste innovation and demand globally. These regions, including China, Germany, and the United States, lead in both production and consumption of advanced solder materials. Regulatory frameworks further shape market dynamics in these critical geographies.
China
Mass production facilities across China create substantial volume demand for cost-effective solder paste solutions. The country's GB standards dictate critical material specifications for electronics components. Major electronics assembly clusters in the Pearl River Delta and Yangtze River Delta regions continuously drive demand for high-throughput paste formulations.
Germany
Automotive electronics manufacturing in Germany necessitates high-reliability solder pastes capable of enduring harsh operational conditions. The EU's RoHS and REACH frameworks compel extensive adoption of lead-free and halogen-free formulations. Industrial centers like Bavaria and Baden-Württemberg house Tier-1 automotive suppliers demanding robust solder materials for ADAS and EV systems.
United States
Advanced packaging and semiconductor manufacturing in the United States require high-performance solder pastes with ultra-fine particle sizes. Environmental Protection Agency (EPA) guidelines influence the development of safer chemical compositions. Technology hubs such as Silicon Valley and manufacturing sites in Texas are key consumers of specialized solder solutions.
Japan
Japan's consumer electronics and high-reliability industrial equipment sectors demand precision solder pastes with consistent quality. The Ministry of Economy, Trade and Industry (METI) promotes material science innovation in electronics manufacturing. The Kanto region, including Tokyo, remains a significant center for electronics production and material development.
Vietnam
Expanding electronics assembly operations in Vietnam generate growing demand for efficient solder paste solutions. Government investment incentives attract foreign direct investment into the manufacturing sector. Industrial parks near Ho Chi Minh City and Hanoi are becoming crucial hubs for high-volume consumer electronics production.
Solder Paste Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the solder paste market, reflecting a tiered competitive structure. Large chemical firms leverage extensive research and development capabilities, while niche manufacturers target high-performance applications. Key strategic archetypes include global material science giants and specialized paste formulators. Companies often pursue portfolio diversification and geographic expansion to solidify their market positions.
Within the global material science giants, Germany-based Henkel AG & Co. KGaA exemplifies extensive research and development and broad solution offerings across diverse industries. Indium Corporation, a US-based entity, represents a specialized paste formulator with a focus on high-performance materials for advanced applications. AIM Solder Technologies LLC, another US-based company, occupies a position among the focused pure-play specialists, providing targeted solutions for electronics manufacturing. These entities anchor distinct segments of the solder paste market, from high-volume production to niche, demanding uses.
| Leading Market Players |
|---|
| Element Solutions Inc. |
| AIM Solder Technologies LLC |
| Henkel AG & Co. KGaA |
| Interflux Electronics N.V. |
| KOKI Company, Ltd. |
| Indium Corporation |
| Senju Metal Industry Co., Ltd. |
| MULTICORE Soldering Products Ltd. |
| Nihon Superior Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The EU's RoHS directive, compelling a shift to lead-free formulations, forces solder paste manufacturers to invest heavily in R&D, influencing the premium associated with compliant, high-performance materials. This regulatory mandate drives up production costs, which suppliers often pass on through higher pricing.
Pricing Analysis
Bundled technical support and application engineering often differentiate pricing models for solder paste. Pricing stratifies across premium, standard, and economy tiers, driven by factors like material quality grade for advanced packaging and volume scale for mass production. Margins are tightening due to input cost volatility in tin and silver, primary components of lead-free alloys. Consumer electronics manufacturers exhibit high price sensitivity, while aerospace systems integrators prioritize performance over cost.
Supply Chain Analysis
Workforce availability and specialized engineering talent in key manufacturing geographies like China, Japan, and Germany significantly influence solder paste supply. The supply chain sources critical metal powders, including tin and silver, from a few global producers. This concentrated powder supply creates a structural risk of single-source vulnerability for paste manufacturers. Distribution runs through direct sales channels to major electronics contract manufacturers and OEMs, supplemented by regional distributors for smaller assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solder paste market operates as a regulatory compounder, with the EU's RoHS directive continuously driving demand for advanced lead-free formulations. This regulatory push accelerates material science innovation and investment across the industry.
For Market Incumbents:
Deploy global scale and material science expertise to address the technical hurdles of lead-free solders. Incumbents must invest in novel alloy research for low-temperature applications and reinforce their certification investments to meet REACH and GB standards. Consolidate supply chains with key OEMs to counter competitive fragmentation and secure volume commitments. This approach mitigates threats from smaller, regional players.
For New Entrants and Emerging Players:
Begin with a focus on niche, high-growth segments like low-temperature solders for heat-sensitive components and advanced packaging materials. Target emerging assembly hubs in Vietnam and Mexico, which are expanding their consumer electronics production. Offer specialized high-performance pastes with tailored rheological properties to differentiate from established players. This strategy allows new entrants to build market share in specific application areas.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized paste formulators possessing strong intellectual property in novel alloys for next-generation electronics. The market offers long-term viability, underpinned by sustained demand for advanced electronics and continuous regulatory evolution. Target companies with proven R&D capabilities in bismuth-indium chemistries or ultra-fine particle technologies. The signal to watch is further consolidation among high-purity metal powder suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | To meet rising demand from electronics manufacturing in Vietnam. |
| Green Manufacturing Transition | To comply with evolving environmental regulations like REACH. |
| Long-term Supply Agreement | To secure consistent raw material supply amidst input volatility. |
| Product Launch (Low-Temperature Solder) | To address demand from heat-sensitive components and flexible electronics. |
| Acquisition of Specialist Firm | To gain expertise in advanced packaging materials and ultra-fine particle technology. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary and secondary research. Primary insights came from discussions with R&D directors, procurement leads at Electronics Contract Manufacturers, material scientists, and regulatory compliance officers. Secondary data sources included customs/trade statistics, SEC 10-K filings of major chemical firms, industry association reports, and patent databases. This approach enabled bottom-up aggregation and top-down validation of market sizing.
Historical reference periods anchored the forecast window, utilizing multi-variable regression analysis. The model incorporated segmentation dimensions including product type, application, alloy composition, end-user industry, and regional manufacturing clusters. Compound annual growth rates were derived from historical trends and projected future growth drivers. Key industry-specific forecast inputs included electronics production volumes in major hubs and regulatory compliance timelines.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and radical technological discontinuities. Forecasts reflect assumptions regarding stable supply chains and predictable regulatory evolution. Practitioners should monitor sudden shifts in commodity prices or unanticipated changes in environmental legislation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Semiconductor and Electronic Parts Manufacturing Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market