
 APAC Acoustic Sensors Market | 2026-2036
APAC Acoustic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Acoustic Sensors Market Outlook
Industrial-grade acoustic sensing specifications is collapsing into a narrower band of high-reliability tiers as buyers consolidate procurement around certified performance benchmarks. Murata Manufacturing Co., Ltd. leverages its ceramic resonator heritage to dominate surface acoustic wave subsystems across Japanese automotive lines. TDK Corporation anchors magnetostrictive sensor production for industrial automation clients in China and Southeast Asia. KYOCERA Corporation differentiates through piezoelectric material control, sustaining margin pools in precision measurement niches.
Acoustic sensors in the APAC region encompass transducers that convert mechanical sound waves into electrical signals through piezoelectric, capacitive, or magnetostrictive mechanisms, typically operating across frequency ranges from infrasonic to ultrasonic with sensitivity thresholds measured in decibels. These devices serve industrial process monitoring, structural health diagnostics, and voice-capture interfaces in connected environments. MEMS Microphones capture the largest volume share as smartphone and wearable OEMs in Taiwan and Vietnam scale orders for miniaturized audio front-ends. Ultrasonic Sensors register the fastest structural expansion, driven by factory automation retrofits in China's Yangtze River Delta manufacturing belt. Neural Network Based technology sits at the premium tier, where algorithm-embedded acoustic processing commands higher unit economics in security and predictive maintenance deployments.
Japan's METI enforces JIS standards for industrial IoT device interoperability, compelling acoustic sensor vendors to certify frequency stability and environmental tolerance. China's MIIT mandates GB standards for smart manufacturing equipment, shaping product access rules for domestic automation procurement. India's BIS certification requirements for electronic components create incremental compliance costs for suppliers targeting automotive and smart home end users. Stakeholders must weigh certification trajectory alignment against manufacturing footprint decisions as regulatory divergence across these three jurisdictions intensifies.
Market Dynamics
Industrial automation corridors across China, South Korea, and Japan are consolidating acoustic sensor procurement around certified high-reliability tiers, compressing vendor margins for uncertified suppliers while rewarding algorithm-embedded premium products.
Growth Catalysts
- China's MIIT GB Standards:Smart manufacturing equipment mandates in the Yangtze River Delta are accelerating factory automation retrofits, pulling ultrasonic sensor volumes into industrial process monitoring applications.
- Semiconductor Manufacturing Corridors:South Korean fabs are scaling MEMS microphone orders for precision equipment diagnostics, creating concentrated demand pools for miniaturized acoustic front-ends.
- Neural Network Integration:Algorithm-embedded acoustic processing is commanding premium unit economics in Japanese predictive maintenance deployments across automotive assembly lines.
Market Restraints
- Ceramic Resonator Supply Concentration:Japanese heritage suppliers dominate surface acoustic wave subsystems, creating single-source vulnerability for automotive OEMs seeking dual-qualified vendors.
- BIS Certification Friction:India's electronic component testing timelines add 4-6 month market entry delays for suppliers targeting smart home and automotive end users.
- Capacitive Sensing Substitution:Optical proximity sensors are capturing position-sensing applications in consumer electronics, narrowing ultrasonic sensor addressable markets at the low-frequency edge.
Strategic Opportunities
- Vietnam Electronics Manufacturing:Smartphone and wearable OEMs are diversifying assembly footprints beyond Taiwan, creating new MEMS microphone demand clusters in northern industrial zones.
- IoT Interoperability Mandates:Japan's METI JIS standardization push is compelling frequency stability certifications that algorithm-embedded vendors can leverage for margin expansion.
- Structural Health Monitoring:Piezoelectric sensor deployments for civil infrastructure diagnostics represent underpenetrated white space in Australian and Southeast Asian construction markets.
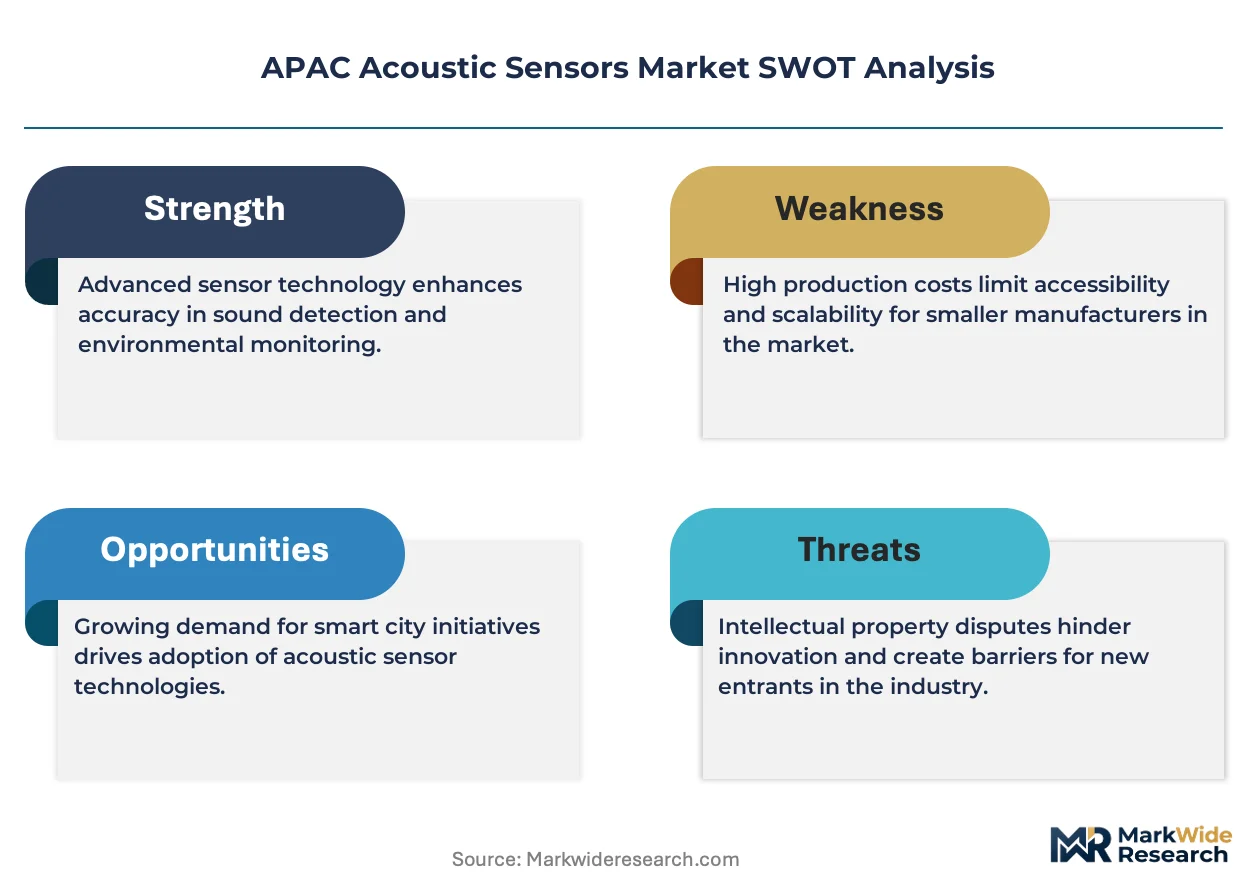
Industry Challenges
- Multi-Jurisdiction Certification Burden:Vendors must simultaneously navigate China's GB standards, Japan's JIS frameworks, and India's BIS requirements, fragmenting product development resources.
- Legacy System Integration Complexity:Industrial automation retrofits in aging Chinese manufacturing plants require analog-to-digital interface engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Acoustic Sensors Market |
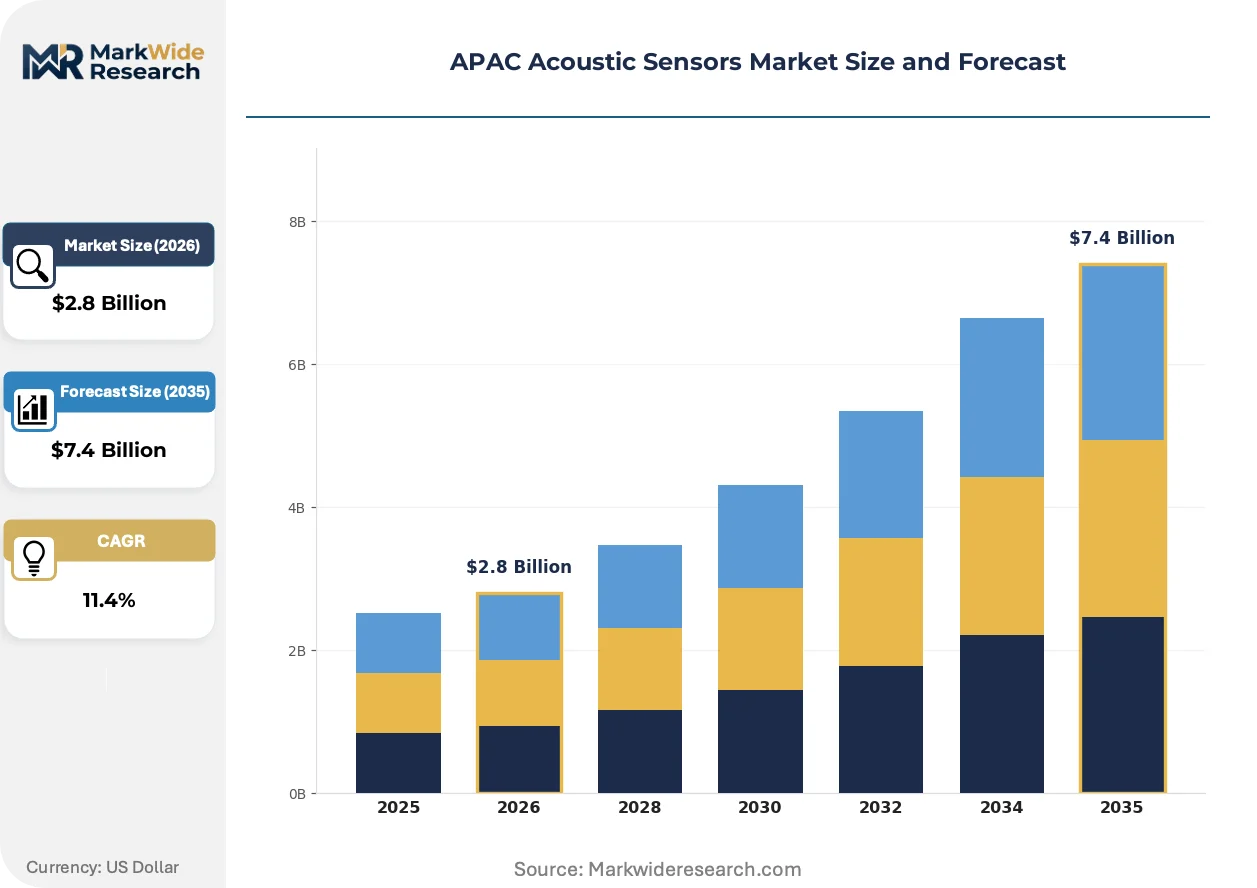
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Laser Diode Sensors, MEMS Microphones, Pressure Sensors Technology: Analog, Digital, 3D Time-of-Flight, Neural Network Based Application: Industrial Automation, Environmental Monitoring, Healthcare, Security Systems End User: Manufacturing, Oil & Gas, Automotive, Smart Homes |
| Companies Covered | Murata Manufacturing Co., Ltd., KYOCERA Corporation, Panasonic Corporation, TDK Corporation, Honeywell International Inc., API Technologies Corp., CeramTec, CTS Corporation, ECS Inc. International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Acoustic Sensors Market Strategic Shifts
Acoustic sensing architectures are converging with edge AI and MEMS fabrication advances, compressing form factors while expanding algorithmic processing capabilities at the sensor node.
Neural network-based acoustic processing is supplanting threshold-based detection in security and predictive maintenance systems. Japanese automotive suppliers are adopting these algorithm-embedded units for assembly line anomaly detection. The shift is compressing margins for conventional transducer vendors while opening premium pricing tiers for integrated sensor-processor modules.
METI's JIS standards for industrial IoT device interoperability are mandating frequency stability and environmental tolerance certifications. Vendors must now document performance across temperature and vibration envelopes to access Japanese automation procurement channels. The regulation most affects magnetostrictive sensor suppliers serving heavy industrial clients in steel and chemical processing.
Buyer concentration among Taiwanese and Vietnamese smartphone OEMs is compressing MEMS microphone supplier margins through volume-scale negotiations. Component vendors are responding by unbundling after-sales technical support and shifting to direct fab relationships. The behavioral shift is most visible in Ho Chi Minh City and Taipei electronics manufacturing corridors where procurement teams now specify lifetime reliability guarantees rather than unit pricing alone.
APAC Acoustic Sensors Market Segmentation
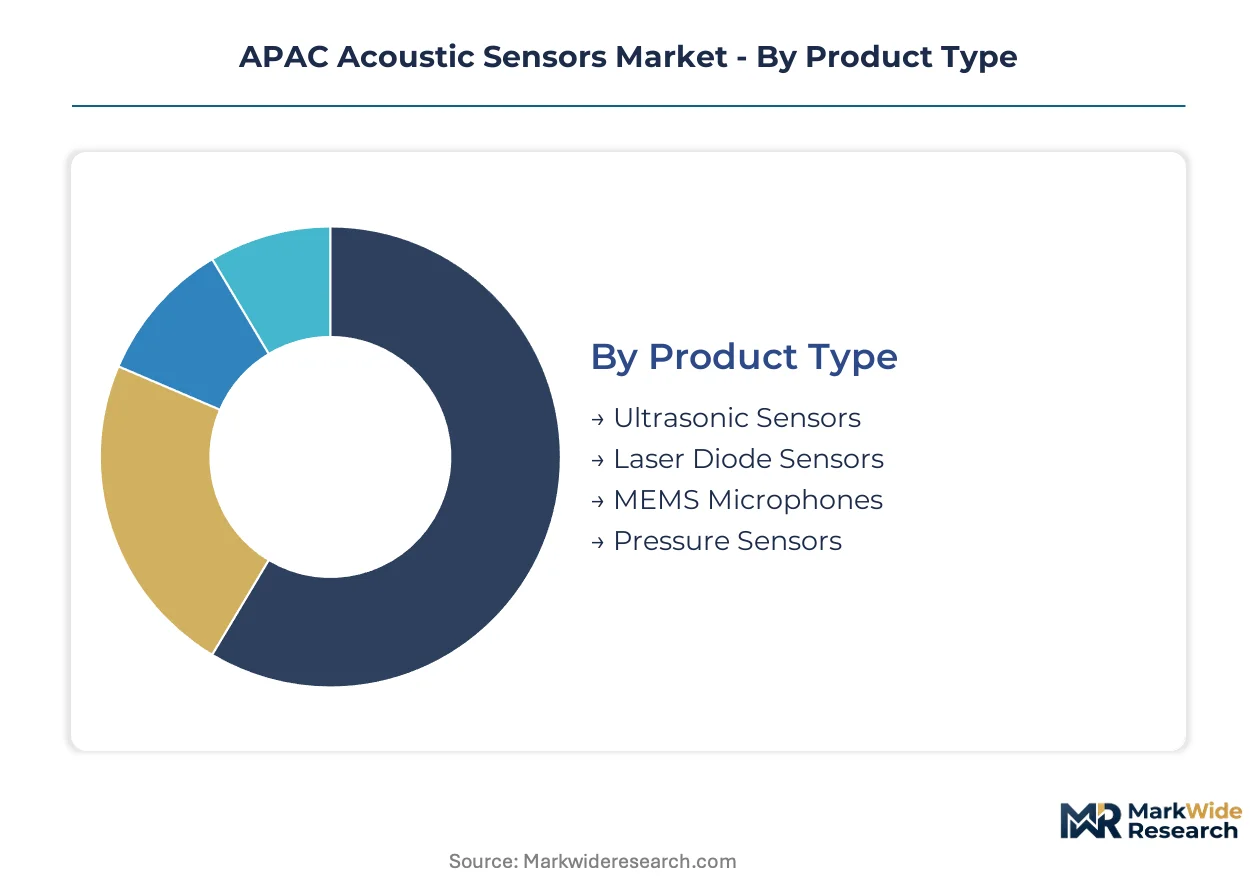
Acoustic sensor procurement across APAC fragments along technology maturity curves and certification requirements. Buyers in Japan, South Korea, and China weight specifications differently, creating tiered demand pools that reward precision engineering over commodity volume.
Product Type:
Domestic demand in China and Japan absorbs the bulk of industrial-grade units, while MEMS microphones serve export-led electronics manufacturing concentrated in Taiwan and Vietnam.
- MEMS Microphones:Miniaturized capacitive transducers fabricated through silicon wafer processing achieve sub-millimeter form factors. Taiwanese and Vietnamese smartphone OEMs scale procurement for audio front-ends in wearable and mobile devices, with procurement teams now specifying lifetime reliability guarantees rather than unit pricing alone.
- Ultrasonic Sensors:Piezoelectric or electrostatic transducers emit high-frequency pulses for distance measurement and object detection. Factory automation retrofits across China's Yangtze River Delta manufacturing belt are pulling volumes into industrial process monitoring, with MIIT GB standards mandating integration into smart manufacturing equipment.
- Laser Diode Sensors:Optoacoustic hybrids measuring displacement through interferometric methods. Japanese automotive lines deploy these for precision assembly verification where acoustic and optical sensing converge.
- Pressure Sensors:Piezoresistive or capacitive elements detecting fluid and gas pressure variations. Oil and gas infrastructure across Australian offshore platforms and Southeast Asian pipelines drives sporadic but high-margin demand.
MEMS Microphones commands the established base. The steepest expansion runs through Ultrasonic Sensors.
Technology:
Cost tiers separate legacy analog implementations from algorithm-embedded premium modules, with Japanese buyers concentrating procurement at the certified high-reliability tier.
- Neural Network Based:Edge-deployed machine learning models process raw acoustic signatures for anomaly classification. Japanese automotive suppliers adopt these integrated sensor-processor modules for assembly line predictive maintenance, commanding premium unit economics that conventional transducer vendors cannot match.
- Digital:Pulse-code modulation and delta-sigma architectures enable software-configurable filtering. South Korean semiconductor fabs scale orders for precision equipment diagnostics requiring configurable acoustic front-ends.
- Analog:Continuous voltage-output transducers with minimal signal conditioning. Legacy industrial installations across aging Chinese manufacturing plants sustain residual demand despite integration complexity.
- 3D Time-of-Flight:Acoustic ranging combined with spatial mapping algorithms. Security system deployments in Australian commercial infrastructure represent nascent application development.
Neural Network Based technology captures margin concentration at the premium tier. Digital architectures are gaining share fastest among new industrial installations.
Application:
Volume concentrates in factory automation, though environmental monitoring is accelerating as Australian and Southeast Asian infrastructure investment expands.
- Industrial Automation:Process monitoring, predictive maintenance, and quality control through acoustic signature analysis. China's MIIT smart manufacturing mandates in the Yangtze River Delta are accelerating ultrasonic sensor integration into retrofit production lines.
- Security Systems:Intrusion detection, perimeter monitoring, and gunshot localization through array processing. Japanese METI JIS standardization pushes are compelling frequency stability certifications that algorithm-embedded vendors leverage for margin expansion.
- Environmental Monitoring:Noise pollution assessment, wildlife tracking, and seismic precursor detection. Australian civil infrastructure diagnostics represent underpenetrated white space for piezoelectric sensor deployments.
- Healthcare:Respiratory monitoring, ultrasonic imaging, and prosthetic feedback systems. India's BIS certification requirements for electronic components create incremental compliance costs for suppliers targeting medical device integration.
Industrial Automation anchors current procurement volumes. Environmental Monitoring is climbing the fastest as infrastructure investment broadens across Southeast Asia.
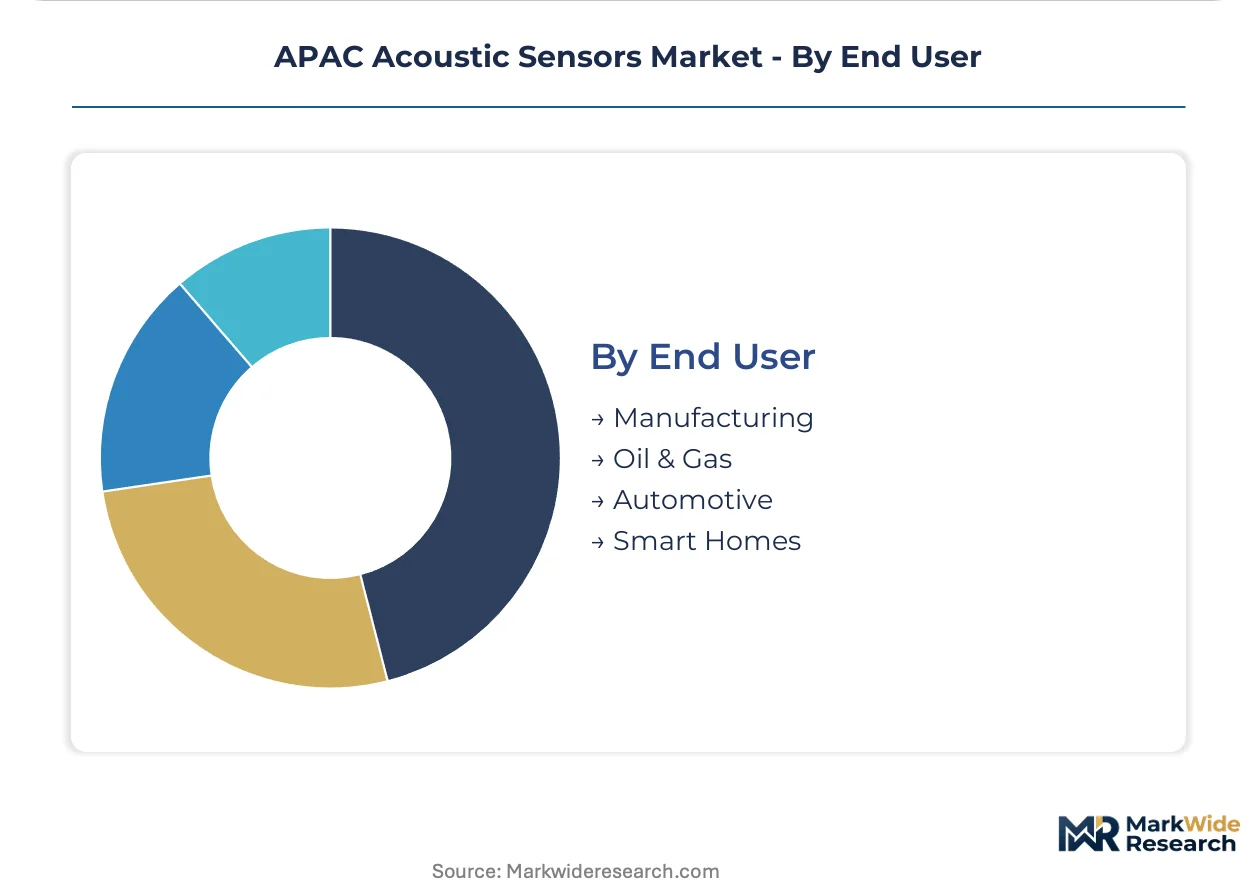
End User:
Customer type stratification shows manufacturing absorbing certified high-reliability tiers, while smart home demand remains price-sensitive and fragmented.
- Manufacturing:Automotive assembly, electronics fabrication, and heavy industrial processing requiring continuous acoustic monitoring. South Korean fabs concentrate MEMS microphone demand for precision equipment diagnostics.
- Automotive:In-cabin voice interfaces, parking assistance, and powertrain noise analysis. Murata Manufacturing dominates surface acoustic wave subsystems across Japanese automotive supply chains through ceramic resonator heritage.
- Smart Homes:Voice assistants, occupancy sensing, and security integration. India's BIS certification timelines add market entry friction for component suppliers targeting this price-sensitive segment.
- Oil & Gas:Pipeline leak detection, compressor monitoring, and offshore platform safety systems. TDK Corporation anchors magnetostrictive sensor production for these heavy industrial clients across China and Southeast Asia.
Manufacturing holds the installed base concentration. Smart Homes is expanding most quickly as voice-interface adoption penetrates mass-market residential construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart home buyers in India and Southeast Asia exhibit acute price sensitivity, while Japanese and South Korean industrial buyers prioritize certified reliability over unit cost. This demand elasticity contrast fragments procurement patterns across the region.
China
MIIT GB standards for smart manufacturing equipment mandate acoustic sensor integration into retrofit production lines. Yangtze River Delta manufacturing clusters in Shanghai, Suzhou, and Hangzhou absorb ultrasonic sensor volumes for factory automation diagnostics. Procurement teams specify environmental tolerance certifications to access state-backed automation subsidies.
Japan
METI JIS standardization pushes compel frequency stability documentation for industrial IoT device interoperability. Kanto and Chubu industrial corridors concentrate demand for algorithm-embedded acoustic processing in automotive assembly predictive maintenance. Ceramic resonator heritage suppliers dominate surface acoustic wave subsystem procurement.
South Korea
Semiconductor fabs in Gyeonggi Province scale MEMS microphone orders for precision equipment diagnostics. MFDS medical device regulations shape acoustic sensor specifications for healthcare integration. Seoul Capital Area electronics manufacturing corridors concentrate miniaturized audio front-end demand from smartphone OEMs.
India
BIS certification timelines add 4-6 month market entry friction for suppliers targeting smart home and automotive segments. Maharashtra and Karnataka electronics manufacturing zones absorb price-sensitive MEMS microphone volumes for domestic smartphone assembly. Procurement teams negotiate lifetime reliability guarantees rather than unit pricing alone.
Vietnam
Smartphone and wearable OEMs diversify assembly footprints beyond Taiwan, creating MEMS microphone demand clusters in northern industrial zones around Hanoi and Hai Phong. General electronics component regulations govern import compliance. Procurement concentration among Ho Chi Minh City electronics manufacturing corridors compresses supplier margins through volume-scale negotiations.
APAC Acoustic Sensors Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Ceramic resonator heritage specialists dominate premium-tier frequency stability applications, while scale-driven fabricators capture MEMS microphone volumes through direct fab relationships. Three archetypes define the field: precision materials specialists, diversified electronics conglomerates, and industrial automation component suppliers. Capacity expansion in Vietnam and strategic partnerships for algorithm-embedded processing represent the dominant competitive moves.
Within the precision materials specialist tier, Murata Manufacturing Co., Ltd. and KYOCERA Corporation occupy positions anchored by ceramic and piezoelectric material control heritage. TDK Corporation exemplifies the diversified electronics conglomerate archetype with magnetostrictive sensor production breadth. These three Japanese-origin entities represent the premium-tier vector where certified performance benchmarks consolidate procurement.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| KYOCERA Corporation |
| Panasonic Corporation |
| TDK Corporation |
| Honeywell International Inc. |
| API Technologies Corp. |
| CeramTec |
| CTS Corporation |
| ECS Inc. International |
| Others |
Value Chain & Pricing Dynamics
Capacitive sensing substitution by optical proximity sensors simultaneously reshapes supply geography and pricing economics, compressing ultrasonic sensor margins in Vietnamese consumer electronics corridors while pushing premium-tier vendors toward algorithm-embedded modules in Japanese automotive lines. This displacement dynamic concentrates procurement power among Taiwanese smartphone OEMs and fragments supplier margins across the low-frequency edge.
Pricing Analysis
After-sales service contracts and technical support unbundling drive lifetime value in MEMS microphone procurement, with Ho Chi Minh City and Taipei electronics manufacturing corridors now specifying lifetime reliability guarantees rather than unit pricing alone. Three-tier pricing structure across premium algorithm-embedded, certified standard, and economy analog tiers separates neural network-based modules from conventional transducers. Pricing pressure stems from buyer concentration among Vietnamese and Taiwanese smartphone OEMs executing volume-scale negotiations. Smart home segments in India exhibit acute price sensitivity, while Japanese automotive buyers prioritize certified reliability over unit cost.
Supply Chain Analysis
Inventory cycles for ceramic resonator substrates extend lead times for surface acoustic wave subsystems, compressing planning horizons for automotive OEMs seeking dual-qualified vendors. Manufacturing concentrates in Japan, China, and South Korea, with magnetostrictive sensor production anchored in Chinese and Southeast Asian industrial zones. Raw material dependencies include piezoelectric ceramics, silicon wafers for MEMS fabrication, and rare-earth magnetostrictive alloys. Single-source vulnerability in Japanese heritage ceramic resonator supply creates procurement risk for automotive tier suppliers. Distribution runs through direct fab relationships with smartphone OEMs and industrial automation system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural network-based acoustic processing represents a high-growth disruption, with METI JIS standardization mandates creating algorithm-embedded premium tiers that conventional transducer vendors cannot access.
For Market Incumbents: Shield market position by deepening backward integration into piezoelectric ceramic supply and accelerating certification investment for METI JIS frequency stability standards. Ceramic resonator heritage suppliers must counter single-source vulnerability perceptions through dual-qualified vendor programs. Channel control through direct fab relationships with Taiwanese and Vietnamese smartphone OEMs defends MEMS microphone volume against emerging scale fabricators.
For New Entrants and Emerging Players: Lead with algorithm-embedded acoustic processing targeting Australian structural health monitoring white space, where piezoelectric sensor deployments for civil infrastructure diagnostics remain underpenetrated. Vietnam electronics manufacturing corridors offer the most penetrable MEMS microphone demand clusters as smartphone and wearable OEMs diversify assembly footprints beyond Taiwan. A certification-first go-to-market angle leveraging METI JIS interoperability mandates opens Japanese industrial automation procurement channels.
For Investors and Strategic Acquirers: The market sits at a standardization-compounding phase that favors precision materials specialists with certified performance heritage. Long-term viability over the next decade hinges on algorithm-embedded processing capabilities and multi-jurisdiction certification infrastructure. Acquisition targets should demonstrate ceramic or piezoelectric material control, frequency stability documentation, and established relationships with Japanese automotive or South Korean semiconductor fab buyers. The signal to watch is BIS certification timeline compression in India, which would accelerate smart home and automotive segment entry for compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Embedded Product Development | Neural network-based acoustic processing commands premium unit economics in Japanese predictive maintenance deployments. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB, JIS, and BIS compliance opens procurement channels across China, Japan, and India. |
| Vietnam Manufacturing Footprint Expansion | Northern industrial zones around Hanoi absorb MEMS microphone demand from diversifying smartphone OEMs. |
| Direct Fab Relationship Cultivation | Taiwanese and Vietnamese electronics manufacturing corridors now specify lifetime reliability guarantees over unit pricing. |
| Ceramic Resonator Supply Security | Dual-qualified vendor programs mitigate single-source vulnerability for automotive OEMs sourcing surface acoustic wave subsystems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT GB standard documentation, METI JIS certification registries, and BIS electronic component testing protocols. Primary interviews engaged procurement directors at Taiwanese smartphone OEMs, plant engineers at Yangtze River Delta manufacturing facilities, and regulatory affairs leads navigating multi-jurisdiction compliance. Secondary sources included customs trade data for acoustic sensor imports, SEC filings from diversified electronics conglomerates, and industrial automation equipment procurement databases. Bottom-up volume triangulation against top-down market sizing validates segment-level outputs.
Segmentation dimensions modeled include product type, technology architecture, application vertical, and end-user industry across the analysis window. The quantitative framework derives CAGRs from installed base growth, replacement cycle dynamics, and technology substitution curves. Industry-specific forecast inputs incorporate MIIT smart manufacturing equipment mandate compliance timelines and METI JIS standardization adoption rates in Japanese automotive supply chains.
Underlying assumptions cover regulatory enforcement continuity, ceramic resonator supply stability, and neural network integration cost trajectories, with deviation risk concentrated in BIS certification timeline variability and capacitive-to-optical sensing substitution velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Gyroscope Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Air Flow Monitoring System Market