
 Photoresist and Photoresist Ancillaries Market | 2026-2036
Photoresist and Photoresist Ancillaries Market Size, Share, and Industry Trends Forecast 2026-2036
Photoresist and Photoresist Ancillaries Market Analysis
Japanese chemical producers is shifting capacity toward extreme ultraviolet resists as advanced lithography nodes require tighter molecular precision. JSR Corporation leverages its polymer synthesis expertise to anchor supply for leading-edge fabs. Tokyo Ohka Kogyo sustains dominance in deep ultraviolet formulations through proprietary photosensitive compound portfolios. DuPont de Nemours competes across broadband and i-line segments with broad geographic manufacturing coverage.
Photoresist and photoresist ancillaries comprise light-sensitive polymer formulations and their supporting chemical systems, including developers, strippers, and edge bead removers, engineered to undergo solubility changes when exposed to specific wavelengths from 436 nm down to 13.5 nm for extreme ultraviolet processes. These materials enable the pattern transfer essential to semiconductor fabrication, printed circuit board manufacturing, and microelectromechanical systems production. Extreme ultraviolet resists command premium positioning as the fastest-growing product category, driven by logic and memory migration below 7 nm nodes. Lithography technology generates the dominant value pool within the technology dimension, while display panel applications mature at slower expansion rates compared to MEMS and sensor fabrication.
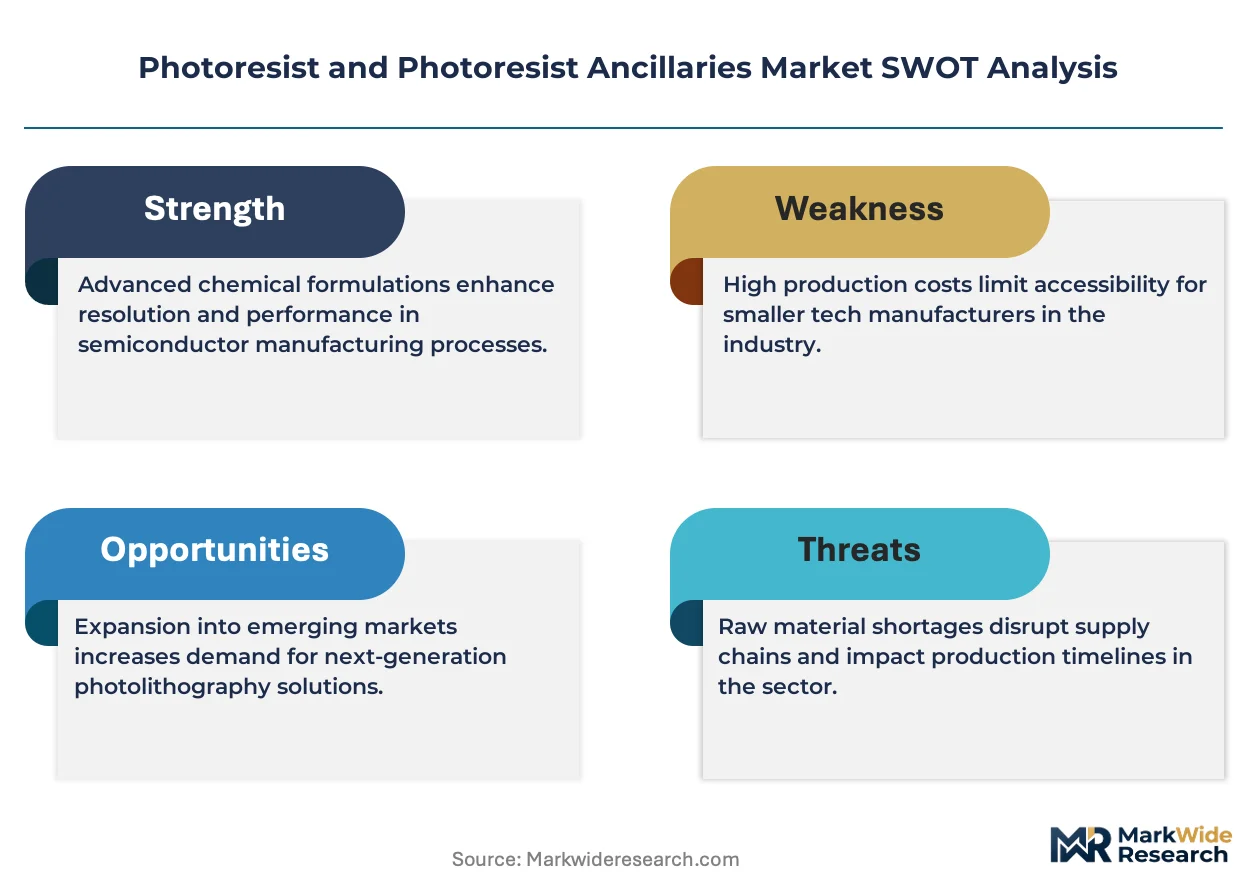
EPA oversight in the United States restricts per- and polyfluoroalkyl substance content in photoresist formulations, compelling reformulation investments. ECHA REACH classifications in Europe mandate extensive substance registration and toxicity documentation for imported ancillaries. Japan's METI coordinates domestic supply security measures for critical semiconductor chemicals. Stakeholders must monitor regulatory divergence across these jurisdictions when structuring multi-site qualification programs and sourcing strategies.
Market Dynamics
Extreme ultraviolet lithography migration below 7 nm nodes is compressing molecular tolerance windows and forcing wholesale reformulation of polymer architectures across the photoresist supply base.
Growth Catalysts
- EU AI Act compliance mandates:Semiconductor foundries in Europe must document chemical provenance for advanced node production, accelerating qualification of high-purity ancillaries.
- South Korea's Gyeonggi cluster expansion:Samsung and SK Hynix capacity additions for 3 nm logic and high-bandwidth memory are pulling EUV resist volumes upward.
- Node shrinkage physics:Each lithography generation halves critical dimension tolerance, multiplying resist layer complexity and ancillary chemical consumption per wafer.
Market Restraints
- Fluorinated raw material volatility:EPA restrictions on per- and polyfluoroalkyl substances constrain photoresist precursor availability, forcing costly molecular redesign.
- Japanese supply concentration:Over 80 percent of advanced resist polymer synthesis capacity resides in three prefectures, creating single-source vulnerability for leading-edge fabs.
- EUV throughput ceiling:Source power limitations and stochastic defect rates cap wafer-per-hour economics, delaying resist volume scaling despite node adoption.
Strategic Opportunities
- India's semiconductor subsidy window:The country's PLI scheme for display and specialty fab construction opens first-mover qualification pathways for ancillary chemical suppliers.
- MEMS sensor lithography:Automotive lidar and medical imaging applications are adopting i-line and DUV resists at volumes disconnected from cyclical logic/memory demand.
- Green chemistry certification:ECHA REACH bio-based substance incentives reward reformulation investments that reduce halogenated solvent content in developer formulations.
Industry Challenges
- EUV resist chemist scarcity:The intersection of polymer physics, photochemistry, and contamination control expertise commands premium compensation and extends R&D team buildout timelines.
- Multi-site qualification friction:Foundry customers demand identical resist performance across Taiwan, South Korea, and United States fabs, complicating batch-to-batch consistency at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoresist and Photoresist Ancillaries Market |
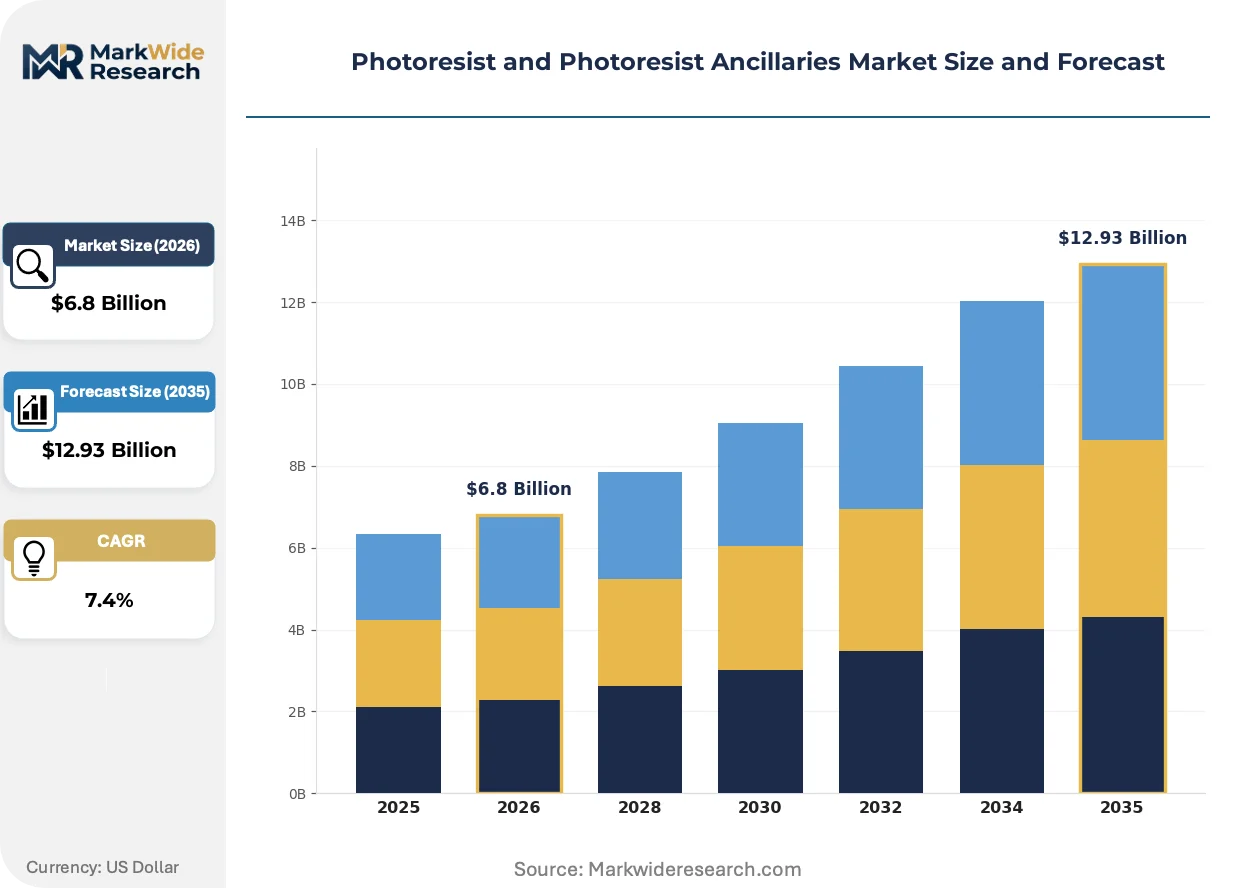
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extreme Ultraviolet, Deep Ultraviolet, i-Line, Broadband End User: Semiconductors, Electronics, Telecommunications, Medical Devices Technology: Lithography, Etching, Deposition, Metrology Application: Circuit Board, MEMS, Sensors, Display Panels |
| Companies Covered | JSR Corporation, Tokyo Ohka Kogyo Co., Ltd, Shin-Etsu Chemical Co., Ltd, FUJIFILM Corporation, DuPont de Nemours, Inc., Sumitomo Chemical Co., Ltd, Merck KGaA, ALLRESIST GmbH, Micro Resist Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoresist and Photoresist Ancillaries Market Emerging Trajectories
Photoresist chemistry is bifurcating between molecular precision for sub-7 nm nodes and cost-optimized legacy formulations, with regulatory pressure accelerating substitution timelines across both tracks.
Metal oxide resists are overtaking chemically amplified organic platforms for high-numerical-aperture EUV systems. TSMC and Intel process teams are qualifying hafnium-based formulations for 2 nm pilot lines. The technology is overtaking incumbent carbon-backbone resists by resolving stochastic defect rates that previously capped yield economics.
EPA per- and polyfluoroalkyl substance enforcement is tightening discharge permits for photoresist manufacturing facilities. Formulators must submit toxicity data for fluorinated surfactants used in edge bead removers and developers. Deep ultraviolet resist segments serving mature nodes face the steepest reformulation cost exposure as alternative surfactant candidates require 18-24 month requalification cycles.
Consolidated procurement through foundry-level chemical management contracts is displacing individual material spot purchasing. Samsung and TSMC now negotiate enterprise agreements covering resists, developers, and strippers as bundled categories. Taiwan's Hsinchu Science Park exhibits the most advanced contract structures, with suppliers bearing inventory carrying costs in exchange for volume commitments and co-development access.
Photoresist and Photoresist Ancillaries Market Segmentation
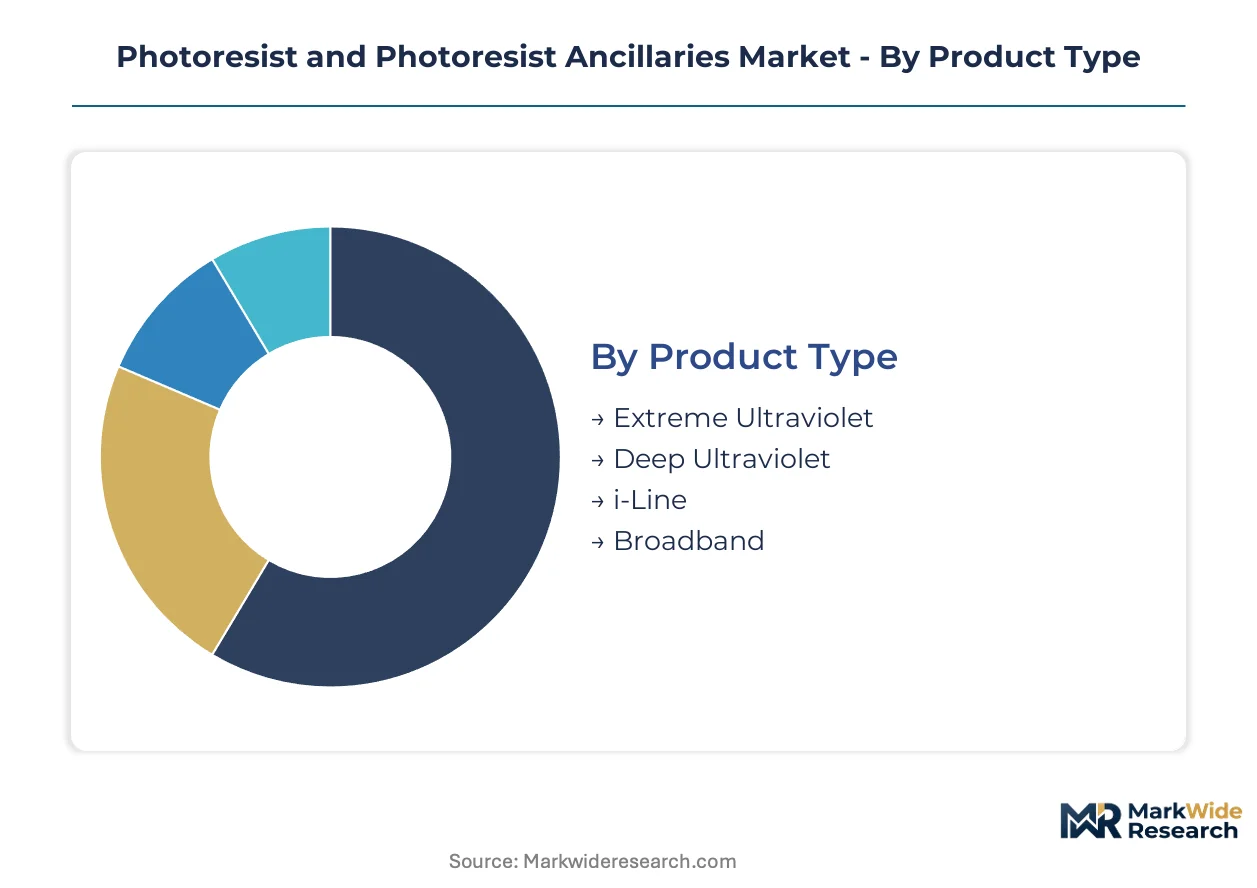
Photoresist segmentation tracks wavelength-specific formulations from 436 nm i-line systems down to 13.5 nm EUV platforms, each tier locking into distinct lithography generations and capital equipment cycles. End-use concentration in semiconductor foundries versus diversified industrial applications creates divergent margin and volume profiles across supplier portfolios.
Product Type:
Integration depth varies sharply across wavelength platforms, with EUV resists embedded exclusively in leading-edge logic and memory fabs while broadband formulations serve standalone PCB and MEMS operations without co-located deposition or metrology tools.
- Extreme Ultraviolet:Metal oxide and chemically amplified organic platforms engineered for 13.5 nm wavelength exposure with sub-20 nm critical dimension control. Samsung's Pyeongtaek complex and TSMC's Hsinchu pilot lines anchor demand as 3 nm and 2 nm node ramps accelerate resist consumption per wafer.
- Deep Ultraviolet:248 nm and 193 nm formulations dominating 7 nm to 28 nm logic production and mature DRAM nodes. SK Hynix fabs in Icheon sustain the largest DUV resist offtake as high-bandwidth memory stacks multiply lithography steps per die.
- i-Line:365 nm g-line/h-line hybrid systems for power semiconductors and analog devices at nodes above 90 nm.
- Broadband:Multi-wavelength resists spanning 350-450 nm for PCB patterning and MEMS prototyping with minimal equipment specialization.
Volume placements concentrate in Deep Ultraviolet; the faster expansion belongs to Extreme Ultraviolet.
End User:
Cost tier stratification separates captive chemical management contracts at semiconductor foundries from spot purchasing patterns in medical device and telecommunications equipment manufacturing.
- Semiconductors:Logic and memory fabs consuming 85 percent of advanced resist volumes through enterprise procurement agreements bundling resists, developers, and strippers. Samsung and Intel qualification protocols demand batch-to-batch consistency across Taiwan, South Korea, and Arizona production sites.
- Electronics:Printed circuit board and passive component manufacturers sourcing broadband and i-line resists through distributor channels with minimal technical service attachment.
- Telecommunications:Optical component and RF module producers utilizing DUV resists for precision waveguide patterning in 5G infrastructure.
- Medical Devices:Biosensor and diagnostic equipment makers adopting MEMS-compatible formulations with ISO 13485 quality system requirements.
Margin concentration sits with Semiconductor; Medical Devices is climbing the fastest on diagnostic miniaturization trends.
Technology:
Application maturity separates lithography as the dominant value pool from etching, deposition, and metrology ancillaries that attach to resist processing as secondary chemical systems.
- Lithography:Pattern transfer operations consuming photoresists, developers, edge bead removers, and rinse chemicals in coordinated process sequences. TSMC's N3E node qualification cycles extend 18-24 months for complete ancillary portfolios.
- Etching:Plasma and wet chemical stripping operations removing resist masks post-patterning with fluorinated and non-fluorinated solvent formulations.
- Deposition:Spin-on carbon and silicon hardmask layers interleaved with photoresists in multi-patterning stacks.
- Metrology:Critical dimension scanning electron microscopy and optical scatterometry consuming specialized calibration standards and consumables.
Revenue weighting favors Lithography; Metrology is gaining share fastest on advanced node inspection intensity.
Application:
Supply concentration diverges between circuit board manufacturing dispersed across Southeast Asian contract manufacturers and MEMS sensor fabrication clustering in automotive lidar hubs.
- Circuit Board:Multi-layer PCB and substrate patterning utilizing g-line, i-line, and laser-direct-imaging resists with lower purity requirements than semiconductor grades.
- MEMS:Microelectromechanical systems for automotive pressure sensors, inkjet printheads, and microphone arrays requiring thick-film resists with high aspect ratio capability. Bosch's Reutlingen fab anchors European demand.
- Sensors:Image sensor and environmental detector manufacturing with backside-illumination and wafer-level packaging specific formulations.
- Display Panels:TFT-LCD and OLED backplane patterning with large-area coating equipment and distinct viscosity specifications from wafer-scale semiconductor tools.
Unit economics favor MEMS; Display Panels is expanding most quickly on OLED capacity additions in South Korea and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity fluorinated precursor synthesis anchors Japanese supply security, while Korean and Taiwanese foundry clusters pull volume toward East Asian lithography hubs. Regulatory divergence across EPA, ECHA REACH, and METI jurisdictions complicates multi-site qualification programs for resist formulators.
Japan
Chiba and Ibaraki prefectures concentrate over 80 percent of advanced resist polymer synthesis capacity, feeding TSMC and Samsung qualification pipelines. METI coordinates domestic supply security measures through critical semiconductor chemical stockpiling directives. Yokkaichi's chemical complex sustains deep ultraviolet formulation dominance through proprietary photosensitive compound portfolios.
South Korea
Samsung's Pyeongtaek complex and SK Hynix's Icheon fabs anchor EUV resist consumption for 3 nm logic and high-bandwidth memory stacks. The country's national environmental regulator enforces discharge permits that constrain fluorinated surfactant use in developer formulations. Gyeonggi Province's cluster expansion pulls ancillary chemical volumes upward through bundled procurement contracts.
Taiwan
TSMC's Hsinchu pilot lines and Tainan gigafabs drive metal oxide resist qualification for 2 nm node migration. The central bank's technology sector lending facilities support foundry capex cycles that synchronize resist demand. Hsinchu Science Park exhibits the most advanced chemical management contract structures, with suppliers bearing inventory carrying costs.
United States
Intel's Arizona and Oregon fabs diversify sourcing away from East Asian concentration through multi-year resist supply agreements. EPA restrictions on per- and polyfluoroalkyl substances compel reformulation investments and toxicity data submissions for edge bead removers. Greater Phoenix anchors domestic advanced packaging demand as CHIPS Act disbursements accelerate equipment installation.
Germany
Bosch's Reutlingen fab and Infineon's Dresden complex sustain MEMS and power semiconductor resist demand disconnected from cyclical logic cycles. ECHA REACH classifications mandate extensive substance registration and bio-based substance incentives for developer reformulations. Saxony's Silicon Saxony cluster coordinates ancillary supplier qualification through centralized chemical management programs.
Photoresist and Photoresist Ancillaries Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulations for MEMS and medical device applications. The vendor base stratifies across three tiers: integrated chemical conglomerates with polymer synthesis depth, mid-scale resist specialists serving mature nodes, and regional formulators capturing PCB and display panel segments. Two dominant competitive moves define positioning: backward integration into fluorinated precursor production to secure supply, and geographic diversification of manufacturing assets to satisfy foundry multi-site qualification requirements.
Among Japanese chemical producers, JSR Corporation, Tokyo Ohka Kogyo Co., Ltd, and Shin-Etsu Chemical Co., Ltd exemplify the integrated conglomerate archetype. These companies occupy positions anchored in polymer synthesis expertise and proprietary photosensitive compound portfolios. DuPont de Nemours, Inc. represents the geographic diversification vector, with manufacturing coverage spanning broadband and i-line segments across multiple continents. Merck KGaA and ALLRESIST GmbH sit within the European specialist tier, serving research and mature node segments through differentiated formulation capabilities.
| Leading Market Players |
|---|
| JSR Corporation |
| Tokyo Ohka Kogyo Co., Ltd |
| Shin-Etsu Chemical Co., Ltd |
| FUJIFILM Corporation |
| DuPont de Nemours, Inc. |
| Sumitomo Chemical Co., Ltd |
| Merck KGaA |
| ALLRESIST GmbH |
| Micro Resist Technology GmbH |
| Others |
Supply Flow & Price Mechanics
Extreme ultraviolet lithography migration below 7 nm nodes is compressing molecular tolerance windows and simultaneously concentrating supply power among polymer synthesis specialists while fragmenting procurement leverage across foundry buyers. This technical transition forces wholesale reformulation investments that reshape cost economics and supplier consolidation dynamics across the photoresist value chain.
Pricing Analysis
Co-development service bundling separates premium EUV resist contracts from unbundled mature node spot purchases. Three-tier pricing structure across premium, standard, and economy levels tracks wavelength specificity, with metal oxide formulations commanding substantial premiums over chemically amplified organic platforms. Cost compression in DUV segments is intensifying because EPA fluorinated surfactant restrictions force 18-24 month requalification cycles. PCB manufacturers exhibit highest price sensitivity; semiconductor foundries locked into enterprise chemical management contracts show lowest.
Supply Chain Analysis
Dual-sourcing mandates from TSMC and Intel require resist suppliers to maintain qualified manufacturing across Japan, South Korea, and the United States simultaneously. Fluorinated precursor synthesis draws from Chiba and Ibaraki prefectures, hafnium oxide feedstocks, and proprietary photosensitive compound portfolios. Single-source vulnerability concentrates in Japanese polymer synthesis capacity exceeding 80 percent for advanced nodes. Distribution runs through foundry-level chemical management contracts bundling resists, developers, and strippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH substance registration and toxicity documentation requirements erect formidable barrier-to-entry moats favoring incumbents with established registration portfolios and dedicated regulatory affairs infrastructure.
For Market Incumbents: Anticipate fluorinated raw material volatility by securing captive supply of per- and polyfluoroalkyl substance alternatives before EPA enforcement tightens discharge permits. Deepen backward integration into hafnium oxide precursor production to anchor metal oxide resist cost structures. Defend against emerging MEMS-specialist formulators by accelerating green chemistry certification timelines. For New Entrants and Emerging Players: Capture India's semiconductor subsidy window before first-mover qualification pathways close for ancillary chemical suppliers. Target automotive lidar and medical imaging MEMS segments where i-line and DUV resist volumes disconnect from cyclical logic demand. Pursue ECHA REACH bio-based substance incentives as differentiation lever for developer reformulations. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking polymer synthesis depth. Long-term viability favors suppliers with demonstrated multi-site qualification capabilities across Taiwan, South Korea, and Arizona fabs. Watch EUV throughput ceiling resolution as inflection indicator for resist volume scaling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Precursors | JSR Corporation and Tokyo Ohka Kogyo secure supply security against EPA restrictions. |
| Multi-Site Manufacturing Qualification | DuPont de Nemours satisfies Intel's Arizona and Oregon fab diversification requirements. |
| Green Chemistry Certification Investment | ECHA REACH bio-based incentives reward halogenated solvent reduction in developer formulations. |
| MEMS Sensor Lithography Specialization | Bosch's Reutlingen fab anchors European demand for thick-film high aspect ratio resists. |
| Enterprise Chemical Management Contracting | Samsung and TSMC bundle resists, developers, and strippers under inventory-bearing supplier terms. |
Methodological Framework
Multi-period observation of EUV node migration timelines, fluorinated precursor price volatility, and foundry capex cycles anchored the trend analysis, supplemented by interviews with semiconductor process integration engineers, chemical procurement leads at Samsung and TSMC, photoresist R&D directors, and ECHA regulatory affairs specialists. Secondary validation drew from EPA discharge permit filings, METI critical chemical stockpiling directives, SEC 10-K disclosures from listed chemical producers, and customs trade data for fluorinated compound imports. Bottom-up resist volume modeling and top-down semiconductor materials market sizing provided triangulation.
Input-output matrices mapped wavelength-specific formulation demand against lithography equipment installation bases across the projection horizon. Segmentation dimensions modeled include resist wavelength tier, end-use application concentration, technology attachment point, and regional regulatory cluster. CAGRs were derived from node shrinkage physics multiplying resist layer complexity per wafer and ancillary chemical consumption intensity. Industry-specific forecast inputs incorporated EUV source power improvement trajectories and stochastic defect rate resolution timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA fluorinated substance enforcement severity, Japanese supply concentration disruption scenarios, and EUV throughput economic viability. Deviation in metal oxide resist qualification timelines at TSMC's 2 nm pilot lines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Global Wafer Cutting Fluids Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market