
 Wind Turbine Bolts Market | 2026-2036
Wind Turbine Bolts Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Bolts Market Insights
Direct procurement channels between fastener manufacturers and wind turbine OEMs is narrowing as tower builders consolidate supplier lists to reduce qualification burdens. Dokka Fasteners leverages its Nordic manufacturing footprint to anchor supply relationships with Vestas and Siemens Gamesa service networks. Stanley Black & Decker competes through its industrial division's global distribution scale, while Ningbo Ningli High-Strength Fastener dominates cost-sensitive onshore segments from its Zhejiang production base.
Wind turbine bolts are high-tensile threaded fasteners, typically rated at property class 10.9 or 12.9 per ISO 898-1, engineered to withstand cyclic fatigue, corrosion, and preload relaxation in tower flanges, nacelle frames, and blade root joints. Their primary purpose is maintaining structural integrity across 20-25 year design lives while permitting controlled disassembly for maintenance. High strength bolts command the largest volume share across product categories, though tension control bolts capture premium pricing in offshore applications where installation torque precision reduces field failure risk. Carbon steel maintains material dominance in onshore utility-scale towers, while alloy steel and titanium grades penetrate offshore segments where salt spray exposure demands elevated corrosion resistance.
FDA oversight extends to bolt materials used in offshore wind platforms serving dual-use desalination or marine food processing equipment, though EPA stormwater and OSHA fall-protection standards more directly shape installation protocols and worker safety requirements during turbine assembly. The EU CE marking and MDR-adjacent structural component directives pressure non-European suppliers to certify fatigue-test documentation before accessing continental wind farm projects. Stakeholders must monitor evolving IEC 61400 structural design standards and national building code amendments that redefine bolt preload specifications for next-generation larger-rotor turbines.
Market Dynamics
Offshore wind farm developers are consolidating fastener procurement around fewer qualified suppliers capable of certifying fatigue-test documentation under tightening EU material traceability mandates. This supplier rationalization is compressing margins for mid-tier bolt manufacturers while elevating pricing power for integrated producers with captive metallurgical testing facilities.
Growth Catalysts
- EU F-Gas Regulation:The regulation's broader decarbonization mandates are tightening material traceability requirements for structural fasteners, forcing certification investments that favor established suppliers with existing documentation systems.
- North Sea offshore clusters:Installation schedule acceleration in Germany and Denmark is concentrating demand for high-specification tension control bolts rated for extreme marine cyclic loading.
- Property class 12.9 bolts:Next-generation larger-rotor turbines are specifying these higher-strength fasteners for blade root joints, expanding addressable volume in the premium product tier.
Market Restraints
- Alloy steel input volatility:Nickel and chromium price swings compress margin predictability for manufacturers serving offshore corrosion-resistant specifications.
- Zhejiang production concentration:Cost-sensitive onshore segments depend heavily on single-province Chinese supply, creating geopolitical and logistics vulnerability.
- ISO 898-1 fatigue testing bottleneck:Limited third-party laboratory capacity in Europe delays certification timelines for new market entrants.
Strategic Opportunities
- US Inflation Reduction Act:Domestic content bonuses for renewable energy infrastructure create procurement preference for North American bolt manufacturers with localized heat-treatment capabilities.
- Titanium grade penetration:Salt spray exposure in floating offshore platforms is opening demand for titanium fasteners previously confined to aerospace applications.
- Direct OEM contracting:Vestas and Siemens Gamesa service networks are shortening supply chains by eliminating distributor tiers for critical spare parts.
Industry Challenges
- IEC 61400 structural design standard revisions:Evolving preload specifications for larger-rotor turbines force continuous requalification of existing bolt inventories.
- Preload relaxation engineering talent:Specialized fatigue analysis expertise for 20-25 year design life verification remains scarce relative to installation volume growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Bolts Market |
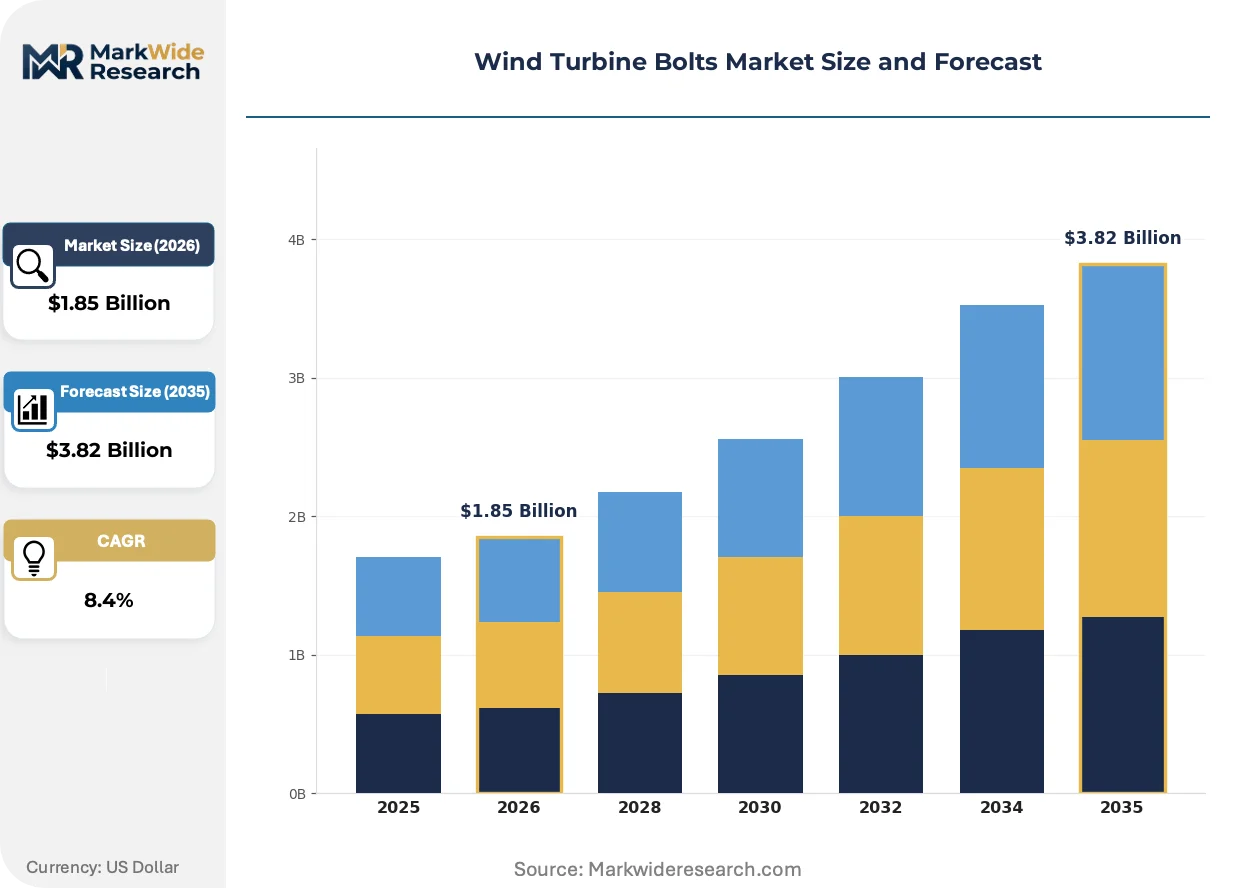
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Strength Bolts, Short Bolts, Tension Control Bolts, Flange Bolts Material: Carbon Steel, Stainless Steel, Alloy Steel, Titanium Application: Onshore, Offshore, Utility Scale, Distributed Generation End User: Wind Farm Operators, OEMs, Maintenance Providers, Contractors |
| Companies Covered | Dokka Fasteners, Stanley Black & Decker, Dyson Corp., Mudge Fasteners, Beck Industries, Bolt Products, Ningbo Ningli High-Strength Fastener, Zhejiang Goodnail Fastener Manufacturing, Finework (HuNan) New Energy Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Bolts Market Trends and Innovations
Tower flange assembly methods are undergoing fundamental revision as precision torque control technologies replace traditional installation practices. These shifts are redrawing competitive boundaries between mechanical and digital solution providers.
Ultrasonic bolt tension measurement systems are replacing torque-wrench installation protocols in offshore foundation assemblies. Siemens Gamesa service crews have adopted these systems across North Sea installations since 2022. The technology is rendering obsolete manual torque-specification tables that failed to account for thread friction variability in salt-exposed environments.
The EU CE marking and adjacent MDR structural component directives now require fatigue-test documentation from non-European suppliers before continental project access. European tower builders are rejecting uncertified Asian shipments at increasing rates. German and Danish port authorities are enforcing these documentation checks during component customs clearance.
After-sales service contracts are unbundling from original equipment supply agreements as wind farm operators seek specialized fastener inspection providers. Independent service companies are displacing OEM-affiliated maintenance crews for tower flange torque audits. This pattern is most visible in German offshore clusters where operator consolidation has concentrated bargaining power.
Wind Turbine Bolts Market Segmentation
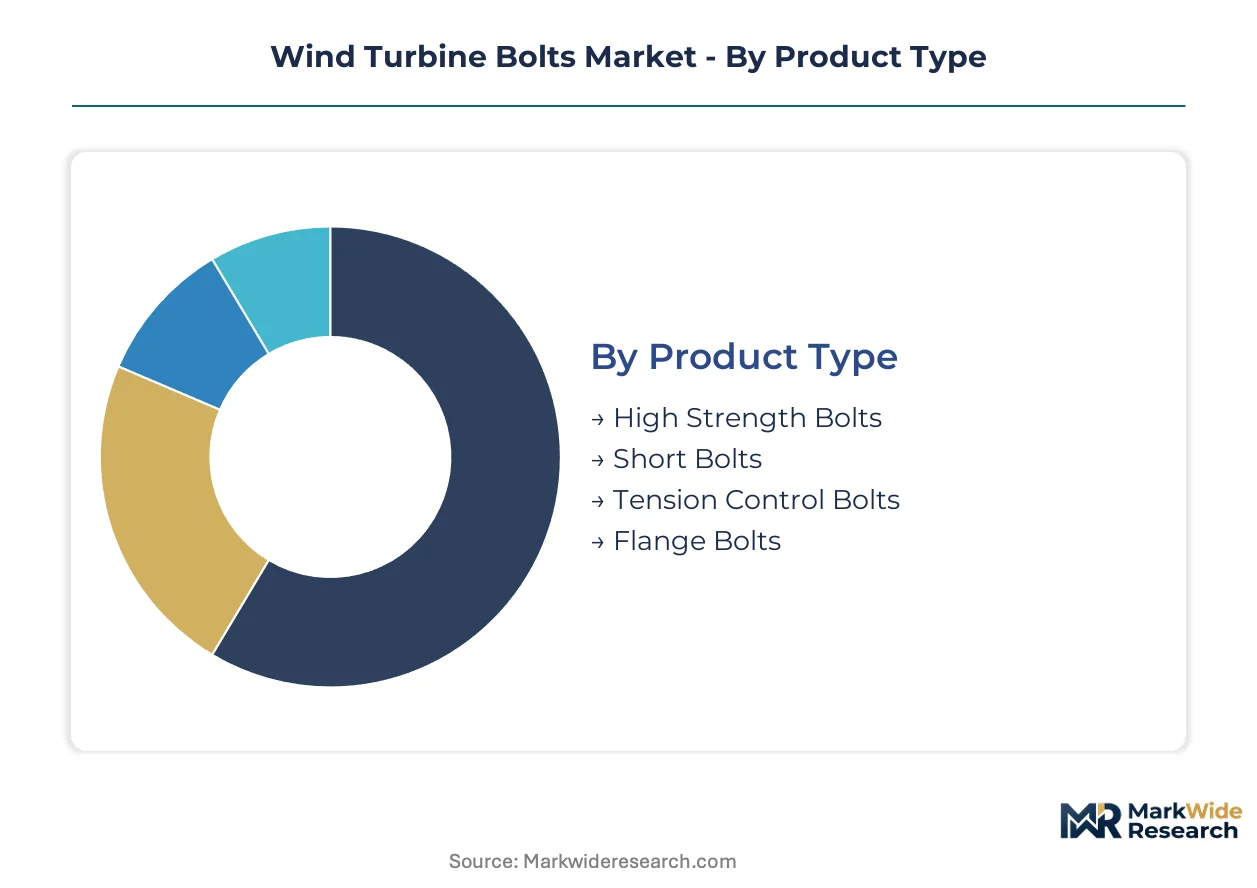
Wind turbine bolt procurement patterns diverge sharply across product grades and installation environments, with after-sales service intensity varying from decades-long corrosion monitoring in offshore foundations to routine torque audits in onshore towers. Segment-specific qualification requirements and inspection protocols create distinct margin profiles that reward specialized manufacturing capabilities.
Product Type:
After-sales service intensity escalates dramatically with bolt specification grade, as tension control variants demand ultrasonic recalibration programs while standard high-strength products require only periodic visual inspection.
- High Strength Bolts:Property class 10.9 and 12.9 fasteners dominate tower flange and nacelle frame applications through ISO 898-1 certification. Demand concentrates in German and Danish North Sea clusters where Vestas and Siemens Gamesa specify these grades for 20-25 year design life verification.
- Tension Control Bolts:Precision-engineered fasteners with built-in tension indicators enable exact preload achievement without post-installation torque verification. Salt spray exposure in floating offshore platforms is accelerating specification of these premium-grade products where installation precision reduces field failure risk.
- Short Bolts:Compact threaded fasteners serve blade root joint applications with restricted clearance envelopes.
- Flange Bolts:Specialized head configurations align with standardized tower section mating surfaces.
By volume, High Strength Bolts leads. By growth pace, Tension Control Bolts is ahead.
Material:
Cost tier stratification separates commodity carbon grades from premium corrosion-resistant alloys, with material selection directly determining inspection frequency and replacement timelines across coastal versus inland installations.
- Carbon Steel:Zinc-coated or hot-dip galvanized grades maintain material dominance in onshore utility-scale towers where atmospheric corrosion remains moderate. Zhejiang production bases supply cost-sensitive segments, though EU F-Gas Regulation traceability requirements are narrowing qualified supplier pools.
- Alloy Steel:Nickel-chromium formulations penetrate offshore segments where cyclic fatigue and salt spray exposure demand elevated mechanical properties. Nickel and chromium price volatility compress margin predictability for manufacturers serving North Sea specifications.
- Stainless Steel:Austenitic and duplex grades offer intermediate corrosion resistance for transitional coastal zones.
- Titanium:Aerospace-grade fasteners are penetrating floating offshore platforms where extreme marine loading and maintenance access constraints justify premium material costs.
By installed base, Carbon Steel dominates. By specification momentum, Alloy Steel is climbing fastest.
Application:
Customer type fragmentation separates owner-operated utility fleets from third-party maintenance contractors, with procurement authority shifting toward specialized inspection providers in mature European markets.
- Offshore:Foundation and tower assemblies exposed to extreme marine cyclic loading require certified fatigue-test documentation under EU CE marking directives. German and Danish port authorities enforce documentation checks during component customs clearance, rejecting uncertified Asian shipments.
- Onshore:Utility-scale and distributed generation towers in continental climates specify lower corrosion resistance grades. The US Inflation Reduction Act domestic content bonuses are redirecting procurement toward North American manufacturers with localized heat-treatment capabilities.
- Utility Scale:Large rotor diameter turbines specify higher property class fasteners across all joint locations.
- Distributed Generation:Smaller tower designs tolerate standard-grade specifications with simplified inspection protocols.
By current installation volume, Onshore leads. By project pipeline value, Offshore is expanding most quickly.
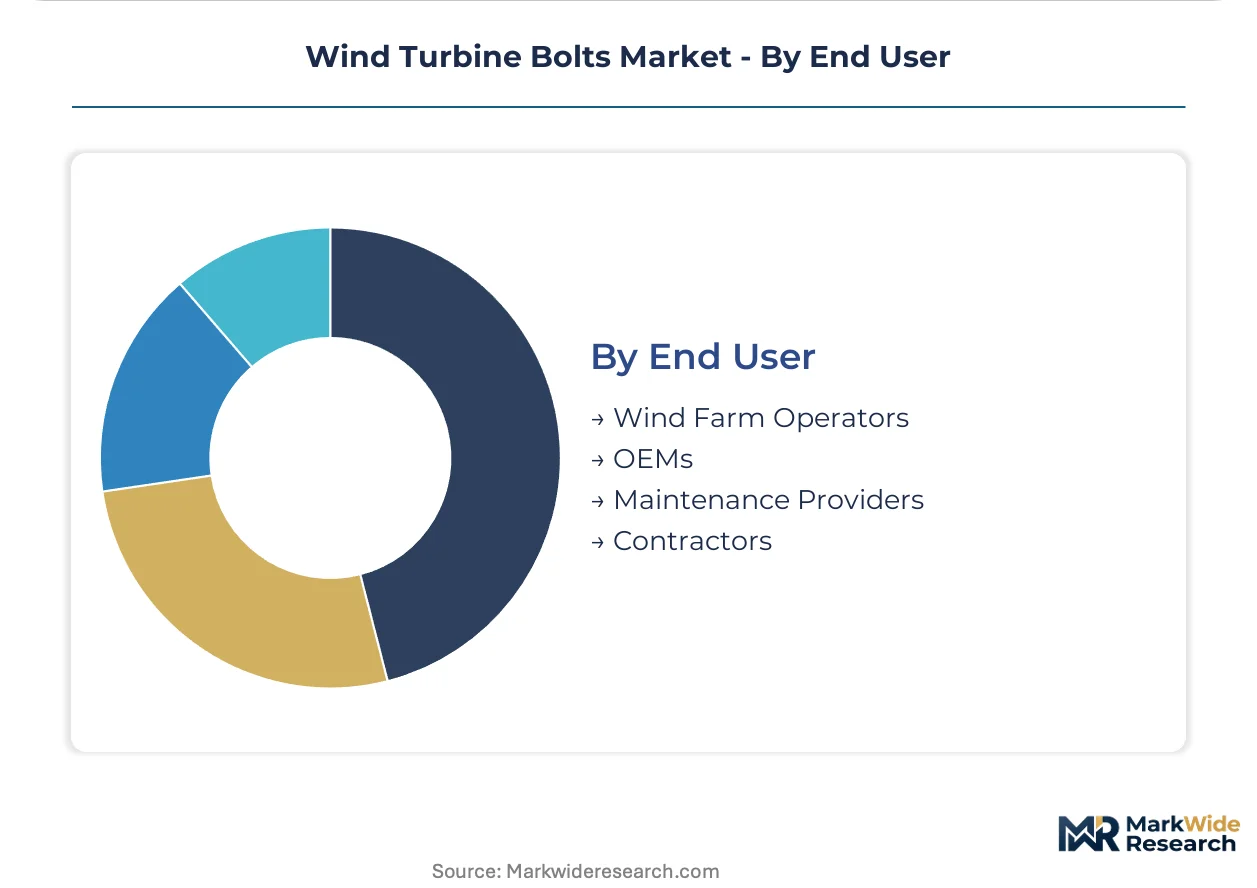
End User:
Supply chain configuration separates direct OEM contracting from aftermarket distribution, with Vestas and Siemens Gamesa service networks shortening procurement channels for critical spare parts.
- Wind Farm Operators:Consolidated owner-operators in German offshore clusters are unbundling after-sales service contracts from original equipment supply agreements. Independent fastener inspection providers are displacing OEM-affiliated maintenance crews for tower flange torque audits.
- OEMs:Vestas and Siemens Gamesa anchor procurement volumes through direct manufacturing partnerships with Nordic fastener producers. Dokka Fasteners leverages regional manufacturing footprint to secure these supply relationships.
- Maintenance Providers:Specialized torque audit contractors are capturing recurring revenue streams from operator consolidation.
- Contractors:EPC firms manage installation-phase procurement with limited post-commissioning service attachment.
By contract value, OEMs dominate new installations. By recurring revenue growth, Wind Farm Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Esbjerg port expansion on Denmark's west coast underwrites Nordic supply chain dominance for North Sea offshore wind infrastructure. German customs authorities at Cuxhaven now enforce EU CE marking documentation checks on every fastener shipment entering continental projects.
Germany
North Sea offshore clusters drive specification of property class 12.9 bolts for larger-rotor turbine blade root joints. The EU F-Gas Regulation mandates material traceability documentation that favors established suppliers with captive metallurgical testing. Port authorities at Cuxhaven reject uncertified Asian shipments at customs clearance.
Denmark
Esbjerg port expansion anchors supply chain consolidation for Vestas and Siemens Gamesa service networks. Danish Energy Agency procurement guidelines prioritize fatigue-test certification under tightening EU structural component directives. Nordic manufacturing footprints secure direct OEM contracting relationships.
United States
The Inflation Reduction Act domestic content bonuses redirect procurement toward North American manufacturers with localized heat-treatment capabilities. OSHA fall-protection standards shape installation protocols during turbine assembly. Texas Gulf Coast wind development concentrates demand for corrosion-resistant specifications.
China
Zhejiang province production bases supply cost-sensitive onshore segments through Ningbo Ningli High-Strength Fastener and Zhejiang Goodnail Fastener Manufacturing. GB standards and MIIT industrial policy guide quality certification pathways. Yangtze River Delta port infrastructure supports export volume to European wind farm projects.
United Kingdom
Dogger Bank offshore development drives tension control bolt procurement for extreme marine cyclic loading. Health and Safety Executive regulations align with EU CE marking requirements for structural fasteners. Scottish port infrastructure at Aberdeen handles North Sea component logistics.
Wind Turbine Bolts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a tiered structure where tower builders consolidate supplier lists to reduce qualification burdens. The vendor base concentrates around integrated producers with captive metallurgical testing facilities and regional manufacturing footprints. Three archetypes dominate: Nordic specialists with direct OEM relationships, Chinese cost-leaders serving onshore utility-scale segments, and diversified industrial conglomerates leveraging global distribution scale. Competitive moves center on capacity expansion in corrosion-resistant alloy grades and strategic partnerships for ultrasonic tension measurement technology licensing.
Among Nordic specialists, Dokka Fasteners anchors supply relationships with regional manufacturing proximity to Vestas and Siemens Gamesa service networks. Stanley Black & Decker occupies a position exemplifying diversified industrial scale through its global distribution infrastructure. Ningbo Ningli High-Strength Fastener represents the cost-driven archetype from its Zhejiang production base, serving volume-intensive onshore utility specifications.
| Leading Market Players |
|---|
| Dokka Fasteners |
| Stanley Black & Decker |
| Dyson Corp. |
| Mudge Fasteners |
| Beck Industries |
| Bolt Products |
| Ningbo Ningli High-Strength Fastener |
| Zhejiang Goodnail Fastener Manufacturing |
| Finework (HuNan) New Energy Technology |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province production concentration for carbon steel fasteners feeds directly into margin compression at the onshore utility-scale tier, while offshore alloy specifications capture value through captive metallurgical testing capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates tension control bolts with ultrasonic calibration support from standard high-strength grades and uncertified commodity imports. Price differentiation hinges on ISO 898-1 fatigue-test documentation and after-sales service bundling. Cost compression in the carbon steel tier is intensifying because EU F-Gas Regulation traceability requirements disqualify Zhejiang suppliers from continental projects. Onshore utility-scale developers exhibit highest price sensitivity; offshore wind farm operators prioritize installation precision over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for fastener procurement. Manufacturing concentrates in China, Germany, and Denmark, with raw material feeds drawing from nickel-chromium alloy suppliers and zinc coating operations. Single-source vulnerability in third-party fatigue-testing laboratory capacity delays certification timelines. Distribution runs through direct OEM contracting channels that Vestas and Siemens Gamesa service networks are shortening for critical spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards producers with in-house preload relaxation engineering talent, a capability gap that constrains expansion for entrants lacking fatigue analysis expertise.
For Market Incumbents: Pre-empt certification bottlenecks by investing in captive metallurgical testing facilities before EU CE marking enforcement tightens further. Secure backward integration into alloy steel heat-treatment capabilities to buffer nickel and chromium price volatility. Anchor direct OEM relationships with Vestas and Siemens Gamesa through regional manufacturing proximity. For New Entrants and Emerging Players: Build out ultrasonic tension measurement service capabilities to capture unbundled after-sales contracts from consolidated German offshore wind farm operators. Target the US Inflation Reduction Act domestic content bonus segment where North American heat-treatment capacity remains scarce. Lead with specialized torque audit offerings rather than manufacturing scale. For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with existing fatigue-test documentation systems and Nordic manufacturing footprints. Long-term viability favors suppliers capable of certifying property class 12.9 bolts for next-generation larger-rotor turbines. Monitor IEC 61400 standard revision timing as an inflection indicator for requalification spending cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Metallurgical Testing Investment | EU CE marking enforcement at German and Danish ports rewards pre-certified suppliers with faster customs clearance. |
| Ultrasonic Tension Measurement Licensing | Siemens Gamesa adoption across North Sea installations creates technology transfer demand from service contractors. |
| Alloy Steel Heat-Treatment Capacity Expansion | Offshore corrosion-resistant specifications require nickel-chromium processing beyond carbon steel capabilities. |
| Direct OEM Contracting Partnership | Vestas and Siemens Gamesa service networks are eliminating distributor tiers for critical spare parts procurement. |
| US Domestic Content Qualification | Inflation Reduction Act bonuses redirect procurement toward North American manufacturers with localized capabilities. |
Research Methodology
Cross-validation between primary interviews with tower flange engineers, procurement leads at wind farm operators, fatigue-testing laboratory directors, and aftermarket service contractors anchors the qualitative findings. Secondary sources include IEC 61400 standard documentation, EU F-Gas Regulation compliance filings, customs data from German and Danish port authorities, and SEC disclosures from diversified industrial conglomerates. Bottom-up volume modeling and top-down value triangulation were reconciled across the analysis window.
Calibration against historical installation schedules from North Sea offshore clusters and onshore utility-scale deployments shaped the analytical framework. Segmentation dimensions span product grade, material specification, installation environment, and end-user procurement channel. CAGRs were derived from slope-logic projection of certified fastener volumes against turbine OEM production forecasts and replacement cycle assumptions for 20-25 year design life verification.
Stress conditions across nickel-chromium price volatility, IEC standard revision timing, and third-party laboratory capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM supplier consolidation patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
SCR Power Controller Market
Power Equipment
Australia Power EPC Market
Power Equipment
Deaerators Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Power Cables Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Portable Power Station Market
Power Equipment
China Power EPC Market
Power Equipment
Uzbekistan Power EPC Market