
 Europe SCR Power Controller Market | 2026-2036
Europe SCR Power Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Europe SCR Power Controller Market Insights
Industrial-grade specification tiers above standard commercial ratings is rotating demand toward higher thermal cycling tolerance and enhanced electromagnetic compatibility. ABB Ltd. leverages its broad automation portfolio to anchor large-scale furnace retrofits across Continental Europe. Siemens AG dominates rail and heavy-machinery electrification with silicon-controlled rectifier modules engineered for 600V-plus bus architectures. Chromalox sustains niche leadership in precision thermal systems for pharmaceutical and chemical process lines.
The Europe SCR Power Controller is a solid-state power regulation device employing silicon-controlled rectifier thyristors to manage AC power delivery through phase-angle or burst-fire firing modes, typically handling load currents from tens to thousands of amperes across 110V–690V supply ranges. Its primary purpose is precise, contactless control of resistive and inductive loads in industrial heating, motor speed regulation, and lighting intensity management. Three-phase configurations command the dominant installed base owing to their compatibility with heavy industrial machinery and three-phase induction heating arrays. Panel-mounted installation types capture expanding share as OEMs integrate controllers into standardized electrical enclosures rather than standalone housings. Process control applications generate the most specialized demand, since semiconductor fabrication and chemical processing require sub-degree temperature stability that only closed-loop SCR firing can deliver.
CE marking under the EU Low Voltage Directive and Electromagnetic Compatibility Directive governs market access, while REACH restricts hazardous substances in semiconductor packaging and heat-sink coatings. The EU Green Deal's industrial decarbonization targets push end-users toward regenerative SCR architectures that recover braking energy in motor control loops. Ecodesign regulations from the European Commission mandate minimum efficiency thresholds for power conversion equipment above specified duty thresholds. Stakeholders must weigh compliance cost trajectories against the performance premium commanded by controllers certified for extended temperature ranges and marine-grade humidity resistance.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are compressing upgrade cycles across Continental Europe's heavy manufacturing base, forcing simultaneous replacement of thermal systems and their control electronics.
Growth Catalysts
- F-Gas Regulation phase-down:Refrigeration and heat-pump OEMs in France and Italy are retrofitting compressor test benches with precision SCR motor controls to meet fluorinated gas containment standards.
- Process control upgrades:German chemical clusters are deploying closed-loop thyristor firing for sub-degree temperature stability in polymerization reactors.
- Rail electrification:Traction motor refurbishment programs across Poland and Spain are specifying 600V-plus silicon-controlled rectifier modules for regenerative braking energy recovery.
Market Restraints
- Silicon carbide substrate costs:Wide-bandgap semiconductors for next-generation controllers face raw material concentration in Chinese processing facilities.
- REACH compliance burdens:ECHA restrictions on heat-sink coatings and semiconductor packaging additives extend certification timelines by eight to fourteen months.
- IGBT substitution pressure:Insulated-gate bipolar transistor modules are capturing sub-100kW motor control applications where switching frequency outweighs SCR ruggedness.
Strategic Opportunities
- Polish industrial corridor:Underpenetrated food-processing and packaging machinery sectors in Lower Silesia lack localized SCR service networks.
- Marine-grade certification:Ecodesign efficiency thresholds for offshore platform power conversion create premium positioning for humidity-resistant controllers.
- Digital twin integration:Convergence of thyristor firing algorithms with predictive maintenance software enables outcome-based thermal system contracts.
Industry Challenges
- Power electronics talent scarcity:Specialized thyristor firing circuit design expertise concentrates in southern German and Dutch technical universities.
- Legacy furnace integration:Cold-rolling mills in northern England and the Ruhr Valley operate 1970s-era control architectures with incompatible signal voltages.
- CE marking timeline compression:Notified body backlogs for Low Voltage Directive electromagnetic compatibility testing extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe SCR Power Controller Market |
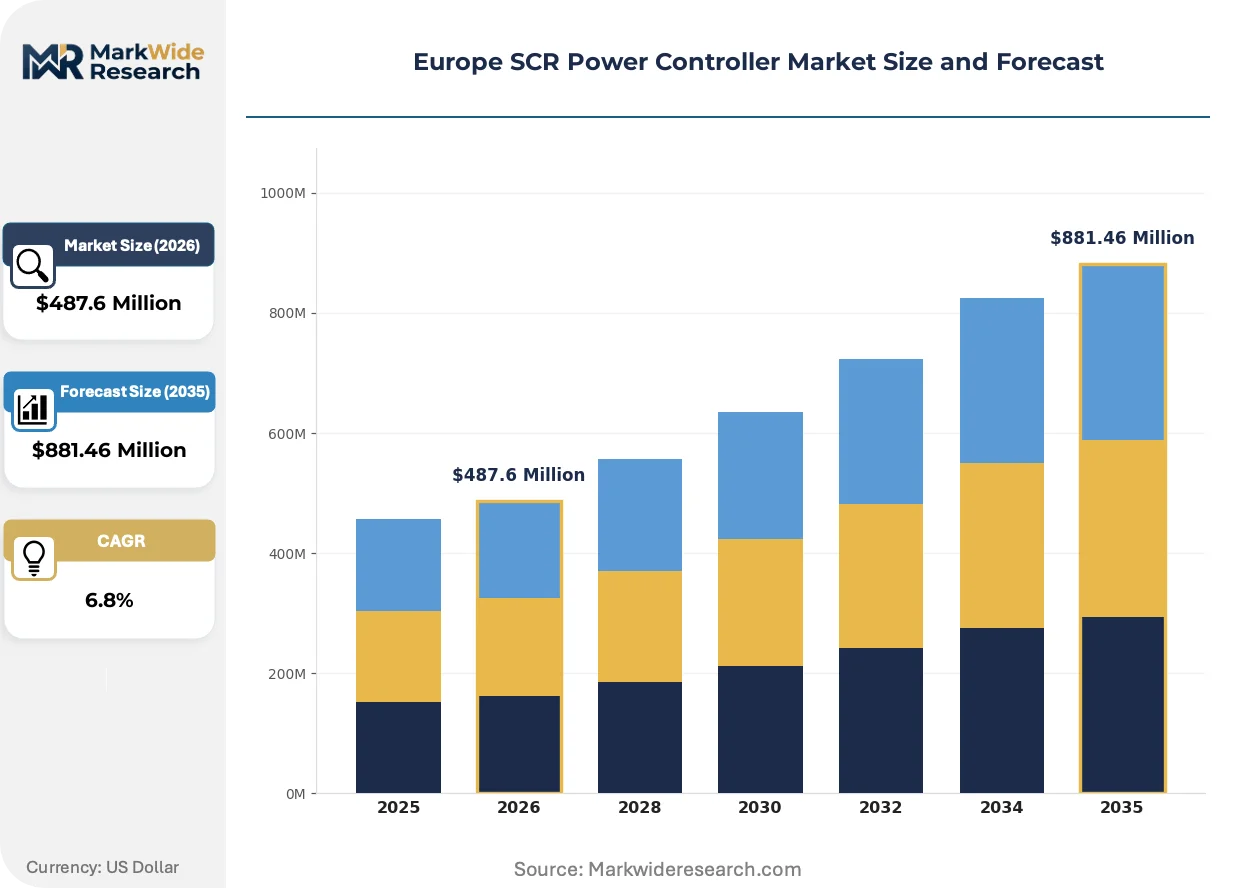
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Control Module, High-Power End User: Manufacturing, Automotive, Renewable Energy, Industrial Automation Installation Type: Indoor, Outdoor, Panel-Mounted, Wall-Mounted Application: Heating, Motor Control, Light Dimming, Process Control |
| Companies Covered | Gefran S.p.A., Watlow Electric Manufacturing Company, ABB Ltd., Chromalox, Omron Corporation, Schneider Electric SE, Advanced Energy Industries, Inc., Fuji Electric, Siemens AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe SCR Power Controller Market Trends and Innovations
Control architecture is splitting between premium digital platforms and cost-optimized analog designs as end-users stratify by automation maturity and thermal precision requirements.
Digital gate driver technology with integrated fiber-optic isolation is bifurcating the installed base. Pharmaceutical lyophilization equipment in Swiss and Belgian facilities adopts these modules for nanosecond firing resolution. Foundry and metal-casting operations in Turin and Bilbao retain analog triggering for electromagnetic immunity in high-arc environments. The technology divide is compressing mid-tier analog-digital hybrid controller margins while expanding service revenue attach rates for digital platforms.
EU Green Deal carbon border adjustment mechanisms are tightening embodied carbon accounting for imported power electronics. Industrial furnace operators in Germany and France now require supply chain documentation proving semiconductor fabrication energy sources. Italian and Spanish OEMs are qualifying domestic and near-shore thyristor foundries to preempt tariff exposure on Asian-sourced silicon wafers.
Buyer consolidation among European automotive battery cell producers is concentrating procurement leverage. Gigafactory thermal management system tenders in Hungary and Germany now specify five-year total cost of ownership guarantees rather than unit pricing. This compresses component supplier margins while rewarding controllers with predictive diagnostics and modular repair architectures. The shift is most visible in solid-state battery pilot lines where thermal ramp rate precision determines electrolyte formation quality.
Europe SCR Power Controller Market Segmentation
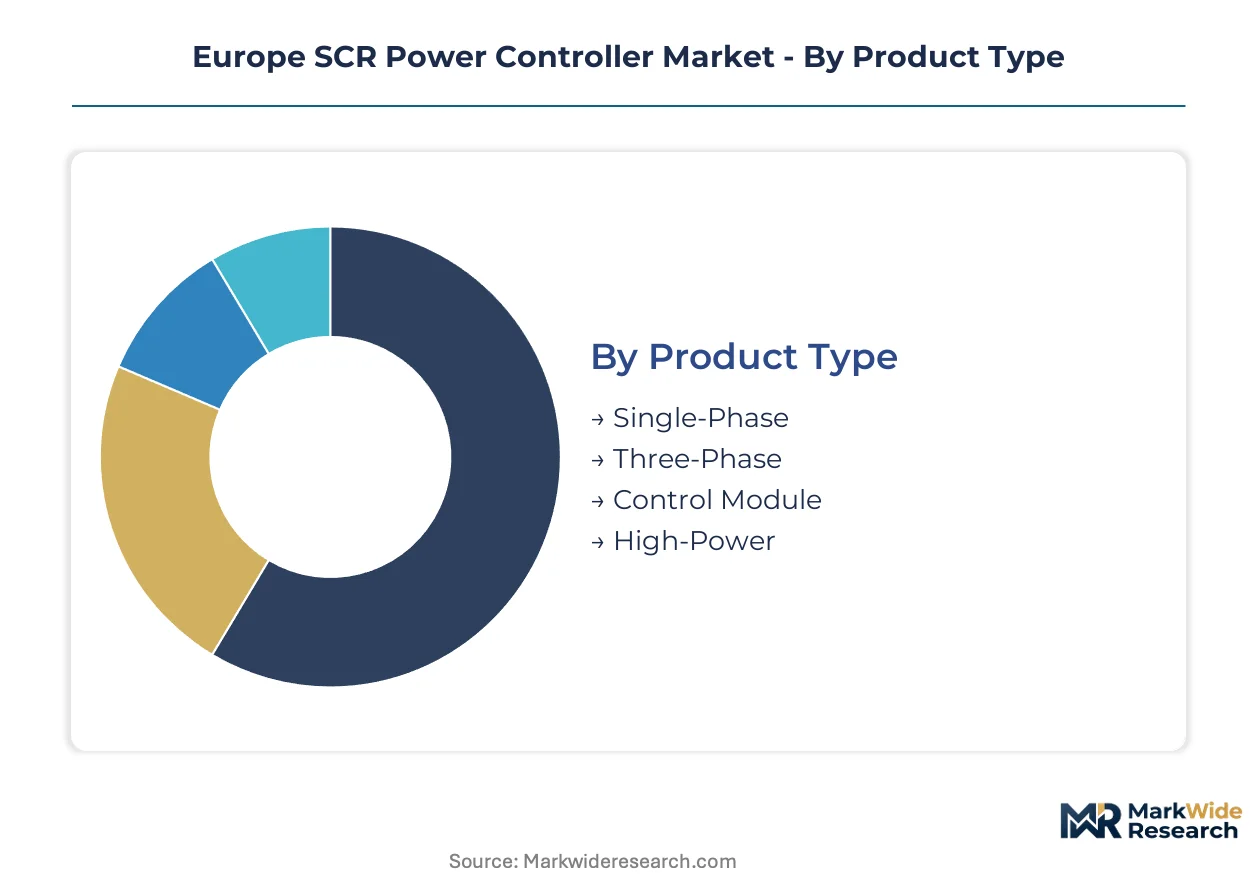
SCR power controller segmentation reveals where silicon-controlled rectifier technology retains pricing power against IGBT and MOSFET substitutes. Category boundaries increasingly blur as digital integration and modular architectures reshape procurement criteria across Continental Europe.
Product Type:
IGBT substitution pressure intensifies below 100kW ratings, forcing SCR suppliers to defend position through thermal ruggedness and phase-angle precision at higher power tiers.
- Three-Phase:Dominant configuration for heavy industrial machinery and induction heating arrays across 400V–690V supply ranges. German chemical clusters and Italian foundry operations specify these units for regenerative braking energy recovery in motor control loops. Three-phase anchors the volume base while high-power gains share at the steepest rate.
- Single-Phase:Compact units handling resistive loads up to 100A for laboratory equipment and small-scale thermal processing. Swiss pharmaceutical lyophilization equipment and Belgian food-processing lines concentrate demand where space constraints outweigh efficiency optimization.
- Control Module:Discrete thyristor firing circuits integrated into OEM-designed enclosures. French packaging machinery builders and Spanish automotive battery pilot lines embed these for customized thermal ramp profiles.
- High-Power:Water-cooled assemblies exceeding 1000A for electric arc furnaces and large-scale polymerization reactors. Polish steel refurbishment programs and northern English cold-rolling mill retrofits drive specialized procurement.
Three-phase controllers anchor the volume base while high-power units gain share at the steepest rate as Ecodesign efficiency mandates accelerate furnace replacement cycles.
End User:
Cost tier stratification separates premium precision buyers from price-sensitive volume purchasers, with certification requirements widening the gap.
- Industrial Automation:Closed-loop temperature stability demands in semiconductor fabrication and chemical processing command premium pricing. German SPC-based manufacturing lines and Dutch petrochemical facilities specify sub-degree precision controllers with predictive diagnostics.
- Manufacturing:Broad deployment across metal-forming, glass tempering, and ceramics firing where thermal cycling tolerance determines equipment lifespan. Italian ceramic tile producers and Spanish aluminum extruders dominate procurement volumes.
- Automotive:Gigafactory thermal management systems for battery cell formation and solid-state electrolyte processing. Hungarian and German battery producers now demand five-year total cost of ownership guarantees.
- Renewable Energy:Biogas digester heating and solar thermal storage applications. French agricultural cooperatives and Italian district heating networks deploy burst-fire controllers for load balancing.
Manufacturing anchors the volume base while automotive gains share most quickly as battery cell capacity expansion accelerates across Central Europe.
Installation Type:
Volume concentration favors standardized electrical enclosures over standalone housings as OEM integration deepens.
- Panel-Mounted:DIN-rail or chassis-mounted units integrated into standardized electrical enclosures. German automation OEMs and French system integrators specify these for modular repair architectures and reduced downtime.
- Indoor:Enclosed controllers for climate-controlled plant environments. Belgian pharmaceutical cleanrooms and Swiss precision manufacturing facilities require electromagnetic compatibility certification for sensitive instrumentation.
- Outdoor:Weather-resistant housings with IP65-plus ratings for remote pumping stations and agricultural applications. Spanish irrigation systems and Polish district heating substations concentrate demand.
- Wall-Mounted:Compact standalone units for commercial heating and ventilation retrofits. Italian hospitality sector and French municipal building upgrades drive replacement cycles.
Panel-mounted configurations anchor the volume base while outdoor installations expand most quickly as distributed energy assets proliferate across rural Europe.
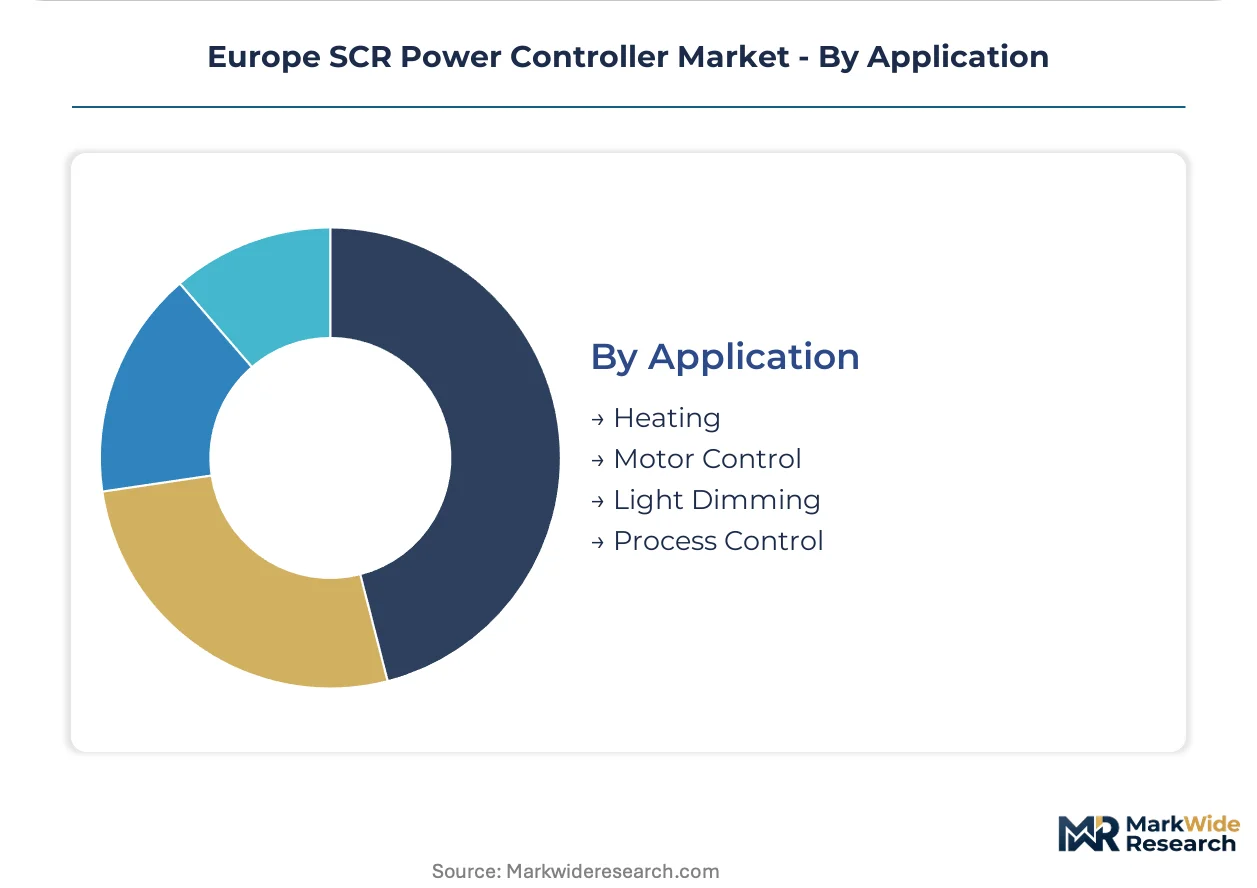
Application:
Margin structure diverges sharply between commodity heating controls and precision process applications with diagnostic integration.
- Process Control:Closed-loop thyristor firing for polymerization reactors, distillation columns, and semiconductor diffusion furnaces. German BASF-Ludwigshafen chemical clusters and Infineon Dresden fabrication lines specify nanosecond firing resolution modules.
- Heating:Resistive load management for industrial furnaces, ovens, and heat-treatment equipment. Turin metal-casting operations and Bilbao foundry facilities retain analog triggering for electromagnetic immunity in high-arc environments.
- Motor Control:Phase-angle regulation for soft-starting and speed control of induction motors. Rail traction refurbishment programs across Poland and Spain specify 600V-plus modules for regenerative braking.
- Light Dimming:Burst-fire control for theatrical and architectural lighting systems. Limited penetration outside specialized entertainment and museum sectors in Paris and London.
Heating applications anchor the volume base while process control gains share at the steepest rate as pharmaceutical and battery chemical precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thyristor controller assembly and precision thermal engineering expertise clusters in southern Germany and the Netherlands, with German automation OEMs and Dutch system integrators driving panel-mounted integration standards across Continental Europe.
Germany
Process control upgrades in BASF-Ludwigshafen chemical clusters and Infineon Dresden fabrication lines demand nanosecond firing resolution modules. The EU Green Deal's industrial decarbonization targets compress upgrade cycles for thermal systems and control electronics. Ruhr Valley cold-rolling mills and Bavarian automotive battery pilot lines concentrate specialized procurement for regenerative SCR architectures.
France
F-Gas Regulation phase-down drives refrigeration and heat-pump OEMs to retrofit compressor test benches with precision SCR motor controls. Ecodesign regulations from the European Commission mandate minimum efficiency thresholds for power conversion equipment above specified duty thresholds. Parisian pharmaceutical cleanrooms and Auvergne-Rhône-Alpes packaging machinery builders embed control modules for customized thermal ramp profiles.
Italy
Ceramic tile producers in Emilia-Romagna and aluminum extruders in Lombardy dominate manufacturing procurement volumes. REACH restrictions on heat-sink coatings and semiconductor packaging additives extend certification timelines by eight to fourteen months. Turin metal-casting operations and foundry facilities in Veneto retain analog triggering for electromagnetic immunity in high-arc environments.
Spain
Rail traction refurbishment programs specify 600V-plus silicon-controlled rectifier modules for regenerative braking energy recovery. The EU Low Voltage Directive and Electromagnetic Compatibility Directive govern CE marking market access. Bilbao foundry facilities and Madrid-area automotive battery pilot lines concentrate demand for closed-loop thyristor firing systems.
Poland
Steel refurbishment programs and Lower Silesia food-processing machinery sectors drive specialized procurement for water-cooled assemblies exceeding 1000A. District heating substations and agricultural irrigation systems concentrate outdoor installation demand. Underpenetrated packaging machinery sectors lack localized SCR service networks, creating strategic entry opportunities.
Europe SCR Power Controller Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with diversified industrial conglomerates commanding premium positioning through automation portfolio breadth while specialized thermal engineering firms defend niche margins in precision process applications. The vendor base stratifies across three tiers: integrated automation platforms with global service networks, regional power electronics specialists with customized firing circuit expertise, and component suppliers focused on discrete thyristor modules. Consolidation pressure intensifies as battery gigafactory tenders demand five-year total cost of ownership guarantees, compressing component supplier margins while rewarding predictive diagnostics capabilities.
Among diversified European industrial conglomerates, ABB Ltd. and Siemens AG exemplify the integrated automation platform archetype, anchoring large-scale furnace retrofits and rail electrification programs through broad portfolio leverage. Chromalox occupies a position within the precision thermal specialist tier, serving pharmaceutical and chemical process lines where sub-degree temperature stability commands premium pricing. These three players represent distinct competitive vectors: portfolio breadth, vertical market depth, and application-specific engineering intensity.
| Leading Market Players |
|---|
| Gefran S.p.A. |
| Watlow Electric Manufacturing Company |
| ABB Ltd. |
| Chromalox |
| Omron Corporation |
| Schneider Electric SE |
| Advanced Energy Industries, Inc. |
| Fuji Electric |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements between German automotive battery producers and thyristor module suppliers lock in silicon wafer access while freezing price visibility across five-year total cost of ownership frameworks. These contracts concentrate procurement leverage among gigafactory operators in Hungary and Germany, forcing component suppliers to absorb margin compression in exchange for volume guarantees.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across the Europe SCR Power Controller Market, separating CE-marked premium units with extended temperature certification from standard commercial ratings. Price differentiation hinges on electromagnetic compatibility testing depth and marine-grade humidity resistance certification. Cost compression in mid-tier analog-digital hybrid controllers is intensifying because IGBT substitution pressure below 100kW ratings forces SCR suppliers to defend position through thermal ruggedness. Automotive battery cell producers exhibit lowest price sensitivity due to five-year total cost of ownership guarantees, while Italian ceramic tile manufacturers and Spanish aluminum extruders drive hardest unit-price negotiations.
Supply Chain Analysis
China and South Korea anchor silicon wafer and thyristor die fabrication for the Europe SCR Power Controller Market, with German and Dutch facilities handling final assembly and firing circuit integration. Raw material dependencies center on high-purity silicon ingots, copper heat-sink substrates, and ceramic isolation substrates. Single-source vulnerability concentrates in Chinese processing facilities for wide-bandgap silicon carbide substrates. Distribution runs through German automation OEMs and French system integrators specifying panel-mounted configurations for modular repair architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the Europe SCR Power Controller Market as battery gigafactory tenders concentrate procurement leverage while underpenetrated food-processing corridors in Poland lack localized service networks. The demand-side shift toward predictive diagnostics and outcome-based thermal system contracts creates niche openings for specialized firing circuit engineers.
For Market Incumbents: Compound predictive maintenance software attach rates to thyristor firing platforms, converting hardware sales into recurring service revenue streams. Deepen backward integration into domestic thyristor foundries to preempt REACH compliance delays and carbon border adjustment exposure. IGBT substitution pressure below 100kW ratings threatens volume tiers; defend position through regenerative braking energy recovery certification for rail and heavy-machinery electrification. For New Entrants and Emerging Players: Predictive diagnostics capability gaps in Polish and Spanish industrial corridors offer white-space entry points where ABB and Siemens service density thins. Target Lower Silesia food-processing machinery sectors with localized repair networks and rapid-response firing circuit calibration. Embed digital twin integration into thermal ramp profile customization for automotive battery pilot lines as the primary go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward precision thermal specialists with pharmaceutical and chemical process line credentials, where sub-degree temperature stability commands durable pricing power. Long-term viability rests on defensible firing circuit engineering talent concentrated in southern German and Dutch technical universities. Watch for inflection when battery gigafactory tenders shift from unit pricing to guaranteed thermal ramp rate precision metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Thyristor Foundries | Italian and Spanish OEMs qualify near-shore silicon sources to preempt EU carbon border tariffs on Asian wafers. |
| Predictive Diagnostics Platform Development | German battery producers demand five-year total cost of ownership guarantees requiring modular repair architectures. |
| Marine-Grade Certification Investment | Ecodesign efficiency thresholds for offshore platform power conversion create premium positioning for humidity-resistant controllers. |
| Digital Twin Integration Partnership | Swiss pharmaceutical lyophilization equipment adopts fiber-optic isolated gate drivers for nanosecond firing resolution. |
| Polish Service Network Expansion | Underpenetrated Lower Silesia packaging machinery sectors lack localized SCR firing circuit calibration expertise. |
Research Methodology
Desk research of EU regulatory filings, ECHA REACH restriction updates, and Ecodesign implementing measures preceded structured interviews with plant engineers at German chemical clusters, procurement leads at French packaging machinery OEMs, and aftermarket service heads at Dutch system integrators. Secondary validation drew from CE marking notification body databases, customs trade data for thyristor module imports, and SEC filings of listed power electronics conglomerates. Bottom-up demand modeling across installation types and end-user segments was cross-checked against top-down industry association capacity estimates.
Variance decomposition across product type, end user, installation configuration, and application dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro industrial automation capex indicators. Key forecast inputs included F-Gas Regulation phase-down timelines for refrigeration OEM compressor test bench retrofits and rail electrification refurbishment program announcements across Poland and Spain.
Forecasts assume regulatory continuity in EU Green Deal industrial decarbonization mandates and REACH substance restrictions; material policy shifts would require re-modeling. Semiconductor fabrication energy source documentation requirements and carbon border adjustment mechanism implementation pace represent specific revision triggers. Recalibration cycles align with material shifts in battery gigafactory tender specifications and notified body backlogs for Low Voltage Directive electromagnetic compatibility testing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
France Power EPC Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Australia Power EPC Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Thailand Power Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
North America Gas Turbine Market
Power Equipment
China Power EPC Market
Power Equipment
Nigeria Power EPC Market