
 China Power EPC Market | 2026-2036
China Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
China Power EPC Market Outlook
The China Power EPC Market is recalibrating around a widening split between premium integrated turnkey contracts and commodity construction services. PowerChina leverages its hydropower heritage to dominate complex mega-dam projects. CEEC anchors its position through thermal-to-renewables conversion expertise. Harbin Electric Corporation differentiates via turbine generator manufacturing scale.
Power EPC encompasses the full-scope engineering, procurement, and construction of electricity generation and transmission infrastructure, typically involving equipment sourcing, civil works, and commissioning with performance guarantees of 25-40 years for major assets. Its commercial purpose centers on delivering bankable, on-budget energy assets to utility offtakers. Thermal retrofit segments carry mature margin pools while offshore wind installation commands premium pricing. Solar EPC competes on standardized module deployment velocity. Hydro and wind technology segments lead in contract value concentration.
MIIT equipment certification rules and MEE environmental impact assessments shape project approval timelines and technology selection criteria. GB standards for grid code compliance and SAMR construction safety audits determine contractor qualification tiers. Stakeholders must monitor how provincial energy bureaus interpret national dual carbon targets into enforceable project pipelines.
Market Dynamics
The China Power EPC Market is restructuring around coal-to-renewables retrofit mandates issued by MEE under dual carbon directives, compressing thermal project timelines while accelerating offshore wind procurement in coastal provinces.
Growth Catalysts
- MEE Dual Carbon Enforcement:Binding emissions reduction targets are forcing provincial energy bureaus to approve renewable retrofit pipelines at unprecedented velocity, creating guaranteed project backlogs for qualified contractors.
- Offshore Wind Clustering:Jiangsu and Guangdong provincial governments are aggregating seabed leases into multi-gigawatt procurement bundles that favor integrated turnkey EPC providers with marine construction capabilities.
- State Grid Procurement Reform:Centralized tendering for ultra-high voltage transmission corridors is consolidating contract awards toward full-scope EPC consortia capable of delivering 25-year performance guarantees.
Market Restraints
- Steel and Copper Input Volatility:Fluctuations in commodity pricing for transformer cores and transmission tower materials are eroding fixed-price contract margins, particularly for thermal retrofit segments with limited pass-through clauses.
- Marine Construction Equipment Concentration:Heavy-lift vessel availability for offshore wind foundation installation remains bottlenecked at yards in Nantong and Yantai, creating scheduling dependencies for coastal project execution.
- Grid Code Compliance Friction:Evolving GB standards for inverter synchronization and frequency response are extending commissioning timelines for solar and wind assets, delaying revenue recognition for EPC contractors.
Strategic Opportunities
- Western Province Renewable Bases:Qinghai and Gansu are opening multi-terawatt-hour wind-solar-hydro hybrid complexes with dedicated ultra-high voltage export corridors, creating greenfield EPC demand outside saturated coastal markets.
- Electrolyzer-Integrated Power Plants:Hydrogen production offtake agreements are enabling merchant renewable projects with captive demand, requiring EPC scope expansion into electrolyzer balance-of-plant engineering.
- MIIT Equipment Certification Acceleration:Streamlined testing protocols for domestically manufactured turbine generators are shortening procurement cycles for hydro and thermal units, favoring contractors with in-house equipment supply partnerships.
Industry Challenges
- Grid Integration Engineering Talent Scarcity:Shortages of power systems engineers capable of modeling inverter-based resource stability are delaying project handovers and forcing reliance on expensive third-party consultants.
- SAMR Construction Safety Audit Complexity:Escalating documentation requirements for high-voltage substation civil works are extending pre-construction approval phases, compressing execution windows for seasonal construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Power EPC Market |
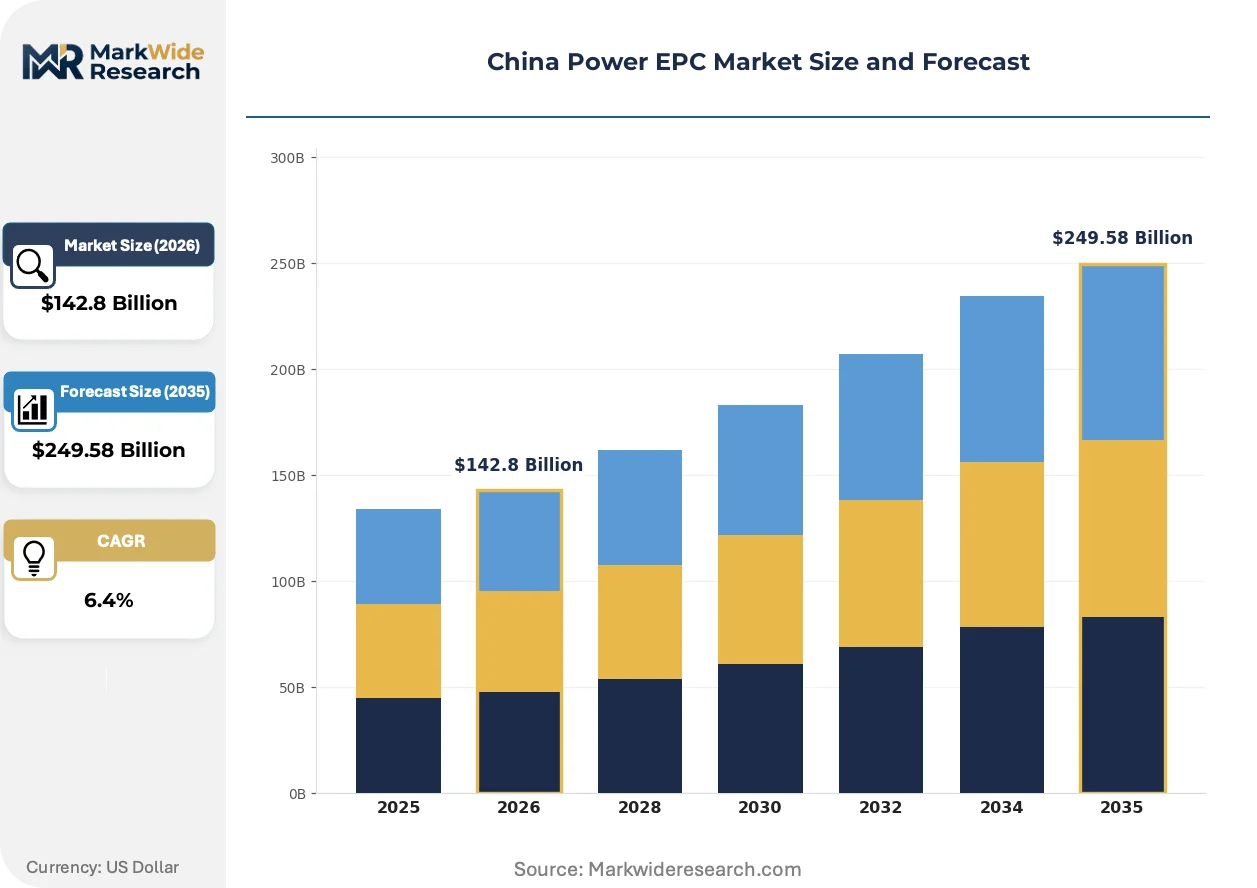
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $249.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management Technology: Thermal, Hydro, Wind, Solar End User: Utilities, Industrial, Government, Commercial Installation: Onshore, Offshore, Remote, Urban |
| Companies Covered | Power Construction Corporation of China (PowerChina), China Energy Engineering Corporation (CEEC), China National Electric Wire & Cable I/E Corp, Datang International Power Generation Company Limited, ShanDong Energy Group Co. Ltd, China Three Gorges Corporation, China National Electric Engineering Co. Ltd, Harbin Electric Corporation, Snc-Lavalin Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Power EPC Market Strategic Shifts
Digital twin deployment and modular construction methods are compressing EPC project timelines while reshaping contractor capability requirements across generation and transmission segments.
Modular substation architecture is decentralizing traditional site-built construction models. State Grid and regional utilities are specifying prefabricated GIS enclosures and skid-mounted transformer assemblies to reduce on-site labor dependencies. This technology is decentralizing project execution geography, enabling inland manufacturing hubs to serve coastal demand clusters without mobilizing specialized field crews.
MEE environmental impact assessment streamlining under revised administrative licensing rules is compressing project approval timelines from 18 months to 9 months for renewable assets in designated development zones. Thermal retrofit projects face stricter cumulative impact reviews, diverting regulatory attention and capital allocation toward greenfield wind and solar installations in western provinces.
Utility offtakers are unbundling long-term O&M contracts from initial EPC awards, forcing contractors to compete on construction-only margins while ceding 25-year service revenue streams to specialized asset managers. This pattern is most pronounced in Guangdong offshore wind auctions, where operators are separating foundation installation from turbine commissioning and interconnection scope to optimize specialist matching.
China Power EPC Market Segmentation
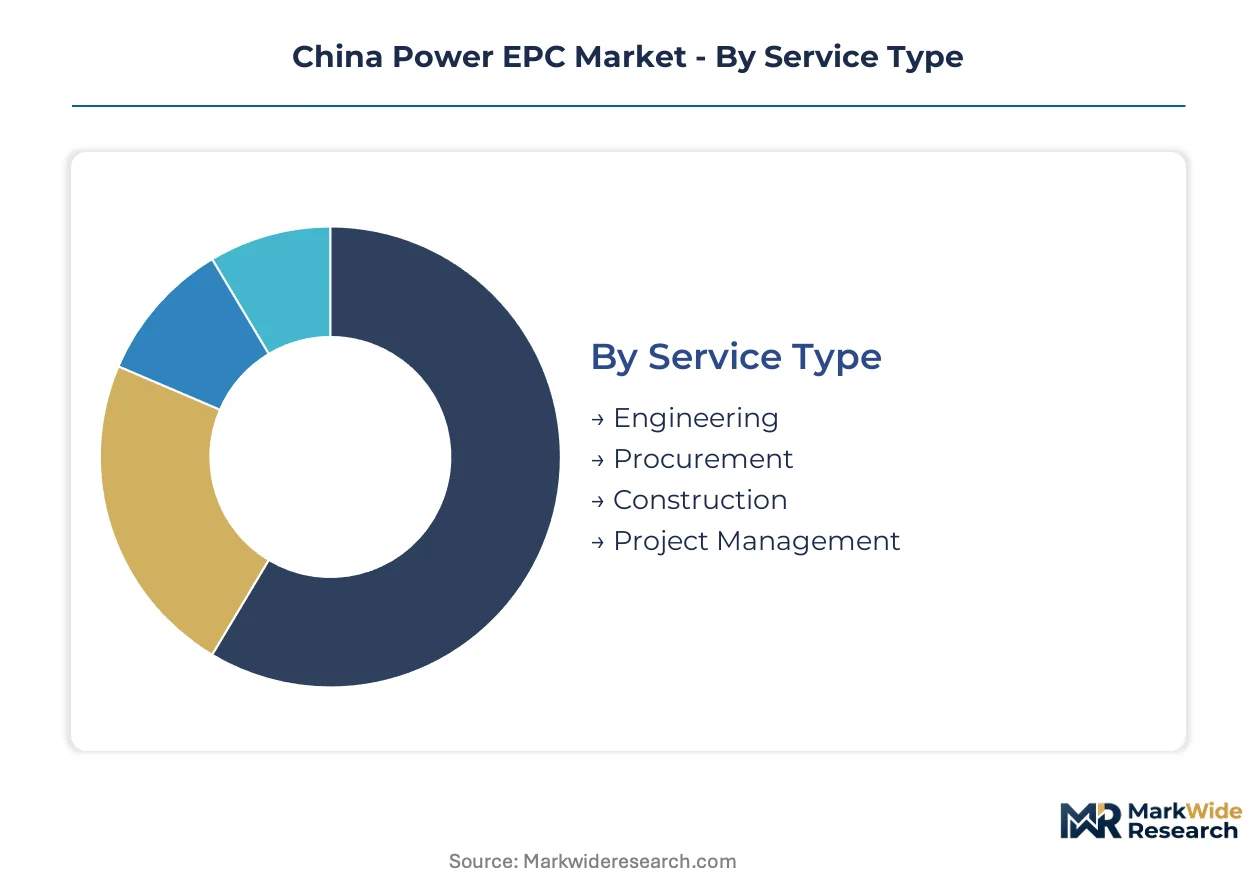
Power EPC contractors configure service portfolios around technology-specific execution risks and procurement complexity. Segment boundaries determine margin structure, capability requirements, and competitive positioning across China's dual carbon transition.
Service Type:
Upgrade cycles differentiate service intensity, with integrated turnkey contracts commanding premium positioning over discrete engineering or procurement-only engagements.
- Engineering:Front-end design and feasibility studies establish project bankability, with State Grid and regional utilities consolidating design-build contracts to compress approval timelines under MEE dual carbon mandates.
- Procurement:Equipment sourcing and vendor qualification absorb 45-60% of total project cost, with MIIT certification requirements for domestic turbine generators and transformers extending procurement cycles for hydro and ultra-high voltage assets.
- Construction:Civil works and installation execution face SAMR safety audit escalation, particularly for high-voltage substations and marine foundation work in Jiangsu and Guangdong offshore zones.
- Project Management:Owner's engineer services and construction supervision are unbundling from full-scope EPC as utilities seek specialist oversight for complex grid integration and inverter synchronization compliance.
Construction sits at the top of the volume ranking, with Project Management climbing the fastest as utilities fragment contractor scope to optimize specialist matching.
Technology:
Cost tiers separate mature thermal retrofits from capital-intensive offshore wind and standardized solar deployment, reshaping contractor capability investments.
- Thermal:Coal-to-gas and efficiency retrofit projects carry compressed margins but guaranteed pipeline volume under MEE emissions enforcement, with execution concentrated in northern provinces facing binding reduction targets.
- Hydro:Mega-dam and pumped-storage projects command the highest contract values and longest execution horizons, with PowerChina leveraging heritage expertise to dominate procurement for western province complexes in Qinghai and Sichuan.
- Wind:Onshore installations compete on turbine deployment velocity while offshore projects in Jiangsu and Guangdong require marine construction partnerships and heavy-lift vessel access from Nantong and Yantai yards.
- Solar:Utility-scale photovoltaic EPC has standardized around module mounting and inverter integration, with western province greenfield development in Gansu and Qinghai absorbing capacity as coastal markets saturate.
Thermal retains the largest installed base, with Wind gaining share fastest on offshore clustering and western province onshore expansion.
End User:
Customer type determines contract structure, performance guarantee duration, and O&M unbundling patterns across generation and transmission assets.
- Utilities:State Grid Corporation and regional power groups dominate procurement volume, consolidating ultra-high voltage corridor awards toward full-scope EPC consortia capable of 25-year performance commitments.
- Industrial:Captive power and merchant renewable projects with hydrogen offtake agreements are emerging in chemical and steel sectors, requiring electrolyzer balance-of-plant integration into EPC scope.
- Government:Provincial energy bureaus in Jiangsu, Guangdong, and western provinces aggregate seabed leases and renewable base development rights into multi-gigawatt procurement bundles.
- Commercial:Distributed solar and microgrid installations for data centers and manufacturing campuses compete on standardized deployment speed with limited customization requirements.
Utilities command the dominant contract volume, with Industrial expanding most quickly on captive demand and hydrogen integration.
Installation:
Geography dictates execution complexity, equipment specialization, and labor mobilization patterns across China's diverse terrain and coastal zones.
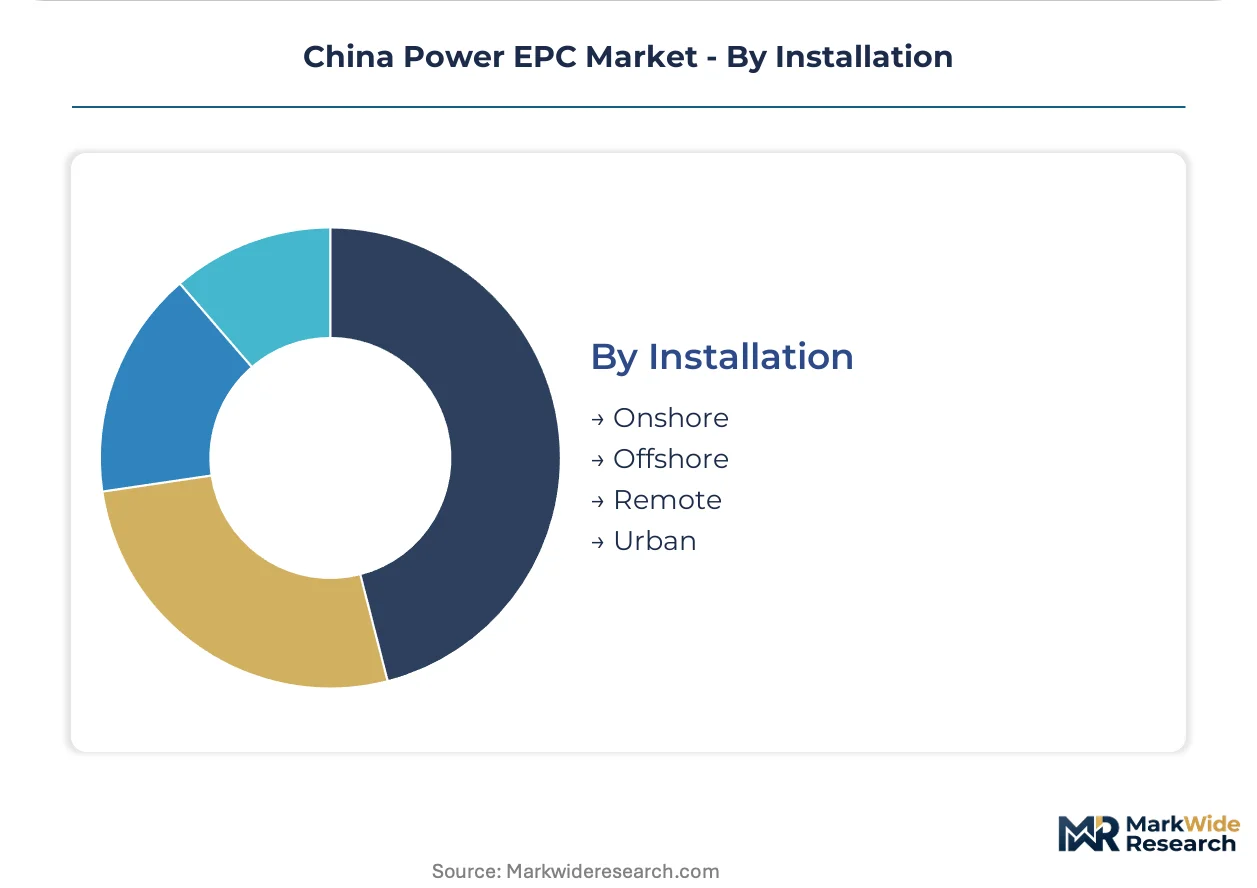
- Onshore:Conventional wind and solar installations in Gansu, Qinghai, and Inner Mongolia benefit from land availability and dedicated ultra-high voltage export corridors, with modular substation architecture reducing field crew dependencies.
- Offshore:Jiangsu and Guangdong seabed developments require marine engineering partnerships, heavy-lift vessel scheduling, and GB standard grid code compliance for distant shore connection, creating premium pricing tiers.
- Remote:Western province hybrid complexes face logistics constraints and seasonal construction windows, compressing execution schedules and favoring contractors with established inland supply chain presence.
- Urban:Grid reinforcement and substation upgrades in coastal megacities confront land scarcity, SAMR safety documentation intensity, and limited construction windows due to population density.
Onshore maintains the largest project pipeline, with Offshore showing the steepest expansion trajectory on provincial procurement bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine construction crews and ultra-high voltage transmission engineers concentrate in coastal provinces, while western regions draw civil works contractors experienced in high-altitude logistics and seasonal construction windows.
Jiangsu Province
Offshore wind foundation installation dominates procurement activity, with seabed lease aggregation creating multi-gigawatt development corridors. MEE dual carbon enforcement timelines compress project approval cycles to nine months in designated coastal zones. Nantong heavy-lift vessel yards anchor marine construction capacity, with installation fleets serving Guangdong developments during Jiangsu seasonal downtime.
Guangdong Province
Greater Bay Area grid reinforcement and distant-shore wind clustering absorb premium EPC capacity, with urban substation upgrades confronting land scarcity constraints. Provincial energy bureau procurement bundling favors integrated turnkey contractors capable of 25-year performance guarantees. Shenzhen and Zhuhai manufacturing hubs produce prefabricated GIS enclosures for modular substation deployment across southern coastal demand clusters.
Qinghai Province
Wind-solar-hydro hybrid base development in the Qaidam Basin requires contractors with high-altitude logistics experience and ultra-high voltage corridor integration expertise. National Energy Administration renewable base designations guarantee pipeline volume through 2030. Golmud and Xining serve as inland supply chain nodes, with dedicated UHVDC export lines connecting western generation to eastern load centers.
Sichuan-Chongqing Region
Pumped-storage and mega-dam construction anchor contract value concentration, with PowerChina heritage positioning dominating procurement for Jinsha River and Yalong River complexes. MEE environmental impact assessments for hydro projects maintain 18-month review timelines despite renewable streamlining elsewhere. Chengdu engineering consultancies supply specialized geotechnical and hydrological modeling capacity for western province developments.
Gansu Province
Utility-scale photovoltaic and onshore wind installations benefit from land availability and dedicated UHV export infrastructure, with modular construction methods reducing field crew mobilization requirements. Provincial energy bureau aggregation of desert renewable bases creates standardized deployment opportunities for velocity-focused contractors. Jiuquan and Wuwei anchor manufacturing and logistics nodes serving Hexi Corridor development corridors.
China Power EPC Market Competitive Environment
Top-tier vendors anchor full-scope integrated turnkey delivery, while mid-tier specialists compete on discrete engineering or construction-only margins. The vendor base stratifies around equipment manufacturing heritage, marine construction capability, and thermal-to-renewables conversion expertise. Three archetypes dominate: state-owned integrated conglomerates with in-house equipment supply, regional construction specialists with provincial bureau relationships, and marine engineering contractors with heavy-lift vessel access. Consolidation pressure operates through State Grid procurement reform favoring 25-year guarantee capacity, while technology licensing partnerships expand geographic reach without capital-intensive yard investments.
Within the state-owned integrated tier, Power Construction Corporation of China (PowerChina) and China Energy Engineering Corporation (CEEC) occupy positions defined by hydropower heritage and thermal conversion expertise respectively. Harbin Electric Corporation anchors equipment manufacturing scale, representing the turbine generator supply archetype that shortens procurement cycles through MIIT certification integration. These three exemplify how execution risk concentration and in-house capability depth determine competitive positioning under dual carbon procurement acceleration.
| Leading Market Players |
|---|
| Power Construction Corporation of China (PowerChina) |
| China Energy Engineering Corporation (CEEC) |
| China National Electric Wire & Cable I/E Corp |
| Datang International Power Generation Company Limited |
| ShanDong Energy Group Co. Ltd |
| China Three Gorges Corporation |
| China National Electric Engineering Co. Ltd |
| Harbin Electric Corporation |
| Snc-Lavalin Group Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive equipment manufacturing within state-owned conglomerates anchors both supply security and pricing power for integrated turnkey contracts. PowerChina, CEEC, and Harbin Electric leverage in-house turbine generator production and MIIT certification integration to compress procurement cycles while commanding premium positioning against construction-only competitors.
Pricing Analysis
Bundled full-scope EPC contracts with 25-year performance guarantees command substantial premiums over unbundled construction-only awards. Pricing stratifies across integrated turnkey, hybrid engineering-procurement, and discrete construction tiers based on technology complexity and marine capability requirements. Cost compression in thermal retrofit segments intensifies due to steel and copper input volatility with limited pass-through clauses. State Grid and regional utilities show lowest price sensitivity for offshore wind and ultra-high voltage corridors, while distributed solar procurement exhibits highest sensitivity to module deployment velocity.
Supply Chain Analysis
Workforce availability constraints in Nantong and Yantai heavy-lift vessel yards bottleneck marine foundation installation capacity for Jiangsu and Guangdong offshore developments. Domestic manufacturing of turbine generators, transformers, and GIS enclosures concentrates in Harbin, Shanghai, and Shenzhen industrial clusters. Raw material dependencies span transformer core steel, copper winding stock, and high-grade concrete additives. Single-source vulnerability runs through specialized heavy-lift vessel scheduling for offshore wind. Distribution feeds from inland manufacturing hubs through State Grid centralized tendering corridors to coastal demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between western province renewable bases and coastal offshore clusters exploits divergent MEE approval timelines and labor cost structures. Qinghai and Gansu project pipelines benefit from streamlined nine-month environmental assessments versus thermal retrofit complexity elsewhere.
For Market Incumbents: Extend marine construction equipment partnerships to secure heavy-lift vessel scheduling priority across Jiangsu and Guangdong seasonal windows. Deepen in-house turbine generator manufacturing through MIIT certification acceleration to defend margin position against commoditized solar EPC entrants. Consolidate ultra-high voltage corridor expertise as State Grid procurement reform favors 25-year guarantee capacity. For New Entrants and Emerging Players: Modular substation architecture offers technology-first entry into urban grid reinforcement segments with reduced field crew dependencies. Target western province wind-solar-hydro hybrid complexes in Qinghai and Gansu where land availability and dedicated export corridors create penetrable procurement bundles. Pursue electrolyzer balance-of-plant integration partnerships with chemical and steel sector captive power developers as hydrogen offtake agreements expand EPC scope. For Investors and Strategic Acquirers: Roll-up economics work for regional construction specialists with provincial energy bureau relationships because SAMR safety audit complexity and MEE licensing fragmentation prevent rapid organic scaling. Five-to-ten year viability hinges on dual carbon enforcement durability and State Grid procurement consolidation pace. Monitor heavy-lift vessel yard expansion in Nantong and Yantai as inflection indicator for offshore wind capacity absorption versus bottleneck persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Construction Equipment Partnership | Secures heavy-lift vessel access for Jiangsu and Guangdong offshore foundation installation scheduling. |
| MIIT Certification Acceleration | Shortens procurement cycles for domestically manufactured turbine generators and transformer assets. |
| Modular Substation Manufacturing Scale-Up | Reduces on-site labor dependencies for urban grid reinforcement and coastal demand clusters. |
| Electrolyzer Balance-of-Plant Integration | Captures hydrogen production offtake opportunities in chemical and steel sector captive power. |
| Western Province Logistics Hub Establishment | Positions contractors for Qinghai and Gansu wind-solar-hydro hybrid base execution windows. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned utility planning officers at State Grid and regional power groups, EPC contractor project directors, provincial energy bureau officials, marine construction fleet operators, and equipment manufacturing procurement leads. Secondary validation drew from National Energy Administration project development databases, MIIT equipment certification registries, MEE environmental impact assessment filings, and SAMR construction safety audit documentation. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Comparable historical periods anchored the projection horizon to observed execution timelines under prior MEE regulatory frameworks. Segmentation modeling spanned service type, technology category, end-user archetype, and installation geography across the forecast period. CAGRs derived from contract value growth trajectories and capacity expansion announcements. Industry-specific inputs included offshore wind seabed lease aggregation patterns, ultra-high voltage corridor commissioning schedules, and thermal retrofit mandate enforcement intensity.
The model holds under sustained MEE dual carbon enforcement and State Grid procurement consolidation; deviation in heavy-lift vessel capacity expansion or GB standard grid code revision timing would shift contractor margin structures and project completion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Chad Power EPC Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Digital Power Conversion Market
Power Equipment
North America Gas Turbine Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Deaerators Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Global Hydraulic Power Unit Market