
 West Africa Oil and Gas Upstream Market | 2026-2036
West Africa Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Oil and Gas Upstream Market Analytics
European Union methane intensity standards for imported natural gas is broadening compliance obligations for West African LNG exporters. TotalEnergies SE leverages integrated project execution across Nigerian deepwater assets to sustain cost discipline. Shell plc anchors its regional portfolio through offshore production in Ghana and Nigeria. Kosmos Energy Ltd specializes in frontier basin exploration along the Atlantic Margin.
West Africa oil and gas upstream encompasses the search for, recovery of, and initial processing of crude oil and natural gas from subsurface reservoirs, typically involving seismic surveys, drilling operations, and well completion at depths ranging from shallow continental shelves to ultra-deepwater zones exceeding 1,500 meters. Production activity dominates value generation across the type dimension, while enhanced oil recovery represents the fastest-expanding technology segment as mature fields require artificial lift and chemical injection to maintain output. Well services command the largest margin pool within service type categories due to recurring intervention requirements across aging asset bases.
Nigeria's Petroleum Industry Act and Ghana's Petroleum Commission licensing framework shape fiscal terms, local content quotas, and environmental bonding requirements for operators across the region. The Environmental Protection Agency in Ghana and Nigeria's Department of Petroleum Resources enforce offshore discharge standards and decommissioning liabilities that elevate capital commitments. Stakeholders must monitor how fiscal stability clauses and carbon border adjustments in European buyer markets reshape project economics and offtake negotiations.
Market Dynamics
The European Union methane intensity standards for imported natural gas are forcing West African LNG exporters to reconfigure measurement infrastructure and certification protocols ahead of contractual renewal cycles.
Growth Catalysts
- Deepwater exploration licensing:Senegal and Mauritania's offshore blocks attract capital allocation through revised fiscal terms and extended exploration periods.
- Enhanced oil recovery adoption:Artificial lift and chemical injection technologies extend productive life of mature Nigerian and Ghanaian fields.
- Regional refinery expansion:Ghana and Côte d'Ivoire operators increase offtake commitments for regional crude, tightening supply-demand alignment.
Market Restraints
- Capital intensity barriers:Ultra-deepwater development exceeding 1,500 meters requires specialized rig contracts and subsea infrastructure.
- Regulatory friction:Nigeria's Petroleum Industry Act introduces fiscal instability clauses that complicate long-term project financing.
- Supply concentration risk:Well services and intervention capabilities cluster around Lagos and Port Harcourt, creating bottleneck vulnerability.
Strategic Opportunities
- Frontier basin development:Mauritania's offshore gas discoveries offer first-mover positioning for integrated LNG export infrastructure.
- Carbon capture integration:Decommissioning liabilities under Ghana's Environmental Protection Agency framework create retrofit service demand.
- Local content mandates:Ghana's Petroleum Commission licensing requirements generate procurement preference for indigenous service providers.
Industry Challenges
- Subsea engineering scarcity:Deepwater completion and intervention expertise concentrates among limited contractor pools.
- Legacy asset integration:Aging shallow-water platforms require digital monitoring overlay without production interruption.
- Certification timeline compression:EU methane verification standards demand accelerated third-party audit completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Oil and Gas Upstream Market |
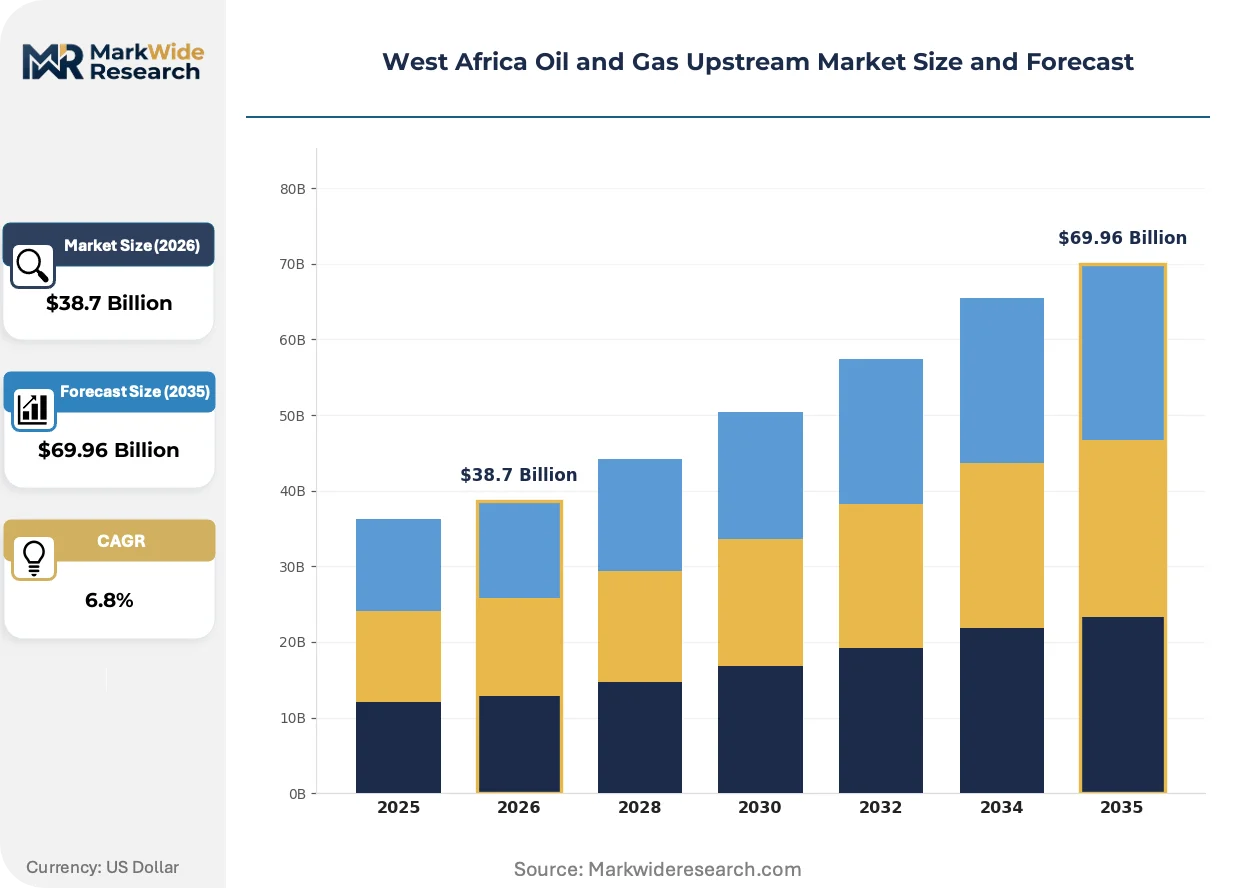
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Drilling, Service Technology: Seismic Imaging, Reservoir Simulation, Enhanced Oil Recovery, Hydraulic Fracturing Service Type: Well Services, Offshore Support, Engineering, Consulting End User: Oil Companies, Government Agencies, Contractors, Service Providers |
| Companies Covered | TotalEnergies SE, Shell plc, ExxonMobil Corporation, Eni S.p.A., Chevron Corporation, Nigerian National Petroleum Company Limited, Kosmos Energy Ltd, Tullow Oil plc, Seplat Energy Plc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Oil and Gas Upstream Market Evolving Landscape
Digital reservoir characterization and automated drilling systems are compressing exploration timelines while regulatory compliance technology is absorbing capital that previously flowed to pure production expansion.
4D seismic monitoring combined with real-time wellbore telemetry is absorbing engineering resources across Nigerian deepwater assets. Operators deploy these systems to reduce dry-hole risk and optimize completion designs. The technology is absorbing margin pressure from extended appraisal phases by accelerating decision cycles.
Nigeria's Department of Petroleum Resources enforces offshore discharge standards that mandate continuous emissions monitoring on floating production facilities. Operators must retrofit legacy platforms with integrated sensor networks. Deepwater production units face the steepest compliance burden as they fall under both national and European buyer market regulations.
Refinery procurement teams in Ghana and Côte d'Ivoire are consolidating crude purchasing through term contracts rather than spot market exposure. This behavior compresses trading margins for intermediaries while rewarding integrated producers with offtake certainty. The shift is most visible in Ghana's Tema refining corridor where operators prioritize supply security over price optimization.
West Africa Oil and Gas Upstream Market Segmentation
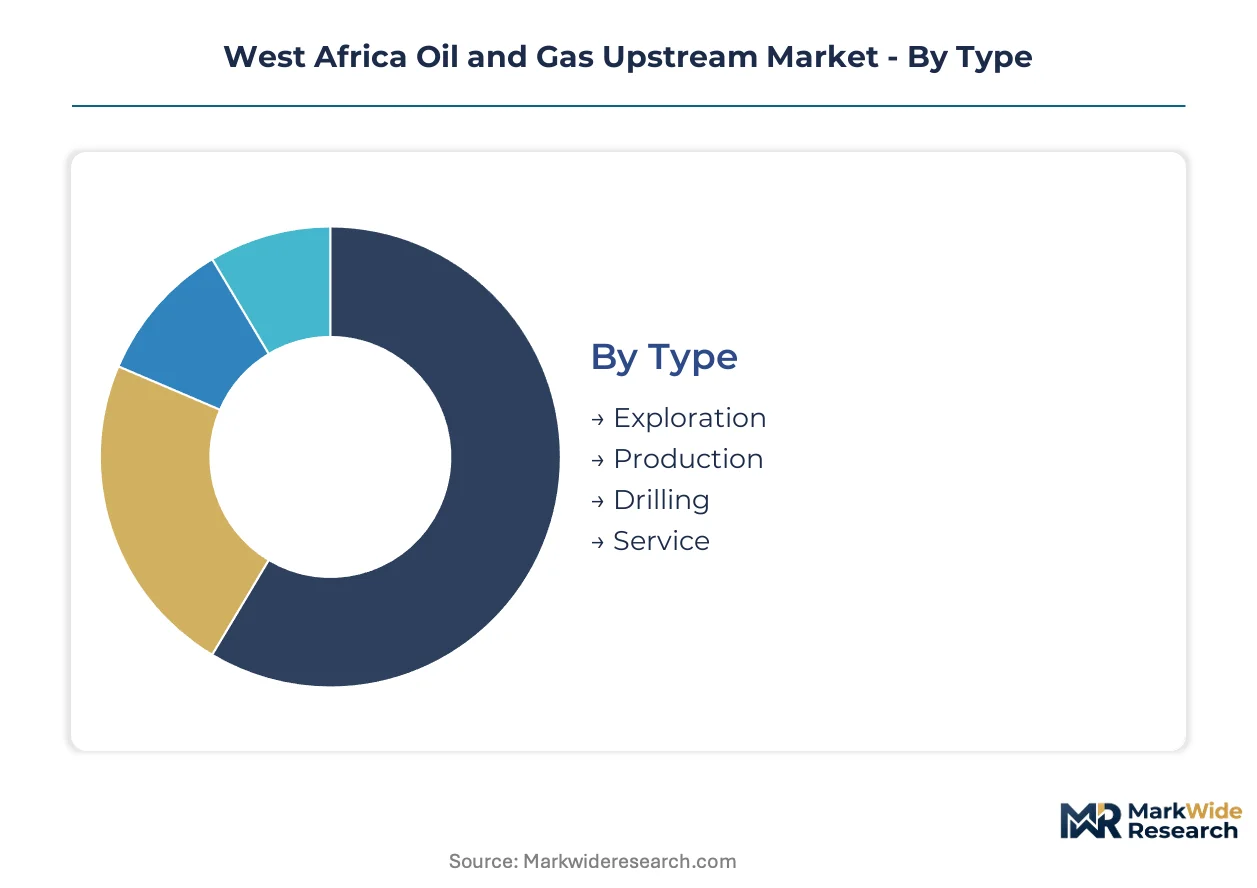
Upstream segmentation in West Africa reflects the capital intensity gradient from frontier exploration through mature field rehabilitation. Operators allocate budgets differently across seismic acquisition, drilling campaigns, and production maintenance depending on water depth and reservoir maturity.
Type:
Capital deployment cycles distinguish buyers—exploration-focused independents run leaner cost structures than integrated majors with full-cycle commitments.
- Exploration:Seismic survey and wildcat drilling activities targeting unproven reservoirs across Senegal-Mauritania's Atlantic Margin. Ghana's Petroleum Commission awards exploration licenses with extended appraisal timelines to attract frontier investment.
- Production:Extraction and surface processing of hydrocarbons from proven fields, generating recurring revenue streams that fund development drilling. Nigerian deepwater assets anchor regional output volumes through floating production facilities.
- Drilling:Well construction and completion operations spanning jack-up rigs in shallow Ghanaian waters to drillships in ultra-deep Nigerian blocks.
- Service:Equipment rental, logistics, and technical support functions outsourced by operators seeking variable cost structures.
Volume sits with Production; growth tilts toward Exploration.
Technology:
Technical sophistication requirements split the market—majors deploy proprietary seismic processing while independents license third-party reservoir models.
- Seismic Imaging:2D and 3D acoustic survey methods mapping subsurface geology, with 4D time-lapse variants monitoring fluid movement in producing Nigerian fields. Licensing rounds in Mauritania require modern seismic datasets as bid prerequisites.
- Enhanced Oil Recovery:Artificial lift, gas injection, and chemical flooding techniques extending productive life of mature onshore Nigerian assets. Declining reservoir pressure in older fields drives retrofit demand.
- Reservoir Simulation:Computational modeling of fluid flow and recovery factors to optimize well placement and production rates.
- Hydraulic Fracturing:Pressure-induced rock fracturing to enhance permeability in tight formations, limited currently to specific Nigerian onshore plays.
Revenue concentrates in Seismic Imaging; Enhanced Oil Recovery climbs the fastest as brownfield investment accelerates.
Service Type:
Contract duration preferences differentiate procurement—NOCs favor long-term well service agreements while independents seek spot offshore support.
- Well Services:Intervention, workover, and maintenance operations on producing wellbores, commanding premium pricing due to specialized equipment requirements. Nigerian Department of Petroleum Resources mandates continuous well integrity monitoring.
- Offshore Support:Platform supply, crew transfer, and emergency response vessels servicing floating production units off Ghana and Côte d'Ivoire. Port infrastructure constraints at Lagos and Takoradi create supply bottlenecks.
- Engineering:Front-end design and project management for subsea infrastructure and topside modifications.
- Consulting:Regulatory compliance, reservoir engineering, and commercial advisory for licensing round preparation.
Margins peak in Well Services; expansion tilts toward Offshore Support as deepwater development intensifies.
End User:
Risk tolerance and capital access separate participants—international oil companies carry full-cycle exposure while contractors operate on fee-based arrangements.
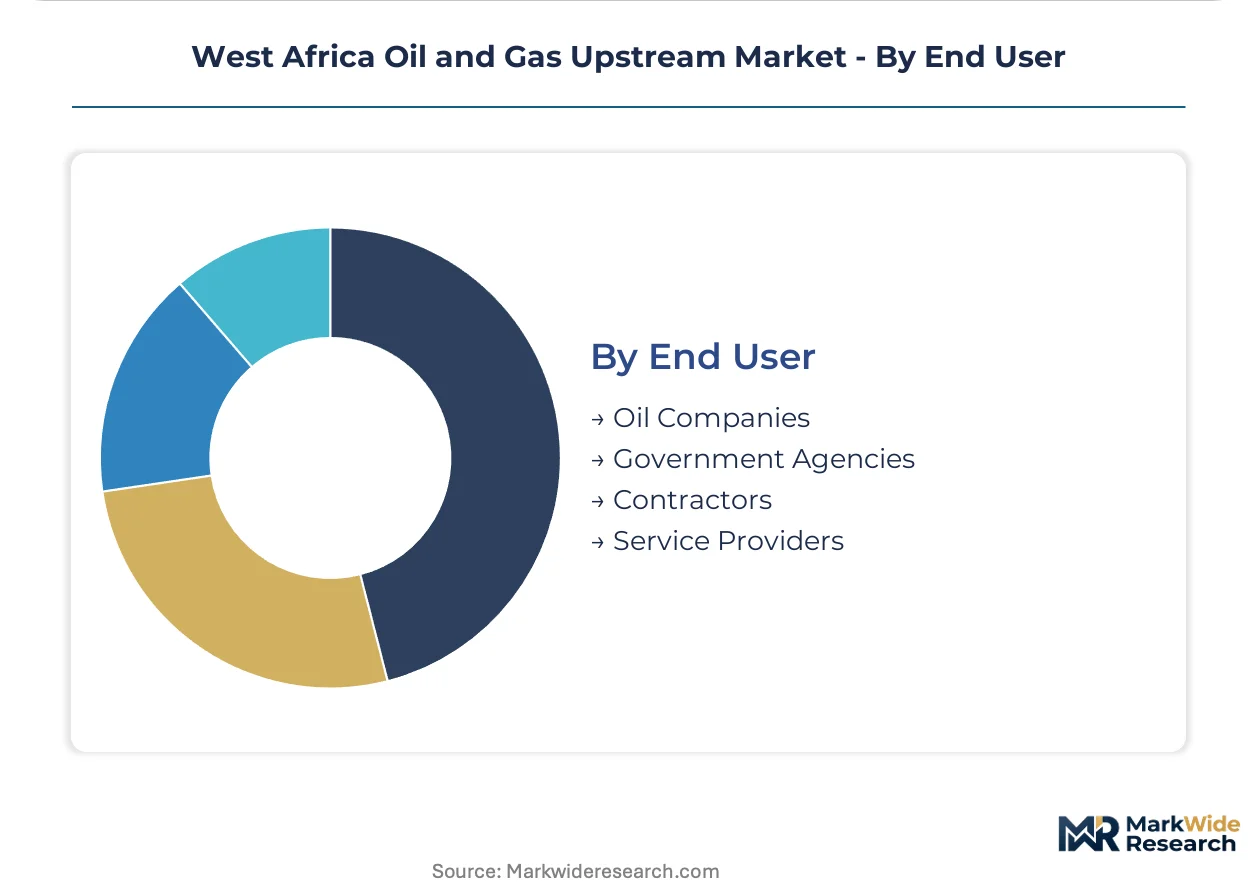
- Oil Companies:Integrated majors and independents holding equity stakes in production sharing contracts across Nigerian deepwater and Ghanaian offshore blocks. TotalEnergies and Shell anchor investment commitments through operated assets.
- Government Agencies:National oil companies and petroleum regulators managing state equity participation and licensing administration. Nigeria's Nigerian National Petroleum Company Limited and Ghana's Petroleum Commission set local content thresholds.
- Contractors:Drilling and construction firms executing lump-sum or day-rate contracts for exploration and development programs.
- Service Providers:Equipment suppliers and technical specialists supporting field operations through rental and service agreements.
Spend concentrates with Oil Companies; procurement reform is expanding Government Agencies' direct contracting authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors West African upstream activity through its concentration of well service contractors, drilling rig operators, and petroleum engineering consultancies serving Nigerian deepwater blocks.
Nigeria
Deepwater production sharing contracts and mature field rehabilitation programs drive capital deployment across the Niger Delta and offshore Bonga fields. The Petroleum Industry Act imposes revised fiscal terms and local content thresholds on operators. Port Harcourt hosts the densest cluster of well intervention specialists and subsea engineering firms serving floating production facilities.
Ghana
Offshore oil production from the Jubilee and TEN fields sustains offtake commitments to the Tema refining corridor. The Petroleum Commission enforces licensing frameworks with extended appraisal timelines and environmental bonding requirements. Takoradi's port infrastructure supports platform supply vessels and crew transfer operations for floating production units.
Senegal
Frontier basin exploration along the Atlantic Margin attracts capital allocation through revised fiscal terms and extended exploration periods. The national petroleum regulator oversees offshore block licensing with emphasis on gas discovery commercialization. Dakar serves as the coordination hub for seismic survey contractors and frontier exploration teams targeting deepwater prospects.
Mauritania
Ultra-deepwater gas discoveries offshore drive first-mover positioning for integrated LNG export infrastructure development. The country's petroleum administration manages production sharing contracts with emphasis on domestic gas utilization obligations. Nouakchott hosts project management offices for subsea infrastructure planning and floating liquefaction facility engineering.
Côte d'Ivoire
Refinery expansion and regional crude offtake commitments tighten supply-demand alignment with Ghanaian production sources. The national hydrocarbons regulator administers licensing rounds with fiscal stability provisions for deepwater investors. Abidjan's commercial district concentrates trading desks and term contract negotiators for West African crude procurement.
West Africa Oil and Gas Upstream Market Competitive Landscape
The competitive structure tilts toward integrated majors with full-cycle capabilities and frontier specialists with basin-specific expertise. Market concentration remains moderate, with state-owned entities holding equity stakes alongside international operators. Two strategic archetypes dominate: integrated majors leveraging project execution scale, and independent explorers targeting first-mover positions in frontier acreage. Competitive moves center on portfolio diversification into gas-weighted assets and strategic partnerships for subsea engineering capacity.
Among the integrated majors, TotalEnergies SE and Shell plc exemplify archetypes with operated deepwater assets and regional portfolio anchoring. Kosmos Energy Ltd occupies a position within the frontier specialist tier, focusing on Atlantic Margin exploration. These entities represent contrasting strategic postures—full-cycle integration versus targeted basin entry—within a market where state equity participation through Nigerian National Petroleum Company Limited shapes partnership structures and local content compliance.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Shell plc |
| ExxonMobil Corporation |
| Eni S.p.A. |
| Chevron Corporation |
| Nigerian National Petroleum Company Limited |
| Kosmos Energy Ltd |
| Tullow Oil plc |
| Seplat Energy Plc |
| Others |
Value Network & Pricing Analysis
Captive integration of well services and subsea engineering capacity around Lagos and Port Harcourt anchors pricing power for Nigerian deepwater operators while exposing marginal players to cost pass-through vulnerability. This concentration pattern rewards integrated majors with procurement leverage and squeezes independents facing rig contract escalation.
Pricing Analysis
Throughput-linked pricing for floating production facility contracts ties operator payments to uptime guarantees and barrel delivery volumes rather than fixed day rates. Nigerian deepwater projects command premium pricing tiers reflecting subsea complexity, while Ghanaian shallow-water developments trade at standard rates due to jack-up rig availability. Cost compression in standard-tier drilling services intensifies as regional rig supply expands faster than demand absorption. National oil companies exhibit lowest price sensitivity due to state-backed financing, whereas frontier independents in Senegal-Mauritania face acute margin pressure.
Supply Chain Analysis
Ghana's Petroleum Commission local content mandates and Nigeria's Petroleum Industry Act domestic procurement thresholds are reshaping sourcing patterns for engineering and platform supply services. Equipment fabrication draws from South Korea, Singapore, and the United Arab Emirates, while specialized well intervention crews concentrate in Nigeria and Angola. Logistics chokepoints at Takoradi and Lagos ports create vessel scheduling vulnerabilities during seasonal demand surges. Distribution runs through integrated majors' captive procurement networks and national oil company tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
West Africa's upstream sector is navigating a technology-transition phase as 4D seismic monitoring and automated drilling systems displace conventional reservoir characterization and manual wellbore operations.
For Market Incumbents: Deepen subsea engineering capabilities through captive hiring or exclusive contractor alliances to defend against frontier specialists poaching technical talent. Prioritize certification investment for EU methane intensity compliance to secure LNG offtake renewal cycles against emerging low-carbon competitors.
For New Entrants and Emerging Players: Capture carbon capture retrofit opportunities under Ghana's Environmental Protection Agency decommissioning framework where incumbent asset operators seek outsourced compliance solutions. Target Mauritania's ultra-deepwater gas commercialization segment through integrated LNG infrastructure partnerships rather than standalone exploration positions.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated majors seeking frontier basin inventory replenishment, with acquisition premiums attaching to Atlantic Margin exploration portfolios. Watch for inflection signals in European buyer market carbon border adjustment implementation timelines, which will revalue gas-weighted assets against oil-heavy portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Deployment | Artificial lift and chemical injection extend mature Nigerian field economics under Petroleum Industry Act fiscal terms. |
| Local Content Compliance Investment | Indigenous service provider partnerships satisfy Ghana Petroleum Commission licensing requirements for offshore operators. |
| Methane Measurement Infrastructure | Continuous emissions monitoring systems secure EU import certification for Nigerian LNG export cargoes. |
| Frontier Basin Seismic Acquisition | Modern 3D datasets satisfy Mauritania licensing round bid prerequisites for Atlantic Margin blocks. |
| Integrated LNG Export Development | Floating liquefaction facilities monetize ultra-deepwater gas discoveries offshore Senegal and Mauritania. |
Research Methodology
Multi-period observation of licensing round outcomes, rig day-rate movements, and production sharing contract fiscal terms anchored the trend analysis, supplemented by interviews with Nigerian deepwater project managers, Ghanaian Petroleum Commission licensing officers, subsea engineering contractors, and European LNG procurement directors. Secondary validation drew from Nigerian Department of Petroleum Resources discharge filings, Ghana Environmental Protection Agency bonding records, IEA West Africa energy outlooks, and customs data on drilling equipment imports. Bottom-up field-level production estimates and top-down regional demand projections were triangulated against operator capex disclosures.
Segment-weighting applied differential growth assumptions across exploration, production, drilling, and service categories, with technology splits between seismic imaging and enhanced oil recovery calibrated to brownfield investment patterns. Water depth classifications and local content compliance tiers provided additional stratification dimensions. CAGRs were derived from production volume trajectories, project sanctioning timelines, and regulatory implementation schedules across the analysis window. Forecast inputs incorporated rig availability curves, refinery offtake contract durations, and EU methane regulation enforcement phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to frontier exploration success rates, European carbon border adjustment scope expansion, and Nigerian fiscal stability clause renegotiations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market