
 India Nuclear Power Plant Equipment Market | 2026-2036
India Nuclear Power Plant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Nuclear Power Plant Equipment Market Foresight
The capability gap between foreign-origin reactor technology suppliers and domestic fabrication specialists is unwinding as India's localization mandates deepen. Larsen & Toubro Ltd anchors heavy forging and reactor component fabrication through its Hazira complex, sustaining long-term contracts for nuclear-grade pressure vessels. Bharat Heavy Electricals Limited dominates turbine-generator packages and auxiliary systems, while Rosatom State Atomic Energy Corporation competes on reactor technology transfer for the Kudankulam expansion.
India nuclear power plant equipment encompasses reactor pressure vessels, steam generators, turbines, and control rods engineered to ASME Section III and Indian nuclear standards for fission heat conversion. These systems operate at primary loop pressures near 15.5 MPa with nickel-alloy cladding to withstand neutron embrittlement and thermal cycling over 40-year design lives. Reactor pressure vessels command the largest capital allocation given forging complexity and limited qualified suppliers globally. Fast Breeder Reactor technology is gaining structural priority as India advances its thorium-utilization roadmap, while government utilities remain the dominant procurement channel under Department of Atomic Energy oversight.
The Atomic Energy Regulatory Board enforces facility licensing and operational safety codes that shape equipment qualification timelines and supplier certification requirements. BIS nuclear standards and the PLI scheme for specialty steel and heavy engineering are tightening domestic content thresholds for new reactor projects. Stakeholders must monitor regulatory clarity on small modular reactor frameworks and indigenization benchmarks for the ten-reactor expansion program.
Market Dynamics
India's three-stage nuclear program is compressing equipment procurement timelines as thorium-utilization mandates force reactor technology transitions and domestic fabrication capacity expansions.
Growth Catalysts
- Indigenization Mandates:The PLI scheme for specialty steel and heavy engineering is channeling capital toward domestic forging complexes capable of nuclear-grade pressure vessel production.
- Fast Breeder Reactor Prioritization:Sodium-cooled Fast Breeder Reactor technology is accelerating procurement of specialized heat exchangers and control rod mechanisms for thorium fuel cycle readiness.
- State Utility Expansion:NPCIL's ten-reactor program across Gujarat, Tamil Nadu, and Rajasthan is sustaining long-term order visibility for reactor pressure vessels and steam generators.
Market Restraints
- Forging Capacity Bottlenecks:Limited qualified heavy forging suppliers globally restricts reactor pressure vessel fabrication throughput and extends delivery timelines.
- Specialty Alloy Dependence:Nickel-based cladding materials and SA-508 Grade 3 steel remain import-dependent, exposing projects to raw material cost volatility and supply disruption.
- Regulatory Qualification Burden:AERB certification timelines for new fabrication facilities add 18-24 months to supplier onboarding, constraining capacity scaling.
Strategic Opportunities
- Small Modular Reactor Frameworks:Emerging AERB regulatory clarity on SMR deployment standards opens design and fabrication contracts for modular reactor pressure vessels and integrated steam generators.
- Rajasthan-Gujarat Industrial Corridor:Concentrated reactor construction in western India is pulling precision machining and non-destructive testing services into regional supplier clusters.
- Technology Convergence:Digital twin integration with ASME Section III compliance documentation is reducing inspection cycle times and enabling predictive maintenance contracts.
Industry Challenges
- Welding Specialist Scarcity:Qualified nuclear-grade welders and ASME-certified inspection engineers remain critically undersupplied relative to projected reactor construction cadence.
- Legacy System Integration:New digital instrumentation and control systems face compatibility friction with existing PHWR analog protection systems at operating stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Nuclear Power Plant Equipment Market |
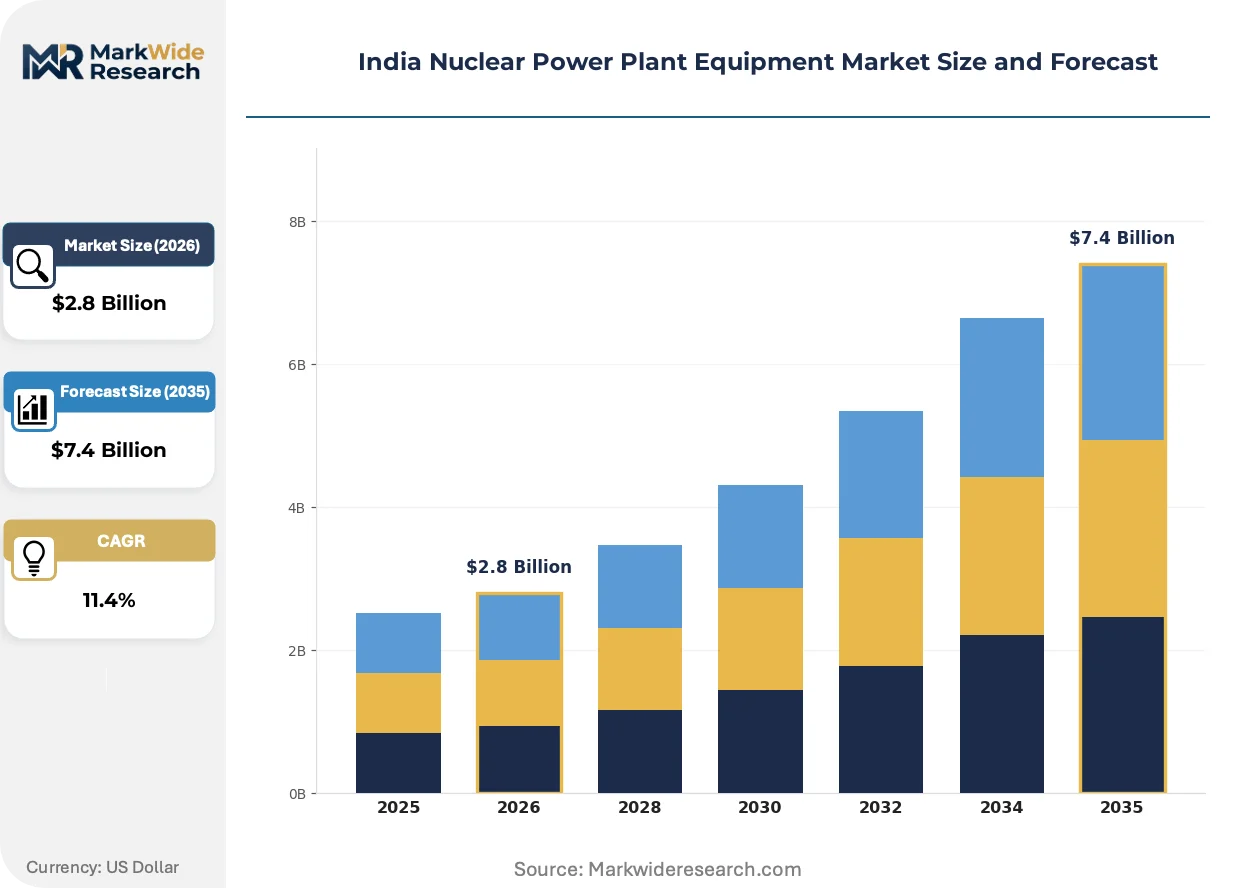
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactor Pressure Vessel, Steam Generator, Turbine, Control Rods Technology: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Advanced Heavy Water Reactor End User: Government Utilities, Private Utilities, EPC Contractors, Maintenance Service Providers Application: Power Generation, Research, Waste Management, Safety Systems |
| Companies Covered | Rosatom State Atomic Energy Corporation, Westinghouse Electric Company LLC, Larsen & Toubro Ltd, Dongfang Electric Corp. Limited, Doosan Corporation, Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries Ltd, Walchandnagar Industries, Hindustan Construction Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Nuclear Power Plant Equipment Market Shifts & Advancements
Equipment qualification protocols are tightening as digital instrumentation converges with legacy analog safety systems, while fabrication automation responds to skilled labor scarcity.
Advanced manufacturing techniques are decomposing traditional forging constraints for reactor pressure vessels. NPCIL and equipment fabricators are adopting electron beam welding and near-net-shape forging to reduce material waste and machining time. This shift is compressing lead times for critical nuclear-grade components while maintaining ASME Section III compliance integrity.
BIS nuclear standards harmonization with ASME codes is reshaping supplier certification pathways. The Atomic Energy Regulatory Board's revised safety codes now mandate enhanced seismic qualification and flood protection for coastal reactor sites. Equipment vendors serving Kudankulam and proposed Gujarat locations are re-engineering containment systems and emergency diesel generator enclosures to meet these elevated benchmarks.
Consolidated procurement frameworks are displacing project-by-project equipment contracting. NPCIL is moving toward multi-reactor fleet agreements with anchor fabricators for standardized PHWR components, reducing transaction costs and enabling volume-based pricing. This concentration is most visible in Tamil Nadu, where long-term steam generator supply contracts now span four reactor units rather than single-project awards.
India Nuclear Power Plant Equipment Market Segmentation
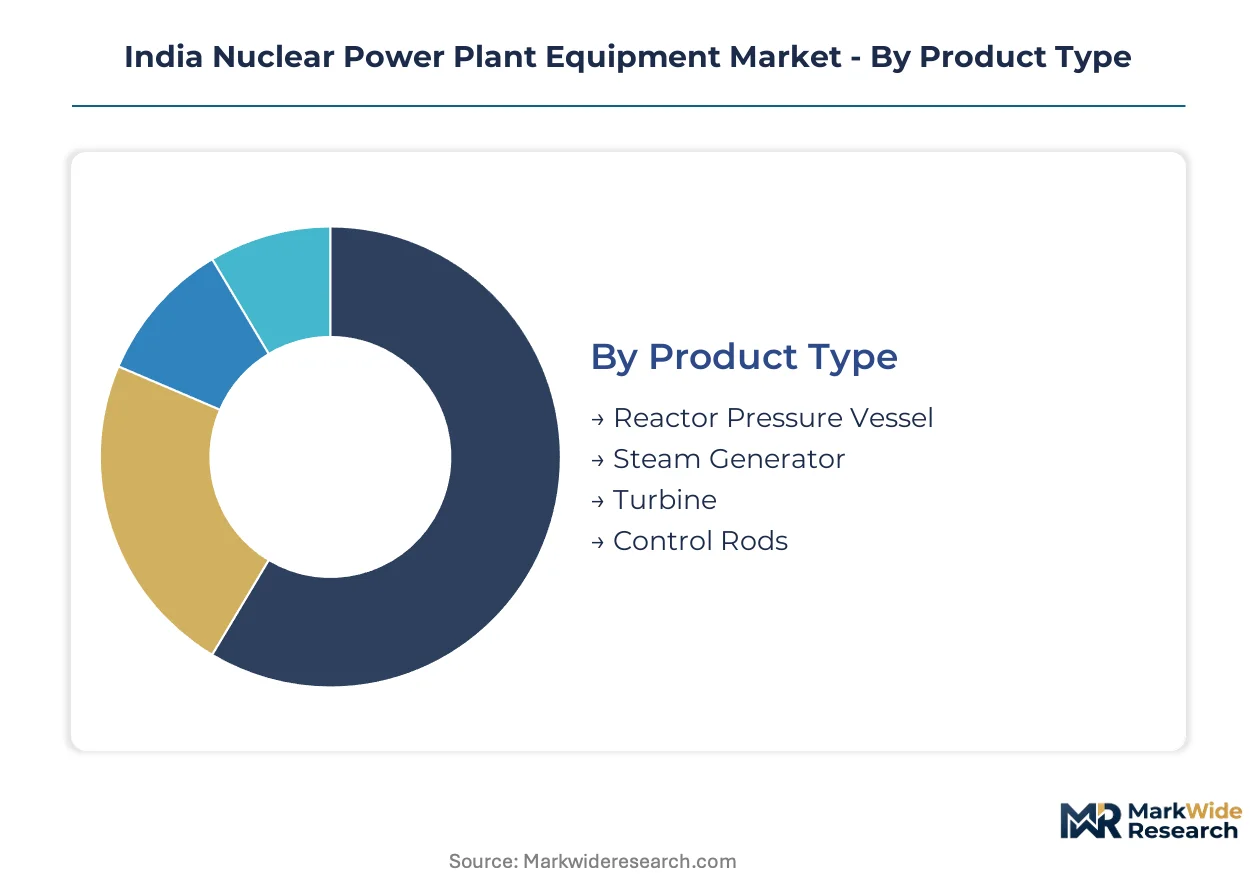
Equipment segmentation in India's nuclear power market reveals stark procurement concentration. Government utilities dominate capital allocation, while reactor technology choices determine forgings demand and indigenization feasibility across the three-stage program.
Product Type:
Domestic fabrication capacity concentrates on heavy forgings, while precision components and specialized alloys retain import dependence.
- Reactor Pressure Vessel:Forged SA-508 Grade 3 steel shells with nickel-alloy cladding withstand 15.5 MPa primary loop pressure and neutron embrittlement across 40-year design lives. NPCIL's ten-reactor program is absorbing nearly all qualified domestic forging capacity at Hazira and other licensed facilities, stretching delivery timelines.
- Steam Generator:U-tube heat exchanger bundles transfer thermal energy from primary to secondary loops, requiring Inconel tubing and precision tube-to-tubesheet welding. Demand clusters at Tamil Nadu and Gujarat coastal sites where corrosion-resistant specifications are tightening under revised AERB safety codes.
- Turbine:Low-pressure and high-pressure turbine stages convert steam thermal energy to mechanical rotation, with Bharat Heavy Electricals Limited dominating domestic generator-turbine packaging for PHWR units.
- Control Rods:Neutron-absorbing assemblies regulate fission rates through cadmium or boron carbide inserts, with specialized drive mechanisms sourced from qualified nuclear instrumentation suppliers.
Reactor pressure vessels command the established base. The steepest expansion runs through steam generators as fleet standardization multiplies unit demand.
Technology:
Technology segmentation tracks India's three-stage roadmap, with each reactor type imposing distinct equipment specifications and localization timelines.
- Pressurized Water Reactor:Light-water moderated systems operating at high pressure require specialized forgings and steam generators with alloy-600 tubing. Kudankulam units represent the sole operating PWR fleet, with Rosatom technology transfer agreements governing component sourcing.
- Pressurized Heavy Water Reactor:Heavy-water moderated indigenous design forms the backbone of NPCIL's fleet, with standardized equipment specifications enabling multi-reactor procurement contracts and domestic fabrication scale.
- Boiling Water Reactor:Light-water designs with direct steam cycle to turbines have seen limited Indian deployment, with equipment requirements overlapping PWR specifications but distinct pressure vessel geometries.
- Fast Breeder Reactor:Sodium-cooled systems operating at higher temperatures demand specialized heat exchangers, electromagnetic pumps, and control rod mechanisms for thorium fuel cycle readiness. Kalpakkam prototype is accelerating procurement of these specialized components.
- Advanced Heavy Water Reactor:Thorium-fueled design under development incorporates passive safety features and reduced moderator requirements, with equipment specifications still stabilizing as indigenization targets are set.
Pressurized heavy water reactors anchor installed capacity. Fast breeder technology is climbing the fastest as thorium-utilization mandates compress development timelines.
End User:
Procurement authority concentrates in state entities, with private participation and service contractors occupying peripheral equipment niches.
- Government Utilities:NPCIL and BHAVINI control reactor construction and major equipment procurement under Department of Atomic Energy oversight, with consolidated fleet purchasing replacing project-by-project contracting.
- Private Utilities:Limited private sector participation in nuclear generation restricts equipment demand to non-nuclear island components and balance-of-plant systems where regulatory barriers are lower.
- EPC Contractors:Engineering-procurement-construction firms package civil works with specialized nuclear equipment, coordinating between fabricators and NPCIL project sites at Kudankulam, Gorakhpur, and Chutka.
- Maintenance Service Providers:Specialized outage contractors handle steam generator tube replacement, pressure vessel inspection, and control rod refurbishment at operating stations.
Government utilities dominate capital expenditure. EPC contractors are gaining procurement coordination scope as project complexity rises.
Application:
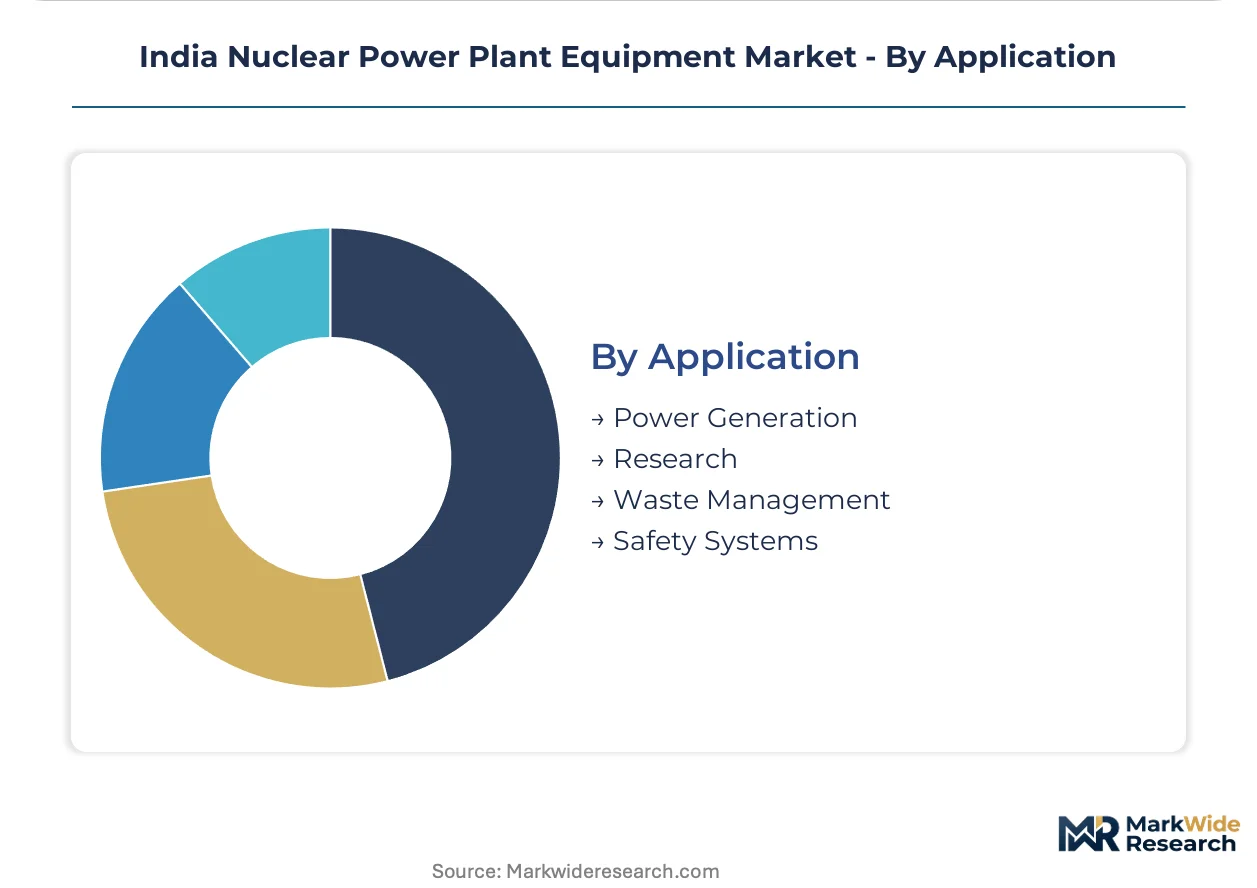
Application segmentation distinguishes revenue-generating power systems from research and safety infrastructure with distinct equipment qualification pathways.
- Power Generation:Reactor island and turbine island equipment for electricity production absorbs the dominant capital share, with 700 MWe PHWR units driving standardized component demand.
- Research:Research reactors at BARC facilities require specialized neutron beam instruments, irradiation rigs, and experimental fuel handling systems with lower production volumes but higher specification variance.
- Waste Management:Spent fuel storage pools, vitrification systems, and dry cask storage equipment address backend fuel cycle requirements with growing procurement as reactor fleets expand.
- Safety Systems:Emergency diesel generators, containment spray systems, and passive autocatalytic recombiners operate under AERB safety code mandates with seismic qualification requirements tightening at coastal sites.
Power generation equipment represents the established base. Waste management systems are expanding most quickly as backend infrastructure lags reactor construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply across Indian states based on reactor technology deployment and coastal versus inland siting requirements. Western and southern regions concentrate forging capacity and active construction, while eastern and northern states host research infrastructure and emerging project pipelines.
Gujarat
Kakrapar and Mithi Virdi host India's most active PHWR construction sites, driving demand for reactor pressure vessels and steam generators. The state's coastal location triggers AERB-mandated seismic and flood protection upgrades for containment systems. Hazira's heavy engineering cluster anchors Larsen & Toubro's nuclear forging complex, supplying pressure vessel forgings for the ten-reactor expansion program.
Tamil Nadu
Kudankulam's VVER-1000 units represent India's only operating PWR fleet, creating specialized procurement channels through Rosatom technology transfer agreements. The Kalpakkam Fast Breeder Reactor prototype accelerates demand for sodium-cooled heat exchangers and electromagnetic pumps. Regional suppliers cluster around Chennai for precision machining and non-destructive testing services supporting both indigenous and foreign-origin reactor projects.
Rajasthan
RAPS units constitute the oldest operating PHWR fleet, generating sustained replacement demand for steam generator tubes and control rod mechanisms. Rawatbhata's proximity to the Rajasthan-Gujarat industrial corridor enables integrated logistics for heavy component transport. The state hosts the Advanced Heavy Water Reactor development site, pulling experimental fuel handling and thorium cycle equipment procurement.
Maharashtra
Tarapur houses India's first commercial reactors and BARC's research facilities, creating dual demand for power generation and experimental equipment. The state's nuclear research infrastructure drives procurement of specialized neutron beam instruments and irradiation rigs. Mumbai-Pune industrial belt suppliers focus on instrumentation and control systems rather than heavy forgings.
Karnataka
Kaiga's four-unit PHWR station sustains maintenance and outage service demand for steam generator tube replacement and pressure vessel inspection. The state's inland location avoids coastal corrosion specifications but requires enhanced seismic qualification under revised AERB codes. Regional EPC contractors coordinate between southern fabrication clusters and project sites.
India Nuclear Power Plant Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with state-owned heavy engineering groups and global reactor technology vendors forming distinct competitive clusters. The market structure reflects dual procurement channels: consolidated fleet purchasing by NPCIL for standardized PHWR components, and technology-specific sourcing for foreign-origin reactor projects. Two strategic archetypes dominate—domestic fabrication specialists with AERB-certified heavy forging capacity, and international reactor vendors with technology transfer obligations. Capacity expansion and strategic partnerships constitute the primary competitive moves, as fabricators scale qualified forging throughput and foreign vendors localize component sourcing.
Among domestic heavy engineering groups, Larsen & Toubro Ltd and Bharat Heavy Electricals Limited anchor the integrated fabrication tier, representing the archetype of state-linked capital goods producers with nuclear-grade certification. Rosatom State Atomic Energy Corporation occupies a distinct position as the foreign technology vendor with established Indian operational presence through Kudankulam. These three entities exemplify the competitive structure: domestic fabricators capturing standardized component demand, foreign vendors serving technology-specific projects, and limited overlap between the two procurement channels.
| Leading Market Players |
|---|
| Rosatom State Atomic Energy Corporation |
| Westinghouse Electric Company LLC |
| Larsen & Toubro Ltd |
| Dongfang Electric Corp. Limited |
| Doosan Corporation |
| Bharat Heavy Electricals Limited |
| Mitsubishi Heavy Industries Ltd |
| Walchandnagar Industries |
| Hindustan Construction Company |
| Others |
Supply & Pricing Matrix
Long-term fleet agreements between NPCIL and anchor fabricators lock in reactor pressure vessel supply while stabilizing unit pricing across multi-reactor procurement cycles. This contract structure shields domestic suppliers from raw material volatility but exposes projects to cost escalation when nickel-alloy cladding and SA-508 Grade 3 steel face import disruption.
Pricing Analysis
After-sales service contracts for steam generator tube replacement and pressure vessel inspection now generate lifetime value exceeding initial equipment sales. Pricing stratifies across ASME Section III certification tiers, with AERB-qualified fabricators commanding premiums over general heavy engineering competitors. Cost compression in standard PHWR components is intensifying because NPCIL's consolidated procurement multiplies unit volumes and squeezes supplier margins. Private EPC contractors exhibit highest price sensitivity due to thin project margins, while government utilities prioritize delivery certainty over unit cost negotiation.
Supply Chain Analysis
Strategic stockpiling of nickel-based alloys and specialized forgings dominates inventory strategy given 18-24 month AERB qualification timelines for new suppliers. Manufacturing concentration rests on India, Russia, and South Korea for qualified pressure vessel forgings, with domestic Hazira capacity absorbing expanding NPCIL demand. SA-508 Grade 3 steel, Inconel tubing, and electromagnetic pump components anchor raw material dependencies. Single-source vulnerability around qualified heavy forging suppliers constrains throughput scaling. Distribution runs through Department of Atomic Energy-controlled procurement channels with limited private sector intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's nuclear equipment market constitutes a high-growth disruption as Fast Breeder Reactor commercialization and thorium fuel cycle readiness force technology transitions and fabrication capacity expansion.
For Market Incumbents: Secure AERB certification for expanded forging capacity at Hazira and secondary sites before competitor qualification timelines compress. Anchor position through backward integration into nickel-alloy cladding production, reducing exposure to import cost volatility. Defend against emerging precision machining specialists by locking multi-reactor steam generator contracts with volume-based pricing floors. For New Entrants and Emerging Players: Differentiate on digital twin integration for ASME Section III compliance documentation, targeting predictive maintenance contracts at aging Rajasthan and Tarapur stations. White-space opportunity concentrates in non-destructive testing services and precision tube-to-tubesheet welding for Tamil Nadu coastal corrosion specifications. Go-to-market through EPC contractor partnerships rather than direct NPCIL engagement bypasses lengthy qualification barriers. For Investors and Strategic Acquirers: Capital is best deployed toward heavy engineering specialists with existing AERB forging licenses and underutilized capacity. Five-to-ten year viability hinges on positioning within the ten-reactor expansion program supply base. Watch for AERB regulatory clarity on small modular reactor frameworks as the inflection signal triggering modular fabrication equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy Forging Capacity Expansion | AERB-certified pressure vessel output at Hazira complex secures NPCIL fleet procurement lock-in. |
| Technology Licensing Agreement | Rosatom transfer protocols for Kudankulam VVER-1000 units govern specialized component sourcing rules. |
| Backward Integration into Specialty Alloys | In-house nickel-alloy cladding production reduces SA-508 Grade 3 steel import dependence exposure. |
| Digital Twin Platform Integration | ASME Section III compliance automation compresses inspection cycle times at operating PHWR stations. |
| Regional Supplier Cluster Development | Rajasthan-Gujarat industrial corridor concentration pulls precision machining capacity toward western construction sites. |
Research Methodology
Desk research of AERB safety code filings, NPCIL project announcements, and BIS nuclear standards documentation preceded structured interviews with reactor project directors, heavy forging plant managers, EPC procurement leads, and nuclear welding inspection engineers. Secondary validation drew from Department of Atomic Energy annual reports, PLI scheme disbursement records, and customs data on specialty alloy imports. Bottom-up equipment demand modeling triangulated against top-down nuclear capacity expansion targets.
Variance decomposition across reactor technology segments, state-level project pipelines, and equipment qualification timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, reactor technology classification, end-user procurement authority, and regional construction cluster. CAGRs derived from unit-level capital cost benchmarks applied to NPCIL's disclosed reactor commissioning schedule, with Fast Breeder Reactor equipment specifications and SMR regulatory pathway uncertainty as industry-specific forecast inputs.
Material uncertainties — AERB certification timeline revisions, nickel-alloy import disruption, and Fast Breeder Reactor prototype performance — sit outside the modeled envelope. Forecasts reflect assumptions on indigenization mandate continuity and thorium fuel cycle development pace. Revision becomes warranted when small modular reactor regulatory clarity crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Romania Power EPC Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Germany Power EPC Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Portable Power Station Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Vietnam Power EPC Market