
 Asia-Pacific SCR Power Controller Market | 2026-2036
Asia-Pacific SCR Power Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific SCR Power Controller Market Insights
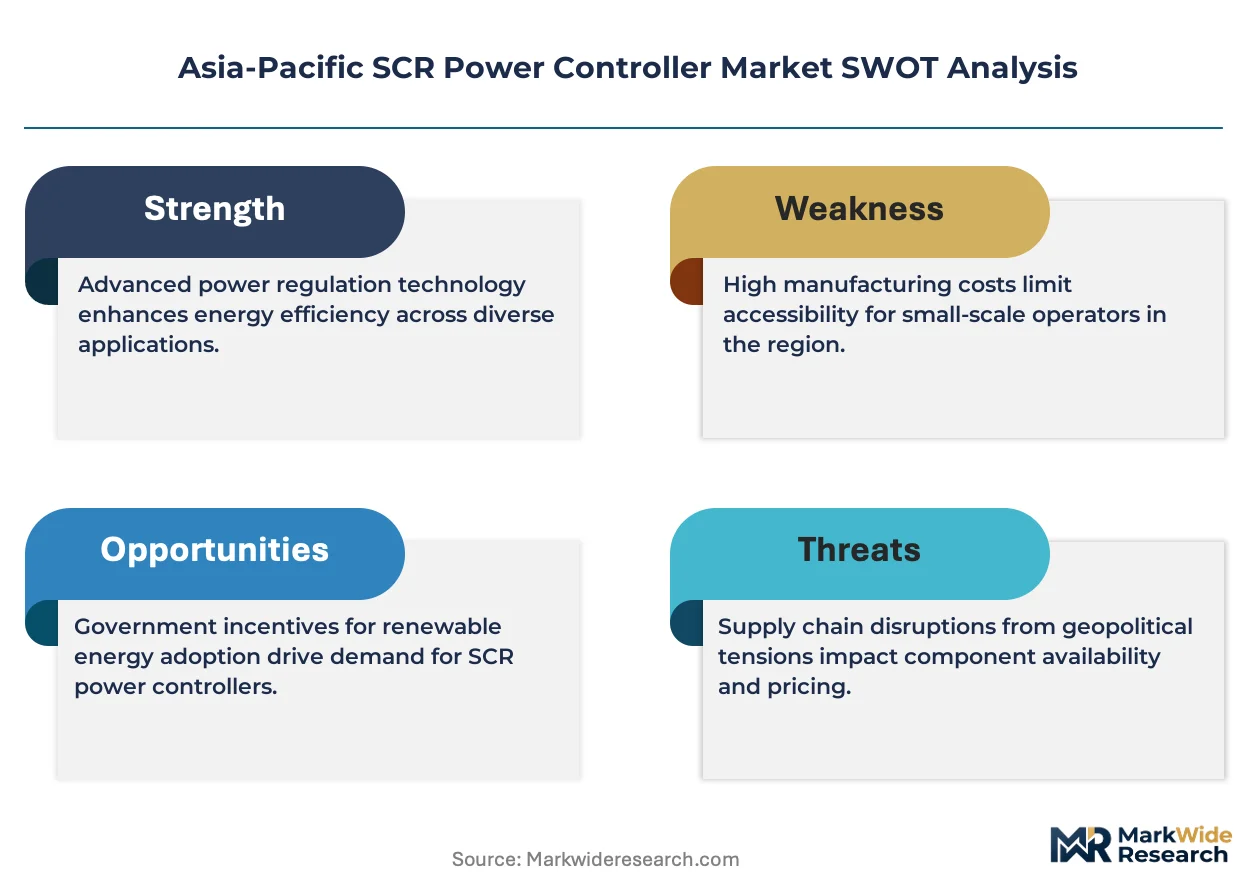
A widening capability gap in silicon-controlled rectifier manufacturing is bifurcating the competitive landscape. ABB leverages integrated drive-train portfolios to anchor premium industrial contracts across East Asia. Siemens competes through digital twin compatibility in its controller architectures. Chromalox specializes in thermal-process applications, sustaining niche dominance in semiconductor fabrication heating.
An SCR power controller is a solid-state device that regulates electrical power to resistive or inductive loads by phase-angle or burst-fire firing of thyristors, typically handling voltages from 120V to 690V and currents exceeding 1000A in heavy industrial configurations. Its primary purpose is precise temperature and power management in electric heating, melting, and drying operations. Three-phase variants command the largest installed base across steel and glass manufacturing, while microprocessor-based control technology captures expanding margin pools through predictive maintenance integration. Modular designs are gaining traction in retrofit installations where footprint constraints limit panel-mounted retrofits.
China's MIIT enforces GB standards on power conversion efficiency that directly shape product certification requirements for controllers sold domestically. Japan's METI administers JIS standards governing electromagnetic compatibility and thermal safety in industrial electrical equipment. Australia's electrical safety regulators mandate AS/NZS compliance for imported controllers, creating segmented compliance obligations across the region. Stakeholders must weigh localization of firmware development against centralized manufacturing when calibrating regional service capabilities.
Market Dynamics
China's MIIT efficiency mandates are compressing replacement cycles for analog SCR controllers across heavy manufacturing clusters, forcing rapid firmware upgrades and digital retrofit investments.
Growth Catalysts
- MIIT GB Standards:China's mandatory power conversion efficiency thresholds are accelerating scrappage of legacy analog units in steel and cement plants.
- Semiconductor fabrication expansion:Thermal process equipment builders in South Korea and Taiwan are specifying microprocessor-based controllers with predictive maintenance integration.
- Japan's precision electronics sector:Smart controller adoption is accelerating as METI JIS compliance requirements tighten electromagnetic compatibility specifications.
Market Restraints
- Silicon carbide supply concentration:Thyristor-grade silicon sourcing clusters in specific East Asian foundry networks create input cost volatility.
- Technical limitation in high-frequency switching:Phase-angle firing above 400Hz generates harmonic distortion that exceeds grid connection standards in Australian industrial zones.
- Substitution threat from IGBT modules:Insulated-gate bipolar transistor alternatives are capturing traction in variable-speed drive applications below 500kW.
Strategic Opportunities
- Underpenetrated Vietnam and Indonesia:Glass and ceramics manufacturing growth in these markets lacks established controller service networks.
- Regulatory tailwind from India's PLI scheme:Production-linked incentives for specialty steel are mandating energy-efficient heating retrofits.
- Technology convergence of edge computing and SCR control:Localized predictive algorithms are enabling real-time thermal optimization without cloud dependency.
Industry Challenges
- Embedded systems firmware talent scarcity:Controller manufacturers face recruitment gaps for thyristor gate-drive algorithm specialists.
- AS/NZS certification timeline compression:Australian electrical safety regulators are extending compliance review periods for imported three-phase units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific SCR Power Controller Market |
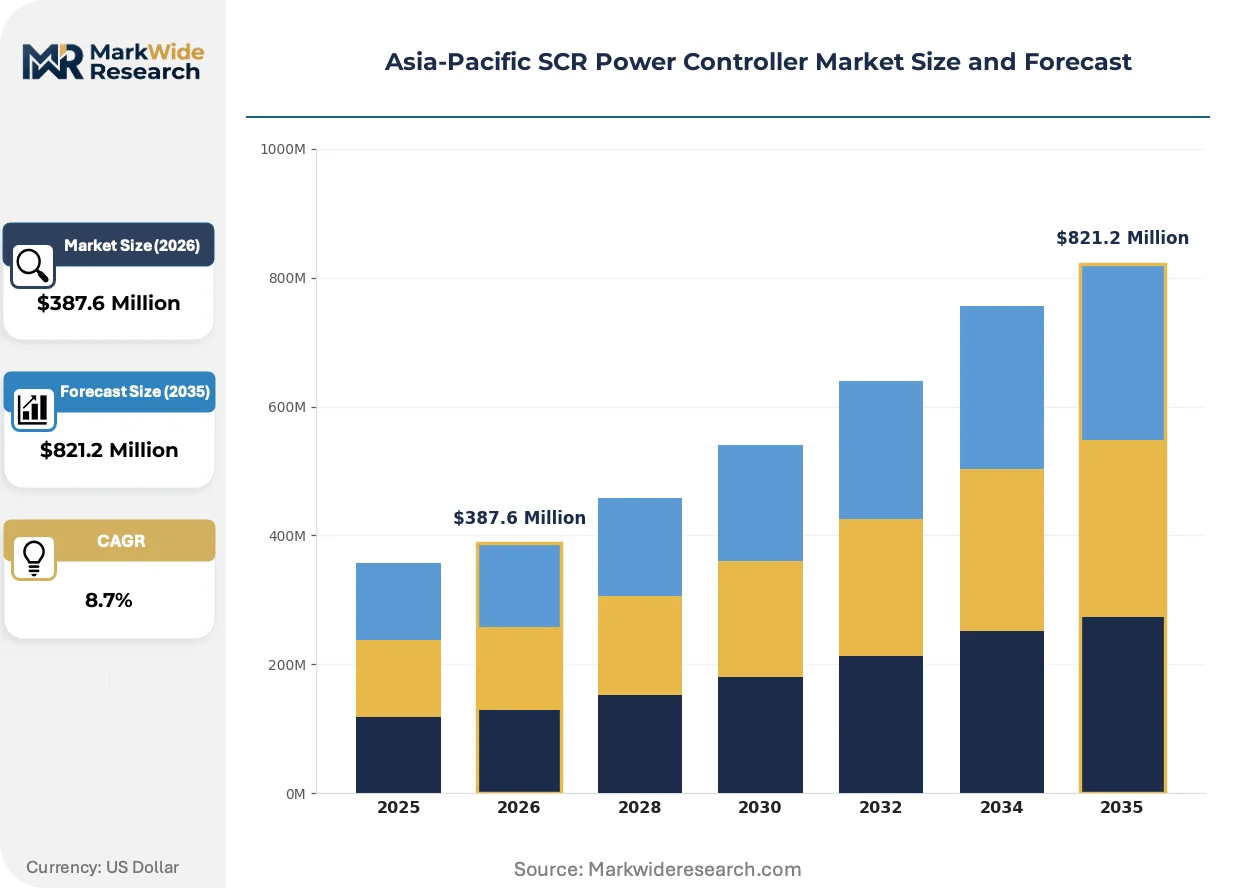
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Modular, Panel-Mounted End User: Industrial, Commercial, Residential, Healthcare Installation: Onshore, Offshore, Indoor, Outdoor Control Technology: Analog, Digital, Microprocessor-Based, Smart Controllers |
| Companies Covered | ABB, Honeywell International, Schneider Electric, Siemens, Omron, Advanced Energy Industries, Gefran, Chromalox, JUMO, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific SCR Power Controller Market Trends and Innovations
Digital twin compatibility is becoming a non-negotiable specification in controller procurement, while edge-native architectures are displacing centralized SCADA dependencies.
Microprocessor-based phase control with integrated power quality monitoring is displacing standalone analog firing circuits in heavy industrial configurations. Steel mill operators across China and India are specifying these units for new furnace installations. This displacement is compressing margins for legacy component suppliers while expanding software service revenue pools.
METI's updated JIS standards for electromagnetic compatibility in industrial electrical equipment are forcing redesigns of controller housing and shielding architectures. Japanese precision electronics manufacturers are absorbing compliance costs through premium pricing. Semiconductor fabrication heating equipment is the most affected segment, with vendors accelerating firmware certification cycles.
After-sales service unbundling is separating hardware procurement from commissioning and calibration contracts. Industrial furnace operators in South Korea are purchasing controllers directly while sourcing integration through specialized system integrators. This pattern is most visible in flat-glass manufacturing clusters where thermal process complexity demands localized expertise.
Asia-Pacific SCR Power Controller Market Segmentation
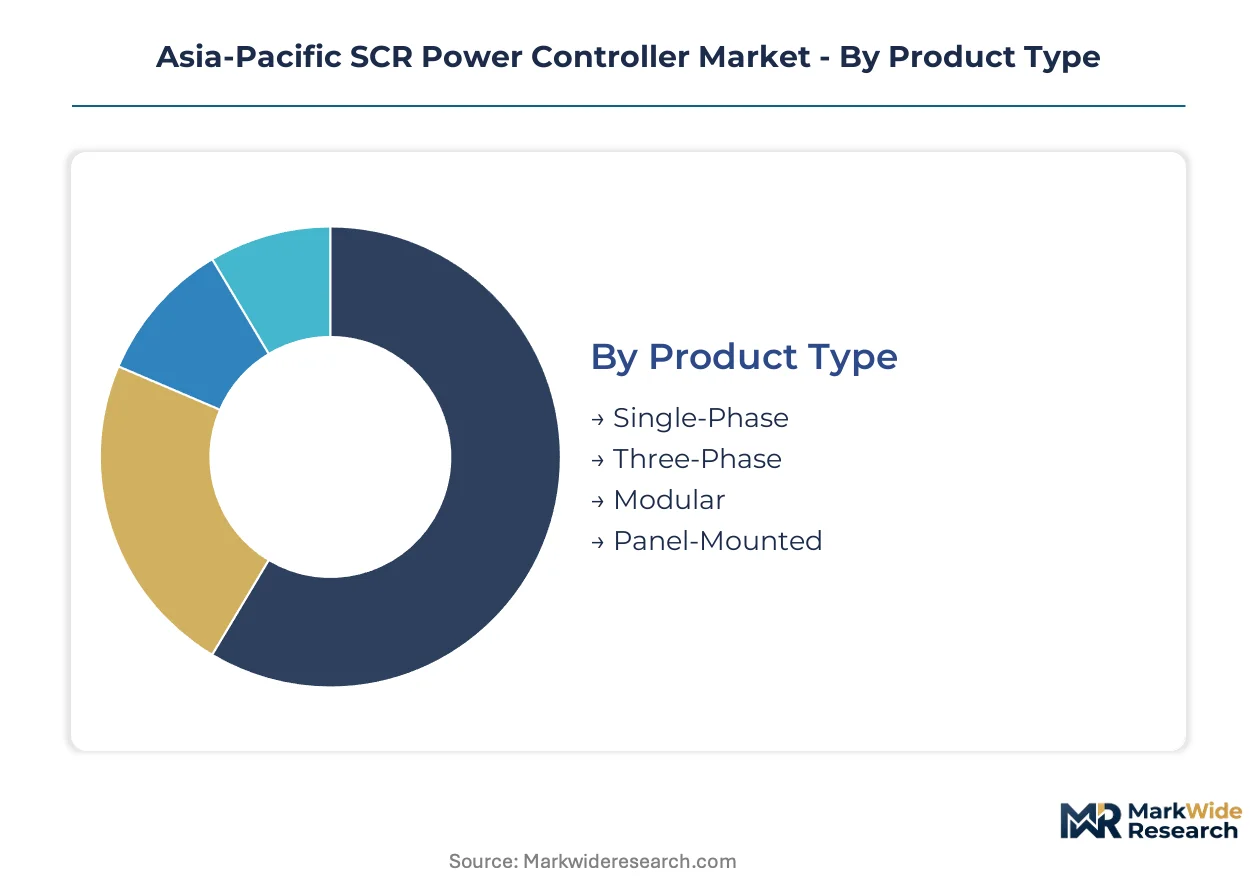
Segmentation in the Asia-Pacific SCR power controller market reveals divergent margin structures across product architectures and control technologies. Procurement patterns in heavy manufacturing clusters favor three-phase configurations, while precision electronics sectors in Japan and South Korea drive premium pricing for microprocessor-based units.
Product Type:
Margin pools concentrate in three-phase and modular configurations where thermal process complexity justifies premium engineering support.
- Three-Phase:Heavy industrial configurations handling voltages up to 690V and currents exceeding 1000A dominate steel and glass manufacturing across China's industrial clusters. MIIT efficiency mandates are accelerating replacement of legacy analog units in cement and steel plants, compressing procurement cycles for furnace operators.
- Modular:Retrofit-optimized designs with reduced footprint address panel space constraints in aging industrial facilities across India and Vietnam. Factory automation targets in these markets are expanding demand for scalable power control without full system replacement.
- Single-Phase:Lower-power applications in commercial heating and small-scale drying equipment across Southeast Asian manufacturing zones.
- Panel-Mounted:Traditional enclosure-based installations in established industrial infrastructure requiring standardized form factors.
Three-phase holds installed capacity. Modular is rotating up the share rankings.
End User:
Application intensity varies sharply, with industrial thermal processes consuming the highest controller density per facility.
- Industrial:Electric furnaces, melting equipment, and drying systems in steel, cement, and ceramics manufacturing represent the core demand base. China's steel sector expansion under MIIT GB standards and India's PLI scheme for specialty steel are mandating energy-efficient heating retrofits across heavy manufacturing clusters.
- Commercial:HVAC systems and commercial kitchen equipment in urban development corridors across Indonesia and the Philippines.
- Residential:Limited penetration in home heating and water heating applications where simpler thermostat controls dominate.
- Healthcare:Sterilization equipment and medical device manufacturing requiring precise thermal control in Japan's precision electronics clusters.
Industrial captures volume concentration. Healthcare is climbing the fastest as METI JIS compliance tightens.
Installation:
Environmental exposure requirements create tiered specification standards across deployment contexts.
- Indoor:Climate-controlled industrial environments where electromagnetic shielding and thermal management follow standardized protocols.
- Outdoor:Hardened enclosures for remote industrial sites and infrastructure applications across Australia's mining and energy sectors.
- Onshore:Standard grid-connected installations in established manufacturing zones with stable electrical infrastructure.
- Offshore:Specialized marine-rated controllers for platform and vessel applications requiring salt-corrosion resistance.
Indoor dominates current deployments. Outdoor is gaining share fastest in resource extraction corridors.
Control Technology:
Technology maturity curves are separating legacy analog suppliers from digital-native competitors capturing service revenue.
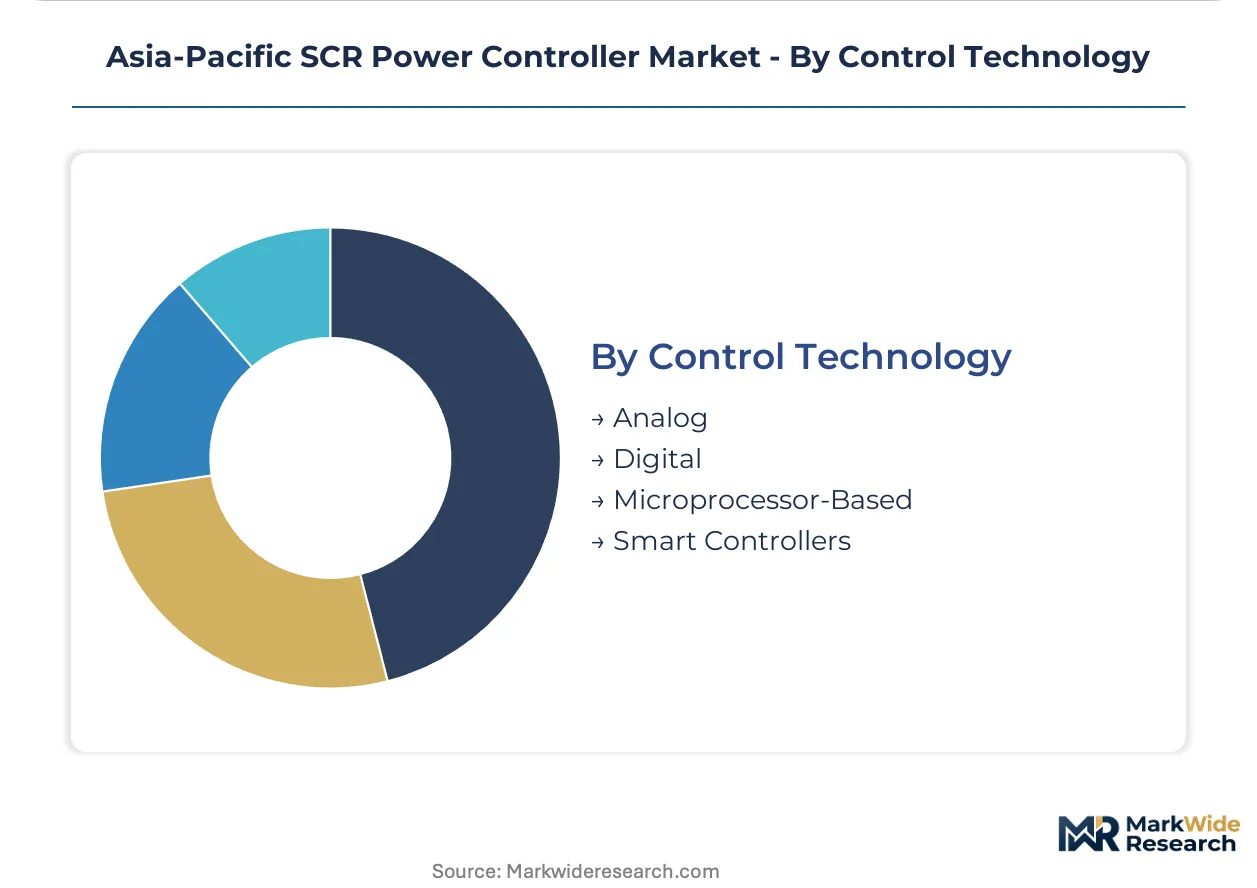
- Microprocessor-Based:Integrated phase control with power quality monitoring and predictive maintenance capability is displacing standalone analog firing circuits. Semiconductor fabrication equipment builders in South Korea and Taiwan are specifying these units for thermal process applications requiring firmware certification cycles.
- Smart Controllers:Edge-native architectures with localized predictive algorithms enable real-time thermal optimization without cloud dependency. Japan's precision electronics sector is absorbing premium pricing as METI updates JIS electromagnetic compatibility standards.
- Digital:Intermediate tier with programmable setpoints and basic diagnostics serving cost-sensitive industrial retrofits.
- Analog:Legacy phase-angle and burst-fire firing circuits facing accelerated scrappage under China's MIIT efficiency mandates.
Microprocessor-based commands the premium tier. Smart controllers are expanding most quickly in precision manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia-Pacific SCR power controller landscape. Procurement in Vietnam and Indonesia prioritizes cost-optimized analog units, while Japanese precision electronics manufacturers absorb premium pricing for smart controllers with predictive maintenance integration.
China
Steel and cement furnace operators dominate controller procurement volumes. MIIT enforces GB standards on power conversion efficiency that compress replacement cycles for legacy analog units. Industrial clusters in Hebei and Jiangsu provinces are retrofitting aging heating infrastructure with three-phase digital controllers to meet dual carbon targets.
Japan
Semiconductor fabrication equipment builders drive demand for microprocessor-based thermal control systems. METI administers updated JIS standards for electromagnetic compatibility that force housing redesigns. Precision electronics manufacturers in the Chubu region around Nagoya are absorbing compliance costs through premium controller specifications.
India
Specialty steel production under the PLI scheme is mandating energy-efficient heating retrofits across heavy manufacturing. The CEA regulates grid connection standards for industrial electrical equipment. Manufacturing corridors in Gujarat and Maharashtra are expanding procurement of modular controllers to address panel space constraints in aging facilities.
South Korea
Flat-glass and display panel manufacturing clusters specify controllers with integrated power quality monitoring. MFDS oversees medical device manufacturing standards that indirectly shape thermal equipment specifications. Thermal process equipment builders in Gyeonggi-do are unbundling after-sales service from hardware procurement.
Australia
Mining and remote resource extraction operations require hardened outdoor enclosures for power control systems. Electrical safety regulators mandate AS/NZS compliance that extends certification timelines for imported three-phase units. Controller deployments in Western Australia's Pilbara region face harmonic distortion constraints above 400Hz phase-angle firing.
Asia-Pacific SCR Power Controller Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific SCR power controller market. The vendor base separates into three tiers: integrated industrial conglomerates with drive-train portfolios, specialized thermal-process specialists, and regional fabricators serving cost-sensitive retrofit markets. Two dominant competitive moves are reshaping positioning: digital twin compatibility investments and after-sales service unbundling that separates hardware procurement from commissioning contracts.
Within the integrated industrial tier, ABB and Siemens occupy positions anchored by comprehensive automation portfolios. Chromalox exemplifies the specialization archetype, representing thermal-process engineering depth in semiconductor fabrication heating applications. Among Japanese precision electronics suppliers, Omron sits within the smart controller segment where METI JIS compliance requirements tighten electromagnetic compatibility specifications.
| Leading Market Players |
|---|
| ABB |
| Honeywell International |
| Schneider Electric |
| Siemens |
| Omron |
| Advanced Energy Industries |
| Gefran |
| Chromalox |
| JUMO |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at thyristor-grade silicon foundries in Taiwan and South Korea anchors cost floors across the Asia-Pacific SCR power controller market. Scale concentration in East Asian semiconductor manufacturing creates asymmetric pricing power for digital controller suppliers while compressing margins for analog retrofit specialists serving cost-sensitive markets in Vietnam and Indonesia.
Pricing Analysis
After-sales service contracts and firmware calibration subscriptions now drive lifetime value capture across the controller installed base. Pricing stratifies across premium, standard, and economy tiers based on METI JIS certification grade and predictive maintenance integration depth. Cost compression in the economy tier intensifies because Vietnamese glass manufacturers prioritize hardware-only procurement. Industrial furnace operators in China's Hebei province exhibit the highest price sensitivity, while Japanese precision electronics manufacturers absorb premium pricing for electromagnetic compatibility-certified units.
Supply Chain Analysis
Inventory buffers for thyristor-grade silicon carbide substrates currently stretch 16-20 weeks at major controller OEMs. Supply concentrates in Taiwan, South Korea, and Japan for semiconductor-grade thyristor fabrication. Raw material dependencies center on high-purity silicon carbide wafers, copper busbar assemblies, and conformal coating resins. Single-source vulnerability in East Asian foundry networks for thyristor-grade silicon creates procurement risk exposure. Distribution runs through authorized system integrators in heavy manufacturing clusters and direct OEM relationships in precision electronics sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific SCR power controller market sits in early-cycle expansion as MIIT efficiency mandates and India's PLI scheme for specialty steel accelerate replacement demand across heavy manufacturing infrastructure.
For Market Incumbents: Consolidate firmware development capabilities through backward integration into gate-drive algorithm talent pools. Deepen service network density in Vietnam and Indonesia before regional fabricators establish retrofit dominance. IGBT substitution threat in sub-500kW applications demands accelerated microprocessor-based controller rollouts to defend premium positioning.
For New Entrants and Emerging Players: Anchor in modular controller configurations for India's aging panel infrastructure where space constraints block full system replacement. Target glass and ceramics manufacturing growth corridors in Vietnam and Indonesia lacking established service networks. Pursue commissioning-only contracts that unbundle from hardware procurement, mirroring South Korean flat-glass manufacturing patterns.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized thermal-process engineering firms with semiconductor fabrication heating expertise over diversified industrial conglomerates. Long-term viability hinges on predictive maintenance software revenue streams and edge-native architecture deployment. Watch for inflection when METI JIS electromagnetic compatibility certification becomes mandatory rather than premium-tier optional.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Compatibility Investment | Siemens and ABB are anchoring premium contracts through controller architecture integration with plant-wide simulation platforms. |
| After-Sales Service Unbundling | South Korean flat-glass manufacturers are separating hardware procurement from commissioning contracts, creating specialized integrator opportunities. |
| Edge-Native Firmware Development | Localized predictive algorithms without cloud dependency address data sovereignty requirements in China's industrial clusters. |
| Modular Retrofit Configuration Launch | Reduced-footprint designs capture India's factory automation targets without requiring full panel replacement in aging facilities. |
| Thyristor-Grade Silicon Backward Integration | Controller OEMs are exploring captive supply arrangements to mitigate foundry concentration risk in Taiwan and South Korea. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined structured interviews with furnace operators across China's steel corridors and thermal process equipment builders in South Korea's Gyeonggi-do region. Secondary validation drew from MIIT GB standard filings, METI JIS certification databases, CEA grid connection regulations, and customs trade records for thyristor-grade silicon imports. Bottom-up unit economics triangulated against top-down manufacturing capacity estimates across the analysis window.
Sensitivity analysis tested forecast robustness across MIIT enforcement intensity scenarios and silicon carbide price volatility bands. Segmentation dimensions modeled include product architecture, control technology tier, end-use application intensity, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, new furnace capital expenditure trajectories, and retrofit penetration curves. Industry-specific inputs incorporated PLI scheme disbursement schedules and semiconductor fabrication capacity expansion timelines.
Material uncertainties — MIIT mandate acceleration delays, thyristor-grade silicon supply disruptions, IGBT substitution pace in variable-speed drives — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and foundry capacity expansion plans. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Power System Simulator Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Air Preheater Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Germany Power EPC Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Power Infrastructure Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Global Exhaust Heat Recovery System Market