
 PV Water Heater Market | 2026-2036
PV Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
PV Water Heater Market Insights
Remote monitoring and predictive maintenance subscriptions is rebalancing how OEMs monetize solar thermal assets. Himin Solar Energy Group leverages its domestic manufacturing scale to anchor supply for utility-scale installations across East Asia. Rheem Manufacturing Company sustains brand recognition through channel control in North American retail and contractor networks. Ariston Thermo SpA differentiates via product specialization in compact integrated systems for European residential retrofits.
PV water heaters convert solar irradiance into thermal energy through absorber plates or vacuum-insulated tubes, storing heated fluid in insulated tanks for domestic or process hot water delivery; evacuated tube collectors achieve higher efficiency in cold climates due to reduced convective heat loss. Flat plate collectors occupy the mature volume tier where manufacturing scale drives cost compression, while evacuated tube collectors represent the fastest-growing product category in high-latitude and high-altitude markets. The residential end user segment dominates unit shipments, though commercial installations command superior margin pools due to engineering complexity and longer service contracts.
China's MIIT enforces GB standards that mandate minimum thermal conversion efficiency thresholds, effectively filtering low-cost entrants from domestic procurement channels. India's BIS certification requirements for solar thermal products create compliance barriers that favor established manufacturers with testing infrastructure. The EU F-Gas Regulation and CE marking directives shape material selection and heat transfer fluid specifications for European market access. Stakeholders must monitor evolving efficiency benchmarks and carbon accounting rules that will determine which product architectures retain eligibility for public incentive programs.
Market Dynamics
China's MIIT enforcement of updated GB standards for thermal conversion efficiency is filtering low-cost entrants from domestic procurement channels while accelerating product architecture upgrades across East Asian manufacturing bases.
Growth Catalysts
- Dual carbon policy framework:China's dual carbon goals mandate building-integrated renewable thermal systems, creating compliance-driven demand across new residential construction in tier-one cities.
- Commercial hospitality expansion:India's Maharashtra and Karnataka states are witnessing concentrated deployment across hotel chains seeking operational cost reduction through solar thermal integration.
- Evacuated tube efficiency gains:Vacuum-insulated collector technology achieves superior performance in high-latitude cold climates, opening addressable markets previously served by conventional flat-plate systems.
Market Restraints
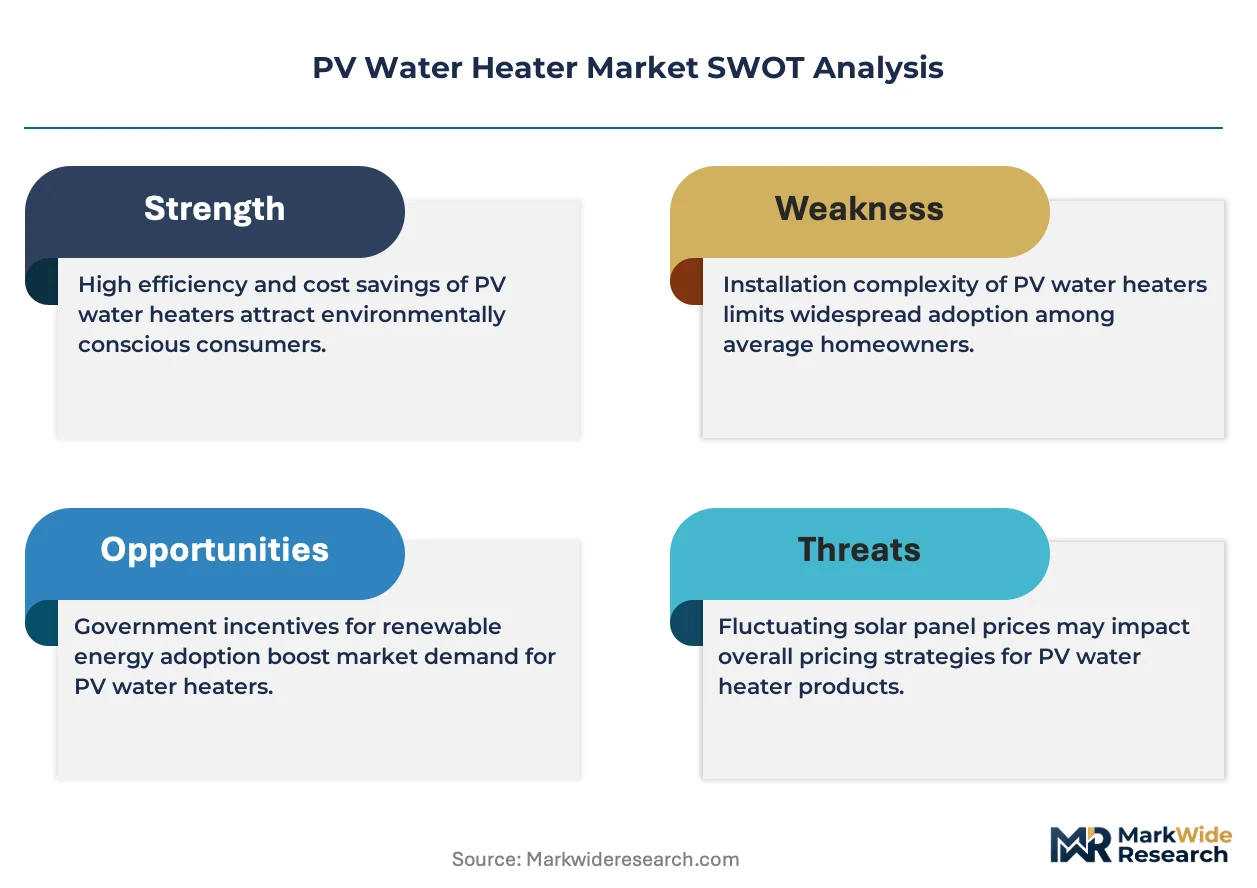
- Copper and aluminum input volatility:Absorber plate manufacturing depends on base metal prices subject to commodity exchange fluctuations, compressing margin predictability for OEMs.
- Heat transfer fluid restrictions:EU F-Gas Regulation limits working fluid chemistries, forcing reformulation costs and supply chain requalification for European market access.
- Grid-tied PV substitution:Rooftop photovoltaic electricity generation paired with electric resistance heating competes for capital allocation in residential new-build specifications.
Strategic Opportunities
- Australian residential retrofit wave:Roof-mounted evacuated tube systems are penetrating existing housing stock as state-level rebate programs reduce payback periods for homeowners.
- Predictive maintenance subscriptions:Remote monitoring platforms enable OEMs to capture recurring revenue streams from commercial asset operators seeking uptime guarantees.
- Heat pump convergence:Hybrid systems combining solar thermal pre-heating with vapor-compression heat pumps address cold-climate performance limitations of standalone collectors.
Industry Challenges
- BIS certification timeline compression:India's testing infrastructure bottlenecks create 12-18 month approval delays for new product variants entering the commercial hospitality segment.
- System integration complexity:Legacy hydronic heating infrastructure in European residential retrofits requires specialized engineering for compatibility with compact integrated solar thermal units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV Water Heater Market |
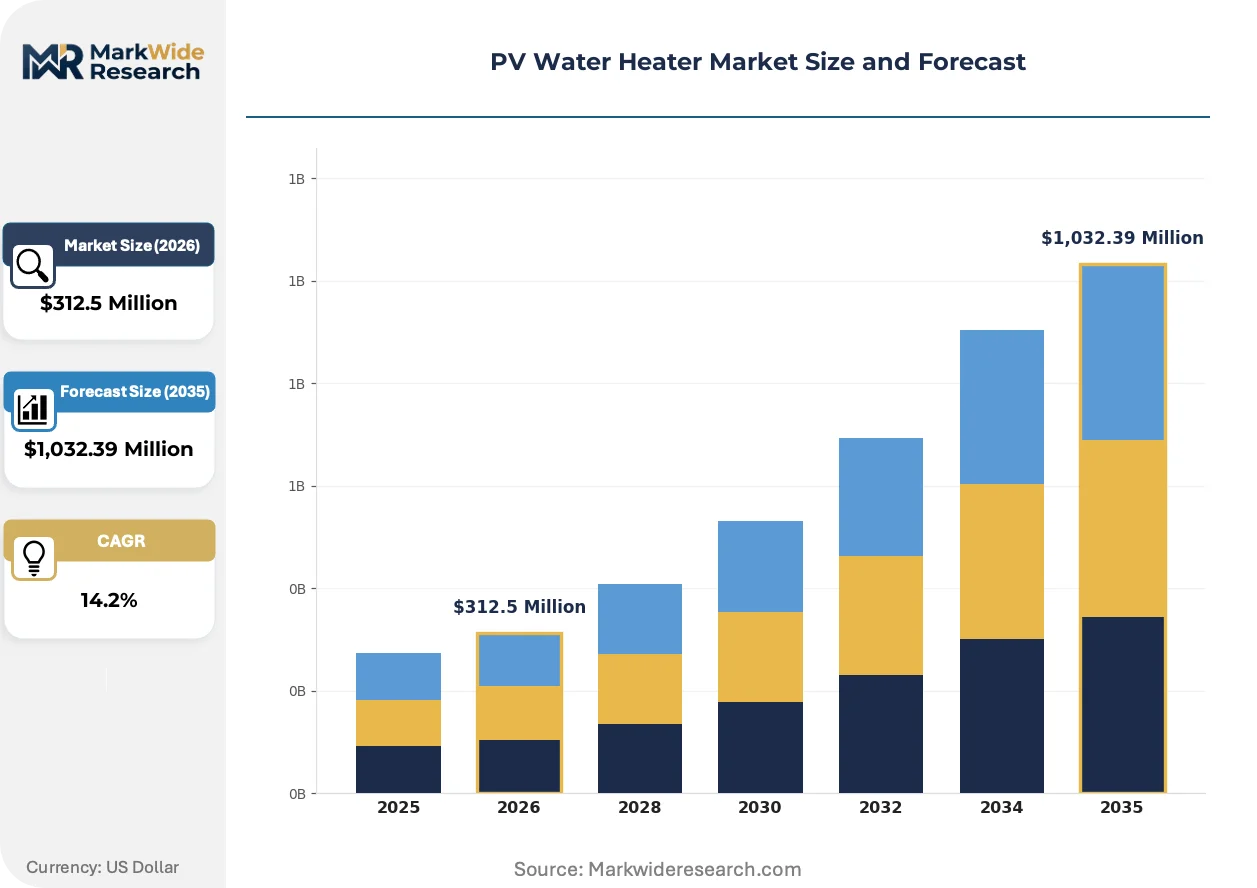
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,032.39 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate Collectors, Evacuated Tube Collectors, Integrated Collectors, Batch Heaters End User: Residential, Commercial, Industrial, Agricultural Installation Type: Roof-mounted, Ground-mounted, Portable, Hybrid Systems Distribution Channel: Direct Sales, Retail, Online Sales, Installers |
| Companies Covered | Himin Solar Energy Group, Rheem Manufacturing Company, A. O. Smith Corporation, Ariston Thermo SpA, Bosch Thermotechnology, V-Guard Industries Ltd, SunEarth Inc., Chromagen Ltd, KODSAN Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV Water Heater Market Trends and Innovations
Product architectures are bifurcating between utility-scale installations demanding predictive maintenance capabilities and distributed residential systems prioritizing plug-and-play installation simplicity.
Selective surface coatings with enhanced spectral absorption properties are absorbing a larger share of incident solar radiation across low-irradiance conditions. Australian housing developers are specifying these coatings for roof-mounted evacuated tube arrays in coastal regions. The technology is absorbing market share from conventional black-chrome surfaces by delivering superior annual yield per installed collector area.
EU F-Gas Regulation amendments are restricting hydrofluorocarbon-based heat transfer fluids in solar thermal circuits. European OEMs are reformulating propylene glycol and hydrocarbon alternatives to maintain CE marking compliance. Compact integrated systems for residential retrofits face the steepest reformulation cost burden due to sealed-unit design constraints.
Commercial asset operators are unbundling after-sales service contracts from equipment procurement, creating standalone subscription revenue pools. North American contractor networks are capturing these service relationships through multi-year thermal performance guarantees. The hospitality sector across Maharashtra and Karnataka states exhibits the most advanced adoption of outcome-based service structures.
PV Water Heater Market Segmentation
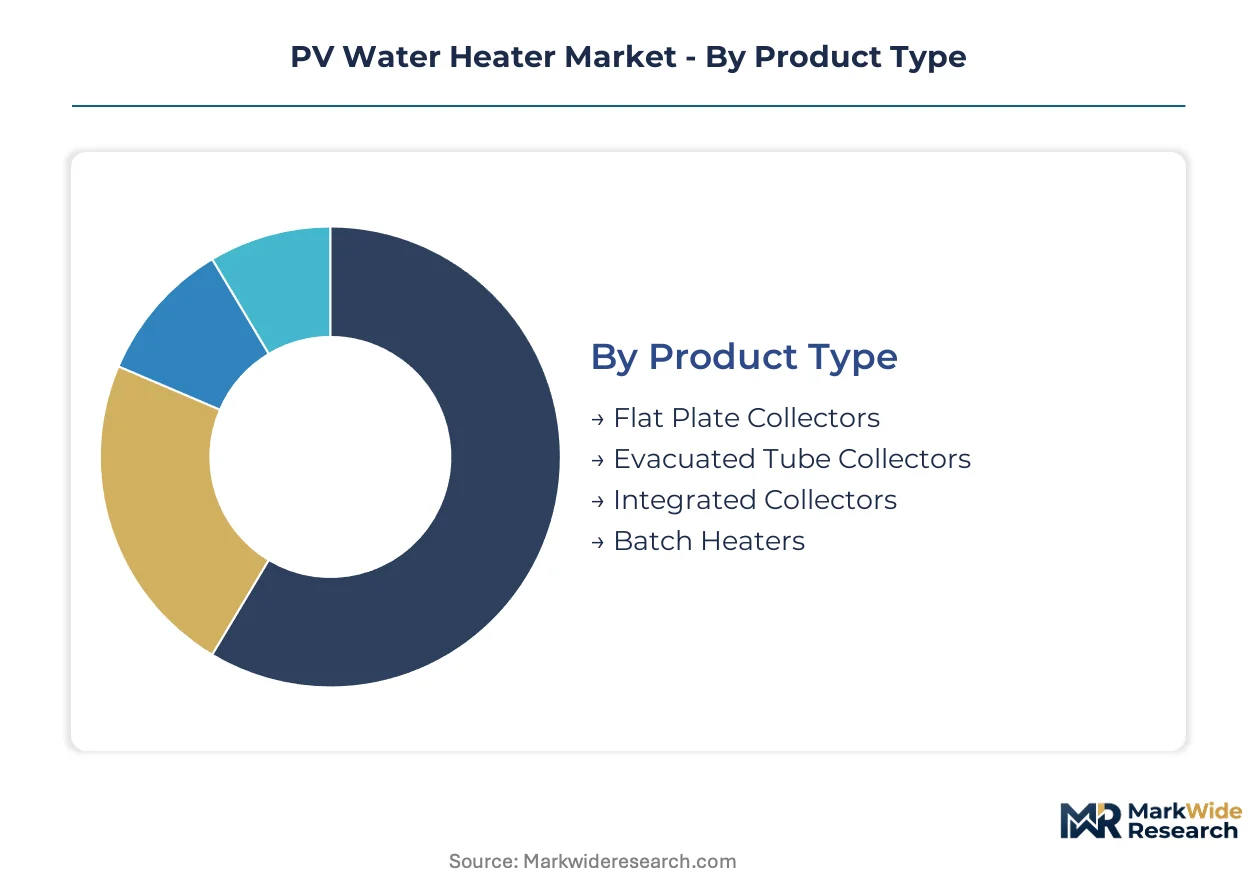
PV water heater architectures vary dramatically in capital requirements, installation complexity, and service revenue potential. Segmentation reveals which product configurations attract utility-scale investment versus distributed residential deployment.
Product Type:
Capital intensity escalates with thermal efficiency specifications and vacuum insulation requirements, separating commodity flat-plate manufacturing from precision-engineered evacuated tube production.
- Flat Plate Collectors:Aluminum or copper absorber plates bonded to insulated glazing deliver baseline thermal conversion at lowest unit cost. Australia's residential retrofit programs specify these for cost-conscious homeowners in Queensland and New South Wales where freeze risk remains minimal.
- Evacuated Tube Collectors:Borosilicate glass vacuum tubes with selective surface coatings achieve superior performance in cold climates through convective heat loss suppression. China's tier-one cities mandate these for new construction compliance under dual carbon building codes, driving procurement volume through state-owned developers.
- Integrated Collectors:Sealed thermal storage units combine collection and tank functions for compact European residential retrofits facing space constraints.
- Batch Heaters:Passive thermosiphon systems without pumps or controls serve off-grid agricultural applications in India's Maharashtra irrigation districts.
Most installed capacity flows through Flat Plate Collectors. Expansion is steepest in Evacuated Tube Collectors.
End User:
Engineering sophistication and contract duration distinguish commercial asset operators from residential consumers, reshaping OEM service model economics.
- Residential:Unit shipments dominate volume through distributed single-family installations. India's state-level subsidy programs and Australia's Small-scale Renewable Energy Scheme compress payback periods for homeowners, though margin pools remain thin due to price transparency.
- Commercial:Hotel chains across Karnataka and Maharashtra states deploy engineered systems with 15-20 year thermal performance contracts. Engineering complexity and remote monitoring subscriptions generate superior recurring revenue versus equipment margins alone.
- Industrial:Process heat integration for food processing and textile manufacturing requires custom absorber field design and heat exchanger specification.
- Agricultural:Dairy sterilization and greenhouse climate control applications concentrate in China's Shandong province and India's Punjab state.
Residential captures shipment volume leadership. Commercial commands premium margin expansion.
Installation Type:
Mounting configuration determines structural engineering requirements, permitting pathways, and maintenance access economics.
- Roof-mounted:Australia's housing developments specify evacuated tube arrays on pitched residential roofs, leveraging existing structural load capacity without foundation costs.
- Ground-mounted:Utility-scale installations across China's Hebei province require concrete piling and frost-protected plumbing, elevating capital intensity per kilowatt-thermal.
- Portable:Military and disaster relief applications demand rapid deployment without permanent infrastructure.
- Hybrid Systems:Solar thermal pre-heat paired with vapor-compression heat pumps addresses cold-climate performance gaps in European alpine regions.
Roof-mounted systems anchor current deployment. Hybrid configurations are gaining adoption fastest in high-latitude markets.
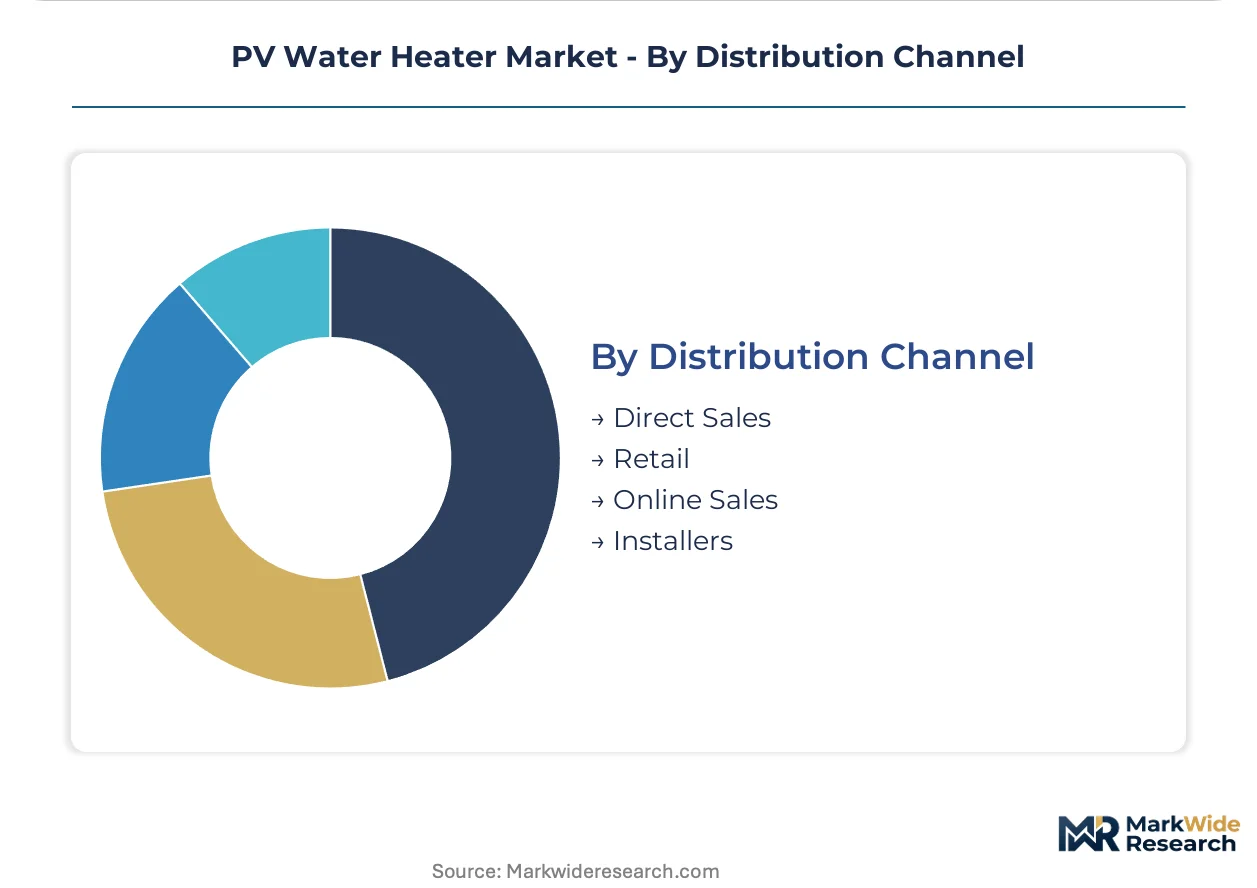
Distribution Channel:
Channel control determines installation quality accountability and aftermarket service attachment rates.
- Direct Sales:OEMs contract directly with commercial hospitality operators in Maharashtra and Karnataka, bundling equipment with predictive maintenance subscriptions.
- Retail:Big-box hardware chains in Australia's eastern states move flat-plate kits to DIY homeowners, though installation quality variability erodes system performance.
- Online Sales:E-commerce platforms penetrate price-sensitive residential segments with limited technical support infrastructure.
- Installers:Certified contractor networks in North America capture multi-year service relationships through thermal performance guarantees.
Direct sales channels concentrate commercial value. Installer networks are extending fastest into residential retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration patterns track divergence in regulatory compliance costs, with OEMs relocating assembly to jurisdictions offering streamlined certification pathways and localized incentive eligibility.
China
MIIT enforcement of updated GB standards for thermal conversion efficiency is filtering low-cost entrants from domestic procurement channels. The dual carbon policy framework mandates building-integrated renewable thermal systems across new residential construction. State-owned developers in Beijing and Shanghai are driving evacuated tube procurement volume through tier-one city construction mandates.
India
Commercial hospitality operators across Maharashtra and Karnataka states are deploying engineered systems with extended thermal performance contracts. BIS certification requirements for solar thermal products create compliance barriers favoring established manufacturers with testing infrastructure. Hotel chains in Mumbai and Bangalore exhibit the most advanced adoption of outcome-based service structures.
Australia
State-level rebate programs are compressing payback periods for homeowners adopting roof-mounted evacuated tube retrofits. The Small-scale Renewable Energy Scheme underpins residential deployment economics across New South Wales and Queensland. Housing developers in coastal regions are specifying selective surface coatings for superior annual yield per installed collector area.
Germany
EU F-Gas Regulation amendments are restricting hydrofluorocarbon-based heat transfer fluids in solar thermal circuits. CE marking directives shape material selection and heat transfer fluid specifications for European market access. Compact integrated systems for residential retrofits in Bavaria and North Rhine-Westphalia face the steepest reformulation cost burden.
United States
Certified contractor networks are capturing multi-year service relationships through thermal performance guarantees. The IRA extends tax credit eligibility for residential renewable thermal installations through 2032. North American retail and contractor networks sustain brand recognition for established OEMs across the Sun Belt states.
PV Water Heater Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with residential volume flowing through retail channels while commercial assets anchor direct OEM relationships. The vendor base organizes around three strategic archetypes: domestic manufacturing scale players serving utility-scale procurement, brand-recognized channel controllers in mature markets, and compact system specialists targeting European retrofit constraints. Dominant competitive moves include predictive maintenance subscription bundling and heat pump convergence for cold-climate performance extension.
Among Asia-Pacific manufacturing specialists, Himin Solar Energy Group exemplifies the domestic scale archetype anchoring supply for utility-scale installations. Rheem Manufacturing Company and Ariston Thermo SpA occupy positions within the brand-recognized tier, with the former representing North American channel control patterns and the latter exemplifying European compact system specialization. These three entities represent divergent geographic and strategic positioning within the competitive structure.
| Leading Market Players |
|---|
| Himin Solar Energy Group |
| Rheem Manufacturing Company |
| A. O. Smith Corporation |
| Ariston Thermo SpA |
| Bosch Thermotechnology |
| V-Guard Industries Ltd |
| SunEarth Inc. |
| Chromagen Ltd |
| KODSAN Company |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum price indices on the London Metal Exchange cascade through absorber plate manufacturing into three-tier pricing structures across premium, standard, and economy levels. China's MIIT enforcement of GB thermal efficiency standards filters low-cost entrants, compressing margin pools for commodity flat-plate producers while vacuum-insulated tube specialists retain pricing power.
Pricing Analysis
Retailer markup layers in Australian hardware chains absorb 18-25 points before reaching DIY homeowners, while direct-to-OEM contracting for commercial hospitality in Maharashtra eliminates intermediary margin capture. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and remote monitoring bundling. Pricing pressure stems from rooftop photovoltaic substitution competing for residential new-build capital allocation. Residential retrofits in Queensland exhibit highest price sensitivity; commercial asset operators in Karnataka prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
Workforce availability constraints in Shandong province and Tamil Nadu manufacturing clusters limit precision glassblowing capacity for borosilicate vacuum tubes. Supply concentrates in China, India, and Germany for absorber plate fabrication and selective coating application. Raw material dependencies draw from Chilean copper cathode, Australian aluminum ingot, and domestic borosilicate glass feedstock. Single-source vulnerability in vacuum pump technology for tube evacuation creates bottleneck risk. Distribution runs through certified installer networks in North America and direct OEM contracting for East Asian utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's dual carbon building codes and India's BIS certification timelines create compliance-driven demand acceleration. MIIT enforcement of updated GB standards represents the pivotal regulatory milestone reshaping competitive eligibility.
For Market Incumbents: Deepen backward integration into selective coating production to defend margin position against commodity flat-plate competitors. Anchor capacity expansion in Shandong province to secure vacuum tube supply for tier-one city construction mandates. Invest in predictive maintenance platform development to capture recurring revenue from commercial hospitality operators seeking uptime guarantees.
For New Entrants and Emerging Players: Capture the Australian residential retrofit segment where state-level rebate programs compress payback periods and brand loyalty remains undeveloped. Penetrate through online sales channels targeting price-conscious homeowners in Queensland and New South Wales. Differentiate via plug-and-play installation simplicity for existing housing stock without specialized hydronic engineering.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification bottlenecks strand sub-scale manufacturers without testing infrastructure. Long-term viability favors OEMs with dual capability in evacuated tube production and heat pump convergence architectures. Target acquisition profiles emphasize compact integrated system specialists serving European residential retrofit constraints. Monitor EU F-Gas Regulation amendment timing as inflection signal for heat transfer fluid reformulation cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Convergence Development | Hybrid architectures address cold-climate performance gaps in European alpine installations. |
| Predictive Maintenance Platform Launch | Remote monitoring subscriptions capture recurring revenue from Maharashtra hospitality operators. |
| Selective Coating Vertical Integration | In-house spectral absorption technology defends margin against black-chrome commoditization. |
| BIS Certification Infrastructure Investment | Testing capacity ownership accelerates 12-18 month approval timelines for commercial variants. |
| Direct Sales Channel Expansion | OEM contracting with Karnataka hotel chains bundles equipment with thermal performance guarantees. |
Research Methodology
Bottom-up residential and commercial deployment modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with solar thermal OEM procurement directors, certified installer network managers, commercial hospitality engineering heads, state renewable energy agency officials, and copper absorber plate suppliers validated demand assumptions. Secondary sources include MIIT GB standard filings, BIS certification registries, Australian Clean Energy Regulator SRES data, EU F-Gas Regulation amendment drafts, and London Metal Exchange price archives. Triangulation across these sources reconciles shipment volume estimates with production capacity surveys.
Input-output matrices map absorber plate and vacuum tube production through distribution channels to end-use segments across the projection horizon. Segmentation dimensions span product architecture, installation type, end-user category, and regional regulatory cluster. CAGRs derive from regression analysis of historical deployment against policy incentive trajectories and commodity price cycles. Forecast inputs incorporate dual carbon policy implementation timelines in tier-one Chinese cities and IRA tax credit extension mechanics for North American residential retrofits.
Underlying measurement precision varies by segment; commercial hospitality deployments with direct OEM contracting carry tighter precision than distributed residential retail sales. Forecasts reflect documented assumptions regarding policy continuity, certification timeline stability, and copper price volatility bands. Material deviation in MIIT enforcement intensity or EU F-Gas Regulation amendment scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Solar Watch Market