
 Fossil Fuel Fired Water Heaters Market | 2026-2036
Fossil Fuel Fired Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Fossil Fuel Fired Water Heaters Market Insights
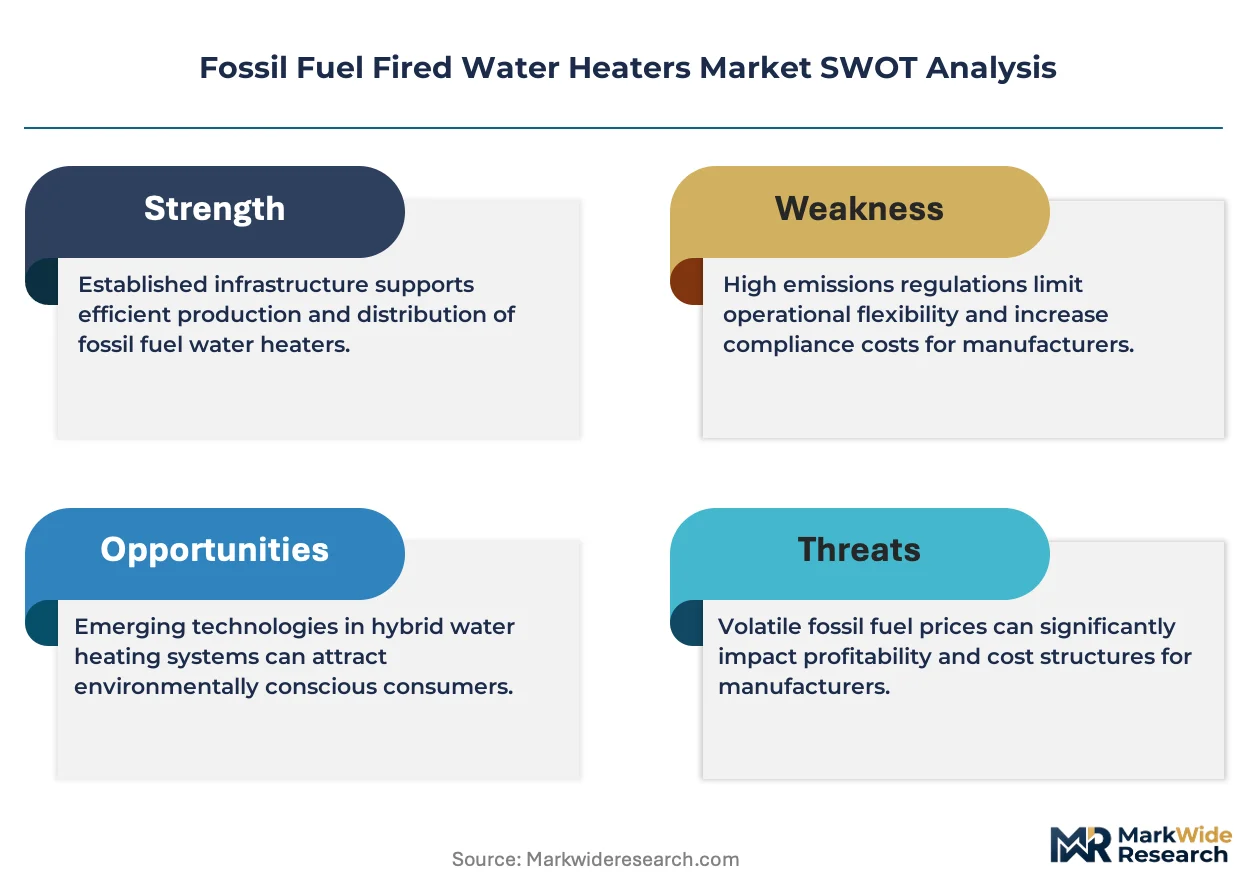
Equipment leasing and managed-service contracts for commercial water heating systems are reshaping competitive dynamics in the fossil fuel fired water heaters space. Rinnai Corporation leverages its tankless specialization to capture retrofit-driven hospitality upgrades across Japan and North America. A.O. Smith Corporation anchors its position through captive distribution networks and vertical manufacturing of condensing gas storage units. Rheem Manufacturing Company competes on scale, operating integrated foundry-to-assembly plants that control cost structures for natural gas product lines.
Fossil fuel fired water heaters are pressurized vessels that combust natural gas, propane, diesel, or oil to transfer thermal energy to potable water, typically achieving thermal efficiency ratings between 80% and 98% depending on condensing architecture and heat exchanger design. Tankless water heaters now lead growth in residential new construction where space constraints and on-demand delivery priorities dominate specification sheets. Storage water heaters retain the largest installed base but face margin compression as efficiency regulations tighten across multiple jurisdictions. The hospitality application segment concentrates replacement demand in full-service hotels where combination water heaters address simultaneous space heating and domestic hot water loads.
The US Department of Energy enforces minimum energy factor standards that disqualify non-condensing gas storage models from federal compliance, directly altering product mix toward higher-efficiency designs. The EPA regulates combustion emissions through New Source Performance Standards that limit NOx output from residential and commercial gas-fired appliances. ISO 9001 and ASME certification requirements govern pressure vessel integrity and manufacturing quality assurance for market access across North America and Europe. Stakeholders must monitor the trajectory of building electrification mandates and hydrogen blending trials in gas distribution networks to anticipate technology obsolescence risks and retooling requirements.
Market Dynamics
The US Department of Energy's condensing technology mandate is forcing a wholesale manufacturing retooling as non-condensing gas storage models lose federal compliance eligibility, compressing margins for legacy product lines while opening premium positioning for heat exchanger innovators.
Growth Catalysts
- DOE Appliance Efficiency Standards:Federal mandates for higher energy factor ratings accelerate replacement cycles in residential construction across suburban markets.
- Hospitality Retrofit Cycles:Full-service hotels drive combination water heater demand where simultaneous space heating and domestic hot water loads require integrated fossil fuel systems.
- Sun Belt Gas Infrastructure:Dense natural gas distribution networks in southern US states sustain deployment advantages over electric resistance alternatives in new housing stock.
Market Restraints
- Copper and Steel Input Volatility:Heat exchanger and tank raw material costs fluctuate with commodity markets, pressuring manufacturing cost structures.
- Building Electrification Mandates:State-level decarbonization policies in California, New York, and Washington restrict new fossil fuel hookups in residential construction.
- Hydrogen Blending Uncertainty:Gas utility pilot programs for H2 injection into distribution networks create technology obsolescence risk for burners not rated for variable fuel composition.
Strategic Opportunities
- Managed-Service Contracting:Equipment leasing models for commercial water heating shift capital expenditure to operational budgets, opening recurring revenue streams.
- Condensing Technology Export:European Union F-Gas Regulation and Ecodesign directives create demand for high-efficiency gas-fired systems in retrofit markets.
- Tankless Hybrid Systems:Integration of fossil fuel combustion with heat pump assist addresses efficiency thresholds while maintaining capacity during peak demand.
Industry Challenges
- ASME Pressure Vessel Certification:Extended testing timelines for new heat exchanger designs delay product launches and compress R&D amortization windows.
- Combustion Engineering Talent Scarcity:Specialized expertise in low-NOx burner design concentrates among retiring workforce cohorts, constraining innovation velocity.
- Legacy Inventory Stranding:Non-compliant product stockpiles face accelerated depreciation as enforcement dates for federal efficiency standards approach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fossil Fuel Fired Water Heaters Market |
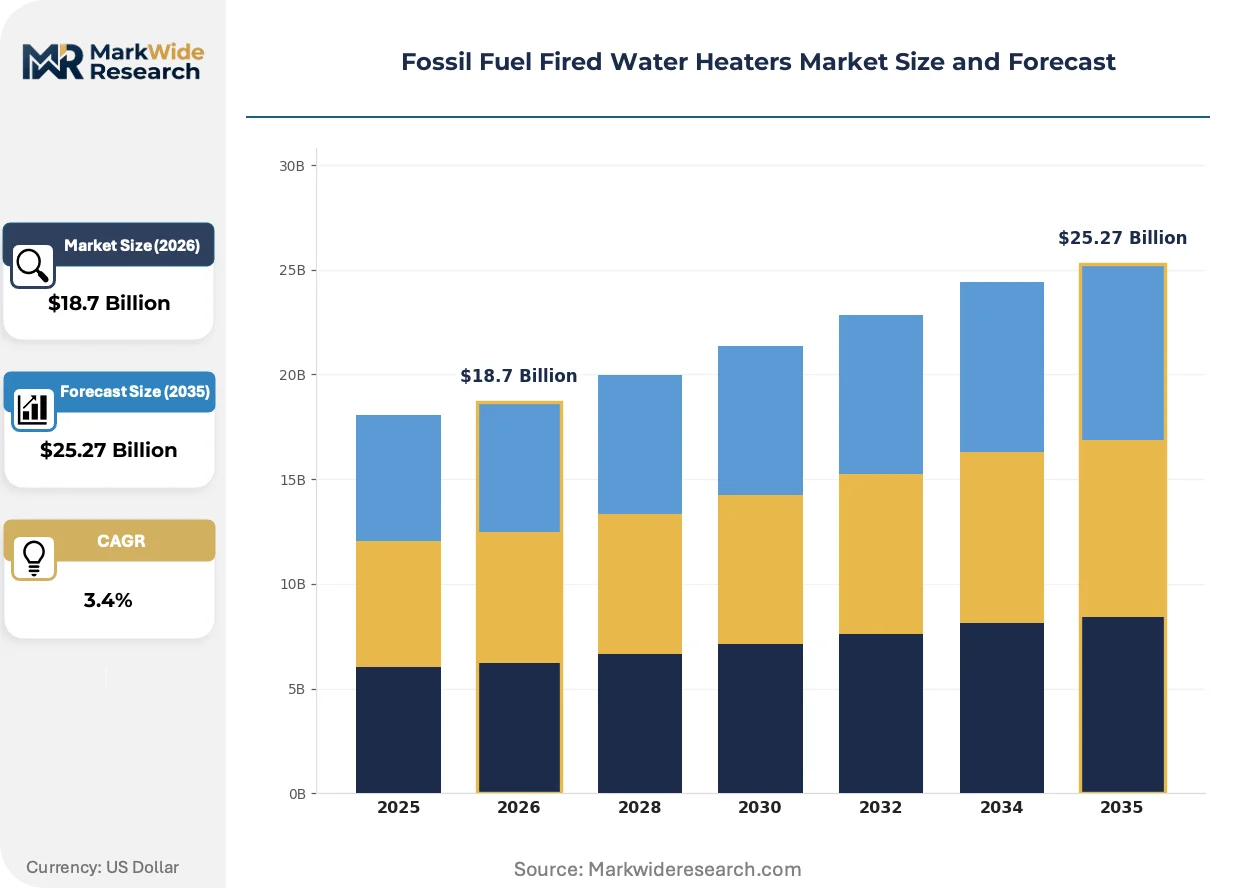
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $25.27 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless Water Heaters, Storage Water Heaters, Combination Water Heaters, Point-of-Use Heaters Fuel Type: Natural Gas, Diesel, Propane, Oil Application: Residential, Commercial, Industrial, Hospitality Installation Type: Indoor, Outdoor, Retrofit, New Construction |
| Companies Covered | Rinnai Corporation, Bosch Thermotechnology, A.O. Smith Corporation, Crompton Greaves Ltd., Midea Group, Rheem Manufacturing Company, Noritz Corporation, Electrolux, Bradford White Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fossil Fuel Fired Water Heaters Market Trends and Innovations
Condensing architecture and intelligent combustion controls are redefining product specifications across residential and commercial segments, with efficiency thresholds now serving as primary competitive differentiators rather than secondary features.
Condensing heat exchanger technology extracts latent heat from flue gases through secondary surface area, boosting thermal efficiency to 95% and above. Multi-family developers in Texas and Florida specify these systems to meet utility rebate thresholds and green building certifications. This performance tier is rendering obsolete atmospheric-vented storage units in new construction specifications.
EPA New Source Performance Standards for residential gas appliances tighten NOx emission limits, requiring burner redesigns and catalytic after-treatment in some jurisdictions. Manufacturers serving California and Texas markets now engineer separate product SKUs to satisfy divergent state-level air quality regulations. The commercial segment bears the heaviest compliance burden, with full-service hotels facing simultaneous federal, state, and local permitting requirements.
Equipment-as-a-service contracting displaces traditional capital purchase models in hospitality and healthcare facilities. Third-party energy service companies assume ownership and maintenance responsibility, charging per-therm or per-gallon fees. This arrangement concentrates most visibly in Arizona and Nevada resort markets where predictable hot water loads support risk-adjusted pricing models.
Fossil Fuel Fired Water Heaters Market Segmentation
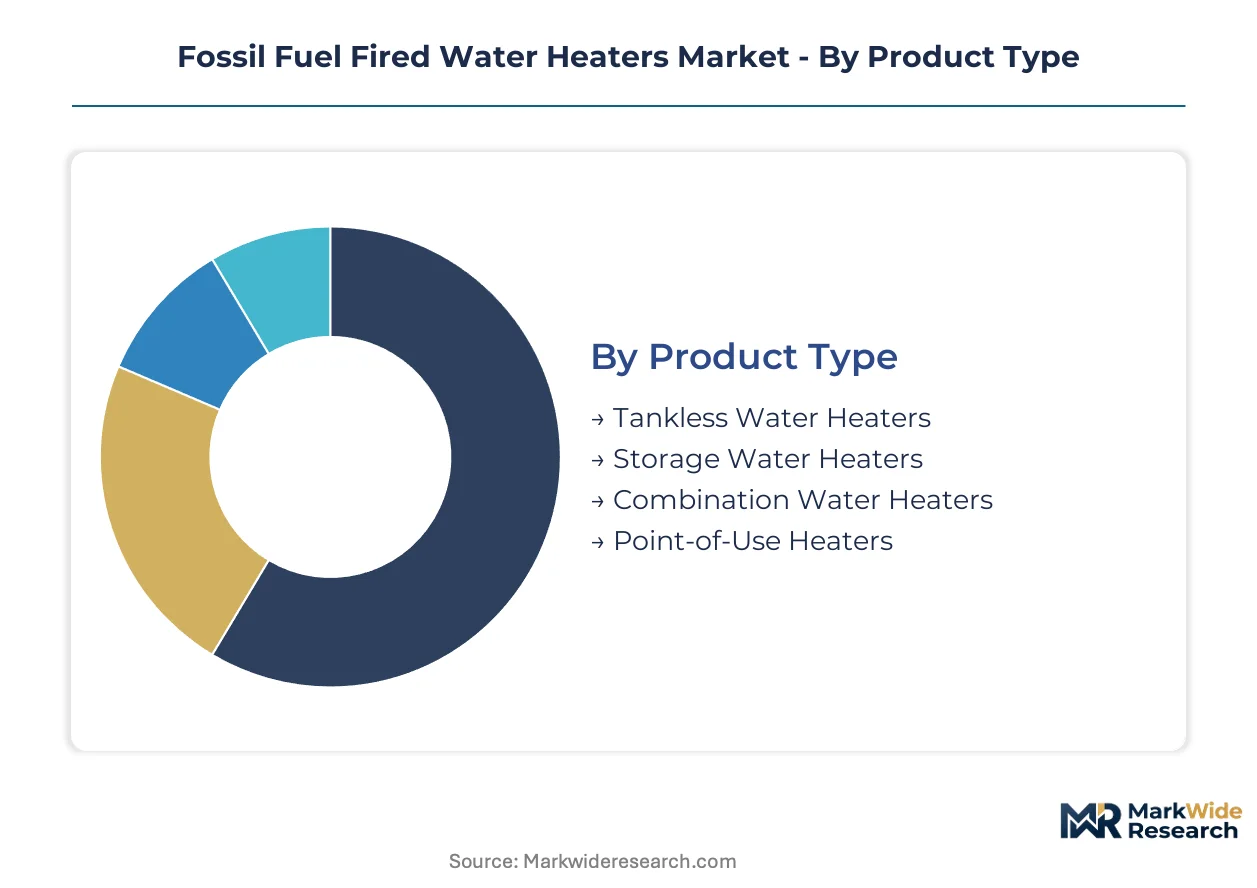
Product architecture and fuel compatibility determine specification pathways in fossil fuel fired water heaters. Installation context and end-use intensity further stratify procurement patterns across residential and commercial deployments.
Product Type:
Equipment configuration dictates thermal efficiency ceilings, spatial footprint, and peak delivery capacity for distinct building scenarios.
- Tankless Water Heaters:On-demand combustion systems eliminate standby losses through instantaneous heat exchanger activation. Suburban new construction in Texas and Florida specifies these units where utility rebate thresholds and green building certifications drive specification. Demand concentrates in single-family homes with space constraints and variable hot water loads.
- Storage Water Heaters:Pressurized vessels maintain heated water reserves for immediate draw, typically achieving 80-98% thermal efficiency depending on condensing architecture. The largest installed base persists in existing residential stock where retrofit compatibility outweighs efficiency premiums. Margin compression accelerates as federal standards disqualify non-condensing atmospheric-vented models.
- Combination Water Heaters:Integrated systems address simultaneous space heating and domestic hot water loads through single combustion appliances. Full-service hotels in Arizona and Nevada deploy these for predictable thermal demand profiles.
- Point-of-Use Heaters:Compact localized units serve isolated fixtures distant from central heating infrastructure. Remote commercial kitchens and hospitality back-of-house applications specify these for targeted capacity.
Storage water heaters command the established base. The steepest expansion runs through tankless systems.
Fuel Type:
Energy density and infrastructure penetration shape fuel selection across geographic markets and regulatory jurisdictions.
- Natural Gas:Pipeline-delivered methane offers lowest per-BTU operating cost where distribution networks exist. Dense infrastructure across US Sun Belt states sustains deployment advantages over electric resistance alternatives in new housing stock. The EPA's New Source Performance Standards mandate low-NOx burner redesigns for compliance.
- Propane:Liquefied petroleum gas serves rural and off-grid locations beyond pipeline reach. Residential construction in exurban Texas and Florida clusters specifies propane where natural gas extension proves uneconomical.
- Diesel:Distillate fuel oil powers high-capacity commercial and industrial systems requiring rapid thermal recovery. Remote industrial facilities and mining operations deploy diesel-fired units for operational independence from grid infrastructure.
- Oil:Heavy fuel oil persists in legacy northeastern US installations where heating oil distribution infrastructure predates gas conversion programs. Replacement demand concentrates in aged multi-family housing stock.
Natural gas dominates volume throughput. Propane is gaining share fastest in exurban construction corridors.
Application:
End-use intensity and load predictability determine equipment sizing, redundancy requirements, and service contract viability.
- Residential:Single-family and multi-family dwellings specify units sized to peak morning and evening demand profiles. Suburban North American housing modernization absorbs both tankless and storage configurations as efficiency regulations tighten.
- Commercial:Office buildings, retail, and institutional facilities require reliable capacity for intermittent but high-volume draws. Equipment-as-a-service contracting displaces capital purchase models where predictable loads support risk-adjusted pricing.
- Industrial:Manufacturing processes and wash-down operations demand ruggedized construction and rapid recovery rates. Food processing and automotive facilities specify heavy-duty heat exchanger designs for continuous-duty cycles.
- Hospitality:Full-service hotels drive combination water heater demand where simultaneous space heating and domestic hot water loads require integrated fossil fuel systems. Arizona and Nevada resort markets concentrate managed-service contract adoption.
Residential applications anchor unit shipments. Hospitality is expanding most quickly through retrofit-driven upgrades.
Installation Type:
Deployment context determines venting architecture, combustion air supply, and regulatory compliance pathways.
- Indoor:Enclosed installations require sealed combustion or power-vented configurations to manage exhaust and intake air. Cold-climate jurisdictions mandate condensing technology with sidewall venting for efficiency compliance.
- Outdoor:Exterior mounting eliminates indoor space requirements and simplifies venting through atmospheric exposure. Sun Belt residential new construction favors outdoor tankless units for minimal footprint.
- Retrofit:Replacement installations must accommodate existing venting infrastructure and utility connections. California and New York building electrification mandates restrict new fossil fuel hookups, compressing retrofit opportunity windows.
- New Construction:Greenfield specifications integrate water heating into holistic mechanical system design. Condensing technology and intelligent combustion controls now serve as primary competitive differentiators in builder selection criteria.
Retrofit installations command replacement volume. New construction is climbing the fastest as housing stock modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fossil fuel fired water heaters reflect concentrated manufacturing in East Asia and North America against import-dependent European markets seeking high-efficiency condensing units. Trade flows track natural gas infrastructure penetration and regulatory divergence on appliance efficiency standards.
United States
Sun Belt suburban construction in Texas and Florida absorbs tankless and storage units as housing stock modernizes. The US Department of Energy's appliance efficiency standards push manufacturers toward condensing technology and higher EF ratings. Arizona and Nevada resort markets concentrate managed-service contract adoption for hospitality applications.
China
Domestic production capacity serves both internal demand and export markets across Southeast Asia and Africa. The country's national standards regulator enforces GB energy efficiency classifications that align with international condensing technology benchmarks. Manufacturing clusters in Guangdong and Zhejiang provinces export tankless systems to Belt and Road infrastructure projects.
Germany
European Union Ecodesign directives and F-Gas Regulation create demand for high-efficiency gas-fired systems in retrofit markets. The national building energy regulator enforces strict thermal performance requirements for residential heating appliances. Industrial concentration in Bavaria and North Rhine-Westphalia supports precision heat exchanger fabrication for export.
Japan
Retrofit-driven hospitality upgrades absorb tankless specialization from domestic manufacturers serving both commercial and residential segments. METI efficiency labeling programs accelerate replacement cycles in aging urban housing stock. Manufacturing concentration around Nagoya and Osaka supplies condensing technology to Southeast Asian markets.
Canada
Cold-climate jurisdictions mandate condensing technology with sidewall venting for efficiency compliance in residential new construction. Natural Resources Canada administers EnerGuide ratings that disqualify non-condensing atmospheric-vented models from federal rebate programs. Ontario and Quebec housing modernization drives replacement demand in multi-family stock.
Fossil Fuel Fired Water Heaters Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive distribution networks and in-house heat exchanger production. Tiered competitive positioning separates premium condensing specialists from scale-driven standard product assemblers and regional private-label fabricators. Strategic archetypes include technology licensors, vertically integrated foundry operators, and energy-service aggregators. Dominant competitive moves encompass backward integration into heat exchanger manufacturing and geographic expansion through managed-service contract platforms.
Within the integrated manufacturing tier, Rinnai Corporation and A.O. Smith Corporation exemplify divergent strategic positioning. Rinnai anchors the tankless specialization archetype with concentrated presence in Japanese and North American hospitality retrofit cycles. A.O. Smith represents the captive distribution model through vertical control over condensing gas storage unit fabrication. Rheem Manufacturing Company occupies the scale-driven position with integrated foundry-to-assembly cost structures.
| Leading Market Players |
|---|
| Rinnai Corporation |
| Bosch Thermotechnology |
| A.O. Smith Corporation |
| Crompton Greaves Ltd. |
| Midea Group |
| Rheem Manufacturing Company |
| Noritz Corporation |
| Electrolux |
| Bradford White Corporation |
| Others |
Pricing and Supply Chain Analysis
Guangdong and Zhejiang manufacturing clusters in China concentrate heat exchanger and burner assembly capacity, anchoring margin pools downstream with North American and Japanese OEMs who command premium positioning through captive distribution networks and condensing technology specialization. Copper coil and stainless-steel tank inputs flow through these hubs before final assembly, with pricing power accumulating at brand owners who control certification pathways and service infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the fossil fuel fired water heaters space. Price differentiation rests on ASME certification grade and condensing efficiency tier, with UL-listed commercial units commanding substantial premiums over residential atmospheric-vented models. Cost compression in the standard tier is intensifying because DOE efficiency mandates are accelerating obsolescence of legacy non-condensing designs. Hospitality procurement teams exhibit the lowest price sensitivity due to operational criticality of hot water uptime, while residential retrofit consumers drive aggressive quote competition.
Supply Chain Analysis
Foundry and heat exchanger fabrication capacity concentrates with Jiaxing Precision, Midea Group, and specialized Japanese metalwork suppliers serving tier-one OEMs. Raw material flows draw from Chilean copper cathode, Indonesian nickel for stainless alloys, and domestic Chinese steel coil. Single-source vulnerability in precision burner nozzle machining creates chokepoint exposure for low-NOx compliance variants. Distribution runs through plumbing wholesale networks, big-box retail, and direct-to-contractor channels with increasing energy-service company intermediation in commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fossil fuel fired water heaters market is entering a cyclical recovery phase as federal efficiency mandates force replacement waves and hospitality retrofit cycles accelerate. Housing stock modernization across Sun Belt states provides the cyclical driver justifying constructive positioning.
For Market Incumbents: Insulate core margin pools by accelerating backward integration into heat exchanger manufacturing and securing captive distribution in exurban propane corridors. Building electrification mandates in California and New York represent the primary demand destruction threat requiring geographic rebalancing toward Texas and Florida growth corridors. Certification investment in hydrogen-ready burner designs offers a defensive technology hedge against fuel composition uncertainty.
For New Entrants and Emerging Players: Exurban propane markets in Texas and Florida present the most penetrable white-space opportunity where natural gas infrastructure gaps persist and incumbent coverage remains thin. Tankless hybrid systems combining fossil fuel combustion with heat pump assist offer specification entry points in green building projects seeking efficiency thresholds without capacity sacrifice. Equipment-as-a-service contracting models provide a go-to-market angle that converts capital expenditure friction into recurring revenue relationships with hospitality developers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with in-house heat exchanger production and established ASME certification pathways. Long-term viability over the next decade hinges on hydrogen compatibility engineering capabilities and managed-service contract platform scale. The signal to watch is state-level building electrification mandate expansion beyond California, New York, and Washington into Sun Belt jurisdictions, which would compress addressable market scope and accelerate technology obsolescence timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Condensing Technology Scale-Up | DOE efficiency mandates render non-condensing designs federally non-compliant, forcing manufacturing retooling. |
| Hydrogen-Ready Burner Development | Gas utility H2 blending pilots create technology obsolescence risk for non-adaptable combustion systems. |
| Managed-Service Contract Expansion | Equipment-as-a-service models shift hospitality capital expenditure to operational budgets in Arizona and Nevada. |
| Backward Integration into Heat Exchangers | In-house production of ASME-certified vessels reduces lead times and protects margin from commodity volatility. |
| Geographic Manufacturing Footprint Shift | Production relocation toward Sun Belt demand centers reduces logistics costs and tariff exposure. |
Research Methodology
Operator-level perspectives from plant engineers at OEM assembly facilities, procurement directors at hospitality chains, plumbing contractor owner-operators, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from DOE appliance efficiency filings, EPA New Source Performance Standards documentation, ASME boiler and pressure vessel code updates, and customs trade data on copper and steel imports. Bottom-up unit shipment modeling and top-down construction spending allocation triangulated market sizing across product and application segments.
Scenario-bracketing around DOE enforcement timelines, building electrification policy trajectories, and hydrogen blending adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, fuel compatibility, application intensity, and installation context. CAGRs derived from regression analysis against housing starts, commercial construction put-in-place, and regulatory compliance cycle timing. Industry-specific forecast inputs incorporated utility rebate program budgets and green building certification adoption rates.
Practitioners should monitor state-level decarbonization mandate expansion, hydrogen blending trial outcomes, and copper price volatility for early signals of forecast revision. Forecasts reflect assumptions regarding federal efficiency standard enforcement continuity and Sun Belt construction cycle durability. Quarterly review of DOE rulemaking dockets, state legislative calendars, and commodity futures curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Europe Combined Heat and Power Market
Boilers
Global Domestic Boilers Market
Boilers
District Heating Market
Boilers
Residential Boiler Market
Boilers
Utility Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Germany Combined Heat and Power Market
Boilers
Biomass Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Global Package Boilers Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Advanced Utility Boilers Market
Boilers
Field Erected Boiler Market