
 Air Preheater Market | 2026-2036
Air Preheater Market Size, Share, and Industry Trends Forecast 2026-2036
Air Preheater Market Outlook
Chinese boiler OEM capacity is rebalancing toward higher-efficiency regenerative designs as domestic power plant overhaul cycles peak. Mitsubishi Heavy Industries leverages its rotating regenerative technology leadership to anchor utility contracts across East Asian markets. Babcock & Wilcox Enterprises sustains its North American installed base through aftermarket service networks and spare rotor assemblies. Howden Group differentiates via vertical integration into corrosion-resistant enameling for heat transfer surfaces.
An air preheater is a heat recovery device that captures waste flue gas thermal energy to preheat combustion air, typically operating across temperature differentials of 150°C to 400°C depending on boiler load and fuel type. The equipment reduces fuel consumption by 5-10% in pulverized coal boilers and extends furnace flame stability. Regenerative systems occupy the dominant share of large utility installations due to their compact footprint and superior heat transfer coefficients versus tubular alternatives. Recuperative configurations sustain demand in smaller industrial boilers where leakage tolerance and maintenance simplicity outweigh efficiency premiums. Manufacturing plants represent a growing end-user segment as process steam systems face carbon accounting pressures.
EPA Mercury and Air Toxics Standards tighten particulate and acid gas thresholds that degrade preheater cold-end surfaces, driving demand for upgraded corrosion-resistant materials. China's MIIT enforces mandatory boiler efficiency minimums that effectively phase out legacy recuperative units without air heater modifications. India's CEA mandates periodic energy audits for plants above designated thermal capacities, creating compliance-driven replacement cycles. Stakeholders must monitor regulatory divergence between efficiency mandates and emissions caps, as tightening one standard without coordinating the other can strand capital in prematurely obsolete configurations.
Market Dynamics
China's MIIT efficiency mandates are forcing boiler OEMs to abandon legacy recuperative designs in favor of regenerative systems with superior heat transfer coefficients and compact footprints. This regulatory compression is reshaping manufacturing priorities across the supply chain.
Growth Catalysts
- Regenerative technology maturation:Rotating regenerative preheaters now achieve leakage rates below 8%, making them viable for India's cement corridor expansion around Rajasthan and Gujarat where clinker lines demand high thermal efficiency.
- EPA Mercury and Air Toxics Standards:The US regulation tightens acid gas thresholds that degrade cold-end surfaces, compelling utilities to upgrade corrosion-resistant materials in existing installations.
- India's CEA energy audit mandate:Plants above designated thermal capacities must undergo periodic assessments, creating compliance-driven replacement cycles for aging air heater fleets.
Market Restraints
- Specialized alloy input volatility:EN 1.4876 and similar heat-resistant steels face price swings tied to nickel supply concentration in Indonesian smelter operations.
- Technical leakage floor:Even advanced regenerative designs cannot eliminate air-to-gas leakage below 5-6% without prohibitive sealing complexity.
- Substitution by economizers:Feedwater economizers in combined-cycle plants capture waste heat with lower maintenance overhead, limiting preheater addressable market in gas-fired installations.
Strategic Opportunities
- Process steam carbon accounting:Manufacturing plants under EU Green Deal reporting requirements face pressure to document thermal efficiency improvements, opening retrofit demand outside traditional power generation.
- Biomass co-firing retrofits:Preheaters with acid-resistant enameling can handle corrosive flue gases from agricultural residue combustion, an emerging application in Southeast Asian sugar mills.
- Aftermarket service unbundling:Independent rotor assembly refurbishment contracts bypass OEM service networks, creating channel innovation opportunities in North America's aging installed base.
Industry Challenges
- Enameling technician scarcity:Corrosion-resistant heat transfer surface preparation requires specialized ceramic coating expertise concentrated in German and Japanese supplier networks.
- Legacy system integration:Retrofitting regenerative units into 1960s-era boiler footprints demands custom ductwork modifications that extend project timelines and capex uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Preheater Market |
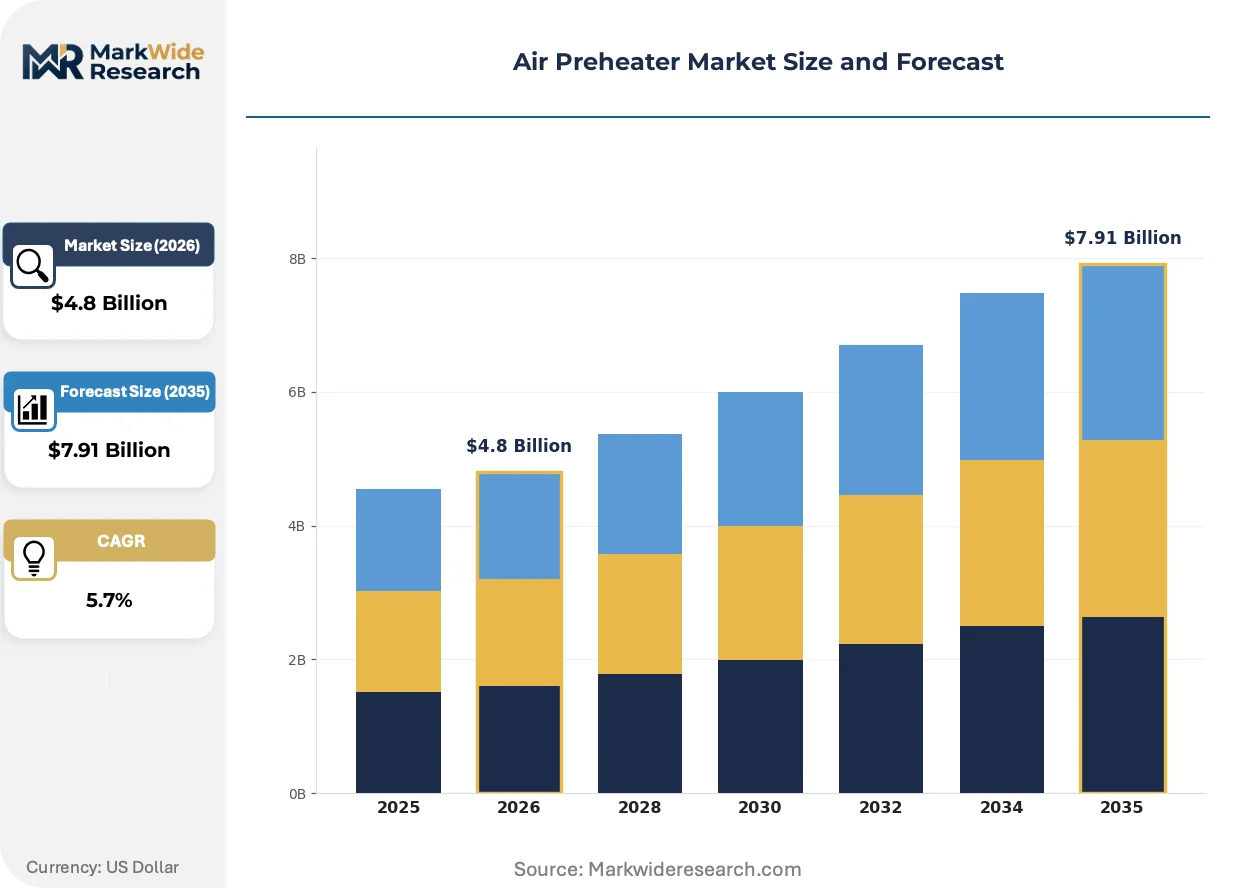
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reheating Units, Regenerative Systems, Recuperative Systems, Others End User: Manufacturing Plants,Power Generation, Petrochemical Industry, Cement Industry Technology: Thermal Exchange, Air-To-Air Heat Exchangers, Gas-To-Air Heat Exchangers, Others Installation Type: Horizontal, Vertical, Mobile, Fixed |
| Companies Covered | Howden Group, Mitsubishi Heavy Industries, Balcke-Dürr GmbH, Kelvion Holding GmbH, ARVOS Group, Babcock & Wilcox Enterprises, Thermax Limited, Andritz AG, GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Preheater Market Strategic Shifts
Digital monitoring systems and advanced materials are compressing maintenance cycles while regulatory pressure accelerates specification upgrades. Equipment buyers now prioritize total lifecycle cost over initial capital expenditure.
Corrosion-resistant enameling for heat transfer surfaces is converging with real-time leakage monitoring to extend cold-end element lifespan beyond 80,000 operating hours. Cement producers in India's Gujarat cluster are piloting these hybrid systems to reduce unplanned outages during peak clinker production seasons. The technology convergence is enabling longer intervals between rotor replacements, compressing aftermarket revenue timing for traditional service providers.
REACH authorization requirements for chromium compounds are restricting hexavalent chrome use in protective coatings for European boiler installations. Manufacturers must reformulate surface treatments or secure costly authorization exemptions for legacy product lines. German utility procurement specifications now explicitly favor trivalent chrome alternatives, forcing coating suppliers to accelerate qualification timelines.
Long-term service agreements are displacing transactional spare parts purchasing among Southeast Asian independent power producers. These contracts bundle rotor assembly refurbishment with performance guarantees, transferring operational risk to OEM service networks. The shift is most visible in Thailand's gas-fired cogeneration sector where fuel price volatility makes predictable maintenance costs attractive to plant operators.
Air Preheater Market Segmentation
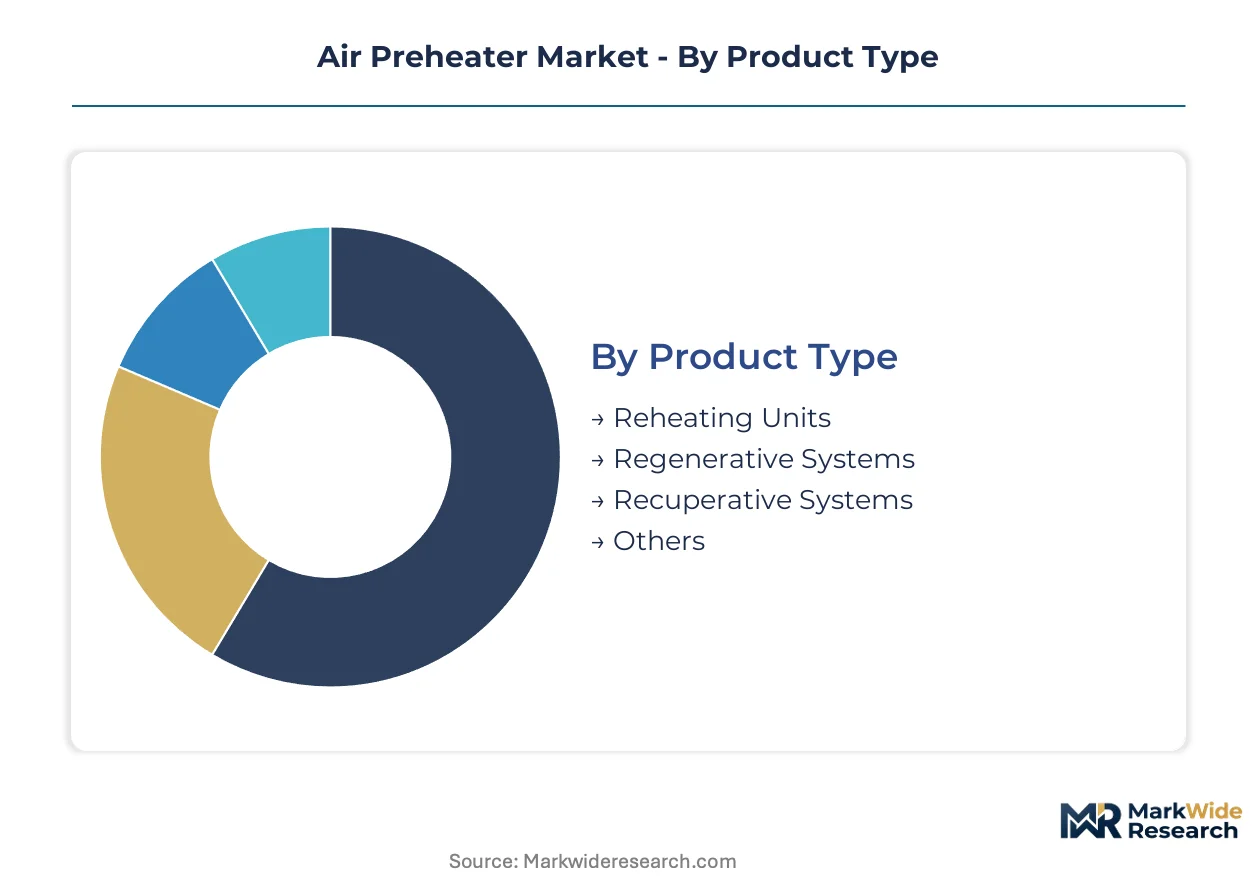
Air preheater procurement decisions hinge on thermal efficiency targets, fuel chemistry, and retrofit constraints. Specification mismatches between boiler duty cycles and heater technology drive replacement cycles and aftermarket service intensity across industrial and utility installations.
Product Type:
Rotating regenerative designs dominate large-scale thermal power applications due to superior heat transfer density and compact footprint advantages.
- Regenerative Systems:Rotating matrix preheaters achieve thermal efficiencies above 75% through cyclic heat storage in corrugated metal elements. Demand concentrates in India's cement corridor around Rajasthan and Gujarat, where new clinker lines specify leakage rates below 8% to meet CEA energy audit thresholds.
- Recuperative Systems:Stationary tubular configurations separate flue gas and combustion air streams through conductive metal walls. China's MIIT efficiency mandates are accelerating phase-out of legacy recuperative units lacking modification headroom, compressing replacement timelines for industrial boiler fleets.
- Reheating Units:Secondary air temperature boosters extend flame stability in low-NOx burner retrofits.
- Others:Hybrid and specialized configurations address biomass co-firing corrosion challenges.
Mature deployment sits with Recuperative Systems in aging industrial boiler parks. Newer deployment is concentrated in Regenerative Systems for utility-scale efficiency compliance.
End User:
Carbon accounting pressures are redistributing demand across process industries previously dependent on conventional thermal management.
- Power Generation:Utility boilers above 300MW specify regenerative preheaters with real-time leakage monitoring to optimize combustion air temperature across load cycles. Southeast Asian independent power producers are shifting toward long-term service agreements bundling rotor refurbishment with performance guarantees.
- Cement Industry:Clinker production lines require acid-resistant enameling to handle alkali-laden flue gases from alternative fuel co-firing. Gujarat-based producers are piloting hybrid monitoring systems to compress unplanned outage windows during peak production seasons.
- Manufacturing Plants:Process steam systems face EU Green Deal reporting requirements for thermal efficiency documentation.
- Petrochemical Industry:Cracking furnace integration demands materials resistant to sulfidation and high-temperature oxidation.
Procurement volume tilts toward Power Generation for replacement cycles. Procurement velocity is climbing fastest in Manufacturing Plants under emerging carbon disclosure obligations.
Technology:
Heat exchange mechanism selection determines maintenance intervals, cold-end corrosion susceptibility, and integration complexity with existing ductwork.
- Thermal Exchange:Direct-contact systems achieve maximum temperature approach but require separation of particulate-laden streams. Petrochemical crackers in the US Gulf Coast deploy these configurations where flue gas cleanliness permits.
- Gas-To-Air Heat Exchangers:Indirect systems isolate corrosive combustion products from combustion air through intermediate heat transfer surfaces. EPA Mercury and Air Toxics Standards are compelling utilities to upgrade cold-end materials in these installations to withstand acid gas condensation.
- Air-To-Air Heat Exchangers:Closed-loop recuperators serve specialized applications requiring absolute leakage isolation.
- Others:Emerging ceramic and compact heat exchanger technologies address ultra-high temperature duties.
Established capacity concentrates in Gas-To-Air Heat Exchangers. Technology investment is flowing toward Thermal Exchange optimization for combined-cycle integration.
Installation Type:
Physical orientation and mobility constraints shape project engineering timelines and capital deployment patterns.
- Horizontal:Low-headroom configurations accommodate retrofit installations beneath existing economizer banks. US Midwest utilities favor these arrangements for 1960s-era boiler footprints where vertical clearance is restricted.
- Vertical:Gravity-assisted drainage and compact plan area suit new-build utility installations. Chinese boiler OEMs are rebalancing manufacturing capacity toward vertical regenerative designs as domestic power plant overhaul cycles peak.
- Fixed:Permanent foundations dominate utility and large industrial applications.
- Mobile:Skid-mounted units serve temporary steam supply and rental boiler markets.
Fixed installations anchor the installed base. Mobile configurations are gaining traction in contingency power and seasonal industrial demand peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel smelters anchor alloy supply chains for heat-resistant steels, concentrating procurement leverage among preheater fabricators across three continents. Regulatory divergence between efficiency mandates and emissions caps is fragmenting specification standards.
China
MIIT boiler efficiency minimums are phasing out legacy recuperative units without modification headroom. Domestic power plant overhaul cycles are peaking, forcing OEM capacity rebalancing toward vertical regenerative designs. Yangtze River Delta fabricators are scaling enameling operations to meet acid-resistant coating demand.
United States
EPA Mercury and Air Toxics Standards tighten acid gas thresholds degrading cold-end surfaces. Midwest utilities favor horizontal configurations beneath 1960s-era economizer banks with restricted vertical clearance. Gulf Coast petrochemical crackers deploy thermal exchange systems where flue gas cleanliness permits.
India
CEA energy audit mandates for plants above designated thermal capacities create compliance-driven replacement cycles. Rajasthan and Gujarat cement corridors specify regenerative preheaters with leakage rates below 8% for new clinker lines. Gujarat-based producers pilot hybrid monitoring systems to compress unplanned outage windows.
Germany
REACH authorization requirements restrict hexavalent chrome in protective coatings for boiler installations. Utility procurement specifications now favor trivalent chrome alternatives, forcing coating suppliers to accelerate qualification timelines. ECHA regulatory pressure is reshaping surface treatment supply chains across European installations.
Japan
METI efficiency guidelines for industrial thermal systems are tightening combustion equipment specifications. Rotating regenerative technology leadership anchors utility contracts across East Asian markets through long-term service agreements. Domestic fabricators concentrate on corrosion-resistant enameling expertise for biomass co-firing retrofits.
Air Preheater Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue aftermarket service unbundling and specialized coating technologies. The vendor base separates into three functional tiers: full-system integrators with rotating regenerative portfolios, component specialists controlling heat-resistant alloy supply, and independent service providers refurbishing rotor assemblies. Consolidation pressure concentrates among enameling technicians with ceramic coating expertise. Dominant competitive moves include strategic partnerships for corrosion-resistant material qualification and geographic licensing of regenerative designs.
Among Asia-Pacific industrial conglomerates, Mitsubishi Heavy Industries and Howden Group represent the integrated-system archetype, while Babcock & Wilcox Enterprises exemplifies the installed-base service model. These three anchors demonstrate how technology leadership, vertical supply control, and aftermarket network density constitute distinct competitive vectors. Specialists in heat transfer surface preparation remain concentrated in German and Japanese supplier networks.
| Leading Market Players |
|---|
| Howden Group |
| Mitsubishi Heavy Industries |
| Balcke-Dürr GmbH |
| Kelvion Holding GmbH |
| ARVOS Group |
| Babcock & Wilcox Enterprises |
| Thermax Limited |
| Andritz AG |
| GEA Group AG |
| Others |
Value Chain & Pricing Dynamics
Enameling technician scarcity in German and Japanese supplier networks widens labor-cost differentials between premium corrosion-resistant coatings and standard metallic finishes, compressing pricing-tier spreads for mid-grade heat transfer surfaces.
Pricing Analysis
Warranty bundling separates premium rotor assembly contracts from unbundled spare parts transactions in North America's aging installed base. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Cost compression in economy tiers is intensifying because independent refurbishment shops bypass OEM service networks. Cement producers in India's Gujarat cluster demonstrate lowest price sensitivity due to unplanned outage costs during peak clinker seasons.
Supply Chain Analysis
Refurbishment flows from US Midwest utilities to specialized rotor assembly shops create reverse-logistics value recovery in aftermarket channels. Heat-resistant steel production draws from Indonesian nickel smelters, Chinese Yangtze River Delta fabricators, and German coating specialists. EN 1.4876 alloy price volatility tied to single-source smelter concentration presents persistent supply risk. Distribution runs through OEM captive networks and independent service providers serving utility maintenance windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around enameling capability scarcity, forcing capital-constrained fabricators toward acquisition or exit as corrosion-resistant coating demand outpaces qualified technician supply.
For Market Incumbents: Extend long-term service agreement coverage to Southeast Asian independent power producers, transferring operational risk through bundled rotor refurbishment with performance guarantees. Deepen backward integration into acid-resistant enameling operations to capture margin pools currently flowing to German and Japanese coating specialists. Biomass co-firing retrofits in Southeast Asian sugar mills represent a substitution threat requiring preemptive technology positioning. For New Entrants and Emerging Players: Launch via independent rotor assembly refurbishment contracts in North America, bypassing OEM service networks to capture aftermarket revenue from 1960s-era boiler fleets. Target India's cement corridor expansion around Rajasthan and Gujarat with regenerative preheater offerings specifying leakage rates below 8%. Process steam carbon accounting in EU manufacturing plants under Green Deal reporting requirements presents the most penetrable white-space segment. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated coating specialists given REACH authorization pressure on hexavalent chrome alternatives. Long-term viability favors fabricators controlling captive enameling capacity across the projection horizon. Acquisition focus should center on German and Japanese heat transfer surface preparation networks with ceramic coating expertise. Monitor ECHA regulatory timelines for trivalent chrome qualification acceleration as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enameling Operations | Captures margin pools from corrosion-resistant coating demand concentrated in German and Japanese networks. |
| Long-term Service Agreement Expansion | Transfers operational risk to OEM networks for Thailand's gas-fired cogeneration sector facing fuel price volatility. |
| Biomass Co-firing Retrofit Development | Opens Southeast Asian sugar mill demand through acid-resistant systems handling agricultural residue combustion. |
| Independent Refurbishment Channel Buildout | Bypasses OEM service networks to capture aftermarket value from North America's aging installed base. |
| Trivalent Chrome Coating Qualification | Secures European utility procurement preference as REACH authorization restricts hexavalent chrome alternatives. |
Study Parameters
Independent corroboration across OEM procurement directors, plant maintenance engineers, and aftermarket service heads underwrites the qualitative findings. Primary interviews with utility planning officers, cement plant operations managers, and coating supplier technical directors combined with secondary validation from customs trade data, boiler manufacturer SEC filings, and EPA regulatory dockets. Bottom-up equipment shipment tracking and top-down energy efficiency mandate impact modeling provide triangulation across the analysis window.
Comparable-period anchoring to historical power plant overhaul cycles and industrial boiler replacement waves structured the forecast window. Segmentation dimensions modeled include regenerative versus recuperative technology, power generation versus cement versus manufacturing end-use, and horizontal versus vertical installation orientation. CAGRs derived from equipment shipment trajectories and regulatory compliance timeline acceleration. Forecast inputs incorporate MIIT efficiency mandate phase-out schedules and CEA energy audit mandate enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for ceramic heat exchanger commercialization would alter the outlook. Forecasts reflect assumptions regarding nickel alloy price stability and enameling technician training pipeline expansion. Practitioners should monitor ECHA authorization timelines and Indonesian smelter output fluctuations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Deaerators Market
Power Equipment
India Power EPC Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
North America Gas Turbine Market
Power Equipment
US Power EPC Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
Romania Power EPC Market
Power Equipment
Europe Power Rental Market
Power Equipment
Australia Power EPC Market