
 North America Oil Filled Electric Heaters Market | 2026-2036
North America Oil Filled Electric Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil Filled Electric Heaters Market Analytics
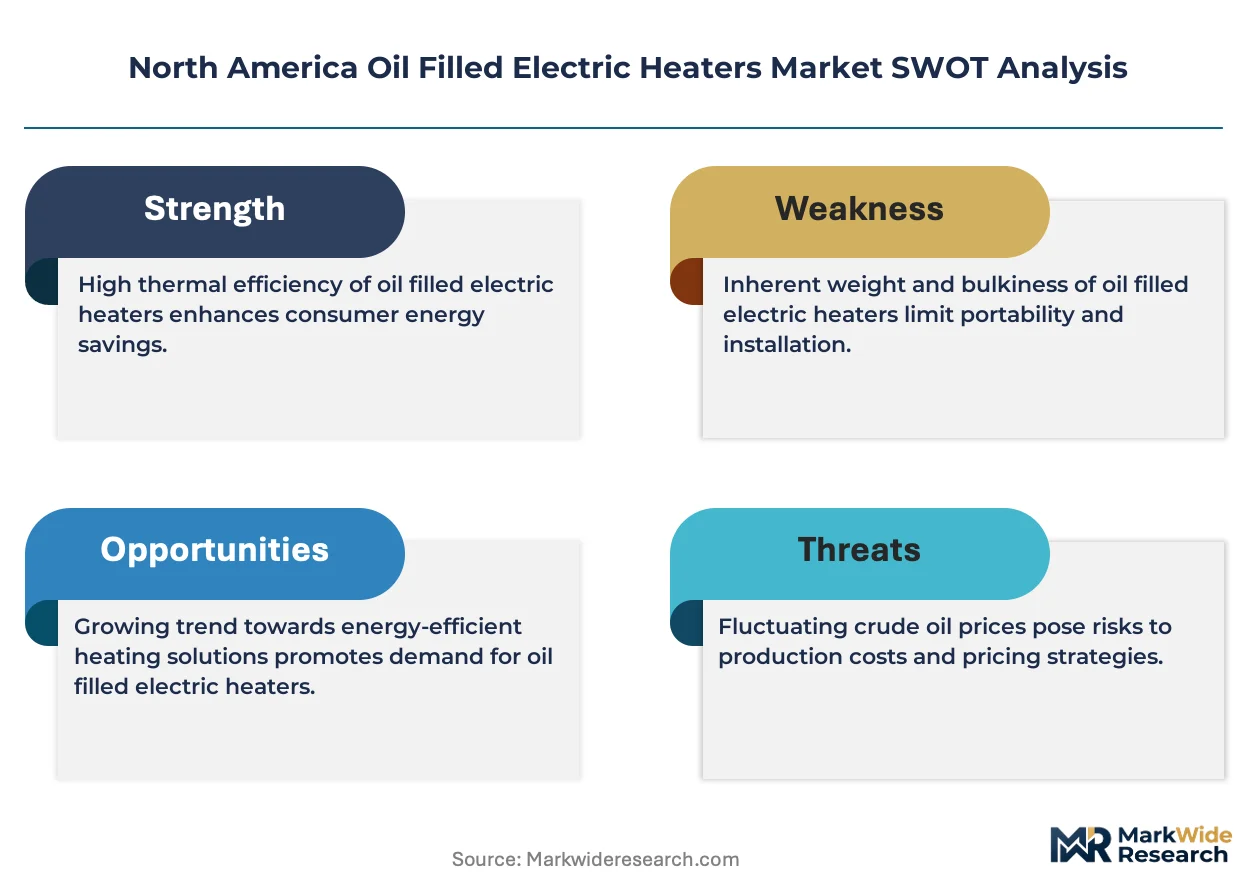
The gap between premium and commodity tiers is broadening as thermal efficiency certification and smart connectivity separate high-margin products from basic convection units. Honeywell International Inc. leverages its controls heritage to dominate the smart thermostat-integrated segment. Glen Dimplex Group anchors its position through captive manufacturing of heating elements and die-cast aluminum radiators. De'Longhi Appliances S.r.l. differentiates via European design positioning and oil-cell construction optimized for silent operation.
North America oil filled electric heaters are sealed thermal mass devices utilizing diathermic oil as a heat transfer medium, where electric resistance elements warm the fluid to radiate infrared heat through finned steel or aluminum housings without combustion or forced airflow. The primary purpose is zone-level space heating in residential and light commercial environments where central HVAC extension proves uneconomical or where supplemental warmth addresses cold spots. Convection heaters occupy the volume base as the default architectural choice for permanent residential installation. Smart control types capture expanding margin pools as Wi-Fi-enabled scheduling and utility demand-response integration command price premiums over manual dial interfaces. The 1500W power rating segment sustains the largest installed base, matching standard North American branch circuit capacity limits.
US Department of Energy appliance efficiency standards and Canadian NRCan regulations jointly dictate minimum heat output-to-wattage ratios and standby power thresholds, compressing margins for non-compliant imports while rewarding certified domestic assembly. UL 1278 safety standards for movable and wall- or ceiling-hung electric room heaters govern tip-over shutoff and surface temperature limits, creating compliance barriers for new market entrants. Stakeholders must monitor state-level building electrification mandates and utility rebate program designs that selectively favor heat pump technology over resistive electric heating, reshaping long-term demand composition across the region.
Market Dynamics
The US Department of Energy's evolving appliance efficiency standards are compressing margins for legacy convection units while rewarding certified thermal performance, reshaping competitive positioning across the value chain.
Growth Catalysts
- Retrofit-driven replacement cycles:Aging natural gas distribution infrastructure in cold-climate housing stock across the US Northeast and Upper Midwest accelerates electric heating substitution for zone-level warmth.
- Utility demand-response integration:Wi-Fi-enabled scheduling capabilities align with FERC Order 2222 implementation, creating revenue streams for grid-interactive thermal mass devices.
- Canadian NRCan efficiency regulations:Minimum heat output-to-wattage ratios elevate certified domestic assembly over non-compliant imports, protecting incumbent manufacturing bases.
Market Restraints
- Input cost volatility in die-cast aluminum:Thermal housing material prices fluctuate with energy-intensive smelting economics, squeezing radiator production margins.
- Substitution threat from cold-climate heat pumps:Building electrification mandates in Vermont, Massachusetts, and New York selectively favor compressor-based systems over resistive heating.
- UL 1278 compliance barriers:Tip-over shutoff and surface temperature testing requirements extend certification timelines for new market entrants.
Strategic Opportunities
- Smart thermostat convergence:Integration with connected home ecosystems opens premium pricing pools beyond manual dial interfaces.
- Underpenetrated Canadian Prairie provinces:Manitoba and Saskatchewan rural electrification gaps present white space for supplemental zone heating deployment.
- State-level rebate program designs:California and Washington utility incentive structures reward thermal mass storage for grid flexibility services.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for demand-response protocols competes with broader HVAC and appliance sectors.
- Legacy housing electrical capacity constraints:Pre-1970s residential branch circuits limit 1500W unit penetration without panel upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil Filled Electric Heaters Market |
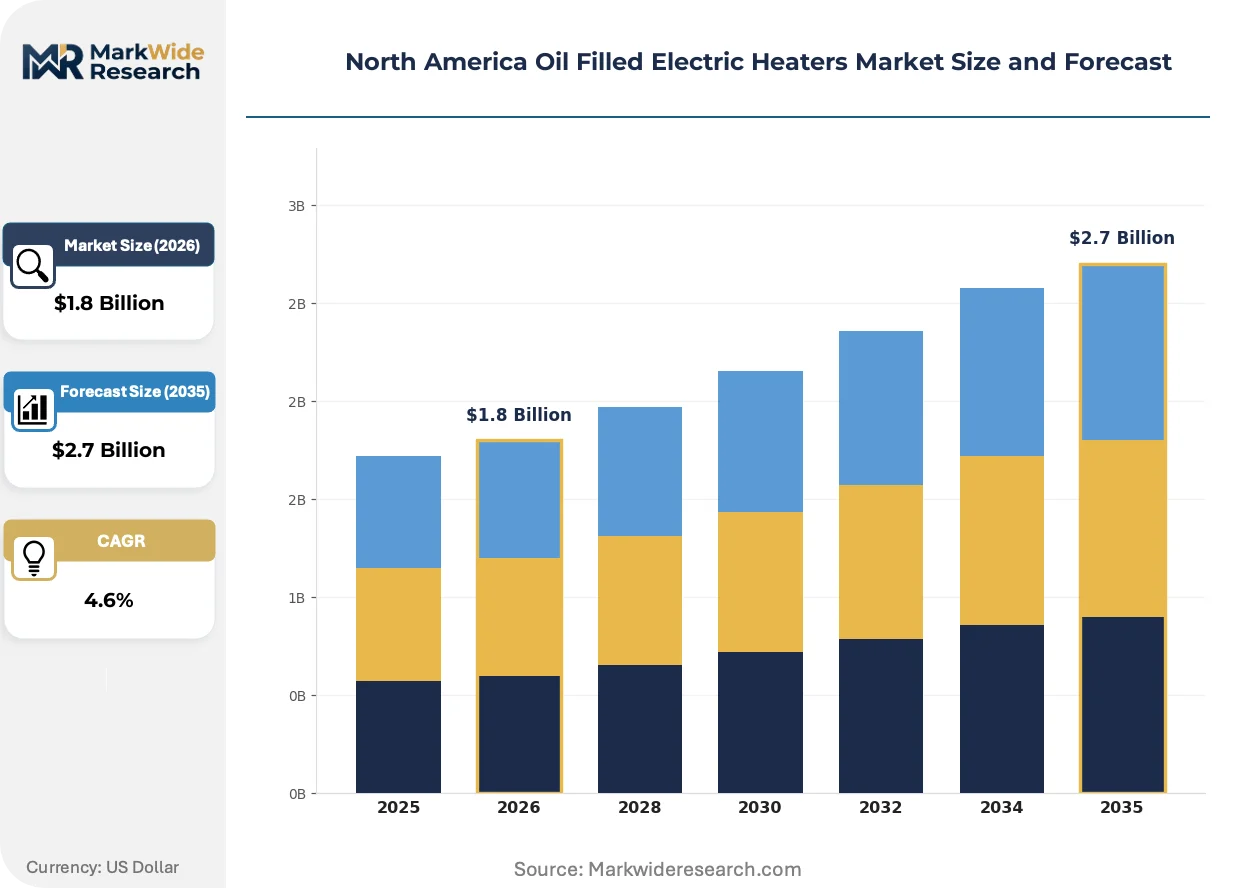
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiant Heaters, Convection Heaters, Fan Heaters, Infrared Heaters End User: Residential, Commercial, Industrial, Institutional Power Rating: 750W, 1500W, 2000W, 2500W Control Type: Manual, Thermostat, Remote Control, Smart |
| Companies Covered | Costway, Runtal North America Inc., Purmo USA, Honeywell International Inc., De'Longhi Appliances S.r.l., Lasko Products, LLC, Newell Brands Inc., Glen Dimplex Group, Pelonis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil Filled Electric Heaters Market Evolving Landscape
Product architecture is bifurcating between connected, efficiency-certified premium tiers and commodity convection units, with thermal performance transparency becoming the primary purchase determinant.
Diathermic oil-cell construction optimized for silent operation is electrifying residential bedroom and home office applications where acoustic comfort outweighs rapid heat-up speed. Multi-generational households and remote workers prioritize noise reduction over forced-air alternatives. This thermal mass approach is compressing market share for fan-assisted ceramic competitors in sleep-critical environments.
The US Department of Energy's amended appliance efficiency standards tighten minimum heat output-to-wattage ratios and standby power thresholds. Manufacturers must redesign resistance element geometry and control board power management to maintain market access. The 1500W segment faces the steepest compliance curve, with redesign costs concentrated among import-dependent distributors.
Buyer preference is rotating toward thermal efficiency certification labels as primary selection criteria over brand heritage or aesthetic design. Retail channel assortments are rebalancing toward NRCan and ENERGY STAR qualified SKUs. This behavioral shift is most visible in the US Northeast, where heating season energy costs drive total cost of ownership calculations ahead of upfront purchase price.
North America Oil Filled Electric Heaters Market Segmentation
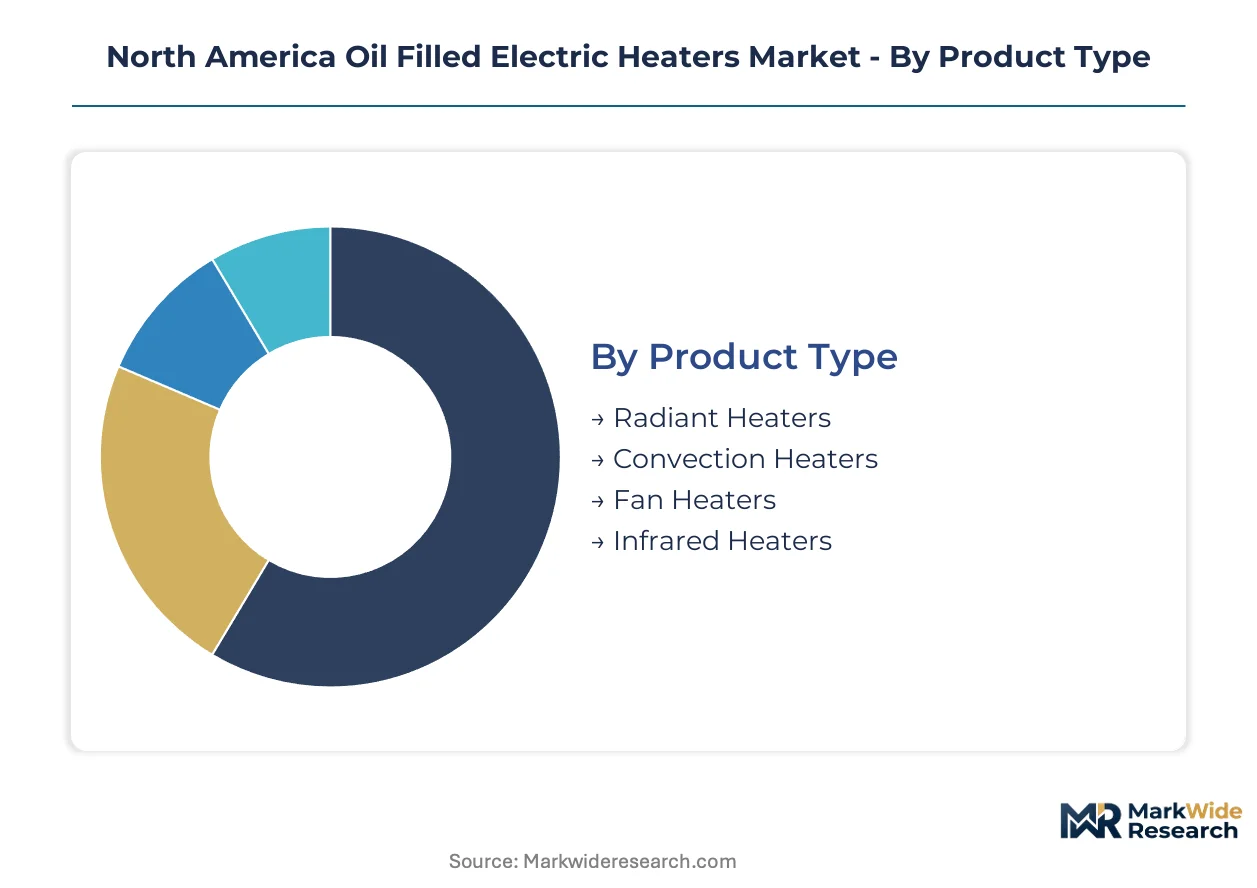
Oil filled electric heaters serve distinct thermal mass applications across North America, with product architecture and control sophistication driving margin stratification. Segment boundaries reflect divergent buyer priorities: silent operation for residential bedrooms versus rapid zone heating for commercial workspaces.
Product Type:
Volume concentration favors convection architectures, while premium capture belongs to radiant and connected variants.
- Convection Heaters:Finned steel or aluminum housings circulate warmed diathermic oil through natural convection currents without forced airflow. Demand concentrates in permanent residential installations across the US Northeast, where aging natural gas infrastructure accelerates electric heating substitution for supplemental zone warmth.
- Radiant Heaters:Optimized oil-cell construction maximizes infrared heat emission through surface area engineering. Deployment is expanding in Minnesota and Wisconsin multi-generational households, where acoustic comfort priorities displace fan-assisted ceramic alternatives in sleep-critical environments.
- Fan Heaters:Hybrid designs incorporate forced-air acceleration for rapid heat-up speed.
- Infrared Heaters:Targeted radiant panels address spot-heating applications in commercial settings.
Mature deployment sits with Convection Heaters. Newer deployment is concentrated in Radiant Heaters.
End User:
Residential retrofit activity dominates unit volume, though commercial and institutional segments command superior pricing power.
- Residential:Zone-level space heating in single-family homes and apartments where central HVAC extension proves uneconomical. Cold-climate housing stock across New York, Pennsylvania, and Michigan drives replacement cycles as natural gas distribution infrastructure ages.
- Commercial:Supplemental warmth for retail spaces, small offices, and hospitality environments. Demand clusters in Massachusetts and Vermont, where building electrification mandates selectively favor compressor-based systems but leave resistive heating viable for targeted applications.
- Industrial:Spot heating for workshops, warehouses, and loading docks.
- Institutional:Schools, healthcare clinics, and municipal facilities requiring code-compliant thermal solutions.
Volume leadership resides with Residential. Margin expansion is accelerating in Commercial.
Power Rating:
Circuit capacity constraints shape the installed base, with standard branch limits creating a ceiling for mainstream adoption.
- 1500W:Matches standard North American residential branch circuit capacity limits, sustaining the largest installed base. US Department of Energy amended appliance efficiency standards impose the steepest compliance curve here, forcing resistance element geometry redesigns.
- 750W:Compact units for bedroom and home office applications where thermal mass storage suits intermittent occupancy patterns. Canadian Prairie provinces present white space as rural electrification gaps persist in Manitoba and Saskatchewan.
- 2000W:Requires dedicated 20A circuits, limiting penetration in pre-1970s housing stock.
- 2500W:Commercial and light industrial applications with upgraded electrical infrastructure.
Installed base concentration sits with 1500W. Emerging deployment is climbing fastest in 750W.
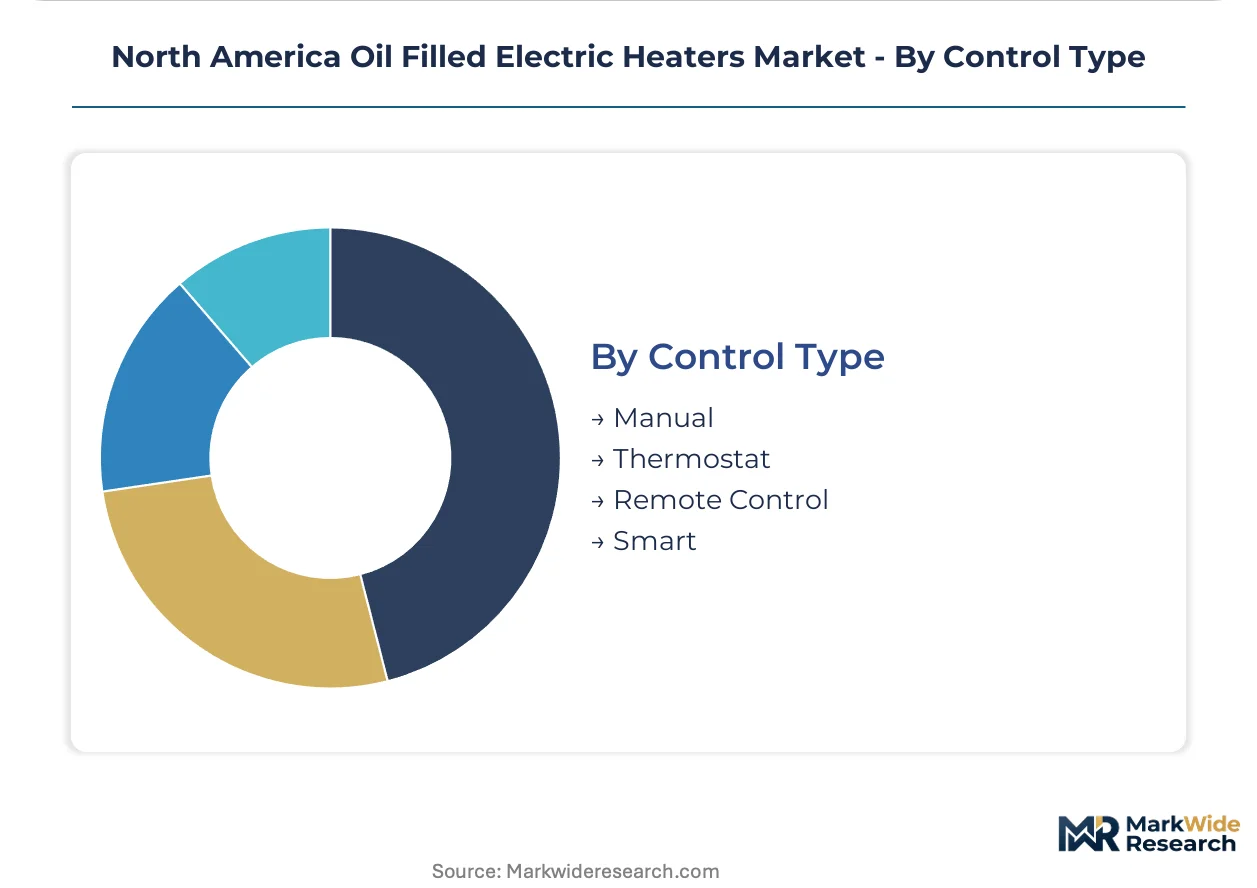
Control Type:
Interface sophistication separates commodity margin pools from premium pricing tiers.
- Smart:Wi-Fi-enabled scheduling and utility demand-response integration align with FERC Order 2222 implementation. California and Washington utility incentive structures reward thermal mass storage for grid flexibility services, creating revenue streams beyond hardware margins.
- Thermostat:Digital temperature maintenance with programmable setpoints. Demand concentrates in the US Upper Midwest, where heating season energy costs drive total cost of ownership calculations ahead of upfront purchase price.
- Manual:Dial interfaces dominate entry-level SKUs.
- Remote Control:Handheld convenience for hard-to-reach installations.
Legacy dominance sits with Manual. Technology transition is accelerating in Smart.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Northeast corridor from Boston to Philadelphia anchors regional demand, where aging row-house stock and century-old natural gas distribution infrastructure accelerate electric heating substitution for supplemental zone warmth.
United States
Cold-climate housing stock across New York, Pennsylvania, and Michigan drives replacement cycles as homeowners seek alternatives to aging natural gas infrastructure. The US Department of Energy's amended appliance efficiency standards compress margins for non-compliant imports while rewarding certified domestic assembly. Massachusetts and Vermont building electrification mandates selectively favor compressor-based systems but leave resistive heating viable for targeted zone applications.
Canada
Rural electrification gaps persist across Manitoba and Saskatchewan, presenting white space for supplemental 750W zone heating deployment in farmsteads and remote communities. Natural Resources Canada efficiency regulations elevate certified domestic assembly over non-compliant imports through minimum heat output-to-wattage ratios. Ontario and Quebec manufacturing bases benefit from NRCan compliance barriers that protect incumbent producers.
Mexico
High-altitude population centers including Mexico City and Toluca experience sustained demand for electric heating as alternatives to liquefied petroleum gas systems. The country's national energy regulator monitors appliance efficiency standards alignment with North American trade integration. Northern border states concentrate distribution infrastructure serving cross-border retail channels.
North America Oil Filled Electric Heaters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal efficiency certification and smart connectivity integration. The vendor base stratifies between controls-heritage conglomerates, captive-manufacturing specialists, and design-forward European exporters. Three archetypes dominate: integrated smart-home platform providers, vertically integrated heating element fabricators, and European design-positioned premium brands. Competitive moves concentrate on thermostat ecosystem convergence and die-cast aluminum radiator capacity expansion.
Within the controls-heritage tier, Honeywell International Inc. and Glen Dimplex Group exemplify divergent strategic positions. Honeywell leverages its building automation legacy to anchor smart thermostat-integrated offerings. Glen Dimplex occupies a manufacturing-specialist position through captive production of heating elements and thermal housings. De'Longhi Appliances S.r.l. represents the European design-export archetype, with its S.r.l. structure signaling Italian corporate form.
| Leading Market Players |
|---|
| Costway |
| Runtal North America Inc. |
| Purmo USA |
| Honeywell International Inc. |
| De'Longhi Appliances S.r.l. |
| Lasko Products, LLC |
| Newell Brands Inc. |
| Glen Dimplex Group |
| Pelonis |
| Others |
Value Network & Pricing Analysis
Embedded systems engineering talent scarcity in Shenzhen and Taipei widens cost differentials between smart-connected premium tiers and manual-dial commodity units, compressing margin spreads for distributors dependent on import assembly.
Pricing Analysis
Thermal efficiency certification anchors value-based pricing, with ENERGY STAR and NRCan qualification commanding 15-25% premiums over uncertified equivalents. Price differentiation stems from smart connectivity integration and die-cast aluminum radiator quality grades. Cost compression in the 1500W segment intensifies as US Department of Energy efficiency standards force resistance element redesigns. Residential retrofit buyers in the US Northeast exhibit lowest price sensitivity due to heating season energy cost calculations, while mass-market retailers face highest sensitivity.
Supply Chain Analysis
Die-cast aluminum supply rests on Chinese smelting capacity and Canadian secondary processing, with diathermic oil sourcing concentrated in German and Belgian specialty chemical producers. Critical dependencies include heating element wire from Japanese and South Korean metallurgical suppliers, plus control board semiconductors from Taiwanese foundries. Single-source vulnerability in Wi-Fi module supply creates bottlenecks for smart-enabled SKU ramp-ups. Distribution runs through big-box retail chains in the US and Canadian Prairie province electrical cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with captive manufacturing of heating elements and thermal housings emerging as the decisive margin-defense lever.
For Market Incumbents: To counter cold-climate heat pump substitution threats in Vermont and Massachusetts, deepen backward integration into die-cast aluminum radiator production and secure UL 1278 pre-certified component platforms. Prioritize smart thermostat ecosystem partnerships to lock in premium pricing pools before connectivity becomes table stakes. For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels offer the lowest friction entry path into underpenetrated Canadian Prairie provinces, where Manitoba and Saskatchewan rural electrification gaps persist. Target 750W bedroom and home office segments with silent-operation oil-cell construction, leveraging acoustic comfort priorities that displace fan-assisted ceramic alternatives. For Investors and Strategic Acquirers: The window for entry favors vertically integrated manufacturing specialists with captive heating element and thermal housing capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch state-level building electrification mandate expansions beyond current Vermont, Massachusetts, and New York boundaries as the primary demand-composition inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive production of resistance wire and die-cast housings protects margins against aluminum price volatility. |
| Smart Thermostat Ecosystem Partnership | Honeywell and Google Nest integration opens premium pricing pools beyond manual dial commodity tiers. |
| Canadian Prairie Distribution Expansion | Manitoba and Saskatchewan rural electrification gaps present white space for 750W supplemental zone heating. |
| ENERGY STAR Certification Investment | NRCan and DOE compliance barriers protect domestic assembly against non-compliant import competition. |
| Demand-Response Firmware Development | FERC Order 2222 alignment creates grid flexibility revenue streams beyond hardware margins in California and Washington. |
Research Methodology
Independent corroboration across plant managers at die-cast aluminum foundries, procurement leads at heating element OEMs, and channel partners at North American electrical distributors underwrites the qualitative findings. Primary interviews with utility demand-response program officers and regulatory affairs specialists at appliance manufacturers were validated against secondary sources including US Department of Energy appliance efficiency filings, Natural Resources Canada technical bulletins, and FERC Order 2222 implementation dockets. Bottom-up unit shipment estimates triangulate with top-down energy consumption models across the projection horizon.
Rate-of-change decomposition separates retrofit-driven replacement cycles from new construction penetration, with segmentation modeling across product type, control sophistication, power rating, and end-use application. CAGRs derive from regression analysis of historical efficiency standard impacts and utility rebate program uptake curves. Key forecast inputs include state-level building electrification mandate timelines and Canadian Prairie province rural electrification gap closure projections.
Inputs from DOE certification databases and NRCan registered product listings were available through the study window; gaps in real-time utility rebate program enrollment data introduce uncertainty bands around demand-response integration adoption curves. Forecasts reflect documented assumptions regarding efficiency standard implementation timelines and aluminum smelting capacity utilization. A small set of triggers—state electrification mandate expansions, FERC demand-response rulemakings, and die-cast aluminum tariff adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Overhead Aluminium Conductors Market