
 Turbine Governor Market | 2026-2036
Turbine Governor Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Governor Market Analytics
A widening capability gap between integrated energy conglomerates and component specialists is reorganizing competitive dynamics in the turbine governor space. General Electric leverages its captive power generation installed base to bundle governor upgrades with turbine overhauls. Woodward Inc sustains technology leadership in hydro-specific electronic governors through dedicated R&D facilities. ABB anchors its position in European markets with IEC-compliant digital control platforms.
A turbine governor is a closed-loop control device that modulates fuel, steam, or water flow to maintain rotational speed within ±0.1% of setpoint despite load fluctuations. Its primary industrial purpose is protecting rotating machinery from overspeed damage while stabilizing grid frequency in synchronous generator applications. Electronic governors now command the dominant margin pool as utilities replace mechanical flyball actuators with sensor-driven digital architectures. Smart control systems represent the fastest-expanding technology category, though analog control persists in marine and remote industrial settings where electromagnetic resilience outweighs precision demands.
Grid interconnection standards from IEEE and IEC shape product certification requirements, while national regulators including FERC in the United States and CEA in India mandate specific frequency response capabilities for generators above defined capacity thresholds. Compliance with evolving cybersecurity frameworks for operational technology networks is becoming a non-negotiable qualification criterion for utility procurement. Stakeholders must monitor whether emerging grid-forming inverter standards will redefine governor functionality requirements in hybrid power plants.
Market Dynamics
Digital control architectures are displacing mechanical flyball governors across utility-scale installations, while grid code harmonization between IEEE and IEC standards compresses product development cycles for multinational suppliers.
Growth Catalysts
- Grid Code Mandates:Frequency response obligations under FERC Order 842 in the United States and CEA technical standards in India compel generator retrofits with electronic governor systems.
- Hydropower Modernization:State-owned utilities in China are retrofitting aging turbine fleets with sensor-driven digital control platforms to extend asset life.
- Combined-Cycle Expansion:Power developers specify electronic governors for new gas turbine installations to achieve sub-0.1% speed regulation precision.
Market Restraints
- Semiconductor Supply Concentration:Discrete component sourcing from East Asian foundries creates lead time volatility for digital governor manufacturers.
- Legacy System Entrenchment:Mechanical governor installed base in marine propulsion and remote industrial sites resists replacement due to electromagnetic resilience requirements.
- Cybersecurity Compliance Burden:Evolving NERC CIP standards for operational technology networks extend qualification timelines and inflate engineering costs.
Strategic Opportunities
- Grid-Forming Inverter Convergence:Hybrid power plant architectures create demand for governors synchronized with battery energy storage control systems.
- Remote Monitoring Services:Cloud-based predictive maintenance platforms offer recurring revenue streams beyond hardware sales to utility operators.
- European Green Deal Alignment:Efficiency upgrade incentives for existing hydropower assets under EU funding mechanisms accelerate replacement cycles.
Industry Challenges
- Control Systems Engineering Talent:Shortage of specialists fluent in both turbine thermodynamics and embedded software development constrains R&D throughput.
- Multi-Standard Certification Complexity:Simultaneous compliance with IEC 61508 functional safety and IEEE 1547 interconnection standards fragments testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Governor Market |
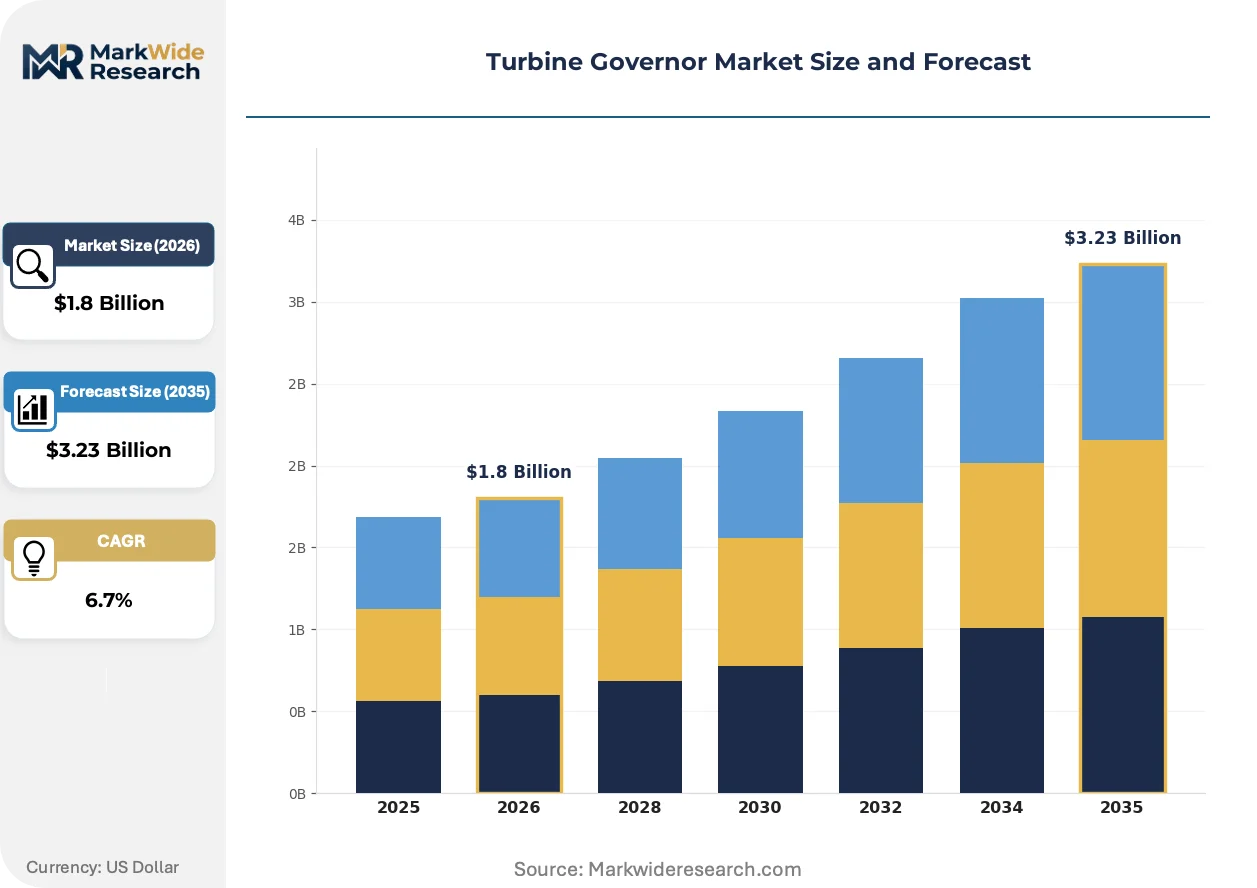
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Governors, Electronic Governors, Mechanical Governors, Pneumatic Governors End User: Power Plants, Industrial Applications, Renewable Energy Facilities, Marine Vessels Technology: Smart Control Systems, Analog Control, Digital Control, Adaptive Control Application: Steam Turbines, Gas Turbines, Hydro Turbines, Wind Turbines |
| Companies Covered | General Electric, Woodward Inc, ABB, Voith Group, Siemens Energy, Emerson Electric Co, Honeywell International Inc, Andritz Hydro, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Governor Market Evolving Landscape
Model-predictive control algorithms and edge computing architectures are redefining governor response characteristics. Hardware-software integration now determines competitive differentiation more than mechanical precision alone.
Adaptive gain scheduling based on machine learning inference is displacing fixed-parameter PID control in large-frame steam turbine applications. Combined-cycle operators in North America and Western Europe are piloting these systems to manage load ramp rates exceeding 5% per minute. The technology is displacing conventional governor tuning services as a recurring revenue category for control system vendors.
The European Union's Cyber Resilience Act imposes mandatory security update obligations on operational technology products placed on the EU market. Manufacturers must maintain vulnerability disclosure programs and provide security patch support for defined product lifecycles. Digital governor suppliers with European utility exposure are restructuring software development workflows to satisfy these traceability requirements.
Utility procurement teams are unbundling governor hardware from long-term service agreements that historically bundled spare parts and field engineering. Independent service providers are capturing aftermarket maintenance contracts through specialized hydro turbine expertise. This pattern is most pronounced in Nordic hydropower markets where asset ownership concentrates among pension fund infrastructure vehicles with aggressive opex reduction targets.
Turbine Governor Market Segmentation
Turbine governor procurement channels diverge sharply by product maturity and end-use technical requirements. OEM-direct sales dominate new power plant construction, while aftermarket retrofit flows through specialized distributors and system integrators with regional field engineering capabilities.
Product Type:
Channel mix varies by actuator technology—electronic governors move through certified system integrators, while mechanical units persist in marine supply chains with legacy parts networks.
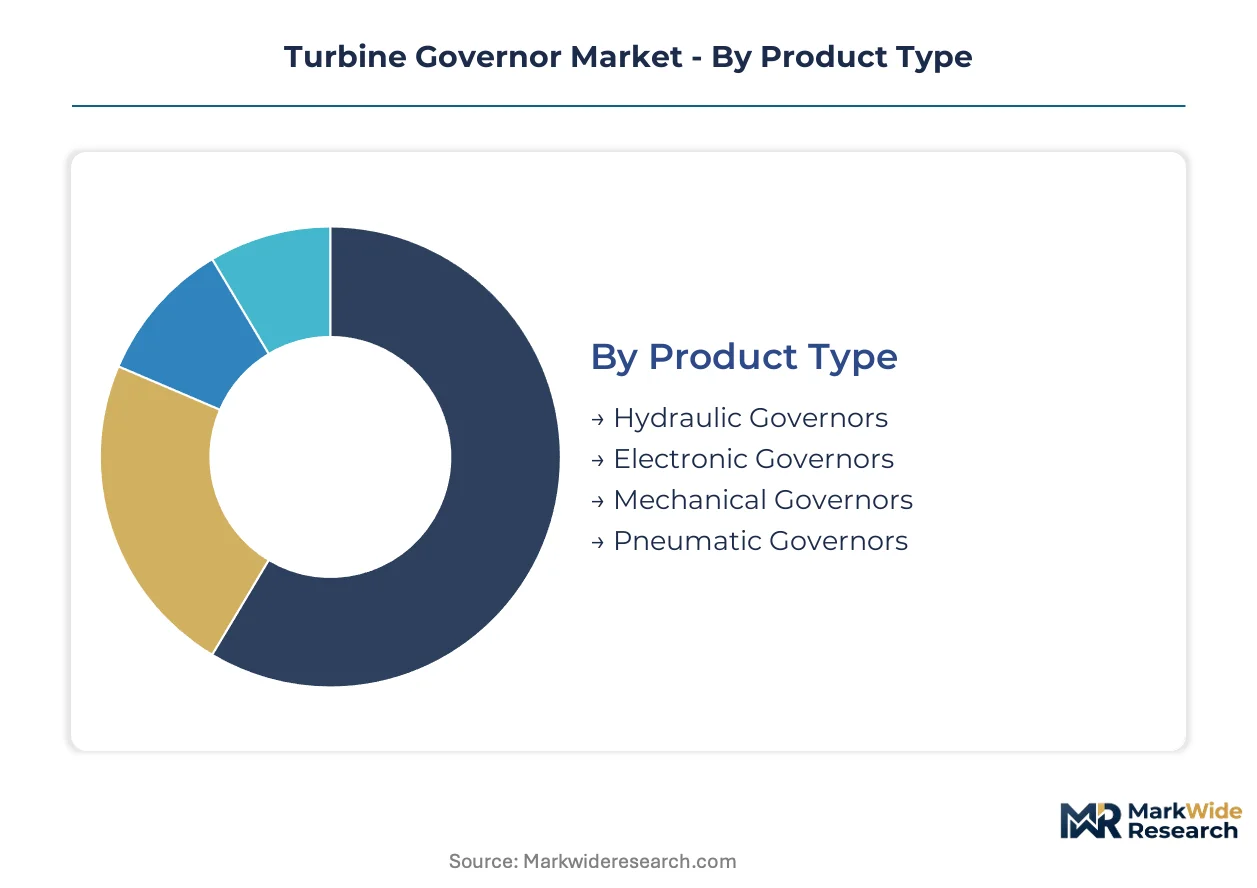
- Electronic Governors:Sensor-driven architectures with microprocessor-based PID algorithms enable ±0.1% speed regulation precision. Demand concentrates in Chinese state-owned utility retrofits and North American combined-cycle expansions where FERC Order 842 mandates frequency response capabilities.
- Hydraulic Governors:Fluid-power actuation systems with pilot-operated control valves serve large-frame steam turbines in baseload coal and nuclear installations. European hydropower operators under EU Green Deal efficiency incentives favor these units for turbine life extension projects.
- Mechanical Governors:Centrifugal flyball mechanisms persist in marine propulsion and remote industrial sites where electromagnetic resilience outweighs precision demands.
- Pneumatic Governors:Compressed-air actuation systems retain niche deployment in hazardous environment applications with intrinsic safety requirements.
Mechanical governors dominate installed base. Electronic governors are where expansion concentrates.
End User:
Cost tier stratification separates specification-grade utility procurement from price-sensitive industrial sourcing.
- Power Plants:Utility-scale generators above 50MW capacity specify IEC 61508-compliant digital platforms with cybersecurity certification. Indian central electricity authority technical standards and German grid codes drive replacement cycles in these accounts.
- Industrial Applications:Cogeneration facilities and process steam users prioritize total cost of ownership over precision, sourcing analog or first-generation electronic governors through regional distributors.
- Renewable Energy Facilities:Hybrid solar-storage and wind-hydro sites require governors synchronized with grid-forming inverter control systems.
- Marine Vessels:Classification society rules and electromagnetic compatibility requirements sustain demand for pneumatic and mechanical architectures in propulsion and auxiliary power units.
Power plants anchor revenue concentration. Renewable energy facilities are climbing the fastest.
Technology:
Application context determines control architecture selection—precision requirements versus environmental resilience.
- Digital Control:Microprocessor-based platforms with deterministic real-time operating systems command utility procurement. Chinese hydropower modernization and Indian grid compliance mandates accelerate displacement of analog predecessors.
- Smart Control Systems:Edge computing architectures with model-predictive algorithms and cloud connectivity enable predictive maintenance revenue streams. North American combined-cycle operators pilot these for load ramp rates exceeding 5% per minute.
- Analog Control:Hard-wired electronic circuits without software components persist in marine and defense applications where cybersecurity attack surface minimization takes priority.
- Adaptive Control:Machine learning inference engines with gain scheduling automation represent emerging specification in large-frame steam turbine retrofits.
Digital control holds dominant share. Smart control systems show steepest expansion trajectory.
Application:
Volume concentration tracks turbine technology lifecycle—mature steam versus expanding gas and hydro.
- Gas Turbines:Combined-cycle and simple-cycle peaking units require sub-0.1% speed regulation for grid stabilization. Procurement concentrates in power developers specifying electronic governors for new installations.
- Hydro Turbines:Kaplan, Francis, and Pelton turbine configurations in run-of-river and reservoir installations. Nordic pension fund infrastructure vehicles and Chinese state-owned utilities drive aftermarket demand with aggressive opex reduction targets.
- Steam Turbines:Fossil and nuclear baseload units with established mechanical and hydraulic governor installed base. Replacement cycles extend due to asset life amortization and regulatory grandfathering provisions.
- Wind Turbines:Pitch and yaw control systems in variable-speed generators with power electronics-based speed regulation. Governor functionality converges with turbine converter control architecture.
Steam turbines dominate installed base. Gas turbines concentrate new order flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Chinese utilities prioritize digital retrofits for aging hydropower assets, while North American developers specify electronic governors for new gas turbine installations. European operators under efficiency mandates favor hydraulic systems for turbine life extension.
United States
FERC Order 842 mandates frequency response capabilities for generators above defined capacity thresholds, compelling widespread governor retrofits. Combined-cycle power developers in Texas and the Mid-Atlantic specify electronic governors for new installations to achieve sub-0.1% speed regulation. The Electric Reliability Council of Texas manages grid stability requirements that shape procurement specifications.
Germany
National grid codes tighten frequency response obligations for synchronous generators, accelerating displacement of mechanical flyball systems. The Bundesnetzagentur enforces compliance timelines that compress vendor qualification cycles. Industrial clusters in North Rhine-Westphalia concentrate aftermarket service demand from pension fund-owned hydropower assets.
China
State-owned utilities execute large-scale retrofits of 1960s-1980s hydropower fleets with sensor-driven digital control platforms. The National Energy Administration coordinates modernization programs across provincial grid companies. The Yangtze River Delta hosts concentrated manufacturing capacity for electronic governor components serving domestic and export markets.
India
Central Electricity Authority technical standards mandate specific frequency response capabilities for utility-scale generators above 50MW. Thermal power developers in Gujarat and Maharashtra specify IEC-compliant digital governors for new supercritical coal units. State transmission utilities in Tamil Nadu and Karnataka drive replacement cycles through grid code enforcement.
Norway
Pension fund infrastructure vehicles with aggressive opex reduction targets unbundle governor hardware from long-term service agreements. The Norwegian Water Resources and Energy Directorate oversees technical standards for run-of-river and reservoir installations. Nordic hydropower clusters concentrate independent service provider activity for aftermarket maintenance contracts.
Turbine Governor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the turbine governor market. General Electric leverages captive power generation installed base to bundle governor upgrades with turbine overhauls. Woodward Inc sustains technology leadership in hydro-specific applications through dedicated R&D facilities. Three archetypes dominate: diversified energy conglomerates with captive aftermarket channels, control system specialists with vertical technology depth, and regional fabricators serving price-sensitive industrial segments. Competitive moves concentrate on strategic partnerships for grid-forming inverter convergence and geographic expansion through certified system integrator networks.
Within the integrated conglomerate tier, General Electric and Siemens Energy exemplify players leveraging turbine manufacturing heritage to capture governor retrofit demand. Woodward Inc and Voith Group occupy positions as technology specialists with concentrated expertise in hydro and rotating machinery control. Among diversified industrial technology providers, ABB and Emerson Electric Co. anchor European and North American market presence through IEC-compliant digital platforms and process automation integration capabilities.
| Leading Market Players |
|---|
| General Electric |
| Woodward Inc |
| ABB |
| Voith Group |
| Siemens Energy |
| Emerson Electric Co |
| Honeywell International Inc |
| Andritz Hydro |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
Component-scale economies in East Asian semiconductor foundries anchor cost structures for digital governor manufacturers, compressing price floors for sensor-driven architectures while amplifying margin pressure on second-tier assemblers lacking captive chip sourcing. Chinese state-owned utilities and North American combined-cycle developers exploit this concentration through volume procurement contracts that extract tiered performance guarantees.
Pricing Analysis
After-sales service contracts and remote monitoring subscriptions now drive lifetime value capture across utility accounts, displacing transactional hardware margins. Pricing stratifies across IEC 61508-certified premium tiers, standard digital platforms, and economy-grade analog units for marine applications. Cost compression in standard electronic tiers intensifies as Chinese system integrators enter European markets with state-backed financing. Industrial cogeneration facilities exhibit highest price sensitivity, while utility-scale power plants prioritize cybersecurity certification over unit cost.
Supply Chain Analysis
Taiwan Strait transit routes for advanced microprocessors and South Korean memory module shipments constitute critical chokepoints for digital governor production timelines. Manufacturing draws from China for power electronics assembly, Germany for precision hydraulic components, and Japan for industrial-grade sensors. Single-source vulnerability concentrates in automotive-grade microcontroller supply from Renesas and NXP fabrication networks. Distribution runs through certified system integrators with FERC and CEA qualification credentials, bypassing traditional industrial distributors for utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The turbine governor market is entering a cyclical recovery phase as FERC Order 842 compliance deadlines and Chinese hydropower modernization programs synchronize replacement waves. Asset life extension mandates and grid code harmonization between IEEE and IEC standards are compressing procurement cycles.
For Market Incumbents: Secure captive semiconductor supply through long-term foundry agreements to insulate margin structures from East Asian lead time volatility. Deepen backward integration into edge computing hardware for smart governor architectures, as machine learning inference capabilities differentiate premium tiers from commoditized PID control platforms.
For New Entrants and Emerging Players: Predictive maintenance software layers for existing hydraulic governor installed base represent underserved white space where incumbents under-serve Nordic hydropower operators. Target Norwegian pension fund infrastructure vehicles with unbundled service contracts, leveraging specialized hydro turbine expertise against conglomerate bundled offerings.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among control system specialists with dedicated hydro R&D facilities and established utility service relationships. Long-term viability hinges on cybersecurity certification depth and grid-forming inverter convergence capabilities. Monitor NERC CIP enforcement intensity as inflection indicator for qualification cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | NERC CIP compliance separates qualified vendors from disqualified bidders in FERC-regulated auctions. |
| Grid-Forming Inverter Partnership | Hybrid power plant architectures demand synchronized governor-battery control under ERCOT and CAISO protocols. |
| Remote Monitoring Platform Launch | Cloud-based predictive maintenance captures recurring revenue from Nordic pension fund infrastructure vehicles. |
| East Asian Foundry Agreement | Long-term semiconductor supply contracts insulate margin structures from Taiwan Strait logistics volatility. |
| Hydro-Specific R&D Expansion | Dedicated facilities for Kaplan and Francis turbine control sustain technology leadership against diversified conglomerates. |
Research Methodology
Operator-level perspectives from utility planning officers, EPC contractors, aftermarket service heads, and grid operators anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through FERC filings, EIA generator databases, CEA technical standards documentation, and IEC certification registries. Bottom-up unit economics for electronic, hydraulic, and mechanical governor categories were triangulated against top-down market sizing from power plant retrofit databases and new build project pipelines.
Sensitivity analysis across semiconductor price volatility scenarios and grid code compliance timeline variations shaped the projection framework. Segmentation dimensions modeled include actuator technology, control architecture, turbine application, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new order flow trajectories, with specific inputs from Chinese hydropower modernization program disclosures and North American combined-cycle expansion permits.
Forecasts assume regulatory continuity in FERC Order 842 enforcement, CEA technical standard adherence, and EU Cyber Resilience Act implementation timelines; material policy shifts would require re-modeling of replacement cycle assumptions and qualification cost structures. Practitioners should keep alternative scenarios live as grid-forming inverter standardization and NERC CIP revision schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Global Power Supply Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Middle East Power Filter Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
Australia Power EPC Market