
 Global Power System Simulator Market | 2026-2036
Global Power System Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power System Simulator Market Foresight
Power systems engineering talent is collapsing across North American utilities, forcing grid operators to outsource complex transient stability modeling to specialized vendors. Siemens leverages its hardware-in-the-loop manufacturing depth to dominate European real-time simulator deployments for offshore wind interconnection. ABB anchors its position through integrated software-hardware bundles that reduce commissioning cycles for protective relay testing laboratories. OPAL-RT TECHNOLOGIES, Inc. competes by specializing in FPGA-based emulation architectures that cut simulation latency for microgrid controller validation.
Power system simulators are computational platforms that replicate electrical grid behavior through mathematical modeling of generation, transmission, and load dynamics, typically executing power flow algorithms with time-step resolutions ranging from microseconds to seconds depending on emulation fidelity. Their primary purpose is to de-risk infrastructure decisions by enabling offline testing of control strategies, fault responses, and renewable integration scenarios before capital deployment. Hardware-in-the-Loop technology leads in margin contribution due to specialized FPGA and processor requirements, while Cloud-Based Simulation is expanding fastest among energy consultants seeking elastic compute for probabilistic load forecasting. Real-Time Simulator demand concentrates with transmission operators managing inverter-dominated grids, whereas Offline Simulator adoption remains mature among university research laboratories prioritizing cost over speed.
FERC Order 2222 and the EPA's greenhouse gas performance standards are reshaping procurement criteria for U.S. grid operators, mandating simulator-validated interoperability before distributed energy resource aggregation. The EU Green Deal's network code on requirements for generators, enforced by national regulators, compels European utilities to demonstrate fault-ride-through compliance using certified real-time emulation platforms. ISO and IEC standards for cyber-physical power system testing are becoming de facto market access requirements across multiple jurisdictions. Stakeholders must decide whether to build captive simulation capabilities or rely on vendor-managed validation services as grid complexity outpaces in-house modeling expertise.
Market Dynamics
Power system simulators face accelerating demand bifurcation as inverter-based renewable penetration forces transmission operators to validate transient stability at microsecond resolution rather than traditional millisecond frames.
Growth Catalysts
- EU Green Deal network codes:European utilities must demonstrate fault-ride-through compliance using certified real-time emulation platforms before interconnecting new generation assets.
- Offshore wind cluster development:Germany's North Sea expansion requires hardware-in-the-loop validation of HVDC converter controls at TenneT and 50Hertz interconnection points.
- FERC Order 2222:U.S. grid operators now mandate simulator-validated interoperability protocols before aggregating distributed energy resources into wholesale markets.
Market Restraints
- FPGA supply concentration:Xilinx and Intel dominate programmable logic device manufacturing, creating single-source vulnerability for real-time simulator hardware.
- Specialized engineering scarcity:North American utilities report collapsing power systems modeling expertise, forcing reliance on external vendor capacity.
- Capital intensity of HIL platforms:Processor and chassis requirements for electromagnetic transient simulation exceed $500,000 per installation, excluding software licensing.
Strategic Opportunities
- Cloud-based simulation elasticity:Energy consultants in India and Brazil seek on-demand compute for probabilistic load forecasting without fixed infrastructure investment.
- Microgrid controller validation:Islanding detection and synchronization algorithms for remote industrial sites remain underserved by current vendor offerings.
- Cyber-physical testing standards:ISO/IEC 27019 and emerging grid cybersecurity mandates create certified platform requirements across multiple jurisdictions.
Industry Challenges
- Multi-timescale model integration:Coupling electromagnetic transient, electromechanical, and steady-state simulations requires reconciliation of incompatible numerical methods.
- Legacy relay testing protocol migration:Protective equipment laboratories face multi-year recertification cycles when transitioning from analog to digital twin-based validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power System Simulator Market |
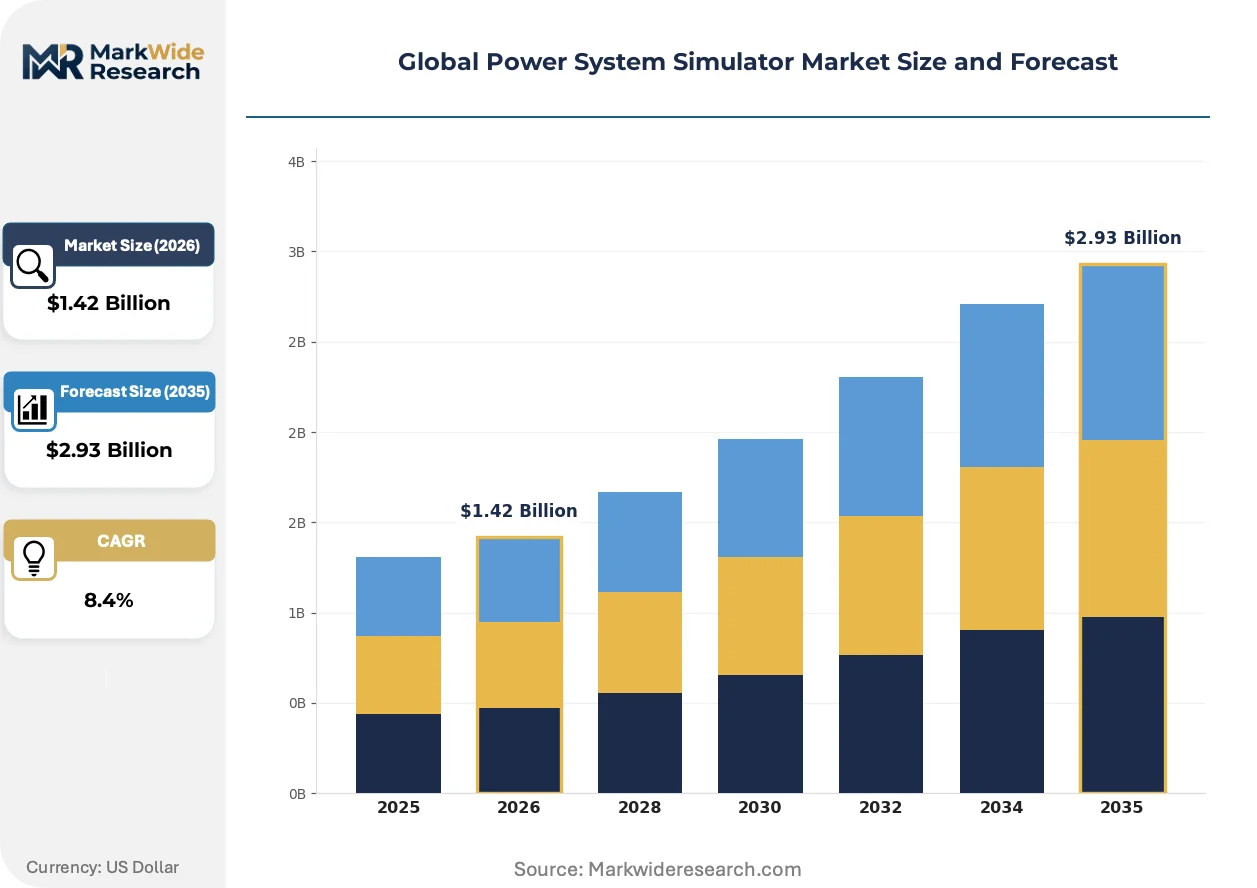
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time Simulator, Offline Simulator, Controller Hardware, Network Simulator, Data Recorder Technology: Digital Signal Processing, Hardware-in-the-Loop, Software-in-the-Loop, Real-Time Emulation, Cloud-Based Simulation Application: Grid Stability Analysis, Renewable Integration Testing, Load Flow Analysis, Fault Analysis, Protective Relay Testing End User: Power Transmission Operators, Independent System Operators, Research Laboratories, Smart Grid Developers, Energy Consultants |
| Companies Covered | Siemens, ABB, Eaton, The MathWorks, Inc., RTDS Technologies Inc., Fuji Electric Co., Ltd., General Electric Company, ETAP, OPAL-RT TECHNOLOGIES, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power System Simulator Market Shifts & Advancements
Digital twin architectures are compressing commissioning timelines for grid infrastructure by enabling parallel virtual testing of control schemes before physical deployment.
FPGA-based emulation is bifurcating the real-time simulation landscape. These architectures execute power electronic switching models at 50-nanosecond time steps, capturing inverter harmonic interactions invisible to processor-based solvers. Transmission operators in Germany and California are prioritizing FPGA platforms for offshore wind and solar-plus-storage interconnection studies. The technology is bifurcating vendor competitive positions between specialized hardware providers and traditional software-centric suppliers.
REACH and RoHS substance restrictions are reshaping simulator hardware manufacturing. European environmental compliance now mandates lead-free soldering and restricted flame retardants in chassis and circuit board assemblies. Hardware-in-the-loop manufacturers serving EU utilities must requalify supply chains or face market exclusion. Component substitution is extending procurement lead times by four to six months for affected product lines.
Utility procurement departments are unbundling validation services from capital equipment purchases. Grid operators in Texas and Australia now contract vendor-managed simulation-as-a-service for intermittent project validation rather than maintaining captive modeling centers. This reconfiguration favors vendors with distributed cloud infrastructure over those with purely on-premise delivery models. The shift is most pronounced among municipal utilities lacking specialized power systems engineering staff.
Global Power System Simulator Market Segmentation
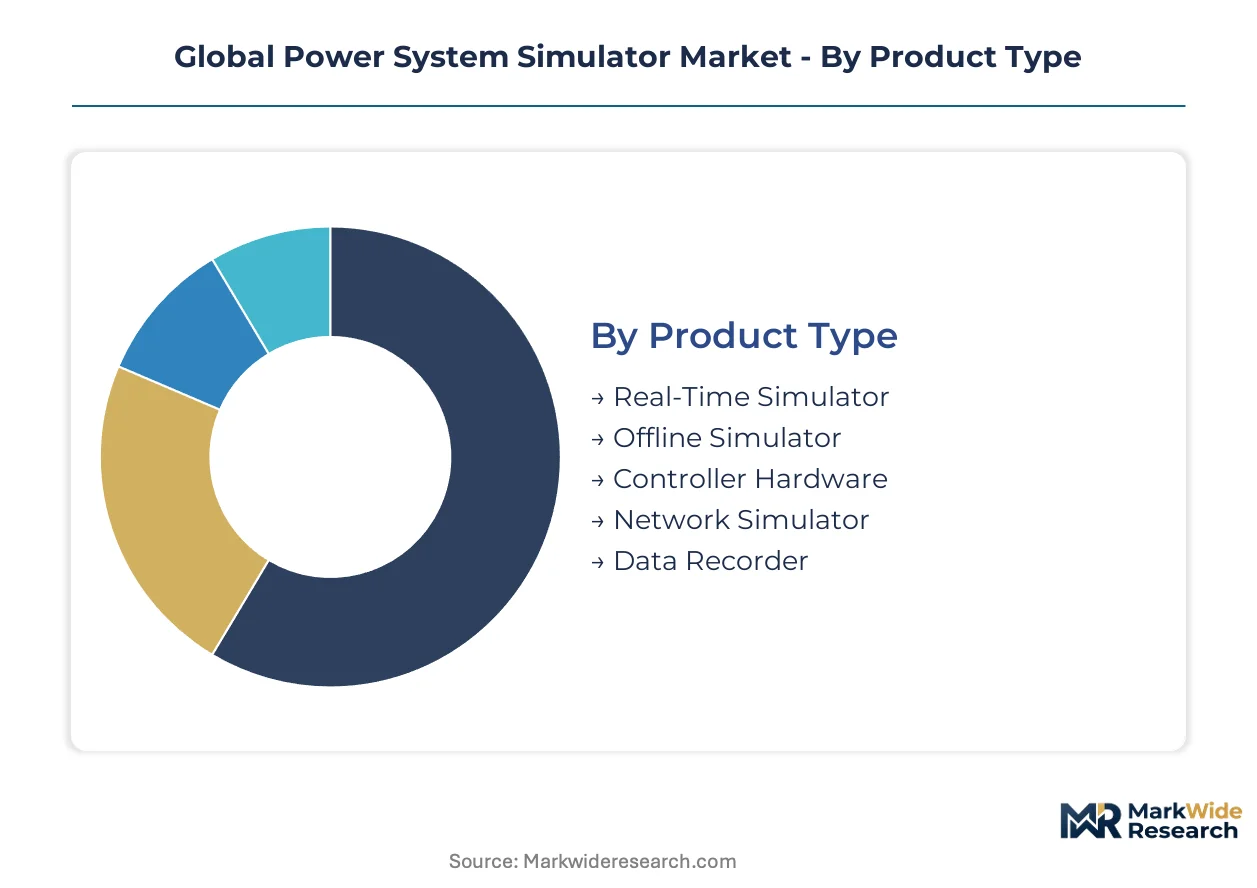
Power system simulator procurement splits sharply between capital-intensive hardware platforms and elastic software services. Channel dynamics vary dramatically across these categories, with transmission operators favoring direct vendor relationships for HIL systems while energy consultants access cloud-based tools through subscription marketplaces.
Product Type:
Channel concentration differs markedly: transmission operators acquire Real-Time Simulators through direct OEM contracts, while Offline Simulators and Data Recorders flow increasingly through academic distributors and cloud marketplaces.
- Real-Time Simulator:FPGA and processor-based platforms execute electromagnetic transient models at microsecond resolution. Demand concentrates with Germany's TenneT and 50Hertz for offshore wind HVDC validation, driven by EU Green Deal network code mandates for fault-ride-through certification.
- Offline Simulator:Software-only solutions run power flow and stability studies on standard workstations without specialized hardware. Research laboratories in India and Brazil dominate procurement, prioritizing cost efficiency over speed for long-horizon planning studies.
- Controller Hardware:Physical control cabinets interface with simulation platforms for protective relay testing protocols.
- Network Simulator:Communication topology emulation validates cyber-physical grid interactions and SCADA integration.
- Data Recorder:High-speed waveform capture devices support post-fault analysis and model validation against field measurements.
Real-Time Simulator dominates installed base. Cloud-accessible Offline Simulator variants are where expansion concentrates.
Technology:
Cost tiering separates premium FPGA-based systems from mid-range processor architectures and entry-level cloud subscriptions.
- Hardware-in-the-Loop:Physical power equipment interfaces with real-time computational models through analog and digital I/O channels. California transmission operators and German offshore wind developers prioritize these systems for inverter-dominated grid validation, constrained by Xilinx and Intel FPGA supply concentration.
- Cloud-Based Simulation:Elastic compute resources execute probabilistic load forecasting and scenario analysis without fixed infrastructure. Energy consultants in Brazil and India drive fastest adoption, seeking pay-per-use models for intermittent project validation.
- Digital Signal Processing:Specialized processor architectures handle high-fidelity power electronic switching models.
- Software-in-the-Loop:Pure software validation of control algorithms precedes hardware deployment.
- Real-Time Emulation:Processor-based solvers target electromechanical transient studies at millisecond resolution.
Hardware-in-the-Loop commands premium pricing tiers. Cloud-Based Simulation is climbing the fastest among consultancies lacking captive modeling centers.
Application:
Application maturity correlates with grid development stage: established markets emphasize Protective Relay Testing, while renewable-heavy systems prioritize Grid Stability Analysis.
- Grid Stability Analysis:Transient and voltage stability studies assess system response to disturbances and N-1 contingencies. ISOs in Texas and Australia concentrate investment here, compelled by FERC Order 2222 mandates for distributed energy resource aggregation validation.
- Renewable Integration Testing:Inverter-based generation interconnection studies evaluate harmonic emissions and fault-ride-through compliance. Germany's North Sea offshore clusters and California solar-plus-storage projects drive specialized FPGA-based emulation demand.
- Load Flow Analysis:Steady-state power flow calculations optimize dispatch and identify thermal constraints.
- Fault Analysis:Short-circuit and protection coordination studies verify relay settings and equipment ratings.
- Protective Relay Testing:Laboratory validation of protection schemes against standard fault scenarios.
Protective Relay Testing retains largest legacy installed base. Renewable Integration Testing is gaining share fastest where inverter penetration exceeds 50%.
End User:
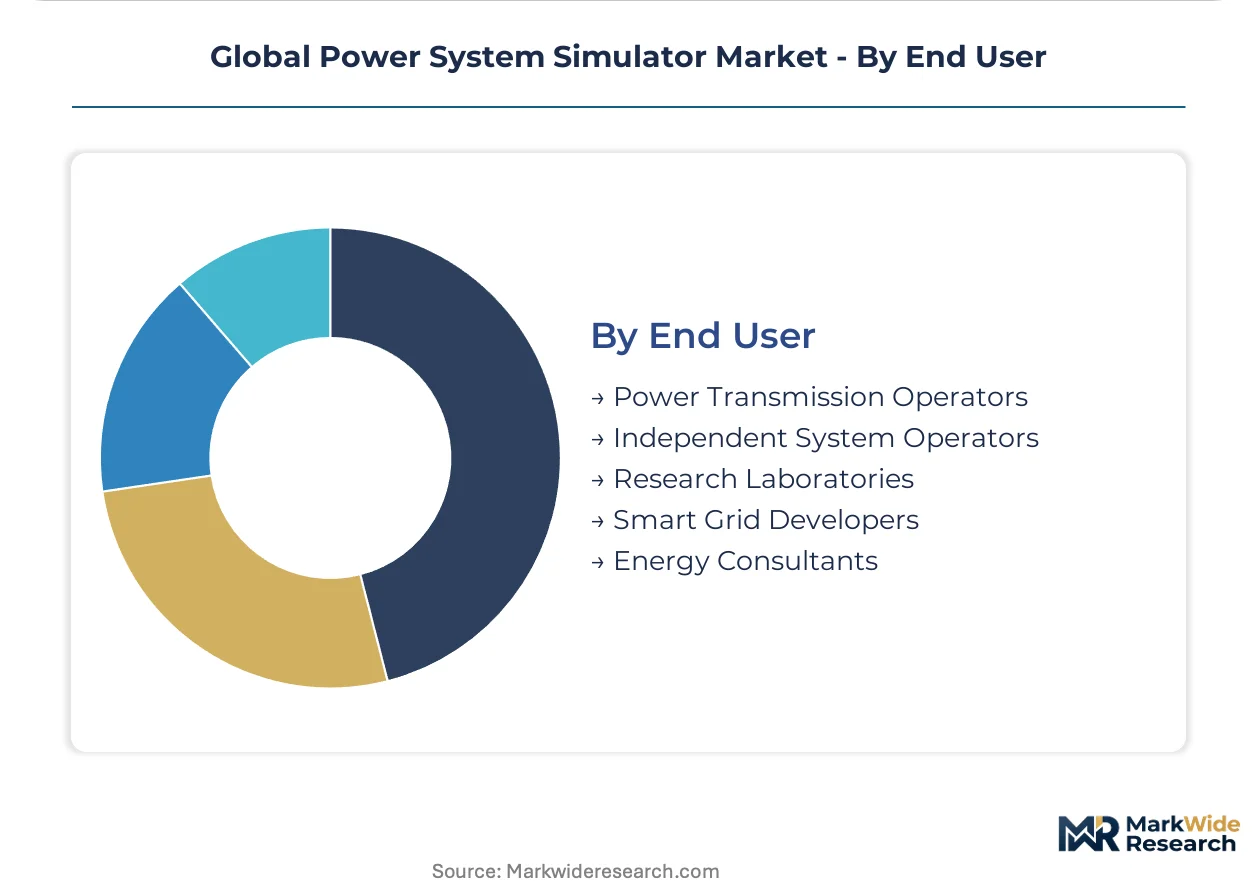
Customer type determines procurement modality: regulated utilities favor capital purchases with long service contracts, while consultancies and laboratories prefer subscription or rental arrangements.
- Power Transmission Operators:Vertically integrated grid owners operate high-voltage networks and interconnection facilities. Germany's TenneT and 50Hertz anchor European demand, modernizing cross-border testing protocols under EU network code enforcement.
- Energy Consultants:Engineering advisory firms deliver project-specific studies without maintaining permanent simulation infrastructure. Brazilian and Indian consultancies are shifting fastest to vendor-managed simulation-as-a-service models.
- Independent System Operators:Regional grid coordinators manage wholesale markets and reliability standards.
- Research Laboratories:University and government research centers prioritize Offline Simulators for algorithm development and training.
- Smart Grid Developers:Technology vendors validate microgrid controllers and distributed energy resource management systems.
Power Transmission Operators dominate capital equipment procurement. Energy Consultants represent the steepest expansion trajectory for cloud-delivered validation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where EU Green Deal mandates command premium hardware-in-the-loop installations, while Brazilian energy consultants access cloud-based validation at fractionally lower cost points through vendor-managed service models.
United States
FERC Order 2222 and EPA greenhouse gas performance standards drive procurement of simulator-validated interoperability protocols for distributed energy resource aggregation. Texas grid operators and California transmission authorities anchor demand, with ISOs in both states mandating real-time emulation before wholesale market participation for inverter-dominated assets.
Germany
TenneT and 50Hertz are modernizing cross-border interconnection testing protocols under EU Green Deal network code enforcement for fault-ride-through compliance. The North Sea offshore wind cluster requires specialized FPGA-based HVDC converter validation, positioning Hamburg and Lower Saxony as Europe's densest concentration of real-time simulator deployments.
China
Dual carbon goals and state grid modernization programs accelerate digital twin infrastructure investment for renewable integration testing. Yangtze River Delta utilities prioritize electromagnetic transient simulation for solar-plus-storage interconnection, with Shanghai and Jiangsu province hosting concentrated procurement of processor-based stability analysis platforms.
India
CEA grid standards and state-level renewable purchase obligations compel transmission utilities to demonstrate transient stability compliance before generator interconnection. Maharashtra and Gujarat dominate offline simulator adoption among engineering consultancies seeking cost-efficient power flow analysis for long-horizon distribution planning studies.
Brazil
ANEEL regulatory mandates for distributed generation interconnection drive demand for probabilistic load forecasting tools among energy consultants. São Paulo and Rio de Janeiro anchor cloud-based simulation adoption, with advisory firms contracting vendor-managed validation services rather than maintaining captive modeling centers.
Global Power System Simulator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the power system simulator market. The vendor base separates into three strategic tiers: diversified industrial conglomerates with integrated software-hardware bundles, specialized real-time emulation houses with FPGA manufacturing depth, and cloud-native platform providers serving consultant markets. Consolidation pressure intensifies as transmission operators unbundle validation services from capital equipment purchases, while M&A activity targets cyber-physical testing capabilities and regional service network expansion.
Among diversified industrial technology providers, Siemens and ABB occupy positions spanning hardware-in-the-loop manufacturing and protective relay testing protocols. RTDS Technologies Inc. exemplifies the specialized real-time emulation archetype with concentrated focus on processor-based solver architectures. These three companies represent distinct competitive vectors: integrated bundling, manufacturing scale, and architectural specialization respectively.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Eaton |
| The MathWorks, Inc. |
| RTDS Technologies Inc. |
| Fuji Electric Co., Ltd. |
| General Electric Company |
| ETAP |
| OPAL-RT TECHNOLOGIES, Inc. |
| Others |
Supply & Pricing Matrix
FPGA substitution for processor-based architectures in electromagnetic transient simulation is redrawing supply geography toward Xilinx and Intel fabrication centers while compressing hardware-in-the-loop pricing premiums. REACH and RoHS substance restrictions are simultaneously forcing lead-free soldering transitions that extend procurement cycles and elevate chassis manufacturing costs for EU-bound equipment.
Pricing Analysis
The customization-premium spread between configured-to-order FPGA platforms and standard processor-based systems spans three distinct tiers: premium FPGA-based hardware-in-the-loop installations for transmission operators, mid-range real-time processor systems for research laboratories, and economy cloud-based subscriptions for energy consultants. Price differentiation rests on emulation fidelity certification and after-sales service bundling rather than raw compute specifications alone. Pricing pressure stems from Brazilian and Indian consultancies migrating toward vendor-managed simulation-as-a-service models that eliminate capital expenditure. Energy consultants exhibit highest price sensitivity, while Germany's TenneT and 50Hertz accept premium positioning for fault-ride-through compliance certification.
Supply Chain Analysis
Inventory lead times for programmable logic devices have extended substantially following supply concentration in Taiwan and South Korea, with Xilinx and Intel dominating FPGA fabrication for real-time simulator hardware. Raw material dependencies center on high-purity silicon substrates, specialized analog-to-digital converter chips, and lead-free solder alloys compliant with RoHS directives. Single-source vulnerability in programmable logic device manufacturing represents the dominant structural risk, compounded by REACH substance restrictions affecting European chassis suppliers. Distribution runs through direct OEM contracts for transmission operators and cloud marketplace subscriptions for consultant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors must defend against cloud-native platform substitution that threatens to unbundle validation services from capital equipment sales. The shift toward vendor-managed simulation-as-a-service models enables new entrants to capture consultant demand without manufacturing infrastructure.
For Market Incumbents: Shield hardware-in-the-loop margins by deepening FPGA manufacturing partnerships and capturing recurring revenue through certification-validated service contracts. Siemens and ABB should anchor integrated software-hardware bundles against pure-play cloud competitors. Prioritize backward integration into programmable logic device supply channels to mitigate Xilinx and Intel concentration risk.
For New Entrants and Emerging Players: Microgrid controller validation for remote industrial sites offers a service-layer gap where incumbents under-serve islanding detection and synchronization algorithm testing. Target Brazilian and Indian energy consultancies with pay-per-use electromagnetic transient models delivered through distributed cloud infrastructure. Lead with probabilistic load forecasting tools that eliminate fixed infrastructure investment for intermittent project validation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized real-time emulation houses with FPGA architectural depth over diversified industrial conglomerates. Long-term viability hinges on cyber-physical testing capabilities as ISO/IEC 27019 mandates expand. Watch FERC Order 2222 enforcement intensity as the signal indicating distributed energy resource aggregation validation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Manufacturing Partnership | Secures programmable logic supply for TenneT and 50Hertz offshore wind validation platforms. |
| Cloud Infrastructure Expansion | Enables vendor-managed simulation-as-a-service for Brazilian energy consultants lacking captive modeling centers. |
| Cyber-Physical Testing Certification | Positions platforms for ISO/IEC 27019 compliance mandates across multiple jurisdictions. |
| Microgrid Controller Validation Suite | Addresses islanding detection gaps for remote industrial sites in underserved segments. |
| REACH/RoHS Supply Chain Requalification | Maintains EU market access amid lead-free soldering and restricted flame retardant requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with transmission planning officers, protective relay testing laboratory directors, energy consultancy principals, and hardware-in-the-loop manufacturing engineers. Secondary validation drew from FERC filings, EU network code enforcement documentation, EIA grid modernization reports, and IEA renewable integration databases. Bottom-up demand aggregation across end-user segments was triangulated against top-down market sizing from equipment shipment records and service contract disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type, technology architecture, application maturity, and end-user procurement modality. CAGRs were derived from regression analysis of historical adoption curves and regulatory mandate implementation timelines. Key inputs included inverter penetration rates in target grids, FPGA supply availability indicators, and cloud infrastructure capex disclosures from major platform providers.
Forecasts assume regulatory continuity in FERC Order 2222 enforcement and EU Green Deal network code implementation; material policy shifts would require re-modeling demand trajectories for distributed energy resource aggregation and fault-ride-through compliance. Supply chain disruptions in programmable logic device manufacturing or REACH substance restriction expansions could accelerate cloud-based substitution beyond baseline projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Germany Power EPC Market
Power Equipment
SCR Power Controller Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
US Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Japan Power EPC Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market