
 Global Auxiliary Power Unit Market | 2026-2036
Global Auxiliary Power Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Auxiliary Power Unit Market Analysis
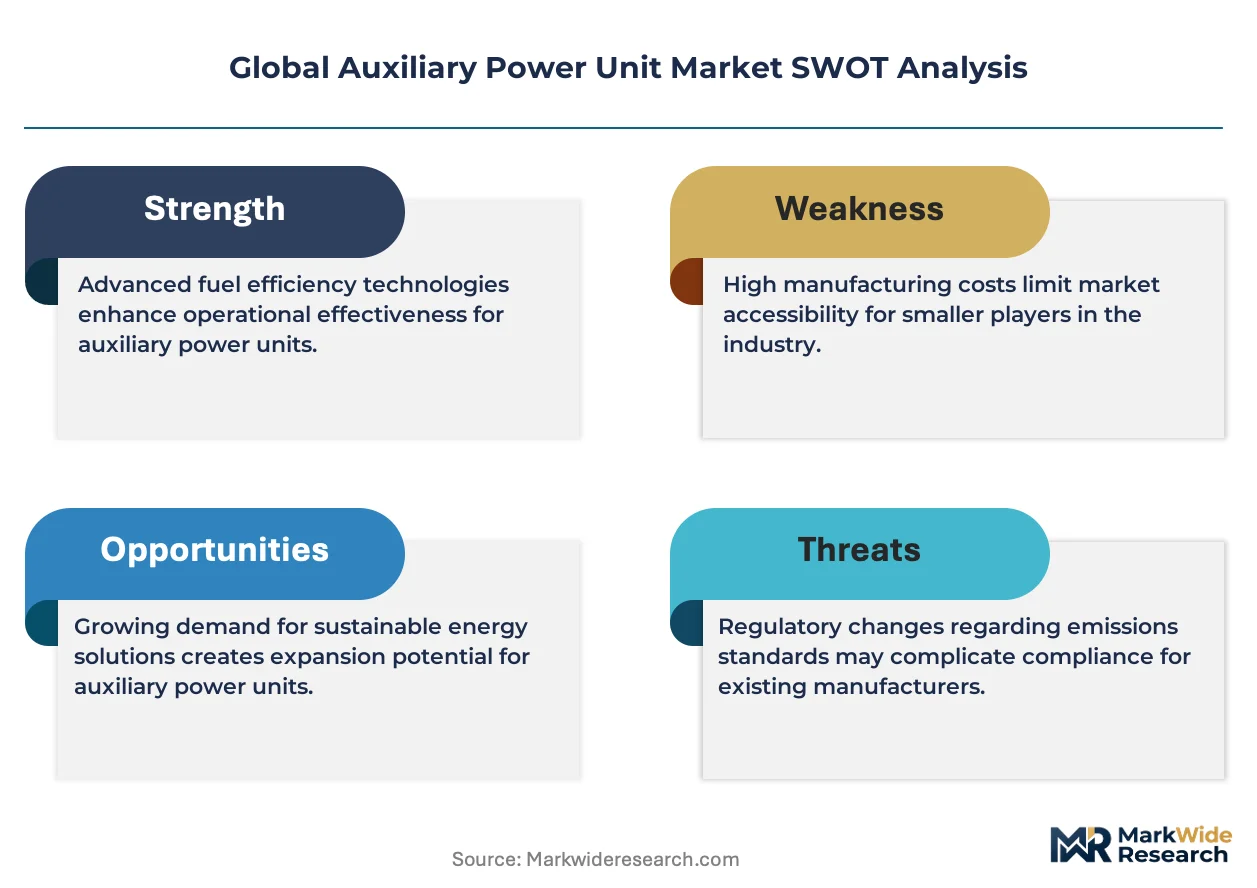
The performance gap between premium aerospace-grade APUs and commodity stationary units is expanding as certification standards diverge. Honeywell International Inc. leverages its integrated flight-deck ecosystem to bundle APU sales with avionics packages. Safran SA anchors its position through dedicated R&D centers in Toulouse that specialize in low-emission combustion architectures. Pratt & Whitney competes on manufacturing scale, operating one of the largest dedicated turbine component facilities serving both military and commercial APU programs.
An auxiliary power unit is a self-contained gas turbine engine designed to provide pneumatic, hydraulic, and electrical power to aircraft, marine vessels, and ground vehicles during ground operations or as emergency backup. Most aerospace APUs operate at rotational speeds between 40,000 and 60,000 RPM and incorporate single-stage centrifugal compressors with annular combustors to achieve power-to-weight ratios exceeding 1.5 kW per kilogram. Mobile APU configurations dominate installed base value due to their integration complexity and recurring overhaul cycles, while hybrid APUs are gaining traction in rail applications where operators face dual pressure to cut idle emissions and maintain cold-start reliability. Stationary APU demand clusters around remote industrial sites where grid connectivity remains uneconomical.
The FAA Part 33 airworthiness standards and EASA CS-APU certification framework govern design validation, noise limits, and dispatch reliability thresholds for commercial aviation APUs. EPA Tier 4 Final and EU Green Deal emission benchmarks are extending compliance obligations to ground-based and marine auxiliary power systems, forcing fuel-type diversification into biofuel and LNG pathways. Stakeholders must monitor how ICAO carbon-offset mechanisms and emerging SAF blending mandates redistribute total-cost-of-ownership calculations across the installed base.
Market Dynamics
Fleet decarbonization mandates and narrow-body aircraft renewal cycles are compressing APU replacement timelines, while certification divergence between aerospace-grade and industrial units widens the competitive moat around established turbine architectures.
Growth Catalysts
- Commercial aviation fleet renewal:Airlines in the United States are retrofitting narrow-body fleets with next-generation APUs to meet FAA Part 33 airworthiness standards for fuel efficiency.
- EPA Tier 4 Final compliance:Ground-based auxiliary power systems face tightened NOx and particulate thresholds, accelerating fuel-type diversification into biofuel pathways.
- Remote industrial electrification:Stationary APU demand clusters around mining and oilfield sites in Canada and Australia where grid connectivity remains uneconomical.
Market Restraints
- Superalloy supply concentration:Single-crystal turbine blade production depends on concentrated cobalt and rhenium sourcing, exposing margins to critical mineral price volatility.
- EASA CS-APU certification friction:Extended validation timelines for low-emission combustion architectures delay product commercialization by 18-24 months.
- Ground power unit substitution:Fixed electrical ground power systems at major hubs displace mobile APU utilization during turnaround cycles.
Strategic Opportunities
- Rail hybridization in Germany:Deutsche Bahn's cold-start reliability requirements create white space for dual-mode diesel-electric auxiliary systems.
- SAF blending mandates:ICAO carbon-offset mechanisms redistribute total-cost-of-ownership calculations toward biofuel-compatible turbine platforms.
- Marine LNG pathway:EU Green Deal emission benchmarks for harbor vessels open retrofit demand for cryogenic-compatible auxiliary power.
Industry Challenges
- Turbine aerodynamics talent scarcity:Specialized combustion engineers with annular combustor experience command premium compensation, constraining R&D throughput.
- Legacy avionics integration complexity:Next-generation APUs must interface with integrated flight-deck ecosystems, extending system verification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Auxiliary Power Unit Market |
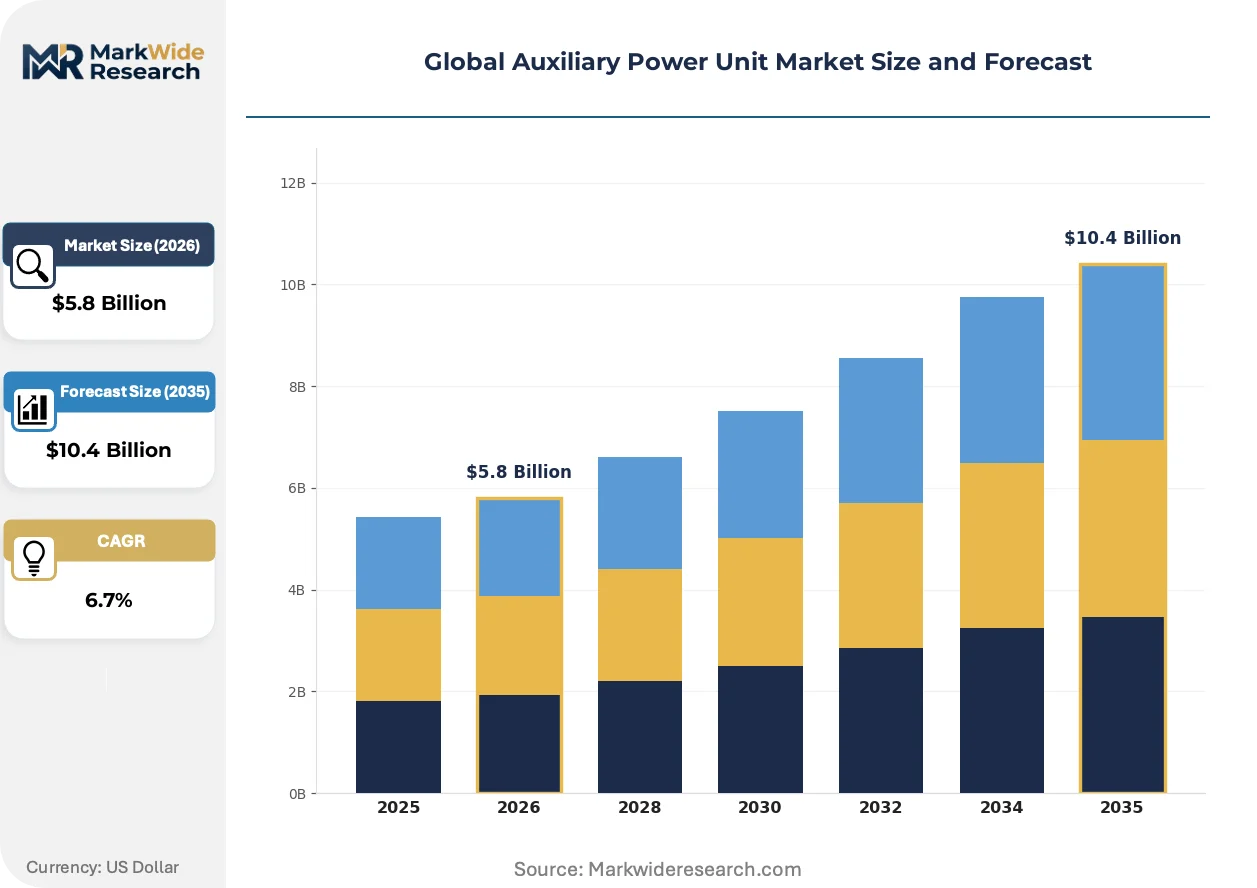
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile APU, Stationary APU, Hybrid APU, Thermal APU Fuel Type: Diesel, LNG, LPG, Biofuel End User: Aerospace, Marine, Rail, Heavy Duty Trucks Installation Type: Retrofit, OEM, Portable, Fixed |
| Companies Covered | Pratt & Whitney, Rolls-Royce plc, Honeywell International Inc., PBS Group, General Electric Company, Raytheon Technologies Corporation, Collins Aerospace, Liebherr-International Deutschland GmbH, Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Auxiliary Power Unit Market Emerging Trajectories
Digital twin architectures and additive manufacturing are compressing development cycles for turbine components, while regulatory fragmentation between aviation and ground-based applications forces parallel certification tracks.
Single-stage centrifugal compressors with advanced blade geometries are consolidating market share in narrow-body applications. Airlines operating Airbus A320neo and Boeing 737 MAX families specify these units for their power-to-weight ratios exceeding 1.5 kW per kilogram. The technology is consolidating supplier tiers as only integrated turbine houses maintain in-house casting and machining capabilities for high-RPM rotating assemblies.
EU Green Deal emission benchmarks are extending compliance obligations to harbor vessels and rail yards. The F-Gas Regulation and parallel EPA Tier 4 Final standards force simultaneous engineering for NOx, particulate, and refrigerant containment. Marine operators in Rotterdam and Hamburg are retrofitting auxiliary systems to meet dual jurisdiction requirements.
Power-by-the-hour contracts are displacing outright purchase models for commercial aviation APUs. Maintenance, repair, and overhaul providers bundle availability guarantees with predictive analytics, shifting balance-sheet treatment for regional carriers. This model concentrates most visibly among low-cost operators in Southeast Asia seeking to minimize unscheduled removal risk.
Global Auxiliary Power Unit Market Segmentation
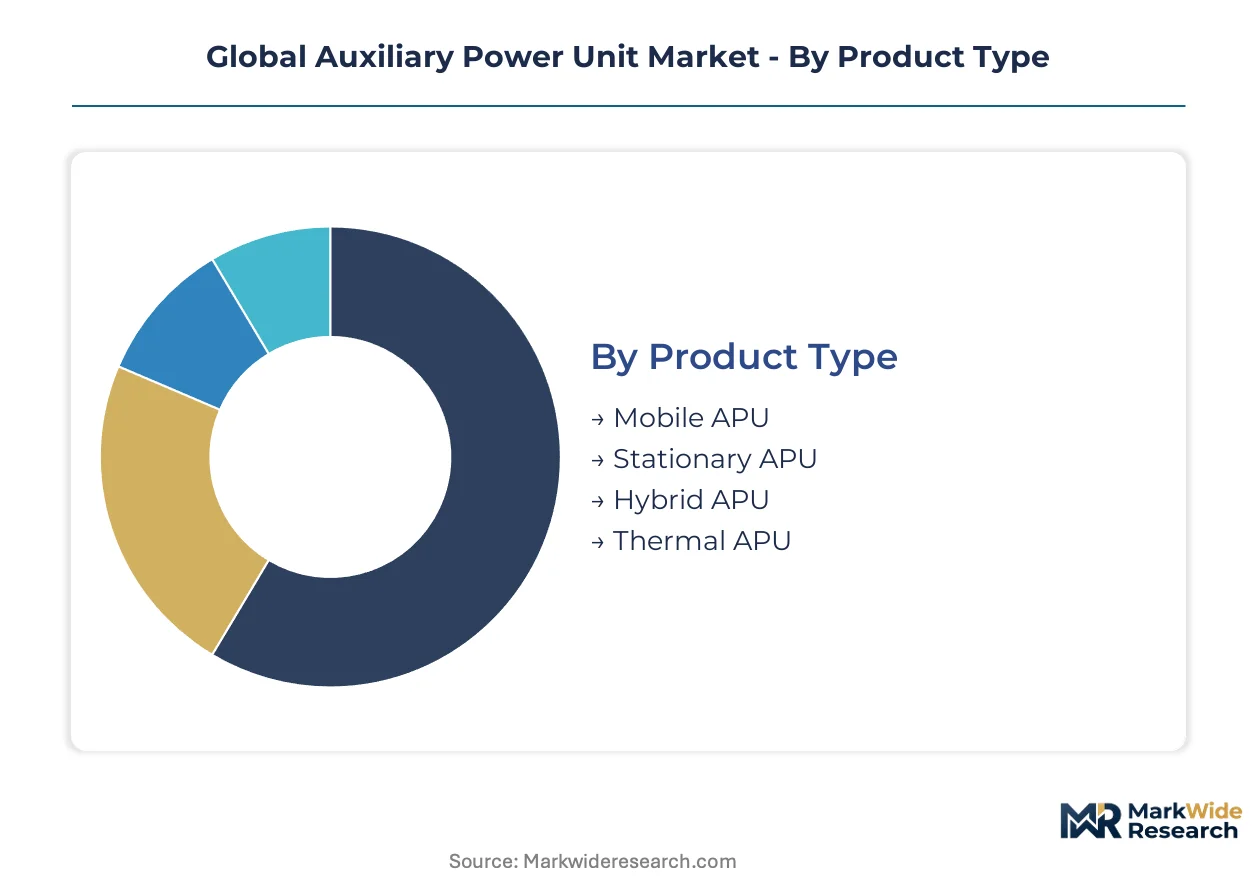
APU buyers exhibit sharply divergent technical requirements based on mobility constraints, fuel access infrastructure, and regulatory exposure. Segmentation reveals how procurement logic splits between aerospace-grade certification premiums and industrial cost optimization.
Product Type:
Buyers in this category separate by integration complexity and overhaul cycle predictability.
- Mobile APU:Self-contained turbine systems rated for 40,000-60,000 RPM operation with single-stage centrifugal compressors. Demand concentrates among narrow-body fleet operators in the United States seeking FAA Part 33 compliant ground power solutions with recurring MRO revenue streams.
- Stationary APU:Fixed-installation units serving remote industrial sites where grid connectivity remains uneconomical. Mining operators in Canada and Australia specify these for continuous duty cycles in extraction environments lacking utility infrastructure.
- Hybrid APU:Dual-mode diesel-electric architectures addressing cold-start reliability requirements in rail applications.
- Thermal APU:Waste-heat recovery systems deployed in marine propulsion auxiliary circuits.
Volume sits with Mobile APU; growth tilts toward Hybrid APU.
Fuel Type:
Procurement decisions here track emission benchmark stringency and fuel logistics maturity.
- Diesel:Conventional distillate systems dominate installed base value due to established supply chains and technician familiarity. EPA Tier 4 Final compliance costs are compressing margins for ground-based operators in the United States.
- Biofuel:Hydrotreated renewable jet fuel and FAME-compatible turbines gaining specification from airlines under ICAO carbon-offset mechanisms. European carriers face EU Green Deal blending mandates that redistribute total-cost-of-ownership calculations.
- LNG:Cryogenic-compatible auxiliary systems opening retrofit demand for harbor vessels in Rotterdam and Hamburg.
- LPG:Propane variants serving remote industrial sites with limited liquid fuel access.
Installed base remains diesel-heavy; biofuel-compatible platforms are expanding most quickly.
End User:
Application-specific certification thresholds create non-overlapping supplier tiers.
- Aerospace:Gas turbine APUs requiring EASA CS-APU or FAA Part 33 validation with power-to-weight ratios exceeding 1.5 kW per kilogram. Airlines retrofitting A320neo and 737 MAX families in the United States drive specification intensity for annular combustor architectures.
- Marine:Harbor vessels in EU jurisdictions face dual pressure from EU Green Deal emission benchmarks and F-Gas Regulation refrigerant containment rules.
- Rail:Deutsche Bahn's cold-start reliability requirements in Germany create specification pull for dual-mode auxiliary systems.
- Heavy Duty Trucks:Sleeper cab idle-reduction units facing patchwork state-level emission rules in the United States.
Revenue concentrates in aerospace; regulatory pressure is steepest in marine.
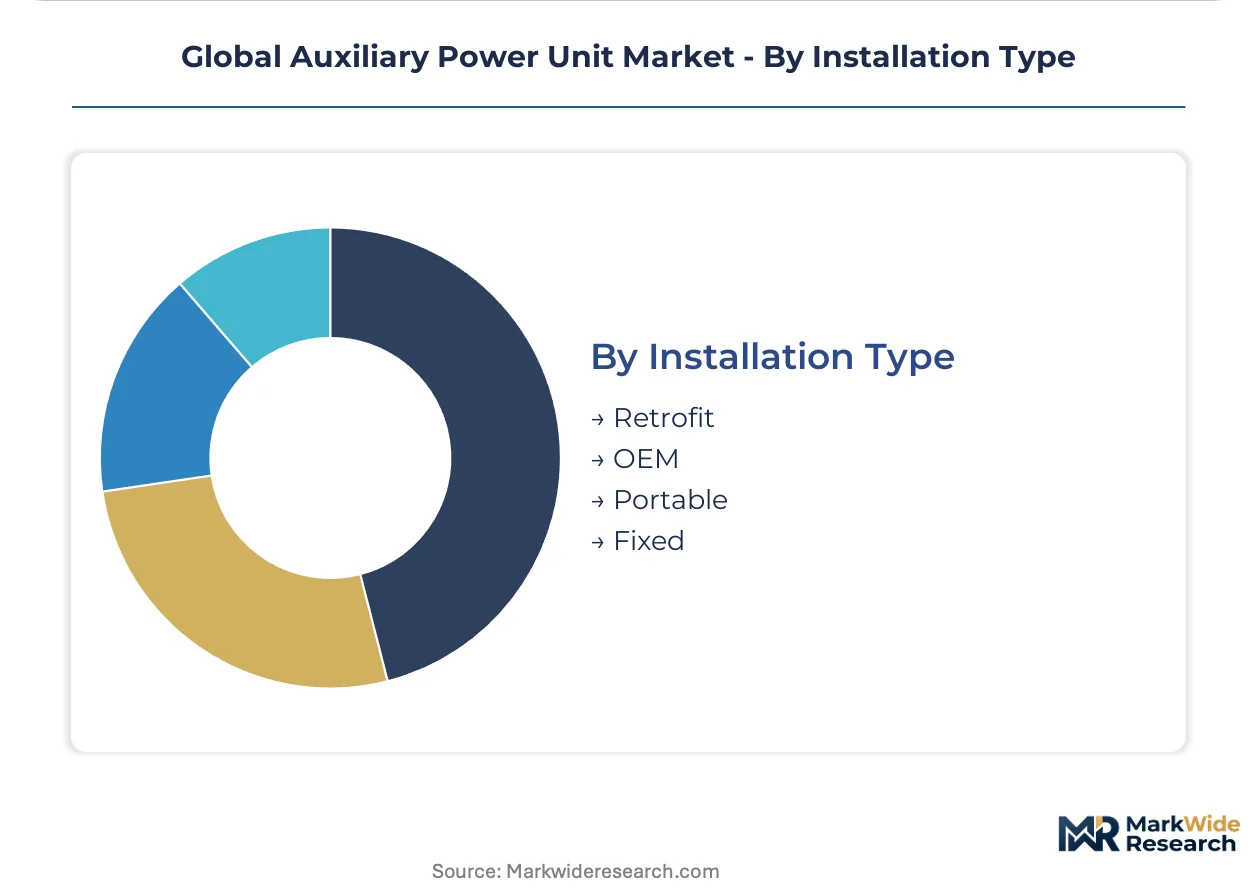
Installation Type:
Channel economics split between factory-integrated warranty coverage and aftermarket availability guarantees.
- OEM:Factory-installed units bundled with airframe or vehicle platform warranties. Airbus and Boeing narrow-body production rates in the United States determine volume timing for supplier foundries.
- Retrofit:Post-delivery replacement cycles accelerating as FAA and EASA emission mandates tighten dispatch reliability thresholds for legacy fleets.
- Portable:Deployable ground power units for military expeditionary operations and emergency response.
- Fixed:Permanent electrical ground power systems at major hubs displacing mobile APU utilization during turnaround cycles.
Retrofit volumes are climbing fastest; OEM retains margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors aerospace-grade APU engineering through Safran's dedicated combustion R&D centers, while Hamburg harbor operators retrofit marine auxiliary systems to meet tightening EU emission benchmarks.
United States
Major carriers retrofit narrow-body fleets with next-generation APUs to satisfy FAA Part 33 airworthiness standards for fuel efficiency. The EPA Tier 4 Final framework tightens NOx thresholds for ground-based auxiliary power systems. Dallas-Fort Worth and Atlanta hubs concentrate MRO infrastructure where predictive maintenance contracts displace outright purchase models.
Germany
Deutsche Bahn's cold-start reliability requirements create specification pull for dual-mode diesel-electric auxiliary systems in rail applications. The EU Green Deal extends emission benchmarks to harbor vessels and rail yards through parallel F-Gas Regulation enforcement. Hamburg port operators retrofit auxiliary power to meet dual jurisdiction requirements for NOx and refrigerant containment.
China
Domestic narrow-body production rates at COMAC facilities drive demand for factory-integrated turbine systems with power-to-weight ratios exceeding 1.5 kW per kilogram. MIIT emission standards for ground-based power systems accelerate fuel-type diversification. Shanghai and Tianjin manufacturing corridors concentrate casting and machining capabilities for high-RPM rotating assemblies.
France
Toulouse-based engineering centers specialize in low-emission annular combustor architectures for next-generation aerospace APUs. EASA CS-APU certification timelines extend validation cycles for novel combustion designs by 18-24 months. The Occitanie aerospace cluster integrates supplier tiers around single-crystal turbine blade production capabilities.
Australia
Mining operators in Western Australia specify stationary APUs for continuous duty cycles at remote extraction sites lacking grid connectivity. The country's national environmental regulator enforces emission benchmarks for industrial ground power systems. Perth and Pilbara region infrastructure projects cluster demand for fixed-installation units with biofuel-compatible turbine platforms.
Global Auxiliary Power Unit Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration complexity. The vendor base concentrates around integrated turbine houses with captive foundry capabilities for aerospace-grade rotating assemblies. Three archetypes dominate: full-stack aerospace integrators bundling avionics with power systems; specialized combustion houses with dedicated R&D centers; and diversified industrial conglomerates leveraging manufacturing scale across military and commercial programs. Competitive moves center on M&A for superalloy supply security and strategic partnerships for SAF-compatible platform development.
Within the full-stack integrator tier, Honeywell International Inc. and Safran SA exemplify positioning through integrated flight-deck ecosystem bundling and dedicated low-emission combustion R&D respectively. Pratt & Whitney anchors the scale-driven segment through manufacturing footprint spanning military and commercial APU programs. Raytheon Technologies Corporation and General Electric Company occupy diversified conglomerate positions with cross-divisional turbine component capabilities. Rolls-Royce plc represents the premium-certification archetype with aerospace-grade validation heritage.
| Leading Market Players |
|---|
| Pratt & Whitney |
| Rolls-Royce plc |
| Honeywell International Inc. |
| PBS Group |
| General Electric Company |
| Raytheon Technologies Corporation |
| Collins Aerospace |
| Liebherr-International Deutschland GmbH |
| Safran SA |
| Others |
Supply Flow & Price Mechanics
Specialized combustion engineers with annular combustor experience in the Occitanie aerospace cluster command premium compensation, widening labor-cost differentials between aerospace-grade and industrial APU tiers. This workforce concentration in Toulouse anchors pricing spreads across certification grades, as EASA CS-APU validation timelines extend product commercialization cycles by 18-24 months.
Pricing Analysis
Power-by-the-hour availability guarantees anchor value-based pricing for commercial aviation APUs, with maintenance, repair, and overhaul providers bundling predictive analytics into long-term contracts. Price differentiation rests on certification tier—FAA Part 33 and EASA CS-APU validated units command substantial premiums over industrial-grade alternatives—and integration complexity with integrated flight-deck ecosystems. Cost compression in ground-based stationary segments intensifies as EPA Tier 4 Final compliance adds engineering overhead, while regional carriers in Southeast Asia exhibit highest price sensitivity through outright purchase avoidance.
Supply Chain Analysis
Dual-sourcing mandates from Airbus and Boeing procurement teams require qualified suppliers for single-crystal turbine blades across at least two foundry locations. Superalloy feedstock concentrates in the United States, France, and the United Kingdom, with cobalt and rhenium dependencies drawing from concentrated mining jurisdictions. Single-source vulnerability in superalloy supply exposes margins to critical mineral price volatility. Distribution runs through airframe OEM assembly lines and aftermarket MRO networks, with power-by-the-hour contracts shifting inventory risk to service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over superalloy supply and annular combustor R&D determines margin sustainability. Players are pursuing backward integration into single-crystal casting capabilities to secure aerospace-grade certification tiers.
For Market Incumbents: Hedge against ground power unit substitution at major hubs by deepening predictive maintenance analytics and availability guarantees. Secure superalloy supply through long-term offtake agreements with cobalt and rhenium producers. Defensive consolidation around low-emission combustion architectures protects against EASA CS-APU certification friction delaying competitor product launches. For New Entrants and Emerging Players: The mid-tier pricing gap between premium aerospace-grade APUs and commodity stationary units creates specification white space in rail hybridization applications. Target Deutsche Bahn's cold-start reliability requirements in Germany with dual-mode diesel-electric architectures. Marine LNG retrofit demand in Rotterdam and Hamburg offers penetrable harbor-vessel entry points without full aviation certification burdens. For Investors and Strategic Acquirers: Re-rating potential sits with specialized combustion houses given EU Green Deal emission benchmark extensions to rail and marine auxiliary systems. Long-term viability favors targets with captive foundry capabilities and SAF-compatible platform development. Watch ICAO carbon-offset mechanism adoption rates as the signal indicating biofuel-compatible turbine platform inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Captive cobalt and rhenium sourcing insulates margins from critical mineral price volatility. |
| SAF-Compatible Platform Development | Biofuel-compatible turbines align with ICAO carbon-offset mechanisms and EU Green Deal mandates. |
| Predictive Maintenance Analytics Investment | Power-by-the-hour contracts shift balance-sheet treatment for regional carriers seeking availability guarantees. |
| Dual-Mode Diesel-Electric Architecture Launch | Rail hybridization addresses Deutsche Bahn cold-start reliability requirements in Germany. |
| Marine LNG Retrofit Certification | Cryogenic-compatible systems open harbor vessel demand in Rotterdam and Hamburg under EU Green Deal benchmarks. |
Methodological Framework
Document review covered FAA Part 33 airworthiness filings, EASA CS-APU certification records, EPA Tier 4 Final compliance documentation, and EU Green Deal regulatory texts, complemented by interviews with aerospace procurement directors, MRO service heads, annular combustor R&D leads, and superalloy supply specialists. Secondary validation drew from customs trade data, SEC 10-K turbine segment disclosures, and airframe production databases. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates across mobile, stationary, hybrid, and thermal APU categories.
Historical production rates for Airbus A320neo and Boeing 737 MAX families were cross-referenced against panel input from foundry operations managers and airline fleet planning executives. The analytical framework modeled demand across product type, fuel type, end user, and installation type dimensions, with power-to-weight ratio thresholds and certification tier as industry-specific variables. CAGRs were derived from installed base replacement cycles, fleet renewal timelines, and emission mandate compliance deadlines throughout the projection horizon.
Inputs from EASA certification databases and EPA compliance filings were available through the study window; gaps in real-time superalloy spot pricing and unannounced airframe production rate adjustments introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding FAA and EASA emission mandate enforcement timelines, SAF blending mandate adoption curves, and rail operator hybridization commitments. Deviation in superalloy supply concentration or airframe OEM production schedule acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Turbine Control Systems Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Air Preheater Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Power Analyzers Market