
 Battery Energy Management System Market | 2026-2036
Battery Energy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Energy Management System Market Insights
Automotive-grade functional safety certification is redrawing competitive boundaries in battery energy management. Siemens leverages its automation heritage to anchor high-reliability offerings for industrial microgrids across European manufacturing corridors. CATL sustains cost-engineering leadership through captive cell production paired with proprietary management firmware. Huawei Digital Power competes aggressively in utility-scale deployments across Middle Eastern and Asian solar-storage hybrids.
A battery energy management system orchestrates cell-level monitoring, thermal regulation, and charge balancing across electrochemical storage arrays, typically maintaining voltage windows between 2.5V and 4.2V per cell depending on chemistry. The platform prevents thermal runaway, maximizes cycle life, and enables safe integration with inverters and grid interconnection hardware. Utility-scale systems command the dominant revenue share given capital intensity and software complexity, while residential systems represent the fastest-expanding installation base as homeowners pair rooftop solar with intelligent storage. Lithium-ion technology retains primacy in new deployments, though flow batteries are carving a niche in long-duration grid stability applications where daily cycling exceeds twelve hours.
The EU Battery Regulation and F-Gas Regulation are tightening traceability and thermal management requirements for systems sold across European member states. In the United States, NHTSA and OSHA guidelines shape safety architectures for vehicular and occupational battery installations respectively. China's GB standards and dual carbon goals mandate interoperable communication protocols for grid-connected storage. Stakeholders must monitor evolving certification reciprocity between jurisdictions, as divergent electromagnetic compatibility and fire-safety test regimes threaten to fragment supply chains and inflate compliance overhead for multi-region vendors.
Market Dynamics
Automotive functional safety certification is redrawing competitive boundaries as ISO 26262 compliance becomes mandatory for EV-grade battery management systems, forcing vendors to rebuild firmware architectures around ASIL-D reliability standards.
Growth Catalysts
- EU Battery Regulation traceability mandates:The regulation's digital passport requirements are compelling industrial energy users across Germany and France to retrofit existing installations with intelligent monitoring platforms.
- California carbon neutrality deadlines:Fleet operators in the state face binding 2035 electrification targets that accelerate procurement of lifecycle-optimizing management systems for heavy-duty vehicle batteries.
- Solid-state cell commercialization:Next-generation chemistries with tighter voltage tolerances demand more sophisticated balancing algorithms, creating pull for upgraded management firmware.
Market Restraints
- Semiconductor supply concentration:Automotive-grade AEC-Q100 qualified microcontrollers concentrate among Taiwanese and South Korean foundries, exposing lead times to geopolitical friction.
- Lithium price volatility:Raw material cost swings compress margins for integrated system vendors who bundle hardware with long-term software service contracts.
- Functional safety certification timelines:ASIL-D validation cycles extend 18-24 months, freezing product roadmaps and delaying revenue recognition for new entrants.
Strategic Opportunities
- Second-life stationary storage:Retired EV batteries from automotive OEMs create a feedstock stream for grid-scale repurposing platforms requiring adaptive management firmware.
- India's PLI scheme for ACC manufacturing:Domestic cell production incentives are attracting management system vendors to establish localized engineering centers in Gujarat and Tamil Nadu.
- V2G integration protocols:Bidirectional charging standards convergence between IEEE and CHAdeMO creates white space for software vendors orchestrating vehicle-to-grid energy arbitrage.
Industry Challenges
- Embedded systems cybersecurity certification:UN R155 and ISO/SAE 21434 compliance demands specialized talent scarce across hardware-software boundary roles.
- Legacy SCADA integration:Industrial microgrid operators struggle to bridge proprietary Modbus and DNP3 protocols with modern cloud-native management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Energy Management System Market |
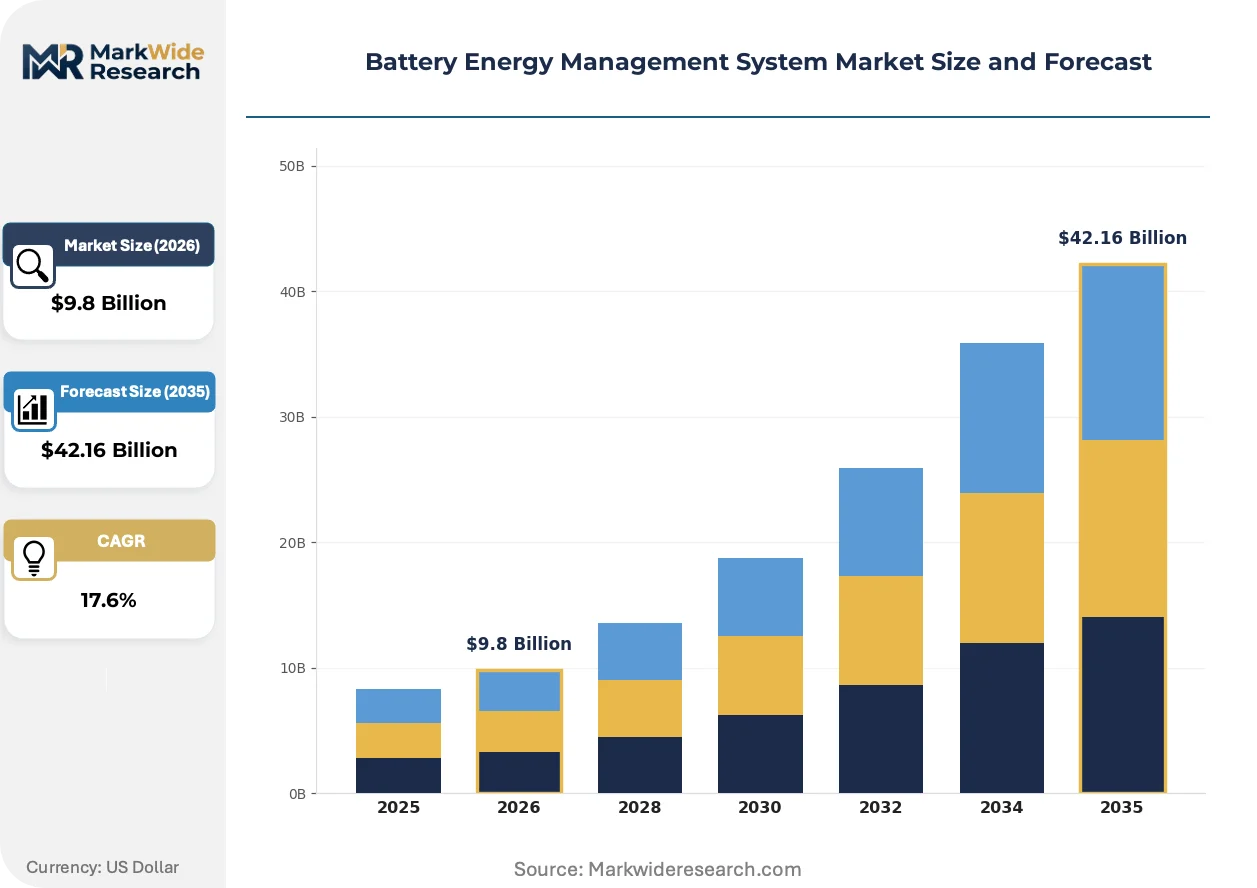
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $42.16 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Systems, Commercial Systems, Industrial Systems, Utility-Scale Systems End User: Homeowners, Businesses, Energy Providers, Fleet Operators Technology: Lithium-Ion, Lead-Acid, Flow Batteries, Sodium-Sulfur Application: Renewable Integration, Peak Shaving, Demand Response, Grid Stability |
| Companies Covered | Siemens, ABB, CATL, Huawei Digital Power, Hitachi Energy, BYD, GE Vernova, Sungrow, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Energy Management System Market Trends and Innovations
Edge-native computing architectures are displacing centralized battery management topologies, distributing computational load to cell monitoring units while compressing latency for thermal runaway detection.
Physics-informed neural networks for state-of-health estimation are fragmenting the predictive maintenance software layer, enabling fleet operators to retire empirical degradation models in favor of real-time electrochemical simulation. European automotive OEMs in Stuttgart and Wolfsburg are piloting these systems at scale, compressing warranty reserve requirements by improving remaining useful life forecasts.
The EU F-Gas Regulation is tightening thermal management refrigerant specifications for battery cooling circuits, compelling system designers to migrate from conventional HVAC architectures to dielectric fluid immersion or phase-change materials. German industrial users face the steepest compliance curves, accelerating partnerships with thermal engineering specialists to redesign factory-scale storage enclosures.
Leasing structures for battery assets are displacing outright purchase across commercial and industrial segments, unbundling hardware ownership from energy management service responsibility. Independent power producers in Texas and California are pioneering this model, transferring operational risk to specialized software vendors while retaining grid interconnection rights.
Battery Energy Management System Market Segmentation
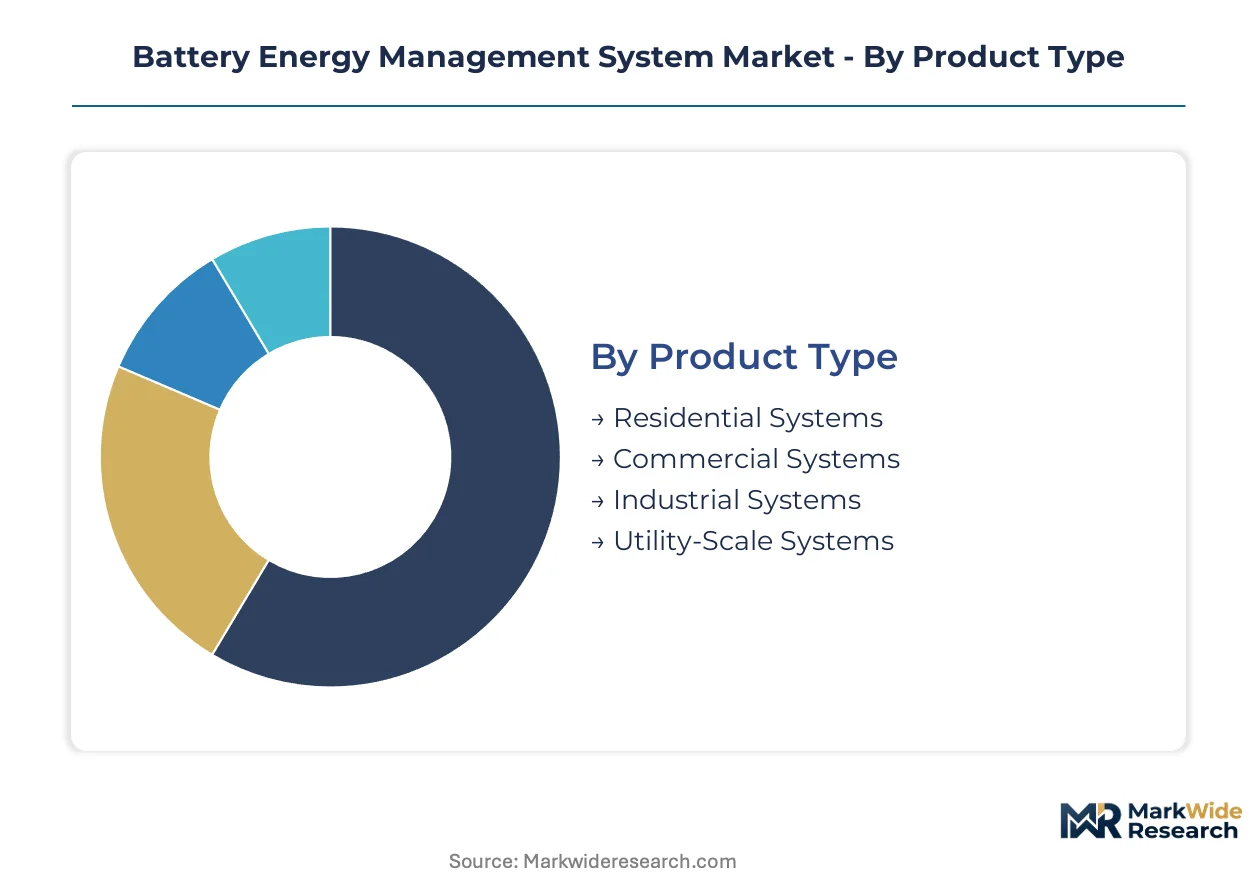
Battery energy management systems fragment across four distinct dimensions, each mapping to divergent procurement channels and technical specifications. Channel strategy varies sharply between residential installers, industrial EPC contractors, and utility procurement offices.
Product Type:
Residential systems flow through electrical contractor networks and solar installer partnerships, while utility-scale deployments route through competitive RFP processes involving EPC firms and grid operators.
- Residential Systems:Compact enclosures integrating 5-20 kWh lithium-ion packs with single-phase inverters dominate rooftop solar retrofits. Demand concentrates in Germany and California where net metering reforms push homeowners toward self-consumption optimization.
- Commercial Systems:Three-phase configurations serving 100 kWh to 2 MWh installations pair with building energy management platforms. German manufacturing corridors and Texas commercial parks are deploying these for demand charge reduction.
- Industrial Systems:Factory-scale microgrids requiring 2-20 MWh capacity integrate with SCADA and process control networks.
- Utility-Scale Systems:Grid-connected arrays exceeding 100 MWh command the highest software complexity and capital intensity.
By volume, Residential Systems leads. By growth pace, Utility-Scale Systems is ahead.
End User:
Customer archetypes determine pricing architecture, with fleet operators negotiating enterprise software licenses and homeowners purchasing through equipment financing.
- Homeowners:Retail purchasers evaluating payback periods against utility rate structures.
- Businesses:Commercial property operators targeting resilience and electricity cost arbitrage.
- Energy Providers:Utilities and independent power producers procuring storage as transmission deferral or ancillary service assets. Procurement concentrates in ERCOT and CAISO territories where market mechanisms reward fast frequency response.
- Fleet Operators:Heavy-duty vehicle electrification programs across California and the European Union mandate lifecycle-optimizing management platforms for depot charging infrastructure.
Energy Providers dominate absolute installation capacity. Fleet Operators are expanding most quickly.
Technology:
Cell chemistry dictates management firmware complexity, with lithium-ion requiring precision balancing and flow batteries demanding pump and electrolyte monitoring subsystems.
- Lithium-Ion:NMC and LFP chemistries retain deployment primacy across all scales. Voltage window management between 2.5V and 4.2V per cell requires sophisticated state-of-charge estimation algorithms.
- Lead-Acid:Mature technology for backup power applications with simpler float-charge management requirements.
- Flow Batteries:Vanadium and zinc-bromine systems excel in long-duration cycling exceeding twelve hours. Installations are concentrating in German grid stability projects and Japanese renewable integration pilots.
- Sodium-Sulfur:High-temperature operation at 300°C demands specialized thermal management subsystems.
Lithium-Ion commands the dominant revenue share. Flow Batteries are climbing the fastest in utility-scale deployments.
Application:
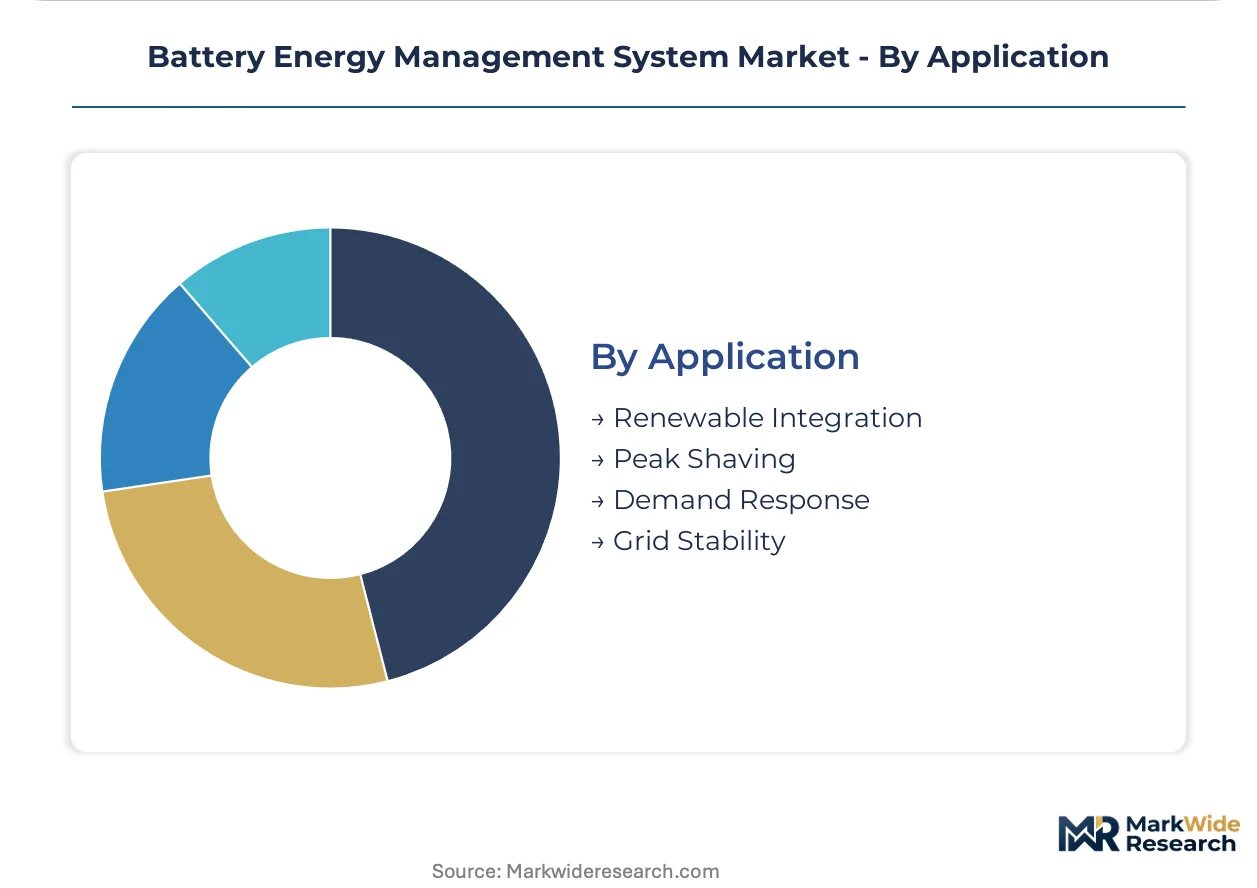
Use-case specificity drives hardware packaging and software licensing models, with grid stability applications requiring utility certification and renewable integration emphasizing forecasting interfaces.
- Renewable Integration:Solar and wind firming applications requiring predictive charge scheduling based on weather forecasts. German and Spanish grid operators mandate these capabilities for new storage interconnection.
- Peak Shaving:Demand charge reduction for commercial and industrial ratepayers.
- Demand Response:Aggregated load curtailment programs requiring utility-controlled dispatch interfaces.
- Grid Stability:Frequency regulation and voltage support services procured through ancillary service markets. PJM and ERCOT market designs are accelerating firmware certification for sub-second response capabilities.
Renewable Integration leads in project pipeline volume. Grid Stability is gaining share fastest in regulated utility procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of battery energy management systems clusters where automotive electrification and grid-scale storage procurement intersect most intensively. Taiwan and South Korean foundries supply the automotive-grade microcontrollers that firmware architects depend upon. Germany, the United States, China, Japan, and India concentrate deployment demand across divergent regulatory environments.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive procurement of ASIL-D certified management platforms for next-generation EV architectures. The EU Battery Regulation's digital passport requirements force retrofitting of existing industrial storage installations with traceable monitoring systems. Grid-scale developers in North Rhine-Westphalia partner with thermal engineering specialists to redesign factory enclosures under tightening F-Gas Regulation refrigerant specifications.
United States
Fleet operators across California face binding 2035 electrification deadlines that accelerate procurement of lifecycle-optimizing systems for heavy-duty depot charging. NHTSA and OSHA guidelines shape safety architectures for vehicular and occupational battery installations respectively. Independent power producers in Texas pioneer leasing structures that unbundle hardware ownership from energy management service responsibility.
China
Domestic cell production at scale creates captive demand for proprietary management firmware integrated with pack manufacturing. GB standards and dual carbon goals mandate interoperable communication protocols for grid-connected storage deployments. Engineering centers in Guangdong and Jiangsu provinces focus on firmware development for utility-scale solar-storage hybrids across Middle Eastern and Asian markets.
Japan
Long-duration grid stability pilots utilizing vanadium flow batteries demand specialized pump and electrolyte monitoring subsystems from management vendors. METI directs standardization efforts for vehicle-to-grid integration protocols that enable bidirectional charging arbitrage. Industrial clusters in Nagoya and Osaka prefectures concentrate pilot programs for solid-state cell architectures requiring tighter voltage tolerance algorithms.
India
The PLI scheme for ACC manufacturing attracts management system vendors to establish localized engineering capabilities in Gujarat and Tamil Nadu. Domestic cell production incentives reshape procurement channels away from import-dependent hardware configurations. Grid operators in Maharashtra pilot renewable integration applications requiring predictive charge scheduling based on weather forecasting interfaces.
Battery Energy Management System Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that leverage automation heritage and captive cell production to anchor high-reliability offerings. Siemens occupies a dominant position in European manufacturing corridors through microgrid integration capabilities. CATL sustains cost-engineering leadership through proprietary firmware paired with vertical control over cell supply. Three strategic archetypes define competitive positioning: automation-heritage industrials, captive-cell battery specialists, and utility-scale power electronics vendors. M&A activity targets firmware startups with ASIL-D certification capabilities, while capacity expansion concentrates in German and Chinese manufacturing zones.
Within the automation-heritage tier, Siemens and ABB exemplify European industrial conglomerates that have extended programmable logic controller expertise into battery management architectures. CATL and BYD represent Chinese captive-cell specialists whose firmware development aligns with pack manufacturing scale. Huawei Digital Power anchors the utility-scale power electronics vector, competing aggressively in solar-storage hybrid deployments across Middle Eastern and Asian markets. LG Energy Solution occupies a position bridging Korean cell manufacturing with integrated management system offerings. These five entities illustrate how competitive positioning fragments across divergent technical foundations rather than consolidating around interchangeable hardware platforms.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| CATL |
| Huawei Digital Power |
| Hitachi Energy |
| BYD |
| GE Vernova |
| Sungrow |
| LG Energy Solution |
| Others |
Pricing and Supply Chain Analysis
ASIL-D functional safety certification gates both supplier qualification and price tiering simultaneously, forcing automotive-grade vendors to absorb eighteen-month validation cycles while tier-2 competitors serve uncertified industrial segments at compressed margins.
Pricing Analysis
ISO 26262 dictates the pricing tier structure across automotive, industrial, and residential deployment categories. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive platforms from industrial microgrid configurations and uncertified residential units. Price differentiation rests on certification grade and after-sales software service bundling. Cost compression in the economy tier is intensifying because raw lithium price volatility squeezes integrated hardware-software vendors. Fleet operators demonstrate the lowest price sensitivity given binding electrification mandates, while residential installers face acute margin pressure from net metering reform uncertainty.
Supply Chain Analysis
Taiwan Strait transit risk underwrites semiconductor supply security for automotive-grade microcontrollers. Manufacturing concentrates in Taiwan, South Korea, and China for AEC-Q100 qualified chips, lithium-ion cell production, and power electronics assembly respectively. Raw material dependencies center on lithium carbonate, nickel sulfate, and electrolyte solvents. Single-source vulnerability in automotive microcontroller foundries exposes lead times to geopolitical friction. Distribution runs through EPC contractor networks for utility-scale deployments and electrical installer channels for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around functional safety certification creates defensive moats for early ASIL-D achievers, as switching costs lock automotive OEMs into validated firmware architectures through multi-year platform cycles.
For Market Incumbents: Secure ASIL-D certification reciprocity across EU, US, and Chinese regulatory regimes before emerging Chinese firmware vendors achieve comparable validation depth. Deepen backward integration into automotive-grade microcontroller supply through strategic foundry partnerships in South Korea. Capacity addition in Gujarat and Tamil Nadu addresses India's PLI-scheme demand while hedging against EU Battery Regulation traceability mandates.
For New Entrants and Emerging Players: Firmware customization for second-life stationary storage applications represents an underserved service layer where incumbent automotive specialists over-index on new-pack development. Target commercial microgrid operators in Texas and California struggling with legacy SCADA integration. White-label edge-native computing architectures for European manufacturing corridors offer the most penetrable entry path.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across residential system manufacturing as leasing structures displace outright purchase and transfer hardware risk to balance-sheet-light software vendors. Five-to-ten-year viability favors vendors with captive cell production or automation heritage rather than pure-play firmware developers. Acquisition target archetype: firmware startups with ASIL-D certification capabilities and utility-scale deployment track records. Monitor CHAdeMO-IEEE protocol convergence as the signal indicating vehicle-to-grid arbitrage software readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Unlocks automotive OEM procurement channels under ISO 26262 mandates in Stuttgart and Wolfsburg. |
| Second-Life Storage Platform Development | Captures retired EV battery feedstock from European fleet electrification programs. |
| India Engineering Center Establishment | Positions for PLI-scheme procurement flows in Gujarat and Tamil Nadu manufacturing corridors. |
| Edge-Native Architecture Deployment | Compresses thermal runaway detection latency for German industrial microgrid operators. |
| V2G Protocol Integration | Enables bidirectional charging arbitrage across ERCOT and CAISO ancillary service markets. |
Research Methodology
Cross-validation between utility procurement databases and automotive OEM technical specifications anchors the qualitative findings in this study. Primary interviews with battery system engineering directors, EPC project developers, fleet electrification managers, and grid operator planning officers combined with secondary validation from FERC interconnection filings, EIA storage deployment data, IEA technology roadmaps, and EU Battery Regulation implementation guidance. Bottom-up unit economics triangulate against top-down market sizing across the projection horizon.
Sensitivity analysis around lithium price trajectories and semiconductor lead time scenarios shapes the analytical framework. Segmentation dimensions modeled include product scale tier, end-user archetype, cell chemistry type, and application use case throughout the forecast period. CAGRs derive from installed base growth rates weighted by software intensity differentials across utility-scale and residential deployment categories. Forecast inputs incorporate EU F-Gas Regulation compliance cost curves and NHTSA safety architecture evolution.
Forecasts assume regulatory continuity in EU Battery Regulation, California CARB mandates, and Chinese GB standards; material policy shifts would require re-modeling. Specific risk factors include ASIL-D validation timeline extensions, Taiwan Strait logistics disruptions, and solid-state chemistry commercialization acceleration. Practitioners should keep alternative scenarios live as V2G protocol standardization and second-life battery supply availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
North America Energy Storage Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Distributed Energy Storage System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Battery Management Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
US Energy Storage Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market