
 Process Air Heater Market | 2026-2036
Process Air Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Process Air Heater Market Analytics
European industrial heater OEM capacity is realigning toward low-emission electric architectures. Chromalox leverages its vertical integration in mineral-insulated cable production to dominate North American retrofit cycles. Tutco-Farnam sustains engineering density in custom open-coil designs for chemical processing. Leister Technologies AG specializes in precision hot-air systems for pharmaceutical cleanroom applications.
Process air heaters are forced-convection thermal devices that raise air temperature for industrial drying, curing, or space conditioning, typically operating between 40°C and 650°C with power ratings from 1 kW to 5 MW. Electric heaters use nickel-chromium or iron-chromium-aluminum resistance elements sheathed in stainless steel or Incoloy, while gas-fired units deploy ribbon or tubular burners with forced-draft combustion chambers. Electric heaters command the premium replacement segment as facilities phase out gas-fired units under carbon accounting rules. Steam tube heaters retain cost advantages in pulp and paper complexes with captive boiler capacity. The food processing vertical drives fastest specification growth for washdown-rated stainless enclosures and sanitary duct connections.
OSHA ventilation standards and EPA National Emission Standards for Hazardous Air Pollutants shape heater specification in US chemical and pharmaceutical plants. The EU Ecodesign Directive and F-Gas Regulation accelerate electric heater substitution across member states. Stakeholders must monitor carbon border adjustment mechanisms and evolving methane intensity rules to time capital deployment across gas-to-electric conversion cycles.
Market Dynamics
Process air heater procurement is pivoting toward electric architectures as carbon accounting rules harden across industrial clusters, forcing gas-to-electric retrofit cycles in chemical processing and food manufacturing facilities.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is compelling German chemical plants to replace gas-fired heaters with electric units to maintain operating permits.
- Food processing hygiene mandates:Washdown-rated stainless enclosures and sanitary duct connections are driving specification upgrades across dairy and meat processing lines.
- Carbon border adjustment mechanisms:Export-oriented manufacturers in the EU industrial corridor are accelerating heater electrification to preserve competitiveness in regulated markets.
Market Restraints
- Nickel-chromium alloy supply concentration:Resistance element feedstock depends on Indonesian and Russian ore processing, exposing heater OEMs to raw material volatility and sanction risk.
- Steam tube heater cost advantage:Pulp and paper complexes with captive boiler capacity face weak economic incentives to switch from steam-based heating despite emission pressures.
- Grid infrastructure lag:Industrial electrification timelines in Eastern Europe are constrained by distribution network upgrade delays and interconnection queue backlogs.
Strategic Opportunities
- Pharmaceutical cleanroom expansion:Precision hot-air systems for aseptic processing present white space as biologics manufacturing capacity scales in Switzerland and Ireland.
- EU Ecodesign Directive alignment:Energy efficiency labeling requirements are creating first-mover advantage for OEMs with modulating control architectures and heat recovery integration.
- Digital twin integration:Convergence of thermal modeling software with IoT sensor networks enables predictive maintenance contracts and remote optimization services.
Industry Challenges
- ATEX and IECEx certification timelines:Hazardous area heater approvals for Zone 1 chemical environments require 12-18 month validation cycles that compress product launch windows.
- Legacy control system integration:Electric heater retrofits must interface with existing DCS and SCADA architectures, complicating commissioning and raising engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Air Heater Market |
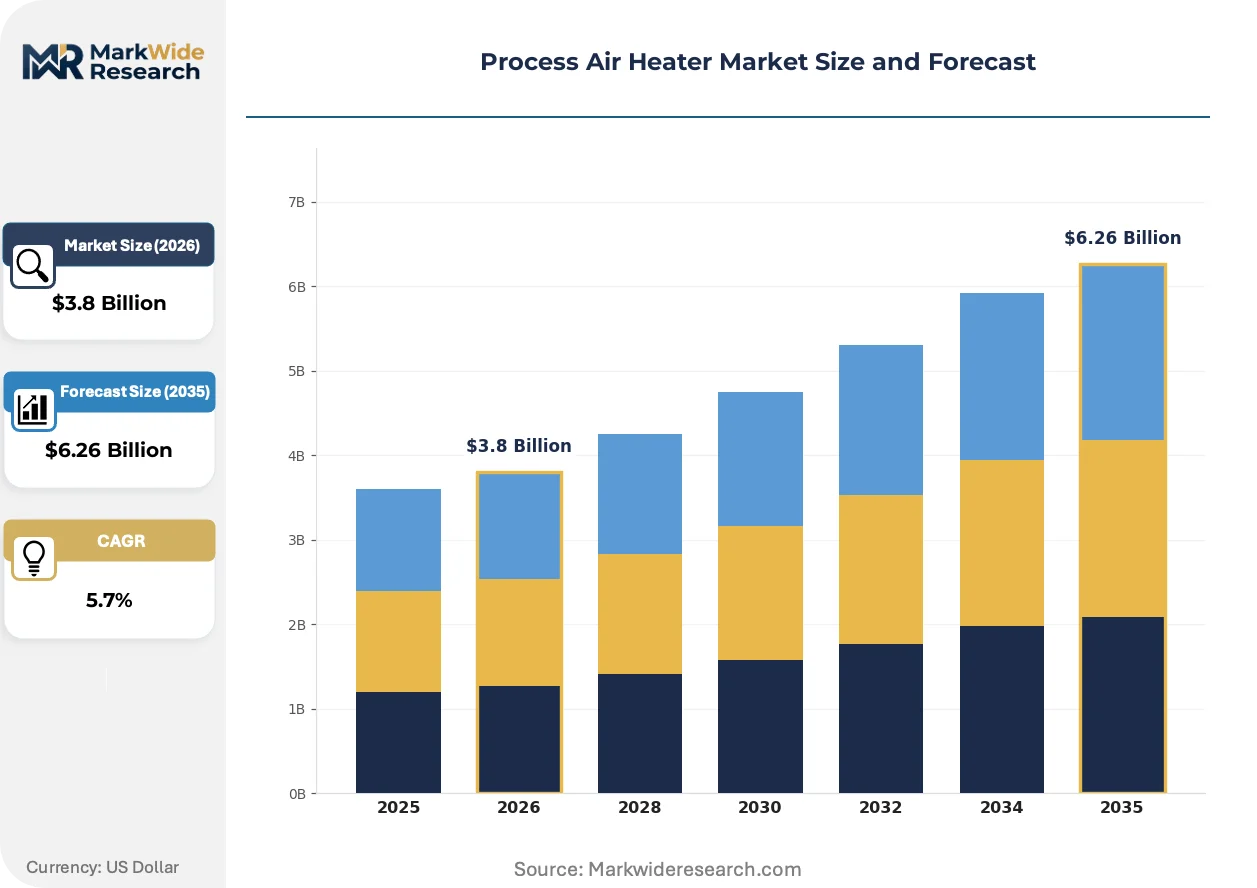
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heaters, Gas-Fired Heaters, Steam Tube Heaters, Indirect-Fired Heaters Installation: Wall-Mounted, Ceiling-Mounted, Portable, Ducted Industry Vertical: Food Processing, Chemical Manufacturing, Textile, Pharmaceuticals End User: Manufacturers, Industrial Facilities, Laboratories, Warehouses |
| Companies Covered | Leister Technologies AG, Tutco-Farnam, Indeeco, Chromalox, Tempco Electric Heater Corporation, Micropyretics Heaters International Inc, Tutco Inc., Thermo Energy Systems, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Air Heater Market Evolving Landscape
Process air heater engineering is converging on modulating electric architectures with embedded intelligence, displacing fixed-output gas systems and enabling demand-responsive thermal management across batch and continuous processing lines.
Silicon carbide heating elements are integrating into high-temperature process air heaters operating above 600°C, delivering faster thermal response and extended service life compared to metallic resistance coils. Aerospace composite curing and specialty chemical synthesis operations are specifying SiC-based systems for temperature uniformity criticality. This material transition is integrating premium pricing power into heater OEM portfolios while compressing replacement cycle frequency.
The EPA National Emission Standards for Hazardous Air Pollutants is tightening combustion source monitoring requirements for gas-fired process heaters in US chemical plants. Facilities in the Gulf Coast petrochemical corridor face incremental compliance costs for continuous emissions monitoring systems. Pharmaceutical and fine chemical manufacturers are responding by accelerating electric heater substitution to eliminate stack testing obligations entirely.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized food processors seeking to transfer thermal asset risk. Leasing structures bundle heater hardware, installation, and predictive maintenance into per-unit-of-output charges. This financing innovation is most visible in German and Dutch dairy processing cooperatives where capital constraints meet stringent hygiene audit requirements.
Process Air Heater Market Segmentation
Process air heater specification hinges on thermal duty, fuel availability, and emission constraints that vary sharply across installation environments and end-use applications. Buyers navigate trade-offs between capital cost, operating efficiency, and regulatory compliance that reshape procurement patterns across each segmentation dimension.
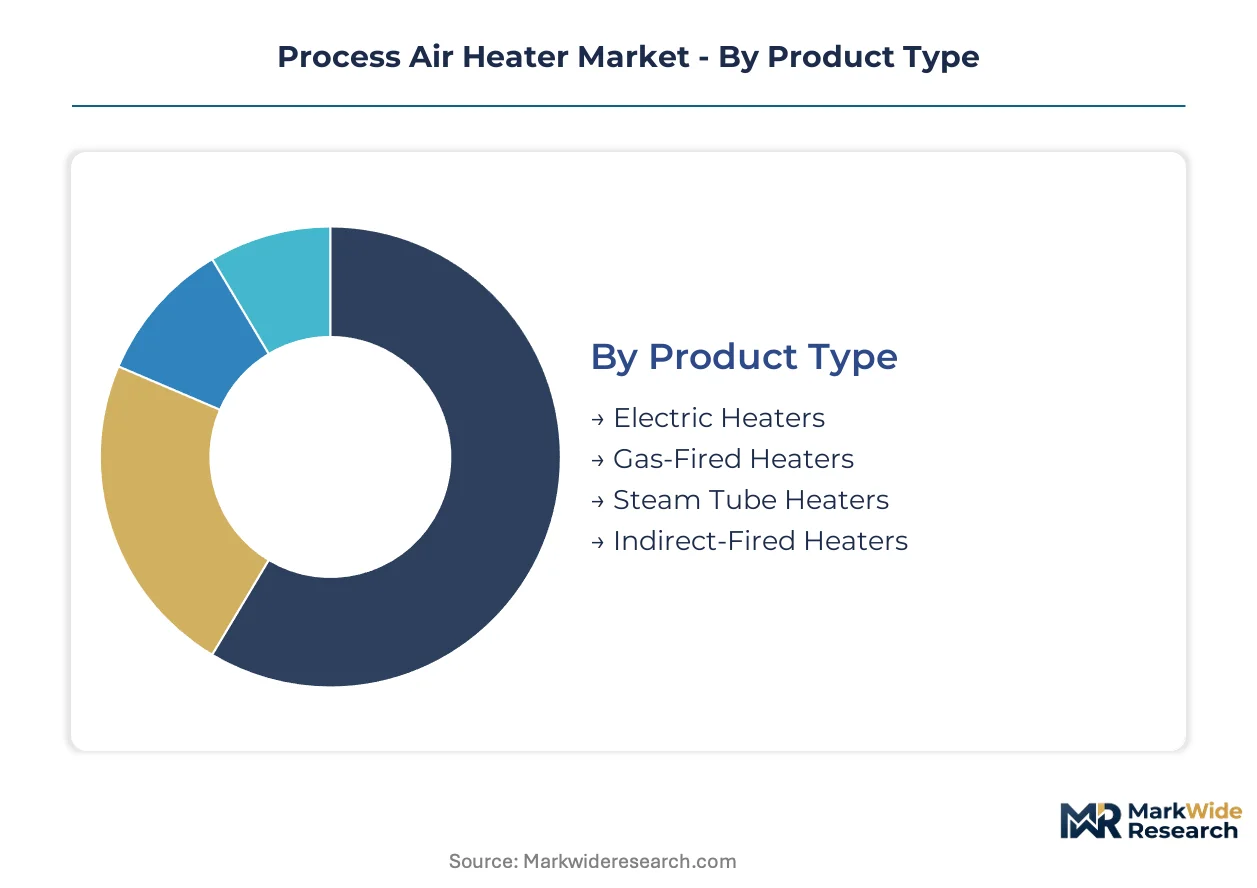
Product Type:
Capital allocation and carbon accounting rules drive heater technology selection, with electric architectures commanding premium positioning against legacy combustion systems.
- Electric Heaters:Nickel-chromium or iron-chromium-aluminum resistance elements sheathed in stainless steel or Incoloy deliver precise temperature control from 40°C to 650°C. German chemical plants under EU F-Gas Regulation are accelerating deployment to secure operating permits and eliminate stack monitoring obligations.
- Gas-Fired Heaters:Ribbon or tubular burners with forced-draft combustion chambers dominate installed base in regions with low natural gas pricing. Gulf Coast petrochemical facilities face incremental EPA compliance costs for continuous emissions monitoring systems that erode operating economics.
- Steam Tube Heaters:Heat exchanger coils circulating plant steam retain cost advantages in pulp and paper complexes with captive boiler capacity.
- Indirect-Fired Heaters:Combustion chambers thermally isolated from process air streams serve hazardous area applications requiring explosion protection.
Electric heaters lead on scale; gas-fired heaters lead on installed base momentum.
Installation:
Physical mounting constraints and airflow architecture determine heater form factor selection across facility retrofit and greenfield construction cycles.
- Wall-Mounted:Compact units with integral fans attach directly to building envelopes for space heating in warehouses and production halls.
- Ceiling-Mounted:Suspended configurations maximize floor space utilization in food processing cleanrooms where washdown protocols prohibit ground-level equipment.
- Portable:Self-contained units on casters serve temporary heating needs in construction and maintenance operations.
- Ducted:In-line insertion into HVAC or process air distribution systems enables centralized thermal management across multi-zone facilities.
Ducted installations dominate industrial process applications; ceiling-mounted configurations gain share fastest in hygiene-critical food and pharmaceutical environments.
Industry Vertical:
Process temperature requirements, regulatory exposure, and hygiene standards create distinct specification profiles across end-use sectors.
- Food Processing:Washdown-rated stainless enclosures and sanitary duct connections are mandatory for dairy and meat processing lines under USDA and FDA sanitation standards.
- Chemical Manufacturing:ATEX and IECEx certification for Zone 1 hazardous environments drives 12-18 month validation cycles that compress product launch windows.
- Textile:Continuous drying operations favor high-volume gas-fired systems where emission regulations permit.
- Pharmaceuticals:Precision hot-air systems for aseptic processing command premium pricing in Swiss and Irish biologics manufacturing expansion.
Chemical manufacturing leads on unit scale; pharmaceuticals climbs the fastest on biologics capacity investment.
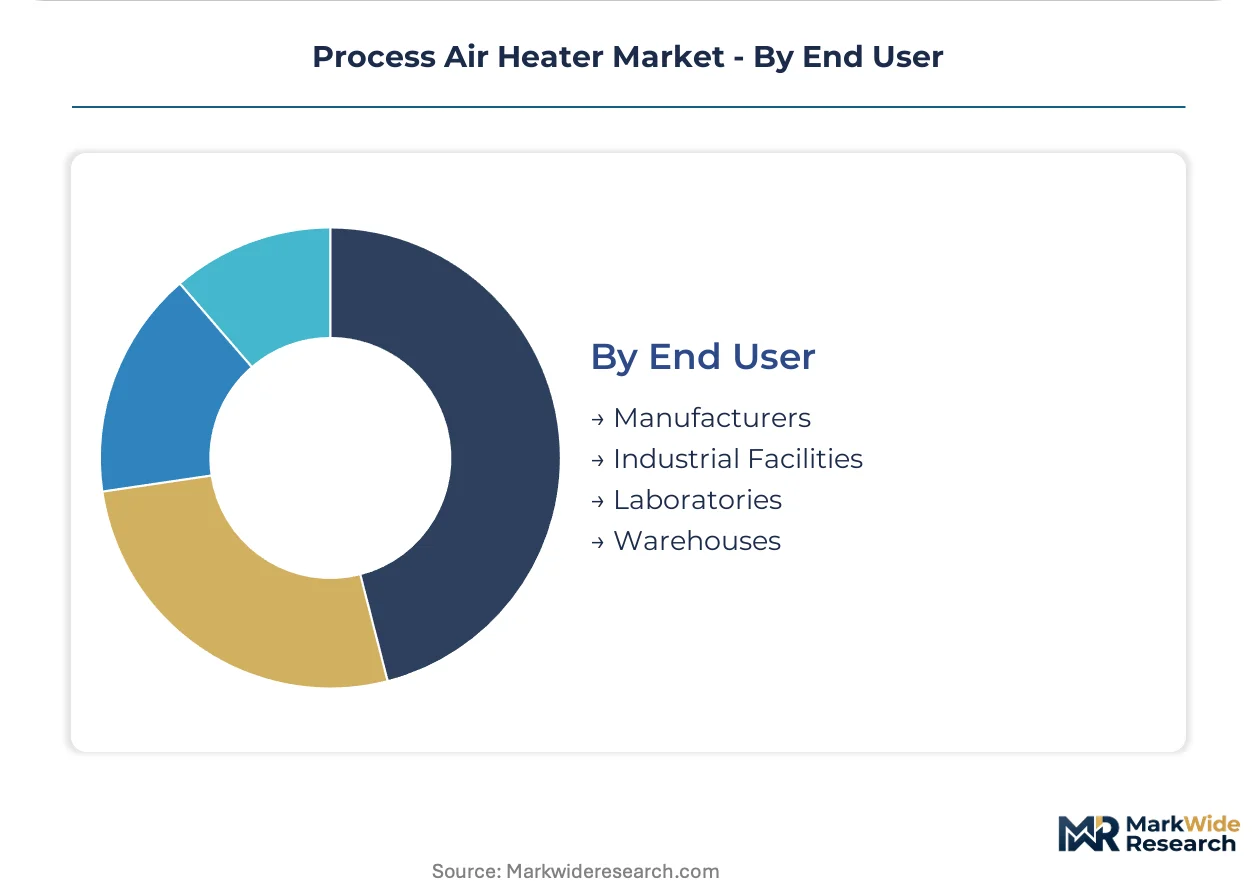
End User:
Capital intensity and technical capability shape whether heaters are procured as owned assets or contracted through service models.
- Manufacturers:Integrated production facilities specify custom-engineered systems with DCS and SCADA integration for continuous process control.
- Industrial Facilities:Multi-tenant manufacturing parks favor standardized units with remote monitoring capabilities.
- Laboratories:Research and quality control operations demand compact electric heaters with tight temperature uniformity.
- Warehouses:Space heating applications prioritize first-cost minimization and rapid installation turnaround.
Manufacturers lead on specification complexity; industrial facilities show steepest expansion trajectory on equipment-as-a-service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping process air heater procurement as manufacturers relocate to jurisdictions with lower carbon-compliance costs. The EU F-Gas Regulation and emerging carbon border adjustments are accelerating facility migration toward regions with cleaner grid profiles or weaker enforcement capacity.
United States
Gulf Coast petrochemical complexes are retrofitting gas-fired heaters under EPA National Emission Standards for Hazardous Air Pollutants. Continuous emissions monitoring obligations are forcing capital allocation toward electric architectures. Houston and Corpus Christi anchor the largest conversion projects as operators seek to eliminate stack testing liabilities.
Germany
Chemical manufacturing in the Rhine-Ruhr and Ludwigshafen corridors is scaling electric heater deployments to satisfy EU F-Gas Regulation phasedown timelines. BASF and Bayer supplier networks are anchoring systematic gas-to-electric retrofits. The country's industrial grid interconnection priority is clearing bottlenecks for electrification projects.
China
Dual carbon goals under MEE oversight are tightening emission intensity benchmarks for chemical and food processing facilities. Yangtze River Delta manufacturers are piloting silicon carbide heating elements for high-temperature applications. Shanghai and Ningbo industrial parks are prioritizing electric heater substitution in export-oriented production lines.
India
PLI scheme incentives for food processing and specialty chemicals are expanding cleanroom and hygiene-rated heater demand. Gujarat and Maharashtra industrial clusters are importing electric heater architectures to meet BIS energy efficiency standards. Mumbai-Pune corridor pharmaceutical manufacturers are specifying precision hot-air systems for aseptic processing expansion.
Switzerland
Swissmedic oversight of biologics manufacturing is driving precision thermal system specification in Basel and Zurich pharmaceutical corridors. Cleanroom-grade process air heaters command premium positioning as contract manufacturing capacity scales. The country's carbon-neutral grid profile supports electrification without emission accounting penalties.
Process Air Heater Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and equipment-as-a-service contracting. The vendor base clusters around three archetypes: vertically integrated resistance element manufacturers, custom engineering houses for hazardous area certification, and precision thermal specialists for pharmaceutical cleanrooms. Consolidation pressure is intensifying as carbon accounting rules favor scale players with integrated control architectures. Dominant competitive moves include backward integration into mineral-insulated cable production and strategic partnerships for predictive maintenance software licensing.
Within the precision cleanroom tier, Leister Technologies AG and Tutco-Farnam exemplify engineering-density positioning for pharmaceutical and chemical processing applications. Chromalox anchors the vertically integrated archetype with captive supply of resistance element feedstock. These three occupy positions spanning Swiss precision manufacturing, North American custom engineering, and integrated production scale respectively.
| Leading Market Players |
|---|
| Leister Technologies AG |
| Tutco-Farnam |
| Indeeco |
| Chromalox |
| Tempco Electric Heater Corporation |
| Micropyretics Heaters International Inc |
| Tutco Inc. |
| Thermo Energy Systems |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phasedown timelines are gating qualified supply and premium-tier pricing access for electric process air heater architectures, as German chemical plants under BASF and Bayer supplier networks demand certified low-emission systems that command 15-25% markups over standard gas-fired alternatives.
Pricing Analysis
Distributor margins in the 12-18% range anchor the channel economics for standard electric heaters, while direct-to-OEM volume discounts of 8-12% apply for BASF and Bayer supplier network procurement. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified hazardous area systems from washdown-rated food processing units and basic warehouse space heaters. Pricing pressure stems from nickel-chromium alloy feedstock volatility originating in Indonesian ore processing. Small-to-mid food processors show highest price sensitivity; pharmaceutical cleanroom buyers demonstrate lowest sensitivity due to Swissmedic compliance mandates.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China form hub-and-spoke patterns that position finished heaters within 48-hour delivery windows of major industrial corridors. Resistance element manufacturing draws from Indonesian and Russian nickel-chromium ore processing, with stainless steel sheathing anchored in Chinese and German mill capacity. Single-source vulnerability concentrates in mineral-insulated cable feedstock controlled by Chromalox's backward integration. Distribution runs through authorized industrial distributor networks and direct OEM procurement channels serving chemical and pharmaceutical plant engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Swiss and German facilities absorb 20-30% cost premiums for carbon-neutral grid electrification while Gulf Coast petrochemical operators delay conversion pending EPA enforcement uncertainty.
For Market Incumbents: Lock in mineral-insulated cable supply through captive production or long-term offtake agreements with Indonesian smelters to defend against nickel-chromium volatility. Deepen hazardous area certification pipelines to compress ATEX validation cycles below 12 months and outpace emerging entrants on pharmaceutical cleanroom launches.
For New Entrants and Emerging Players: Equipment-as-a-service bundling opens white space among capital-constrained German and Dutch dairy cooperatives seeking to transfer thermal asset risk. Target precision hot-air systems for Swiss biologics manufacturing expansion where Swissmedic oversight creates specification stickiness. Pursue predictive maintenance software licensing partnerships with established heater OEMs to bypass manufacturing scale requirements.
For Investors and Strategic Acquirers: Roll-up economics work for precision thermal specialists because pharmaceutical cleanroom demand concentrates in Basel and Zurich corridors with limited qualified vendor pools. Five-to-ten year viability hinges on electric architecture conversion cycles completing across EU chemical manufacturing. Watch carbon border adjustment mechanism implementation timelines as the inflection signal for accelerated gas-to-electric retrofit spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resistance Elements | Captive nickel-chromium supply insulates Chromalox from Indonesian ore volatility and sanction exposure. |
| ATEX Certification Pipeline Expansion | Compressed 12-18 month validation cycles accelerate product launches for Zone 1 chemical environments. |
| Equipment-as-a-Service Launch | Per-unit-output leasing transfers asset risk for German dairy cooperatives facing hygiene audit mandates. |
| Predictive Maintenance Platform Integration | IoT sensor convergence enables remote optimization contracts with pharmaceutical cleanroom operators. |
| Silicon Carbide Element Commercialization | SiC systems above 600°C capture aerospace composite curing and specialty chemical synthesis premiums. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, customs and trade data reconciliation, SEC 10-K filings from industrial heater manufacturers, and ACC/Cefic chemical industry reports — were reconciled through bottom-up installation tracking and top-down market sizing validation across the projection horizon.
Data-stream reconciliation applied a segmented analytical framework modeling heater technology type, installation configuration, end-use vertical, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from trend extrapolation against carbon accounting rule implementation timelines and electrification capital deployment patterns. Forecast inputs incorporated EU F-Gas Regulation phasedown schedules and EPA National Emission Standards enforcement intensity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel-chromium supply disruptions, grid infrastructure upgrade delays in Eastern Europe, and carbon border adjustment mechanism coverage expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Power Fastener Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Thailand Power Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Portable Power Station Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Saudi Arabia Power EPC Market