
 Automatic Power Factor Controller Market | 2026-2036
Automatic Power Factor Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Power Factor Controller Market Analysis
Project finance structures for distributed energy assets are reshaping procurement patterns across the automatic power factor controller supply chain. Schneider Electric leverages its integrated energy management portfolio to anchor large commercial installations across European industrial zones. ABB Ltd. competes through captive production of capacitor banks and switching components, sustaining margin control across project lifecycles. Larsen & Toubro Ltd. dominates India's domestic utility infrastructure tenders through localized manufacturing scale and channel depth in state transmission networks.
An automatic power factor controller is an electrical device that monitors reactive power in alternating current systems and automatically switches capacitor banks to maintain power factor near unity, typically operating across voltage classes from 230V to 33kV with response times under 100 milliseconds. Static controllers retain the largest installed base across legacy industrial motor loads, though active variants are displacing hybrid architectures in variable-speed drive applications where harmonic distortion exceeds 5% THD. The industrial end-user segment anchors volume demand through steel, cement, and chemical processing facilities with heavy inductive loading profiles. Smart control methods are gaining traction in commercial buildings where BACnet and Modbus integration enables remote power quality monitoring through building management systems.
The International Electrotechnical Commission's IEC 61000-3-6 standard shapes product design requirements for harmonic emission limits in medium-voltage installations, while IEEE 519 in North America mandates utility-level compliance for total demand distortion at point of common coupling. India's Central Electricity Authority enforces reactive power tariff penalties for industrial consumers falling below 0.85 power factor, directly stimulating controller retrofit demand across Maharashtra and Gujarat manufacturing belts. Stakeholders must monitor evolving grid code harmonization between regional transmission operators and distributed energy resource interconnection standards as inverter-based generation alters traditional reactive power flow dynamics.
Market Dynamics
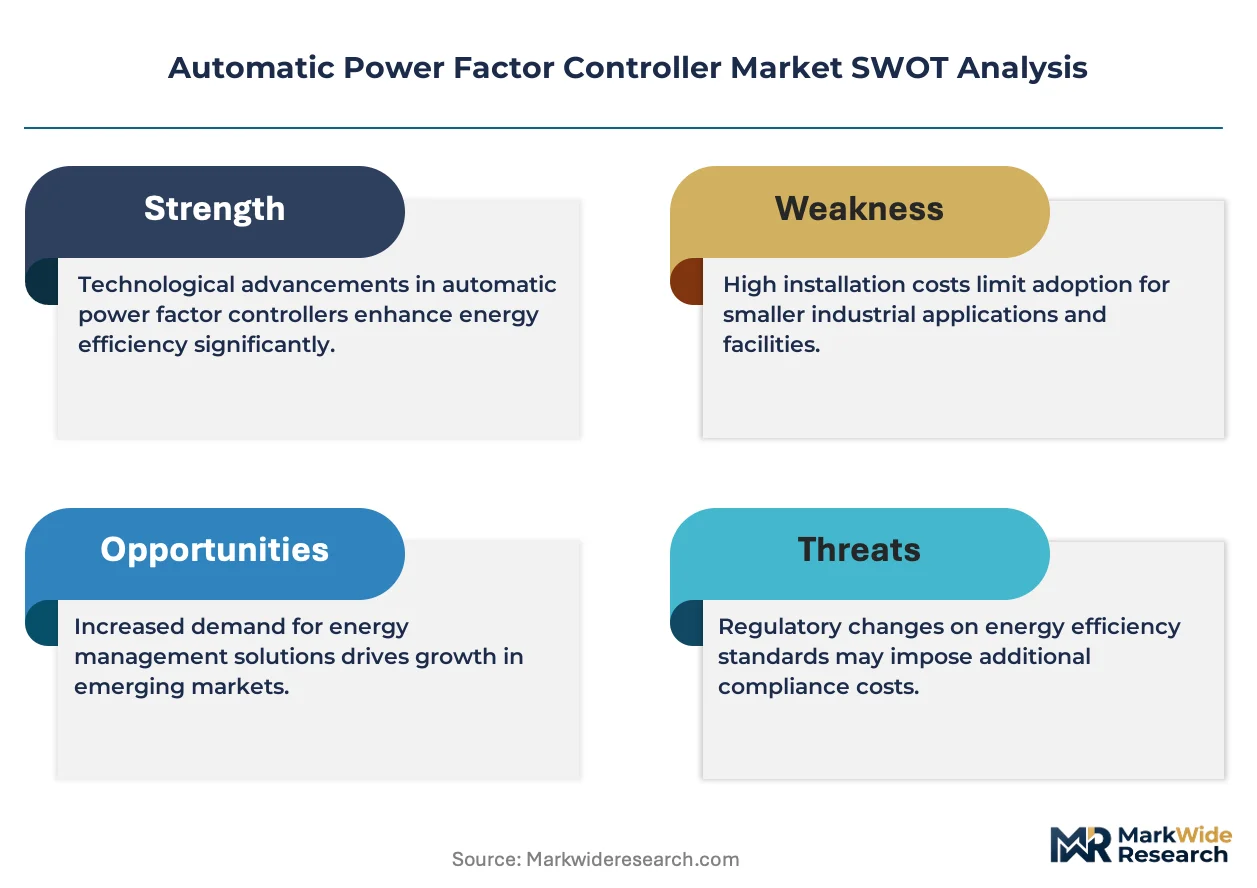
Active power factor correction architectures are displacing static capacitor switching across industrial motor loads as harmonic distortion thresholds tighten under IEC 61000-3-6 and IEEE 519 mandates. This technology migration compresses legacy controller margins while elevating semiconductor content in bill-of-materials.
Growth Catalysts
- IEC 61000-3-6 Emission Limits:Medium-voltage harmonic standards in European industrial zones mandate active filtering capabilities, forcing retrofit cycles across steel and cement processing facilities.
- India CEA Reactive Power Tariffs:Penalty structures for power factor below 0.85 drive controller deployment across Maharashtra and Gujarat manufacturing belts.
- Variable-Speed Drive Proliferation:Motor control systems exceeding 5% THD require active PFC integration, creating replacement demand in automotive and chemical processing plants.
Market Restraints
- IGBT and SiC Semiconductor Supply:Active controller production depends on power electronics sourcing concentrated in East Asian foundries, exposing lead time volatility.
- Copper and Aluminum Price Swings:Capacitor bank and busbar fabrication faces raw material cost instability, compressing project margins for system integrators.
- Legacy Static Controller Installed Base:Decades of thyristor-based deployments create switching inertia among cost-sensitive industrial maintenance departments.
Strategic Opportunities
- Utility-Scale Solar Integration:India's state transmission networks seek voltage stability solutions for inverter-dominated generation, opening procurement channels for grid-scale reactive power management.
- Building Management System Convergence:BACnet and Modbus integration enables remote power quality monitoring in commercial real estate portfolios across Chinese tier-one cities.
- EU Green Deal Electrification:Industrial decarbonization incentives accelerate motor system upgrades, embedding PFC requirements in energy audit compliance frameworks.
Industry Challenges
- Power Electronics Engineering Talent:Active controller design requires scarce expertise in digital signal processing and wide-bandgap semiconductor gate drive circuits.
- Dual Certification Burden:Manufacturers must simultaneously satisfy IEC 61000 for European export and IEEE 519 for North American utility interconnection, extending product development timelines.
- Legacy Motor Compatibility:Retrofit installations face integration complexity with aged magnetic contactor control circuits and obsolete protection relay settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Power Factor Controller Market |
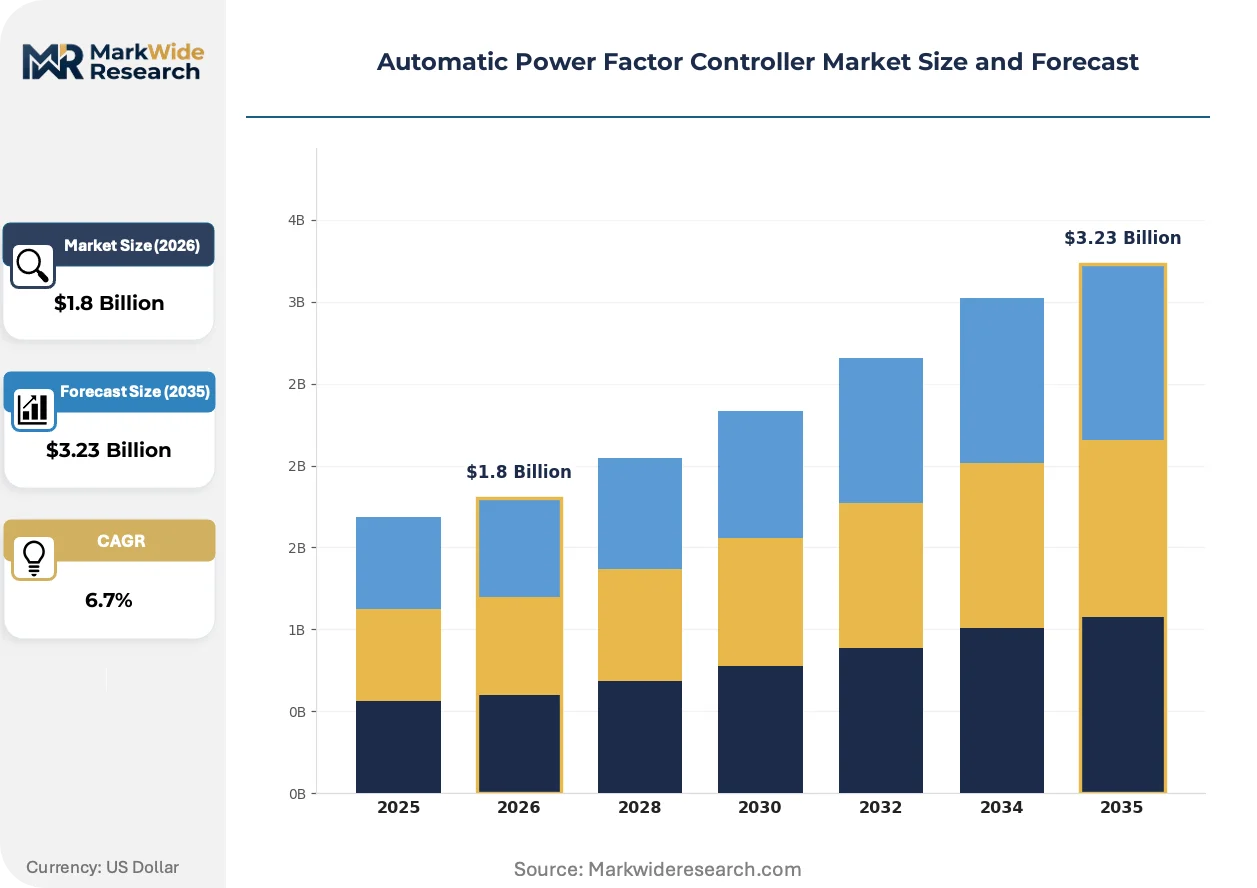
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Active, Hybrid, Digital End User: Industrial, Commercial, Residential, Utilities Installation Type: Indoor, Outdoor, Modular, Fixed Control Method: Manual, Automatic, Semi-Automatic, Smart |
| Companies Covered | ABB Ltd., Schneider Electric, General Electric Company, Eaton Corporation Plc, Siemens, STMicroelectronics NV, Texas Instruments Inc., Larsen & Toubro Ltd., Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Power Factor Controller Market Emerging Trajectories
Silicon carbide power semiconductors and digital control algorithms are compressing response times below 50 milliseconds while expanding operating voltage classes. These advances enable new applications in renewable integration and electric vehicle charging infrastructure.
Active PFC controller architecture is migrating from thyristor-switched capacitor banks to IGBT-based active harmonic filters. Steel mills in China's Hebei province are adopting these systems at accelerated pace to meet provincial environmental bureau emission deadlines. The technology shift is compressing market share for legacy static controller manufacturers unable to source power electronics talent.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate SF6-insulated switchgear from medium-voltage capacitor bank assemblies. Industrial PFC system suppliers in Germany's Ruhr region are redesigning vacuum interrupter topologies to maintain arc quenching performance. The regulatory pressure most severely affects 11kV and 33kV installations in European chemical processing clusters.
Chinese industrial facilities are consolidating procurement authority for power quality equipment under centralized energy management departments. State-owned enterprise purchasing departments in Sichuan and Shandong provinces now specify integrated PFC-transformer-switchgear packages rather than component-level sourcing. This behavioral shift compresses distributor margins while favoring turnkey system providers with in-house manufacturing scale.
Automatic Power Factor Controller Market Segmentation
Controller architectures vary sharply in replacement cadence and margin profile across the automatic power factor controller market. Static systems installed in the 1990s face accelerated displacement cycles, while active variants command extended depreciation schedules tied to semiconductor reliability curves.
Product Type:
Replacement velocity separates segments sharply. Static controllers turn over on 15-20 year cycles as capacitor degradation forces maintenance events, while active systems with modular IGBT stages extend service intervals through predictive thermal monitoring.
- Active:IGBT-based harmonic filtering architectures with response times below 50 milliseconds. Demand concentrates in Hebei province steel mills facing provincial environmental bureau emission deadlines for variable-speed drive integration.
- Static:Thyristor-switched capacitor banks operating across 230V to 11kV classes with electromechanical contactor stages. Maharashtra and Gujarat manufacturing belts drive retrofit demand as CEA reactive power tariff penalties bite below 0.85 power factor thresholds.
- Hybrid:Combines thyristor stages with limited active filtering for 5-8% THD environments.
- Digital:DSP-controlled architectures with Ethernet-enabled remote monitoring capabilities.
Static controllers dominate installed base across legacy industrial motor loads. Active architectures are where expansion concentrates as IEC 61000-3-6 harmonic mandates tighten across European steel and cement processing zones.
End User:
Customer type determines specification intensity and channel access. Industrial buyers demand integrated transformer-switchgear packages, while commercial procurement favors BACnet-compatible systems for building management convergence.
- Industrial:Heavy inductive loading profiles in steel, cement, and chemical processing facilities. Sichuan and Shandong state-owned enterprises now specify turnkey PFC-transformer-switchgear packages rather than component-level sourcing.
- Utilities:Grid-scale reactive power management for voltage stability in inverter-dominated transmission networks. India's state transmission operators seek these solutions for renewable integration projects across Maharashtra and Gujarat.
- Commercial:Real estate portfolios with BACnet and Modbus integration requirements.
- Residential:Distributed generation interconnection at distribution transformer levels.
Industrial end-users anchor volume demand through energy audit compliance frameworks. Utility procurement channels are expanding most quickly as grid codes harmonize around distributed energy resource interconnection standards.
Installation Type:
Physical configuration shapes margin structure and project complexity. Indoor cabinet assemblies concentrate manufacturing scale, while outdoor specifications demand IP-rated enclosures that compress system integrator margins.
- Indoor:Enclosed metal-clad assemblies for climate-controlled electrical rooms. European chemical processing clusters in Germany's Ruhr region drive demand as F-Gas Regulation phase-down pressures SF6 elimination from medium-voltage capacitor banks.
- Outdoor:Weather-hardened enclosures with active thermal management for substation yards.
- Modular:Containerized skid-mounted systems for rapid deployment in utility-scale solar integration.
- Fixed:Permanent concrete-pad installations with integrated fencing and grounding grids.
Indoor installations dominate manufacturing throughput. Modular configurations are climbing the fastest as procurement authority consolidates under centralized energy management departments in Chinese state-owned enterprises.
Control Method:
Automation depth determines semiconductor content and firmware development burden. Smart controllers require scarce digital signal processing expertise, while manual systems face obsolescence pressure from grid code modernization.
- Smart:AI-enhanced predictive algorithms with cloud-connected power quality analytics. Chinese tier-one city commercial real estate portfolios specify these for remote monitoring through building management systems.
- Automatic:Microprocessor-based capacitor switching with programmable power factor setpoints. India's industrial zones deploy these widely to avoid CEA-mandated reactive power tariff penalties.
- Semi-Automatic:Operator-override capable systems with local HMI interfaces.
- Manual:Fixed-capacitor installations with seasonal switching schedules.
Automatic controllers dominate current procurement volumes. Smart control architectures are gaining share fastest where BACnet integration enables portfolio-level power quality management across commercial building stocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-level reactive power tariff structures and tightening electromagnetic compatibility mandates are redrawing procurement geographies across the automatic power factor controller market. National regulators deploy penalty mechanisms and emission limits that directly stimulate controller deployment in industrial manufacturing belts.
China
State-owned enterprises in Sichuan and Shandong provinces now mandate integrated PFC-transformer-switchgear packages under centralized energy management departments. Provincial environmental bureaus in Hebei enforce emission deadlines that accelerate active harmonic filter adoption in steel mills. Variable-speed drive integration projects across the Yangtze River Delta command response times below 50 milliseconds.
India
The Central Electricity Authority enforces reactive power penalties for industrial consumers below 0.85 power factor, directly retrofitting manufacturing belts in Maharashtra and Gujarat. State transmission operators procure grid-scale voltage stability solutions for renewable integration projects. Larsen & Toubro anchors domestic utility infrastructure tenders through localized manufacturing scale.
Germany
EU F-Gas Regulation phase-down schedules pressure elimination of SF6-insulated switchgear from medium-voltage capacitor banks in the Ruhr region's chemical processing clusters. Industrial decarbonization incentives under the EU Green Deal embed PFC requirements in energy audit compliance frameworks. Vacuum interrupter redesigns maintain arc quenching performance without fluorinated gases.
United States
IEEE 519 mandates utility-level compliance for total demand distortion at point of common coupling, shaping product specifications for North American interconnection. Commercial building portfolios specify BACnet-compatible systems for remote power quality monitoring. Industrial motor loads across the Midwest face replacement cycles as harmonic thresholds tighten.
Japan
METI industrial efficiency standards drive precision manufacturing facilities toward smart control architectures with predictive thermal monitoring. Semiconductor fabrication plants in the Kanto region demand sub-50 millisecond response times for sensitive process equipment. Digital signal processing expertise concentrates among power electronics engineering clusters in Nagoya and Osaka.
Automatic Power Factor Controller Market Vendor Landscape
On the supply side, the industry is consolidating around integrated energy management portfolios and captive component production. Tiered competitive positions separate turnkey system providers from component specialists and semiconductor suppliers. Three archetypes dominate: diversified electrical conglomerates with project finance capabilities, regional infrastructure contractors with localized manufacturing scale, and power electronics semiconductor vendors supplying controller subsystems. Competitive maneuvering concentrates on strategic partnerships for grid-scale deployments and backward integration into capacitor bank fabrication.
Within the diversified electrical conglomerate tier, ABB Ltd. and Schneider Electric exemplify contrasting geographic anchoring strategies. ABB's captive production of capacitor banks and switching components sustains margin control across project lifecycles. Schneider leverages integrated energy management portfolios to anchor large commercial installations. Larsen & Toubro Ltd. occupies the regional infrastructure contractor position, dominating India's domestic utility tenders through channel depth in state transmission networks. These three represent the archetypal competitive positions: global integrated systems, regional project execution, and component-level supply.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric |
| General Electric Company |
| Eaton Corporation Plc |
| Siemens |
| STMicroelectronics NV |
| Texas Instruments Inc. |
| Larsen & Toubro Ltd. |
| Emerson Electric Co. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's power electronics foundries is compressing IGBT module pricing while simultaneously pressuring controller manufacturers to extend payment terms to capacitor bank suppliers. This utilization dynamic forces margin trade-offs between semiconductor content and raw material hedging strategies.
Pricing Analysis
Certification level creates the primary spread, with IEC 61000-3-6 and IEEE 519 dual-certified systems commanding premium positioning against single-standard alternatives. Project-based pricing dominates large industrial deployments, while component-level transactions persist in maintenance retrofit channels. Price differentiation stems from harmonic filtering bandwidth and response time performance tiers. Cost compression in static controller segments is intensifying because active IGBT-based architectures capture specification authority in new steel and cement installations. Commercial building buyers exhibit highest price sensitivity, whereas utility-scale transmission operators prioritize voltage stability guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from European system integrators to Taiwanese semiconductor foundries are lengthening working capital cycles across the controller value chain. Manufacturing concentrates in China, Germany, and India, with Hebei province steel mill demand anchoring Asian production volumes. Raw material dependencies span copper busbar stock, polypropylene capacitor film, and silicon carbide wafer substrates. Single-source vulnerability in wide-bandgap semiconductor gate drive ICs exposes lead time volatility for active controller architectures. Distribution runs through electrical wholesale channels serving industrial maintenance departments and EPC contractors executing utility infrastructure tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic power factor controller market is entering a cyclical recovery phase as IEC 61000-3-6 retrofit deadlines across European steel processing facilities force replacement waves. This regulatory-driven replacement cycle justifies capacity positioning ahead of demand inflection.
For Market Incumbents: Build captive capacitor bank fabrication as a margin defense moat against commodity copper price swings. Incumbents should consolidate switching component production in-house while accelerating IEC-IEEE dual certification pipelines to capture specification authority in multinational industrial accounts. Semiconductor supply volatility from East Asian foundries represents the primary threat requiring inventory positioning and alternative source qualification. For New Entrants and Emerging Players: Mid-market commercial buildings in Chinese tier-one cities represent the most penetrable entry point, with BACnet-integrated smart controllers underserved by legacy static suppliers. New entrants should target predictive thermal monitoring capabilities as a differentiated software layer, avoiding direct competition with established players in heavy industrial motor load segments. Channel partnerships with building management system integrators offer the strongest go-to-market angle for commercial portfolio penetration. For Investors and Strategic Acquirers: Long-term, this sits as a grid modernization play because inverter-based renewable generation is fundamentally altering reactive power flow dynamics across transmission networks. Acquisition targets should emphasize power electronics engineering talent pools and active harmonic filter IP portfolios. The signal to watch is grid code harmonization progress between regional transmission operators and distributed energy resource interconnection standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Capacitor Bank Fabrication | Captive copper busbar and polypropylene film processing insulates margin from commodity volatility in Maharashtra manufacturing belts. |
| IEC-IEEE Dual Certification Investment | Dual-standard compliance opens procurement channels across European steel mills and North American utility interconnection tenders simultaneously. |
| Silicon Carbide Power Semiconductor Transition | SiC module adoption enables sub-50 millisecond response times required by Hebei province environmental bureau emission deadlines. |
| Building Management System Platform Integration | BACnet and Modbus protocol convergence captures specification authority in Chinese commercial real estate centralized procurement. |
| Utility-Scale Solar Partnership Development | Grid-scale reactive power management contracts with Indian state transmission operators anchor long-term revenue visibility. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, electrical contractors, utility planning officers, and power quality equipment procurement managers; and secondary validation through IEC standard documentation, IEEE 519 compliance filings, Central Electricity Authority tariff orders, and customs trade data for capacitor bank and semiconductor imports. Bottom-up segmentation modeling triangulated against top-down market sizing from industrial motor load statistics and renewable integration project pipelines.
Forecast inputs incorporated active versus static controller replacement velocity, copper and aluminum price trajectory assumptions, and semiconductor foundry capacity utilization trends across the projection horizon. Segmentation dimensions modeled include controller architecture type, end-user industry vertical, installation configuration, and voltage class tier. CAGRs were derived from regression analysis of historical deployment patterns against regulatory deadline schedules and utility tariff penalty enforcement intensity.
Stress conditions across IGBT supply lead times, raw material price bands, and grid code harmonization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding industrial electrification rates and renewable penetration targets. Macroeconomic contraction, trade restriction escalation, or breakthrough solid-state transformer technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Magnetic Bearing Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Romania Power EPC Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Levant Power Cable Market